
 Liquid Organic Hydrogen Carrier (LOHC) Market | 2026-2036
Liquid Organic Hydrogen Carrier (LOHC) Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Organic Hydrogen Carrier (LOHC) Market Insights
German chemical producers is hardening LOHC supply capacity through dedicated hydrogenation reactor investments. Hydrogenious Technologies leverages its proprietary storage technology to anchor European project pipelines. BASF SE sustains R&D intensity across dibenzyltoluene formulations. Chiyoda Corporation dominates Asia-Pacific commercial deployment with its SPERA maritime transport system.
Liquid Organic Hydrogen Carrier denotes an organic compound—typically dibenzyltoluene, toluene, or methylcyclohexane—that reversibly binds hydrogen through catalytic hydrogenation and releases it via dehydrogenation at 250–350°C, enabling ambient-pressure storage and transport of hydrogen in liquid form. The technology eliminates cryogenic handling requirements and reduces infrastructure retrofit costs versus compressed or liquefied hydrogen. Dibenzyltoluene-based systems lead product type adoption due to thermal stability and low vapor pressure, while methylcyclohexane competes in markets prioritizing existing petrochemical logistics. Transportation applications command the largest application share as maritime hydrogen corridors mature, though energy storage segments accelerate fastest behind grid-scale hydrogen buffering demand.
EMA guidelines on hydrogen purity standards, EU Green Deal delegated acts defining renewable hydrogen thresholds, and Japan's METI hydrogen supply chain certification framework collectively shape product specifications and cross-border market access. Germany's KBA transport classifications and the EU F-Gas Regulation indirectly influence carrier selection through handling and emissions protocols. Stakeholders must monitor regulatory divergence between EU taxonomy criteria and Japanese METI certification timelines to avoid stranded asset risk in bilateral hydrogen trade corridors.
Market Dynamics
The LOHC market is being fundamentally restructured by the EU Green Deal delegated acts, which mandate strict renewable hydrogen certification thresholds that directly determine carrier eligibility for cross-border trade corridors and project financing access.
Growth Catalysts
- EU Green Deal delegated acts:These regulations establish binding renewable hydrogen thresholds that validate LOHC systems for green hydrogen transport, unlocking project finance for maritime import terminals.
- Maritime hydrogen corridors:Japan's METI certification framework enables commercial-scale hydrogen imports via toluene-based LOHC systems, creating templateable trade routes for other Asia-Pacific importers.
- Dibenzyltoluene thermal stability:This carrier chemistry eliminates cryogenic infrastructure requirements, reducing capital barriers for hydrogen refueling station deployment in dense urban zones.
Market Restraints
- Dehydrogenation energy intensity:The 250–350°C thermal requirement for hydrogen release consumes 30% of stored energy value, compressing round-trip efficiency versus direct electrolysis.
- Catalyst supply concentration:Platinum-group metal catalyst production concentrates in South Africa and Russia, exposing LOHC project economics to geopolitical supply disruptions and price volatility.
- Liquefied hydrogen competition:Cryogenic liquid hydrogen achieves higher volumetric density for short-distance transport, threatening LOHC economics in regional hydrogen distribution networks.
Strategic Opportunities
- Grid-scale hydrogen buffering:Seasonal renewable energy storage applications in Germany's industrial clusters create demand for dibenzyltoluene systems as electricity-to-hydrogen-to-electricity assets.
- Existing petrochemical logistics repurposing:Methylcyclohexane LOHC systems leverage established toluene supply chains and tanker fleets, enabling rapid corridor deployment without dedicated infrastructure builds.
- Japan METI certification alignment:Bilateral harmonization of hydrogen purity standards between Japanese and European regulators would eliminate dual-certification costs for transcontinental LOHC suppliers.
Industry Challenges
- Catalytic deactivation management:Hydrogenation reactor operators must maintain catalyst activity across thousands of charge-discharge cycles, requiring specialized process engineering talent scarce outside petrochemical hubs.
- Dehydrogenation heat integration:Offtake agreements for waste heat from LOHC release facilities remain structurally underdeveloped, stranding thermal energy value and compressing project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Organic Hydrogen Carrier (LOHC) Market |
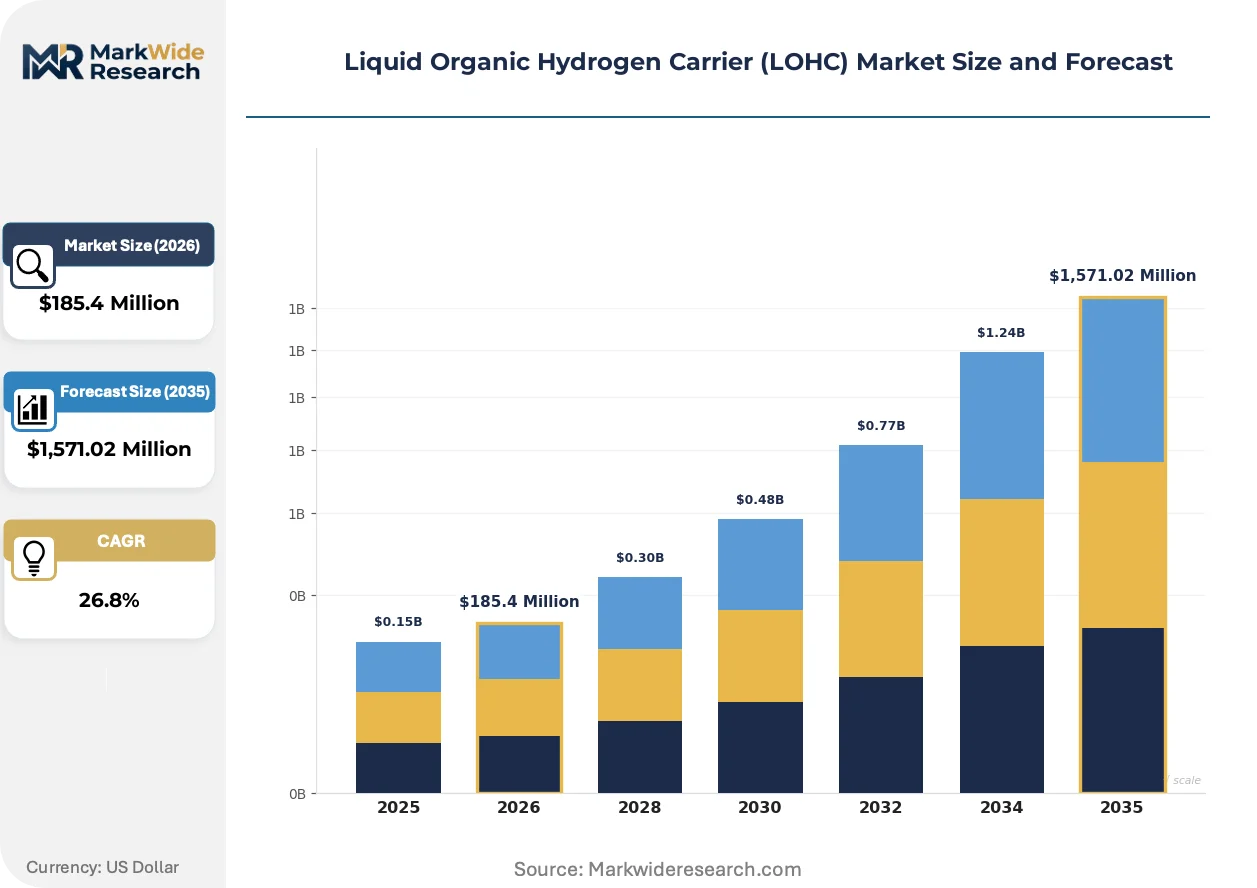
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $1,571.02 Million |
| CAGR (2026 – 2036) | 26.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dibenzyltoluene, Toluene, Naphthalene, Methylcyclohexane Application: Transportation, Energy Storage, Chemical Synthesis, Fuel Cells End User: Industrial, Automotive, Aerospace, Power Generation Technology: Catalytic Hydrogenation, Dehydrogenation, Thermal Process, Pressure Swing Adsorption |
| Companies Covered | Covalion, Mitsubishi Chemical Corporation, Hynertech, Air Products and Chemicals, BASF SE, Chiyoda Corporation, Wuhuan Engineering, Toyota Tsusho Corporation, Hydrogenious Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Organic Hydrogen Carrier (LOHC) Market Trends and Innovations
Technology convergence between hydrogen storage chemistry and maritime logistics is compressing deployment timelines for commercial-scale LOHC corridors. Regulatory certification harmonization and carrier formulation advances are simultaneously expanding addressable market scope.
Dibenzyltoluene carrier chemistry is overtaking methylcyclohexane in European project pipelines due to superior thermal stability and negligible vapor pressure. Hydrogen refueling infrastructure developers in Germany are selecting this formulation for urban deployment. The shift is compressing methylcyclohexane's addressable market to petrochemical corridor repurposing applications exclusively.
REACH registration requirements for hydrogen carrier substances are tightening purity and traceability documentation obligations across EU member states. Chemical producers must demonstrate full supply chain mass balance for renewable hydrogen attribution. Dibenzyltoluene suppliers are responding by integrating blockchain-based batch tracking from hydrogenation through dehydrogenation.
Industrial offtakers are consolidating procurement around long-term hydrogen supply agreements with embedded LOHC transport clauses. Power-to-X project developers in Rotterdam and Hamburg are replacing spot hydrogen purchases with 10–15 year carrier service contracts. This contractual shift is most visible in German steel and chemical decarbonization clusters seeking supply certainty for electrolyzer investment decisions.
Liquid Organic Hydrogen Carrier (LOHC) Market Segmentation
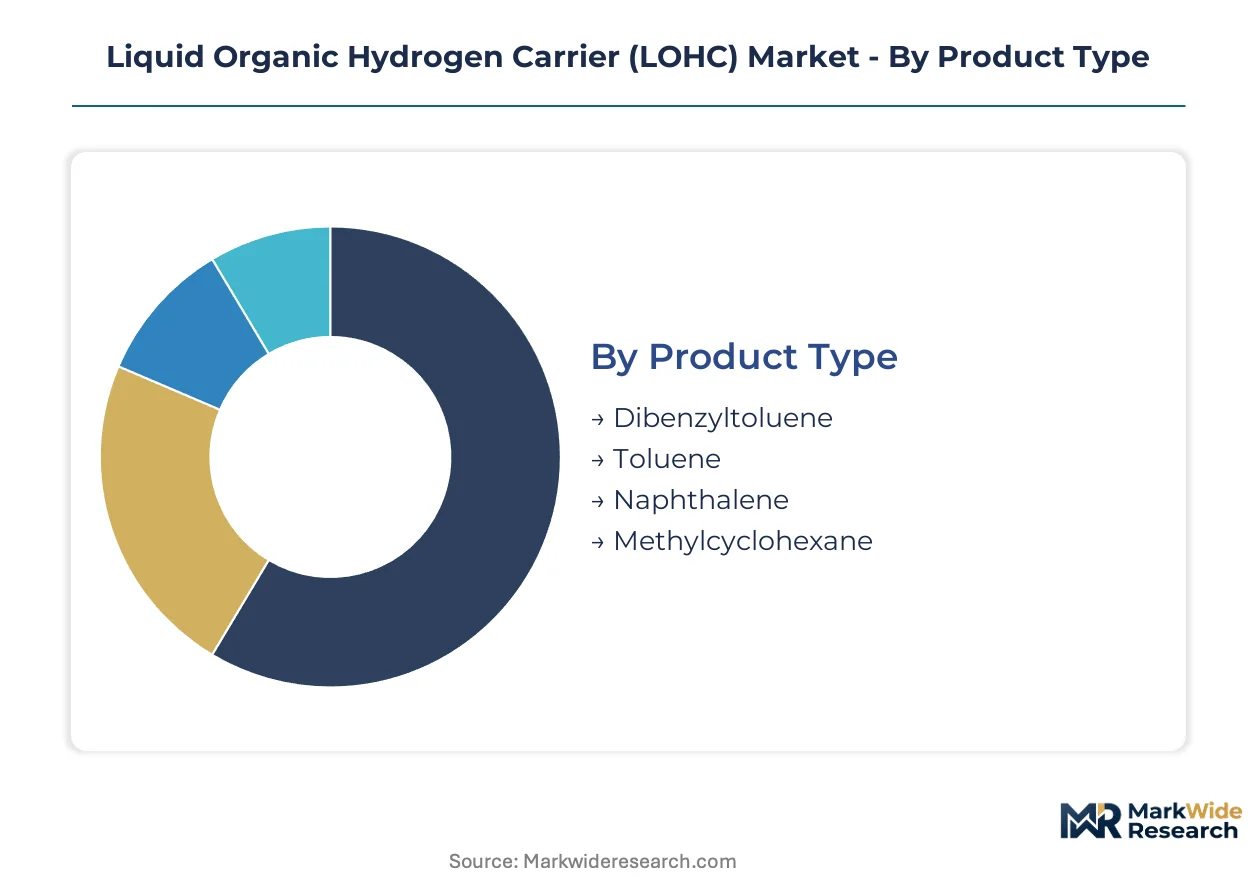
Carrier chemistry and release technology selection directly determine project economics for hydrogen corridor developers. End-use requirements and regulatory certification pathways create divergent demand profiles across industrial clusters.
Product Type:
Upgrade cycles favor carriers with superior thermal stability and lower vapor pressure, reducing infrastructure retrofit costs for operators.
- Dibenzyltoluene:A bicyclic aromatic compound with negligible vapor pressure and thermal stability above 300°C. German hydrogen refueling station developers favor this chemistry for urban deployment due to simplified handling protocols under KBA transport classifications.
- Toluene:A monocyclic aromatic hydrocarbon with established petrochemical supply chains. Japan's METI-certified SPERA maritime import system from Brunei anchors demand for this carrier in Asia-Pacific hydrogen corridors.
- Naphthalene:A polycyclic aromatic with higher hydrogen storage density per unit volume. Emerging interest from chemical synthesis operators seeking feedstock integration.
- Methylcyclohexane:A saturated cyclic hydrocarbon leveraging existing toluene logistics infrastructure. Preferred in markets prioritizing rapid corridor deployment without dedicated tanker builds.
Volume placements concentrate in dibenzyltoluene; the faster expansion belongs to methylcyclohexane.
Application:
Cost tier differentiation separates large-scale infrastructure plays from distributed energy assets.
- Transportation:Maritime hydrogen corridors and heavy-duty fueling networks. Chiyoda Corporation's commercial-scale deployments and German refueling infrastructure investments anchor this segment's capital intensity.
- Energy Storage:Grid-scale hydrogen buffering for seasonal renewable arbitrage. German industrial clusters drive procurement for electricity-to-hydrogen-to-electricity assets.
- Chemical Synthesis:Green hydrogen feedstock for ammonia and methanol production. Rotterdam and Hamburg power-to-X developers embed LOHC transport clauses in long-term supply agreements.
- Fuel Cells:Stationary and mobile power generation requiring high-purity hydrogen release. EMA purity standards and EU Green Deal certification thresholds shape carrier eligibility.
Transportation commands the dominant capital allocation; energy storage is climbing the fastest.
End User:
Customer type determines contractual structures, with industrial offtakers consolidating around decade-long carrier service agreements.
- Industrial:Steel and chemical decarbonization clusters in Germany's Ruhr region. Hydrogenious Technologies anchors European project pipelines with dedicated hydrogenation reactor investments.
- Automotive:Heavy-duty and passenger fuel cell vehicle fleets. Urban refueling station economics favor dibenzyltoluene for ambient-pressure storage.
- Aerospace:Emerging demand for sustainable aviation fuel precursors and airport hydrogen logistics. Early-stage certification alignment with EU taxonomy criteria.
- Power Generation:Grid operators and independent power producers seeking seasonal storage. Waste heat integration from dehydrogenation facilities remains structurally underdeveloped.
Industrial procurement dominates contract value; automotive deployment is gaining share fastest.
Technology:
Supply concentration in catalyst manufacturing exposes project timelines to platinum-group metal sourcing constraints.
- Catalytic Hydrogenation:Exothermic binding of hydrogen to carrier molecules using platinum or palladium catalysts. BASF SE sustains R&D intensity for dibenzyltoluene formulation optimization.
- Dehydrogenation:Endothermic hydrogen release at 250–350°C consuming approximately 30% of stored energy value. Heat offtake agreements remain underdeveloped, compressing project returns.
- Thermal Process:Direct heating systems for hydrogen release without catalytic beds. Emerging interest for simplified maintenance in remote corridor terminals.
- Pressure Swing Adsorption:Purification technology for hydrogen stream conditioning post-release. Required for fuel cell applications under EMA and METI purity frameworks.
Catalytic hydrogenation anchors installed capacity; pressure swing adsorption shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum-group metal deposits in South Africa and Russia concentrate catalyst supply chains for LOHC hydrogenation reactors. Maritime hydrogen corridors from Brunei to Japan demonstrate commercial viability for toluene-based systems. German industrial clusters anchor European dibenzyltoluene deployment for refueling infrastructure.
Germany
The Ruhr industrial corridor drives dibenzyltoluene demand for steel and chemical decarbonization clusters. KBA transport classifications favor this carrier chemistry for urban hydrogen refueling stations under simplified handling protocols. Hydrogenious Technologies anchors project pipelines with dedicated hydrogenation reactor investments in North Rhine-Westphalia.
Japan
Commercial-scale hydrogen imports from Brunei via Chiyoda Corporation's SPERA system validate toluene-based maritime corridors. METI certification frameworks establish purity standards for cross-border hydrogen trade. Tokyo Bay industrial zones concentrate dehydrogenation terminal development for power-to-X applications.
Netherlands
Rotterdam port authorities integrate LOHC transport clauses into long-term hydrogen supply agreements for ammonia and methanol producers. REACH registration requirements tighten mass balance documentation for renewable hydrogen attribution. The port's industrial cluster attracts power-to-X developers embedding carrier services into electrolyzer investment decisions.
China
Wuhuan Engineering and domestic catalyst producers scale hydrogenation reactor manufacturing for Asia-Pacific corridor deployment. The country's dual carbon goals accelerate LOHC interest for seasonal renewable energy storage. Yangtze River Delta industrial zones pilot dibenzyltoluene systems for grid-scale hydrogen buffering.
United States
Gulf Coast petrochemical corridors repurpose existing toluene logistics infrastructure for methylcyclohexane LOHC deployment. EPA handling protocols and OSHA safety standards shape carrier selection for domestic hydrogen distribution networks. Texas industrial clusters evaluate waste heat integration from dehydrogenation facilities to improve project economics.
Liquid Organic Hydrogen Carrier (LOHC) Market Competitive Landscape
Established chemical producers occupy the standard tier; emerging hydrogen technology ventures pursue dedicated LOHC system integration. The market structure reflects moderate consolidation around petrochemical incumbents with hydrogenation expertise, complemented by specialized storage technology developers. Two strategic archetypes dominate: integrated chemical conglomerates leveraging existing aromatic production, and pure-play hydrogen storage specialists commercializing proprietary reactor designs. Competitive moves concentrate on strategic partnerships for maritime corridor deployment and technology licensing for regional hydrogen hub integration.
Within the integrated chemical tier, BASF SE and Mitsubishi Chemical Corporation exemplify incumbents with dibenzyltoluene formulation capabilities and established aromatic supply chains. Hydrogenious Technologies represents the pure-play archetype, occupying a position as a dedicated LOHC system developer with proprietary storage technology. Chiyoda Corporation anchors the maritime corridor specialization segment, having demonstrated commercial-scale deployment through its SPERA system. These three entities collectively illustrate the competitive spectrum from petrochemical scale advantages through specialized hydrogen logistics expertise.
| Leading Market Players |
|---|
| Covalion |
| Mitsubishi Chemical Corporation |
| Hynertech |
| Air Products and Chemicals |
| BASF SE |
| Chiyoda Corporation |
| Wuhuan Engineering |
| Toyota Tsusho Corporation |
| Hydrogenious Technologies |
| Others |
Pricing and Supply Chain Analysis
Long-term hydrogen supply agreements from German steel and chemical decarbonization clusters are compressing spot market liquidity and forcing carrier suppliers toward decade-long offtake structures with embedded service warranties. This contractual shift toward bundled hydrogen release services is reshaping how LOHC projects monetize thermal energy recovery and catalyst replacement cycles.
Pricing Analysis
Warranty bundling distinguishes LOHC service contracts, with premium tiers covering catalyst replacement and dehydrogenation heat offtake guarantees while economy tiers strip these to bare hydrogen delivery obligations. Price differentiation centers on certification grade under EU Green Deal delegated acts and METI purity frameworks, with renewable hydrogen attribution commanding substantial premiums over uncertified supply. Pricing pressure stems from liquefied hydrogen competition in short-distance regional distribution networks, where cryogenic density advantages compress LOHC margins. Industrial offtakers in the Ruhr region exhibit lowest price sensitivity due to decarbonization mandates, while automotive refueling station developers face acute capital constraints and demand unbundled carrier-only procurement.
Supply Chain Analysis
Carrier molecule refurbishment through hydrogenation reactor cycling creates reverse-logistics value streams that remain structurally underdeveloped, stranding potential catalyst recovery economics. Platinum-group metal catalyst production concentrates in South Africa and Russia, drawing LOHC project timelines into geopolitical supply risk exposure. Raw material dependencies span aromatic hydrocarbon feedstocks from petrochemical complexes, specialized reactor vessels from German and Japanese fabricators, and pressure swing adsorption membranes for hydrogen purification. Single-source vulnerability in platinum-group metal supply chains threatens project economics during price spikes. Distribution runs through maritime tanker fleets repurposed from existing chemical transport and dedicated hydrogenation terminal networks at Rotterdam, Hamburg, and Tokyo Bay.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated chemical conglomerates with captive aromatic supply chains, as pure-play hydrogen storage specialists face margin compression from catalyst cost volatility and dehydrogenation energy penalties that weaker balance sheets cannot absorb.
For Market Incumbents: Hedge catalyst supply exposure through offtake agreements with South African platinum-group metal producers or backward integration into catalyst recycling infrastructure. BASF SE and Mitsubishi Chemical Corporation should accelerate dibenzyltoluene capacity additions in North Rhine-Westphalia to anchor European hydrogen corridor development before regulatory certification timelines harden. Defensive patent positioning around thermal process dehydrogenation alternatives will protect against emerging thermal-release competitors.
For New Entrants and Emerging Players: EU Green Deal delegated acts in Germany open a window for specialized dehydrogenation heat integration services, addressing the structurally underdeveloped waste heat offtake market that incumbent chemical producers ignore. White-space targets include grid-scale hydrogen buffering installations in Yangtze River Delta industrial zones and aerospace hydrogen logistics at EU taxonomy-aligned airports. The most penetrable segment is methylcyclohexane corridor deployment leveraging existing toluene logistics, where petrochemical incumbents lack dedicated hydrogen expertise. Go-to-market positioning should emphasize blockchain-based mass balance tracking for REACH compliance.
For Investors and Strategic Acquirers: The window for entry favors pure-play hydrogen storage technology developers with proprietary reactor designs and established METI or EU Green Deal certification pathways. Long-term viability hinges on bilateral regulatory harmonization between Japanese and European hydrogen purity standards, which would eliminate dual-certification costs and expand addressable market scope for transcontinental suppliers. Acquisition targets should demonstrate commercial-scale deployment experience, such as demonstrated maritime corridor operation or grid-scale buffering installations. The critical signal to monitor is catalyst supply agreement renegotiation activity, which indicates stress in project economics and potential distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Supply | Secures platinum-group metal access for Hydrogenious Technologies and reduces exposure to South African supply disruptions. |
| Long-term Hydrogen Supply Agreement | Rotterdam power-to-X developers embed LOHC transport clauses to de-risk electrolyzer investments with offtake certainty. |
| Green Certification Program | EU Green Deal delegated acts validate renewable hydrogen attribution for cross-border trade corridor financing access. |
| Technology Licensing | Chiyoda Corporation's SPERA system template enables rapid Asia-Pacific corridor replication without proprietary reactor development. |
| Joint Venture | German industrial clusters partner with hydrogen refueling developers to share hydrogenation reactor capital intensity. |
Research Methodology
Independent corroboration across hydrogen refueling infrastructure developers, electrolyzer project financiers, and petrochemical procurement leads underwrites the qualitative findings on LOHC carrier selection criteria. Primary interviews with plant managers at German hydrogenation facilities, regulatory affairs specialists tracking EU Green Deal implementation, and maritime logistics operators in Rotterdam and Tokyo Bay were cross-referenced against secondary validation from EIA hydrogen trade data, IEA renewable hydrogen reports, FERC filings on power-to-X project interconnections, and customs records of aromatic hydrocarbon feedstock flows. Bottom-up project pipeline aggregation and top-down market sizing triangulate volume estimates.
Rate-of-change decomposition across carrier chemistry adoption curves, dehydrogenation technology efficiency improvements, and regulatory certification timeline accelerations structures the analytical framework. Segmentation dimensions modeled include carrier type, application, end-user industry, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to commercial deployment announcements and hydrogen corridor commissioning schedules. Industry-specific forecast inputs incorporate platinum-group metal price volatility scenarios and METI-EU certification harmonization probability assessments.
The model assumes a particular technology adoption path; alternative pathways for thermal process dehydrogenation without catalytic beds would alter the outlook by compressing maintenance requirements and expanding remote terminal viability. Forecasts reflect assumptions about renewable hydrogen subsidy durability and maritime insurance acceptance of LOHC transport. Practitioners should monitor catalyst supply agreement renegotiation frequency and bilateral METI-EU certification alignment announcements for early signals of market structure shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Liquid Hydrogen Tank Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Electrolyzer Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
Hydrogen Market