

Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market Insights
SAE J2601 fueling protocol certification is reorganizing competitive entry barriers for test system suppliers. CSA Group leverages its North American standards authority to anchor hydrogen dispenser validation workflows. HORIBA FuelCon sustains R&D intensity in integrated fueling simulation rigs. UL Solutions differentiates through safety-science credentials that span electrical, pressure, and materials testing domains.
Hydrogen refueling protocol and dispenser performance test systems comprise calibrated instrument suites that verify pressure ramp rates, temperature compensation accuracy, and communication handshake integrity between vehicle and station under SAE and ISO specifications. These systems enforce mass flow precision within grams per second tolerance bands to prevent tank overfill or thermal damage during fast fills. Pressure sensor systems and flow meter instruments command premium pricing due to metrological traceability requirements, while control software segments gain share as stations adopt predictive maintenance architectures. Automated calibration technology reduces field service intervals, shifting margin pools toward subscription-enabled diagnostic platforms.
FDA-equivalent energy safety frameworks in Germany through KBA and in Japan through METI mandate type-approval testing for all commercial hydrogen dispensers, creating recurring revenue for certification bodies and equipment manufacturers alike. The EPA and NHTSA in the United States coordinate on heavy-duty vehicle emission thresholds that indirectly accelerate station buildout and associated test infrastructure procurement. Stakeholders must monitor which national metrology institutes will host reference standards for next-generation 700-bar dispensing protocols.
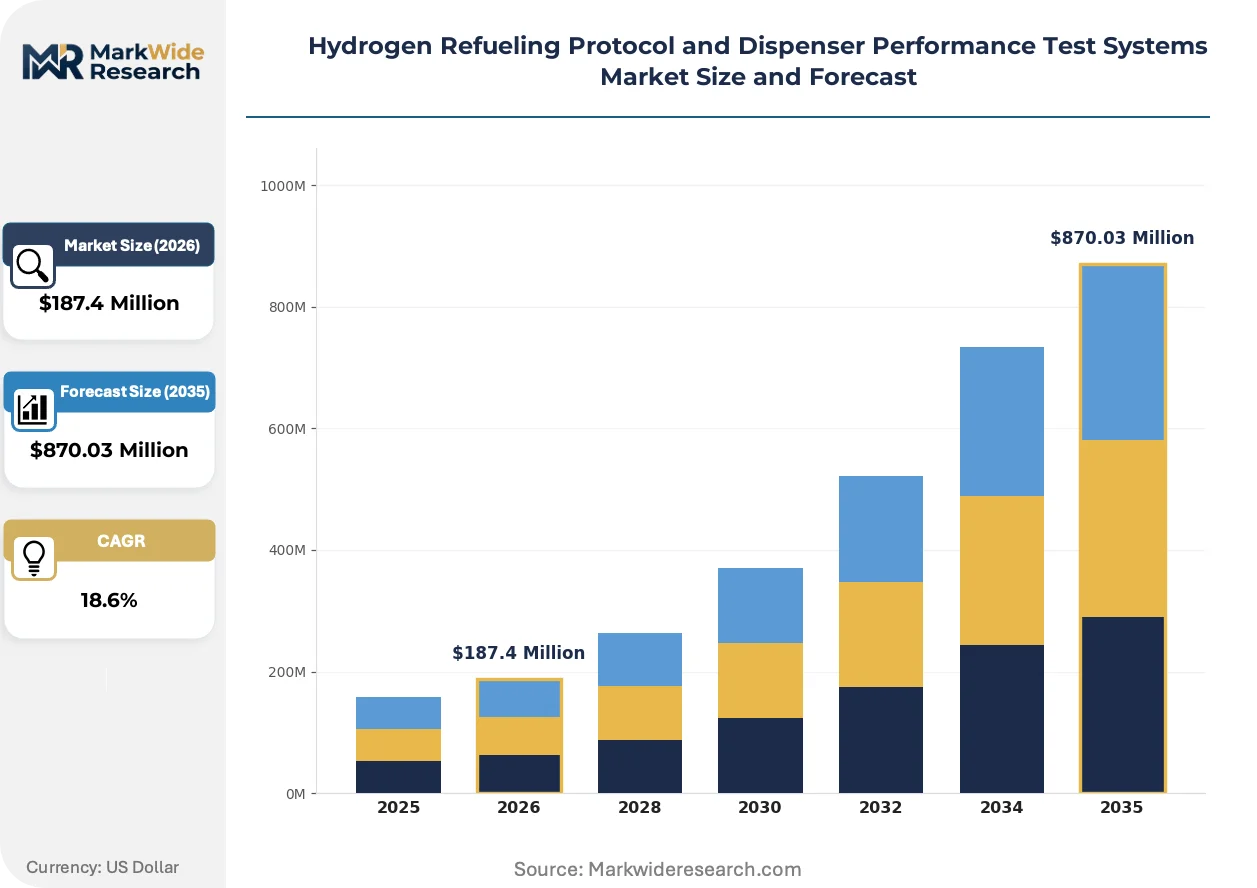
Market Dynamics
SAE J2601 protocol revisions and ISO 19880 certification tightening are compressing equipment qualification cycles, forcing test system suppliers to accelerate validation throughput while maintaining metrological traceability.
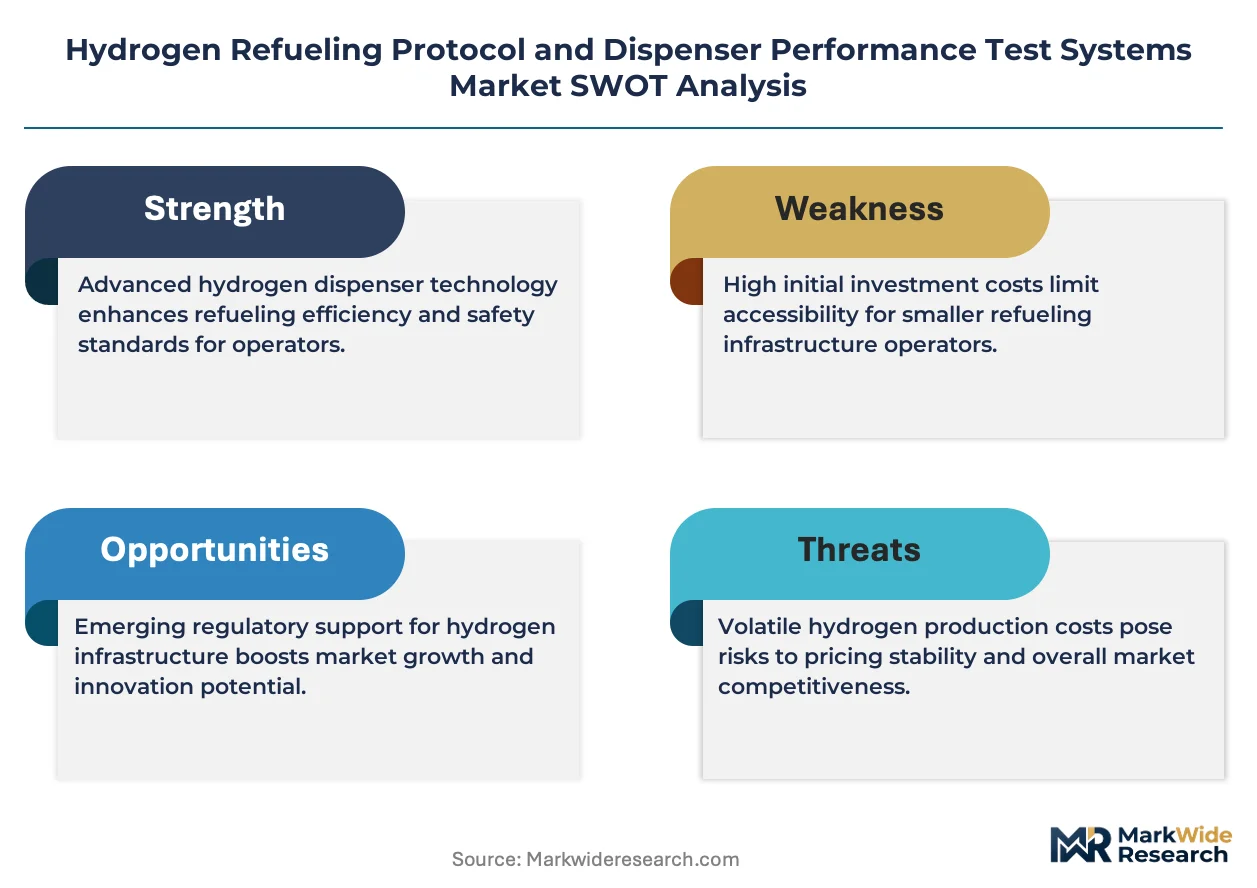
Growth Catalysts
- Heavy-duty fleet electrification mandates:California's Advanced Clean Trucks regulation and Germany's KBA type-approval requirements are mandating hydrogen infrastructure buildout, creating sustained demand for dispenser validation equipment.
- 700-bar protocol maturation:Next-generation fueling specifications for heavy commercial vehicles are expanding the addressable instrument market beyond light-duty passenger applications.
- Industrial corridor clustering:Automotive OEMs and energy utilities in Germany's Rhine-Ruhr region are co-investing in high-throughput stations, concentrating procurement of integrated test rigs.
Market Restraints
- Metrology-grade sensor scarcity:Pressure transducers and Coriolis flow meters with NIST-traceable calibration command 40-60% price premiums, constraining station operator capex flexibility.
- Certification body concentration:CSA Group, UL Solutions, and TÜV hold effective oligopoly over North American and European dispenser validation, limiting supplier negotiation leverage.
- Electrolyzer capacity bottlenecks:Green hydrogen production shortfalls in Japan and California are delaying station commissioning timelines and deferring test system procurement.
Strategic Opportunities
- Predictive maintenance software:Automated calibration technology is enabling subscription diagnostic platforms that shift margin pools from hardware sales to recurring revenue streams.
- Asia-Pacific regulatory alignment:METI's hydrogen roadmap and China's GB standards development are creating openings for test system suppliers to anchor regional certification workflows.
- Multi-fuel dispenser integration:Convergence of hydrogen and compressed natural gas dispensing infrastructure is expanding instrument suite addressability at integrated mobility hubs.
Industry Challenges
- Cross-disciplinary engineering scarcity:Test system development requires simultaneous competence in high-pressure thermodynamics, SAE protocol firmware, and safety-science validation, compressing talent pipelines.
- Field service calibration complexity:Maintaining metrological traceability for pressure sensors and mass flow meters at remote station sites extends service intervals and elevates operational overhead.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market Trends and Innovations
Digital twin architectures and embedded AI diagnostics are displacing periodic manual calibration with continuous condition monitoring, restructuring service revenue models across the supplier base.
Digital twin simulation platforms are replicating SAE J2601 fueling sequences in virtual environments before physical station commissioning. Station developers in Germany and California are adopting these tools to compress validation timelines. The technology is bifurcating the market between suppliers offering integrated hardware-software bundles and those confined to discrete instrument sales.
EPA and NHTSA coordination on heavy-duty vehicle emission thresholds is indirectly accelerating station buildout and associated test infrastructure procurement. The regulatory pressure is forcing dispenser manufacturers to front-load certification investments. European OEMs are responding by consolidating validation contracts with full-service metrology providers.
After-sales service unbundling is separating hardware warranties from calibration maintenance contracts. Fleet operators and station developers in Japan are preferring outcome-based service agreements that guarantee uptime rather than equipment ownership. This restructuring is most visible in METI-subsidized hydrogen corridor projects where operational availability clauses dominate procurement specifications.
Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market Segmentation
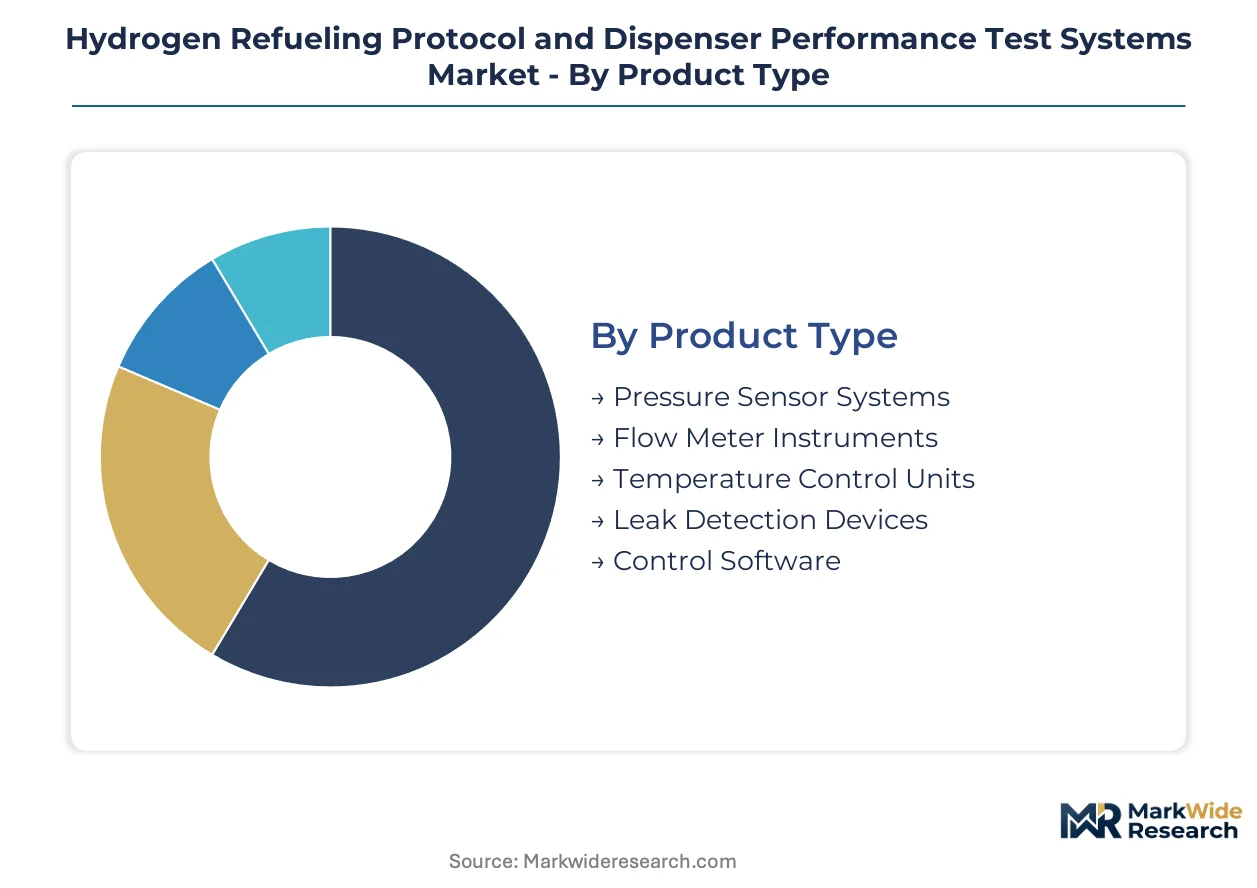
Segmentation in hydrogen refueling test systems reveals how regulatory pressure cascades through equipment specifications and procurement patterns. Each dimension—product, technology, application, and end user—carries distinct compliance burdens that reshape supplier positioning and margin structures.
Product Type:
SAE J2601 and ISO 19880 certification tiers differentiate instrument pricing by metrological rigor, with NIST-traceable variants commanding substantial premiums over industrial-grade alternatives.
- Pressure Sensor Systems:These instruments measure ramp rate accuracy and peak pressure containment during 700-bar fueling sequences. Demand concentrates in Germany's KBA-mandated type-approval laboratories, where calibration traceability requirements exclude lower-tier suppliers from qualification workflows.
- Flow Meter Instruments:Coriolis and thermal mass configurations enforce grams-per-second precision to prevent tank overfill. California's heavy-duty fleet operators prioritize these systems for Advanced Clean Trucks compliance, driving procurement at high-throughput station clusters in the Central Valley and Los Angeles basin.
- Temperature Control Units:Compensation modules manage thermal gradients during fast fills. Japan's METI-subsidized corridors specify these for pre-cooling validation.
- Leak Detection Devices:Hydrogen-specific sensors with flame-ionization detection secure station safety perimeters. German TÜV certification mandates govern adoption.
- Control Software:Embedded protocols execute SAE J2601 handshake sequences between vehicle and dispenser. Predictive maintenance architectures are shifting procurement toward subscription licensing in North American deployments.
Pressure sensor systems handle the majority of throughput; control software is expanding most quickly on share.
Technology:
Station digitization intensity varies by operator sophistication, with integrated mobility hubs in industrial corridors leading adoption of connected instrument suites.
- Wireless Connectivity:Industrial IoT protocols enable remote diagnostic access for dispersed station networks. Fleet operators in California's hydrogen corridors deploy these to reduce field service intervals across geographically distributed assets.
- Data Analytics:Pattern recognition algorithms predict sensor drift before calibration failure. German OEM-utility consortia embed these capabilities in Rhine-Ruhr high-throughput stations to guarantee uptime clauses.
- Real-Time Monitoring:Continuous condition surveillance displaces periodic manual calibration. Japanese METI projects specify these for operational availability guarantees.
- Automated Calibration:Self-adjusting instrument loops reduce technician dispatch frequency. Adoption tracks labor cost differentials across regions.
- Cybersecurity Protocols:IEC 62443-aligned defenses protect dispenser-vehicle communication integrity. European critical infrastructure designations are hardening requirements.
Data analytics commands the steepest expansion trajectory; wireless connectivity remains the workhorse across installed base.
Application:
Application segmentation reflects the certification chain from component validation through operational compliance, with each stage imposing distinct instrument configurations.
- Fuel Cell Vehicle Refueling:End-to-end protocol verification for light-duty and heavy-duty hydrogen tanks. California's Advanced Clean Trucks regulation is accelerating heavy-duty validation rig procurement.
- Station Safety Assessment:Pressure containment and emergency shutdown verification. Germany's KBA mandates recurrent assessment cycles for commercial dispensers.
- Infrastructure Maintenance:Predictive diagnostics for compressor, storage, and dispenser subsystems. Japanese fleet operators prefer outcome-based maintenance contracts.
- Compliance Testing:Formal certification workflows for SAE J2601 and ISO 19880 adherence. CSA Group and UL Solutions anchor North American validation demand.
- Performance Validation:Throughput and accuracy benchmarking for station commissioning. Industrial corridor clustering concentrates procurement in Germany and California.
Compliance testing absorbs the dominant certification expenditure; infrastructure maintenance is climbing fastest as operational contracts displace equipment sales.
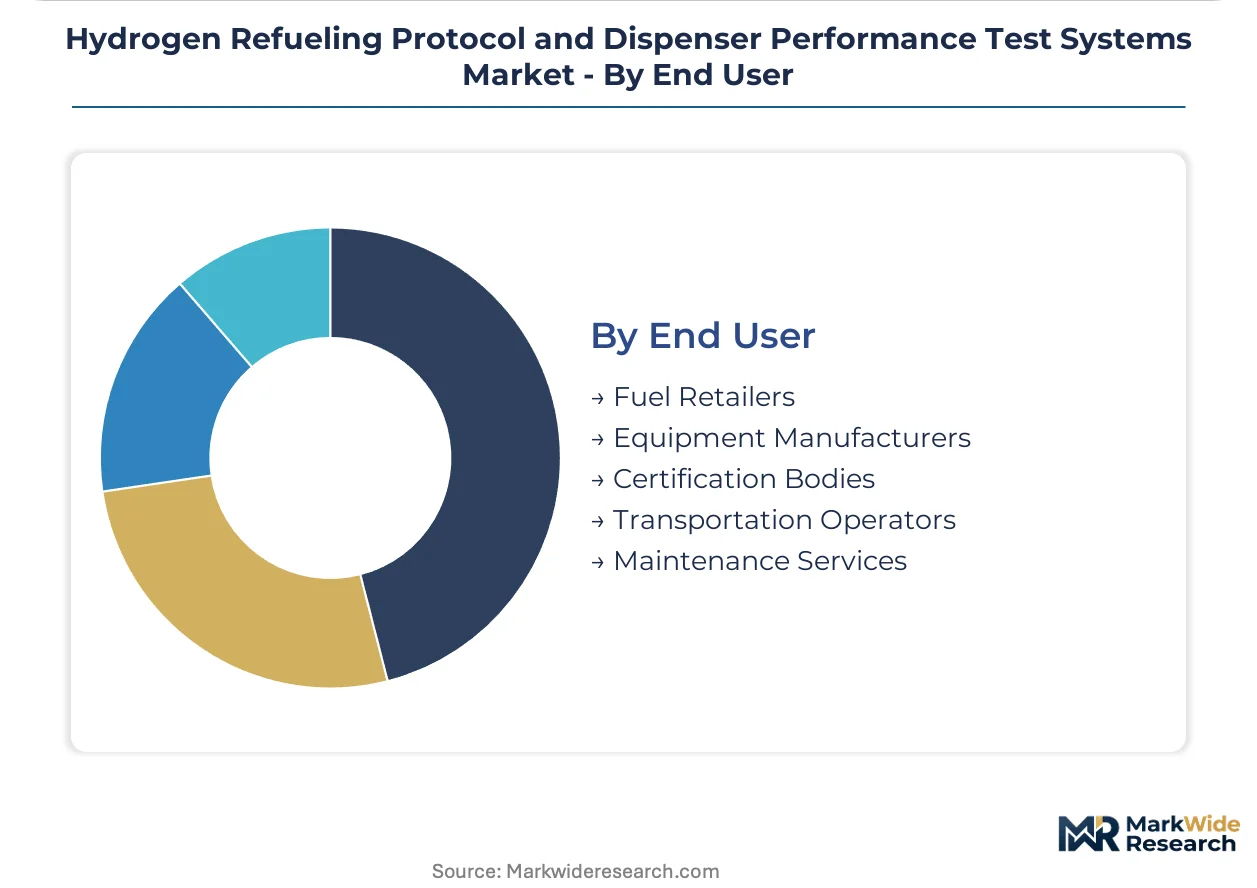
End User:
Procurement authority fragmentation across the value chain creates multiple entry points, each with distinct technical specifications and contract structures.
- Fuel Retailers:Hydrogen station operators purchasing integrated test rigs for commissioning and recurrent validation. Germany's industrial corridor consortia consolidate procurement through OEM-energy utility partnerships.
- Equipment Manufacturers:Dispenser builders acquiring in-house validation capabilities to compress KBA and METI type-approval timelines. Vertical integration pressures are rising.
- Certification Bodies:CSA Group, UL Solutions, and TÜV procuring reference-grade instrument suites for third-party validation services. Oligopoly concentration limits supplier negotiation leverage.
- Transportation Operators:Fleet owners specifying test system inclusion in station buildout contracts. California heavy-duty operators drive this segment.
- Maintenance Services:Field service providers acquiring portable calibration equipment for remote station support. Metrological traceability at distance remains the operational constraint.
Certification bodies dominate premium instrument demand; transportation operators are gaining procurement influence fastest as fleet-scale deployments expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific Coast Hydrogen Hub and German hydrogen core network anchor infrastructure investment corridors where test system procurement concentrates. California's heavy-duty freight corridors and Germany's Rhine-Ruhr industrial belt generate the dominant validation equipment demand. Japan's METI-subsidized hydrogen supply chains complete the triad of high-activity markets.
United States
California's Advanced Clean Trucks regulation mandates zero-emission heavy-duty fleet transitions by 2036. The EPA coordinates with NHTSA on emission thresholds that accelerate hydrogen station buildout. The Central Valley and Los Angeles basin concentrate high-throughput station clusters where dispenser validation rigs deploy at scale.
Germany
KBA type-approval requirements enforce recurring certification cycles for all commercial hydrogen dispensers. The EU Green Deal hydrogen backbone initiative funds industrial corridor infrastructure. North Rhine-Westphalia hosts OEM-utility consortia co-investing in Rhine-Ruhr high-throughput stations with integrated test capabilities.
Japan
METI's hydrogen roadmap subsidizes corridor development connecting industrial ports to urban demand centers. JIS standards alignment with SAE J2601 protocols tightens equipment qualification specifications. The Chubu region around Nagoya anchors automotive OEM validation partnerships with test system suppliers.
China
MIIT's fuel cell vehicle demonstration cities program expands hydrogen infrastructure in the Yangtze River Delta. GB standards development for 700-bar dispensing protocols creates certification workflow openings. Shanghai and surrounding Jiangsu province concentrate state-owned energy utility station investments.
South Korea
The government's hydrogen economy roadmap targets 200,000 fuel cell vehicles by 2025. MFDS-equivalent energy safety frameworks mandate dispenser type-approval testing. The Ulsan-Busan industrial corridor hosts petrochemical conglomerate hydrogen station deployments with embedded validation requirements.
Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market Competitive Landscape
Listed leaders compete with private specialists across certification authority and technology integration dimensions. The market structure concentrates around standards-body-affiliated validators and full-service metrology providers. Three archetypes dominate: certification-authority-anchored validators, integrated instrument-software bundlers, and national-laboratory-linked technology developers. Competitive moves center on strategic partnerships with automotive OEMs and backward integration into sensor manufacturing.
Among North American certification-authority-anchored validators, CSA Group and UL Solutions occupy positions where safety-science credentials translate into dispenser validation workflow control. HORIBA FuelCon represents the integrated instrument-software bundler archetype with sustained R&D intensity in fueling simulation rigs. These three exemplify how metrological authority and protocol firmware competence combine to create defensive positioning around tightening SAE and ISO qualification cycles.
| Leading Market Players |
|---|
| Powertech Labs |
| CSA Group |
| AVL List GmbH |
| HORIBA FuelCon |
| Intertek |
| UL Solutions |
| PDC Machines |
| Sandia National Laboratories |
| National Renewable Energy Laboratory |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at NIST-traceable calibration laboratories in Germany and the United States shapes both supply concentration and price floors for hydrogen refueling test systems, with metrological-grade sensor scarcity elevating baseline procurement costs for station operators.
Pricing Analysis
Three-tier pricing structure across NIST-traceable premium, ISO-certified standard, and industrial-grade economy levels dominates procurement contracts, with certification grade and after-sales service bundling as the primary differentiation drivers. Cost compression in the economy tier is intensifying because fleet operators defer non-mandatory validation cycles amid electrolyzer capacity bottlenecks. Transportation operators exhibit highest price sensitivity due to outcome-based contract structures, while certification bodies demonstrate lowest sensitivity given regulatory-mandated precision requirements.
Supply Chain Analysis
Just-in-time inventory strategies prevail for Coriolis flow meters and pressure transducers, though strategic stockpiling of hydrogen-specific leak detection sensors is emerging among German OEM-utility consortia. Manufacturing concentrates in Germany, Japan, and the United States, with supply anchored in specialized high-pressure thermodynamics component fabrication. Single-source vulnerability for NIST-traceable calibration services represents the dominant structural risk. Distribution runs through direct OEM partnerships and certification-body-anchored validation service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics driven by heavy-duty fleet electrification mandate timelines, with procurement waves tracking regulatory compliance deadlines rather than organic demand growth.
For Market Incumbents: Compound defensive positioning through backward integration into sensor manufacturing and captive calibration laboratory capacity in North Rhine-Westphalia. Emerging software-native competitors threaten hardware-centric margin pools, making predictive maintenance platform investment the priority lever for recurring revenue conversion.
For New Entrants and Emerging Players: Anchor in Asia-Pacific regulatory alignment opportunities, specifically METI-subsidized hydrogen corridor projects in Japan's Chubu region where incumbent certification body presence remains underdeveloped. Portable calibration equipment for remote station maintenance represents the most penetrable white-space segment, with outcome-based service contracting as the viable go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated instrument-software bundlers over discrete component suppliers across the projection horizon. Long-term viability hinges on protocol firmware competence rather than hardware manufacturing scale. Acquisition targets should display embedded AI diagnostic capabilities and SAE J2601 protocol certification authority. The signal to monitor is 700-bar protocol maturation timelines for heavy commercial vehicles.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Body Partnership | CSA Group and UL Solutions validation workflow anchoring accelerates market entry timelines. |
| Predictive Maintenance Platform Launch | Subscription diagnostic architectures shift margin pools from hardware sales at California fleet operators. |
| Backward Integration into Sensor Manufacturing | In-house production of NIST-traceable pressure transducers reduces procurement cost volatility. |
| Digital Twin Simulation Development | Virtual SAE J2601 fueling sequence replication compresses German station commissioning timelines. |
| Asia-Pacific Certification Workflow Expansion | METI and GB standards alignment creates regional validator positioning in Japan and China. |
Research Methodology
Initial hypotheses were tested against primary input from hydrogen station commissioning engineers, certification body validation specialists, fuel cell vehicle platform engineers, and fleet operator procurement directors and refined through secondary validation against SAE J2601 protocol documentation, ISO 19880 certification standards, KBA type-approval filings, and METI hydrogen roadmap disclosures. Bottom-up instrument shipment tracking and top-down infrastructure investment flow analysis enabled triangulation across modeling approaches.
Variance decomposition across product type, technology tier, application stage, and end-user procurement authority dimensions structured the analytical framework, with CAGRs derived from segment-level growth rate reconciliation against aggregate market trajectory. Electrolyzer capacity commissioning schedules and heavy-duty fleet electrification mandate timelines served as industry-specific forecast inputs throughout the projection horizon.
Material uncertainties — green hydrogen production shortfalls, 700-bar protocol revision timing, and national metrology institute reference standard relocations — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory compliance deadline adherence and certification cycle compression rates. Revision becomes warranted when electrolyzer capacity bottlenecks extend station commissioning deferrals beyond threshold durations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.