
 Hydrogen Purifiers Market | 2026-2036
Hydrogen Purifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Purifiers Market Foresight
Data center operators and semiconductor fabs are redrawing the buyer landscape for hydrogen purifiers as their uptime-critical operations require ultra-high-purity hydrogen for generator cooling and chip fabrication. Air Products dominates on-site gas supply contracts for electronics-grade hydrogen, leveraging its pipeline network across the U.S. Gulf Coast. Linde sustains leadership in cryogenic purification systems for aerospace test facilities, while Mott Corporation specializes in porous metal membrane filters that compete on filtration efficiency at sub-micron levels.
Hydrogen purifiers are systems that remove contaminants such as water vapor, oxygen, nitrogen, and hydrocarbons from hydrogen feedstock, typically achieving purity levels from 99.99% to 99.9999% depending on the application through pressure swing adsorption, membrane diffusion, or catalytic deoxidation processes. PSA technology anchors the installed base due to its scalability for chemical production facilities requiring continuous bulk purification. Membrane separation is capturing incremental share in fuel cell applications where compact footprint and modular expansion matter more than absolute throughput. The automotive end user segment concentrates margin pools around proton exchange membrane-compatible purity standards as OEMs qualify suppliers for hydrogen refueling station networks.
The U.S. EPA and OSHA enforce hydrogen handling and purity disclosure standards that shape equipment certification requirements for domestic installations. The EU Green Deal and F-Gas Regulation are accelerating demand for purification systems that support fluorinated gas-free industrial processes across member states. Stakeholders must monitor how the EU AI Act and emerging digital certification requirements for hydrogen quality tracking will reshape vendor qualification timelines and aftermarket service obligations.
Market Dynamics
The hydrogen purifiers market is restructuring around the tension between centralized chemical plant scale and distributed fuel cell infrastructure. Pressure swing adsorption systems anchor bulk industrial supply while membrane modules capture mobility and electronics applications requiring compact footprints.
Growth Catalysts
- EU Green Deal hydrogen mandates:Steel producers in the Rhine-Ruhr corridor must source certified green hydrogen, forcing purification upgrades at existing reforming facilities.
- Fuel cell logistics fleets:Heavy-duty truck operators in California and Germany are qualifying station networks that demand PEM-compatible 99.97% purity standards.
- Semiconductor fab expansion:Taiwan and South Korea are adding capacity for advanced node production where generator cooling requires ultra-high-purity hydrogen with sub-ppb oxygen content.
Market Restraints
- Palladium membrane cost volatility:Russian and South African supply concentration exposes membrane system manufacturers to metal price swings that compress project margins.
- PSA system energy intensity:Compression cycles consume 15-25% of hydrogen energy content, limiting adoption in off-grid renewable hydrogen projects.
- EU F-Gas Regulation compliance friction:Refrigerant restrictions on cryogenic distillation units extend equipment qualification timelines by 12-18 months.
Strategic Opportunities
- India PLI scheme for electrolyzers:Domestic manufacturing incentives are creating demand for purification skids that pair with alkaline and PEM electrolyzer deployments.
- Ammonia cracking for maritime fuel:Singapore and Rotterdam port authorities are piloting hydrogen release from ammonia carriers, requiring novel impurity removal for fuel cell compatibility.
- Digital certification platforms:Blockchain-based hydrogen quality tracking under development in Germany and Japan opens aftermarket service contracts for sensor-integrated purifier systems.
Industry Challenges
- Cryogenic technician scarcity:Distillation system maintenance requires specialized training that outpaces vocational program output in the U.S. Gulf Coast and North Sea industrial clusters.
- Multi-standard certification complexity:Equipment must simultaneously satisfy ISO 14687 for fuel cells, SEMI standards for electronics, and customer-specific chemical purity protocols.
- Legacy SMR asset integration:Steam methane reforming plants retrofitted for carbon capture need purification upgrades that accommodate variable feedstock quality from biogas blending.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Purifiers Market |
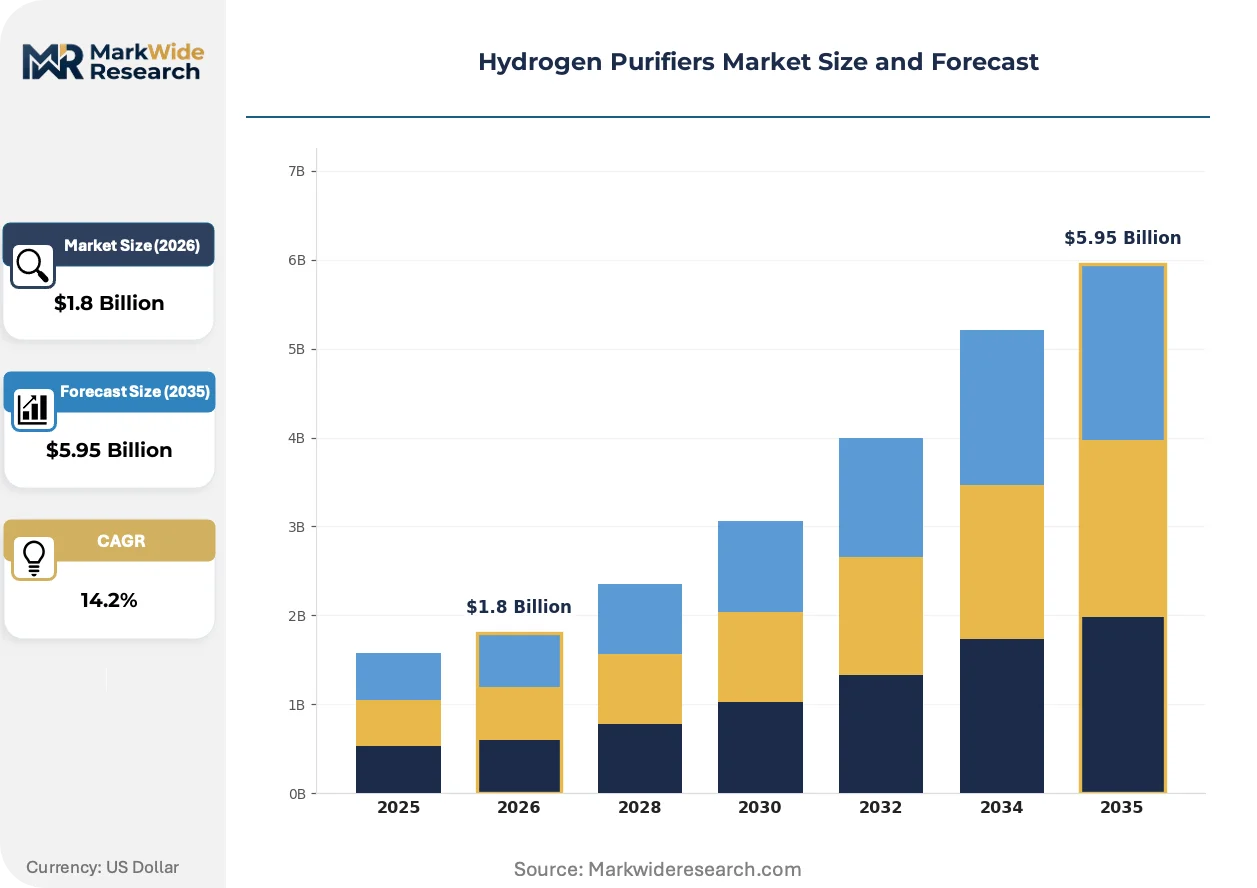
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PSA, Membrane Separation, Catalytic Purification, Cryogenic Distillation Application: Fuel Cells, Electronics Manufacturing, Chemical Production, Metal Treating Technology: Purification Technology, Pressure Swing Adsorption, Proton Exchange Membrane, Electrochemical Separation End User: Automotive Industry, Power Generation, Aerospace, Manufacturing |
| Companies Covered | Mott Corporation, Cummins, Linde, Sinopec, Air Liquide, Air Products, FuelCell Energy, Ballard Power Systems, Shell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Purifiers Market Shifts & Advancements
Electrification of transport and heavy industry is fragmenting hydrogen demand into purity-tiered segments. Modular purification architectures are displacing centralized systems as distributed production scales.
Compact palladium-alloy membrane modules are miniaturizing for vehicle onboard fuel processing and portable refueling applications. Fuel cell forklift fleets in warehouse logistics are adopting these units for site-level hydrogen generation from natural gas or methanol. The technology is miniaturizing the addressable market from megawatt-scale chemical plants down to kilowatt commercial installations.
The U.S. Inflation Reduction Act hydrogen production tax credits are redirecting capital toward domestic purification infrastructure. Project developers must demonstrate 99.9% carbon intensity thresholds that require purification systems capable of handling variable renewable feedstock quality. Electrolyzer OEMs in Texas and Louisiana are qualifying multi-stage PSA-membrane hybrid systems to secure credit eligibility.
Long-term gas supply contracts are fragmenting into purity-as-a-service arrangements. Data center operators in Northern Virginia and Frankfurt are unbundling hydrogen procurement from purification operations, paying per-kilogram premiums for guaranteed uptime rather than capital equipment ownership. This model concentrates risk with specialized service providers who maintain membrane replacement schedules and sensor calibration protocols.
Hydrogen Purifiers Market Segmentation
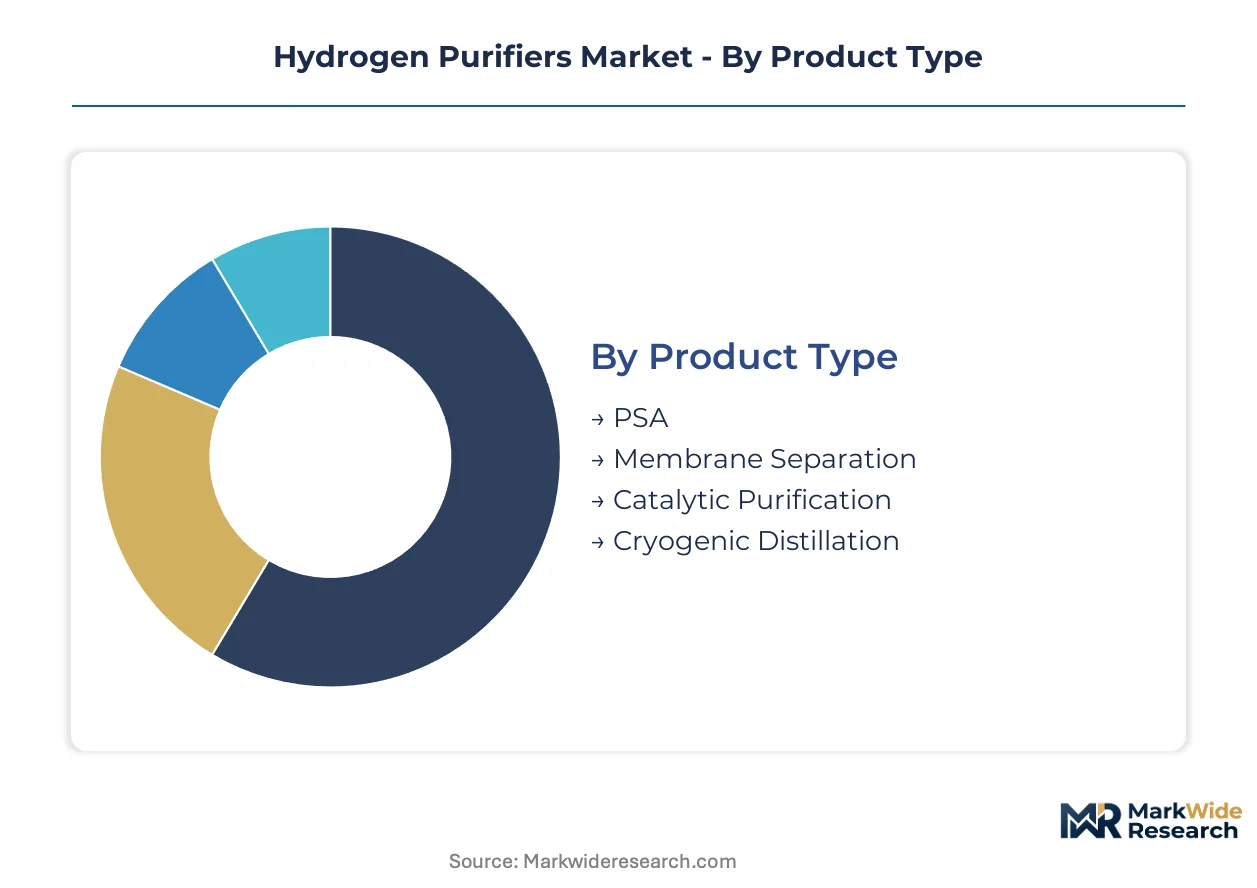
Hydrogen purifier selection hinges on purity thresholds that vary sharply across end-use certifications. Equipment specifications diverge based on whether the application demands fuel cell-grade hydrogen or ultra-high-purity gas for semiconductor fabrication.
Product Type:
Regulatory frameworks in Germany, Japan, and the United States enforce distinct certification requirements that favor specific purification architectures. The EU F-Gas Regulation restricts refrigerant use in cryogenic systems, while OSHA and EPA standards in the United States govern pressure vessel integrity and hydrogen handling protocols.
- PSA:Pressure swing adsorption systems utilize zeolite or activated carbon beds to remove nitrogen, oxygen, and moisture through cyclic pressurization and depressurization. Chemical production facilities in Germany's Rhine-Ruhr corridor deploy PSA units for continuous bulk purification where energy intensity is offset by scale economies. The EPA enforces leak detection standards that shape vessel design for domestic installations.
- Membrane Separation:Palladium-alloy or polymer membranes selectively permeate hydrogen while blocking larger contaminant molecules. Fuel cell vehicle refueling stations in California and Germany favor membrane modules for their compact footprint and modular expansion capability. The technology faces palladium cost volatility tied to South African and Russian supply concentration.
- Catalytic Purification:Deoxidation catalysts convert trace oxygen to water vapor for subsequent removal. Metal treating operations in Japan employ these systems for controlled atmosphere furnaces requiring moderate purity levels.
- Cryogenic Distillation:Ultra-low temperature separation achieves the highest purity grades through boiling point differentiation. Semiconductor fabs in Taiwan and South Korea specify cryogenic systems for sub-ppb contaminant removal. The EU F-Gas Regulation extends equipment qualification timelines by restricting traditional refrigerants.
Established volume favors PSA; emerging adoption favors Membrane Separation.
Application:
End-use purity specifications create tiered demand patterns that concentrate margin pools in electronics and fuel cell segments. Customer procurement cycles range from multi-year chemical plant contracts to rapid-deployment mobility infrastructure.
- Fuel Cells:Proton exchange membrane fuel cells demand 99.97% hydrogen purity with strict limits on carbon monoxide and sulfur compounds that poison catalysts. Heavy-duty truck fleets in California and Germany are qualifying station networks under ISO 14687 protocols. The United States Inflation Reduction Act production tax credits require demonstrated carbon intensity thresholds that purification systems must support.
- Electronics Manufacturing:Generator cooling and chip fabrication require ultra-high-purity hydrogen with sub-ppb oxygen and moisture content. Advanced node semiconductor expansion in Taiwan and South Korea drives specification escalation. SEMI standards govern impurity limits that exceed fuel cell requirements by orders of magnitude.
- Chemical Production:Ammonia synthesis and hydrocracking operations consume hydrogen at massive scale with purity requirements varying by process. Green hydrogen integration into German steel and chemical value chains is forcing purification upgrades at existing reforming facilities.
- Metal Treating:Heat treatment and powder metallurgy applications utilize hydrogen for reducing atmospheres and sintering processes. Automotive component suppliers in Japan and Germany specify controlled purity levels for consistent metallurgical outcomes.
Electronics Manufacturing commands premium pricing; Fuel Cells are expanding most quickly.
Technology:
Technology selection reflects a trade-off between purification depth, energy consumption, and system footprint that varies by deployment context. Hybrid architectures combining multiple mechanisms are gaining traction in variable renewable hydrogen projects.
- Purification Technology:Broad category encompassing physical and chemical contaminant removal methods. The term serves as umbrella classification for equipment qualification frameworks.
- Pressure Swing Adsorption:Cyclic gas separation exploiting differential adsorption affinities at varying pressures. Chemical producers favor PSA for proven reliability in continuous operation.
- Proton Exchange Membrane:Electrochemical purification leveraging selective proton transport through hydrated polymer membranes. Fuel cell applications specify PEM-compatible purity standards that OEMs enforce through supplier qualification.
- Electrochemical Separation:Voltage-driven hydrogen purification achieving high selectivity without thermal cycles. Emerging deployments pair with electrolyzer installations for integrated renewable hydrogen production.
Pressure Swing Adsorption anchors installed base; Electrochemical Separation shows steepest expansion trajectory.
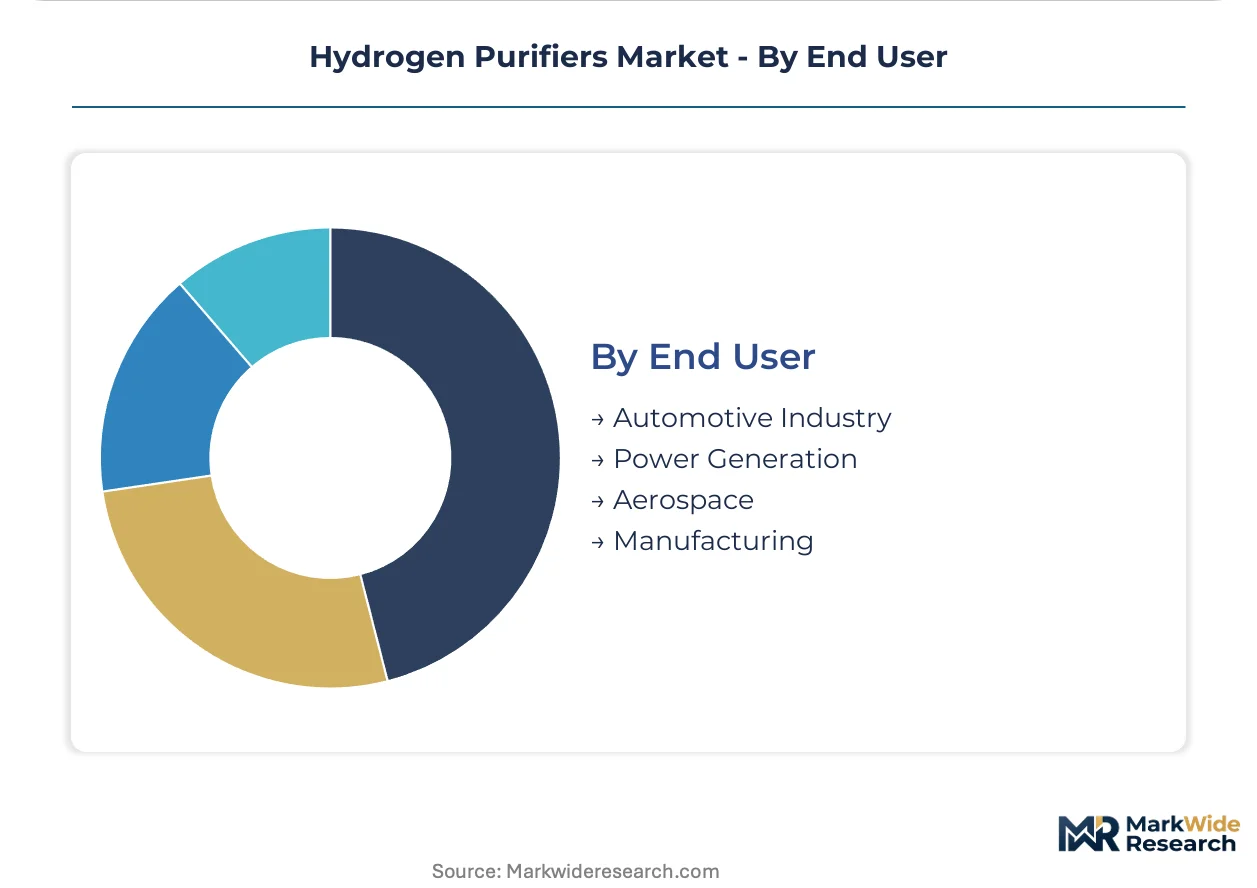
End User:
End user procurement patterns fragment between capital-intensive industrial operators and distributed infrastructure developers. Service models are unbundling equipment ownership from guaranteed purity delivery.
- Automotive Industry:OEMs and tier suppliers specify purification systems for fuel cell vehicle production and refueling networks. German and California fleet operators are committing to zero-emission logistics that demand PEM-compatible hydrogen at scale.
- Power Generation:Gas turbine co-firing and grid-scale storage applications are emerging demand centers. Pilot projects in Japan and Germany test hydrogen blending in existing infrastructure.
- Aerospace:Test facilities and launch operations require cryogenic hydrogen with extreme purity for propulsion system validation. Linde sustains leadership in this specialized segment.
- Manufacturing:Broad industrial category encompassing glass, food, and materials processing. Purity requirements vary widely, with some applications accepting lower grades that PSA systems deliver cost-effectively.
Automotive Industry concentrates investment velocity; Power Generation represents emerging volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports purification systems and technical expertise to hydrogen project developers across the European Union, particularly into steel and chemical corridors in the Netherlands and Poland.
United States
Fuel cell logistics fleets in California and Texas are qualifying station networks demanding PEM-compatible purity standards. The Inflation Reduction Act hydrogen production tax credits require demonstrated carbon intensity thresholds that purification systems must support. Gulf Coast industrial clusters around Houston and Baton Rouge are integrating carbon capture with SMR retrofits that need variable feedstock handling.
Germany
Steel producers in the Rhine-Ruhr corridor must source certified green hydrogen under EU Green Deal mandates, forcing purification upgrades at existing reforming facilities. The EU F-Gas Regulation restricts refrigerant use in cryogenic distillation units, extending equipment qualification timelines. Industrial clusters around Cologne and Duisburg are piloting blockchain-based hydrogen quality tracking for digital certification.
China
Electrolyzer manufacturing scale-up in Jiangsu and Shandong provinces is creating demand for purification skids that pair with alkaline and PEM deployments. The MIIT dual carbon goals are accelerating hydrogen integration into steel and chemical value chains. Yangtze River Delta industrial zones are qualifying multi-stage PSA-membrane hybrid systems for renewable hydrogen projects.
Japan
Semiconductor fab expansion for advanced node production drives specification escalation for ultra-high-purity hydrogen with sub-ppb oxygen content. METI hydrogen roadmap targets are channeling investment into import infrastructure and domestic purification capacity. Kyushu and Chubu industrial corridors are testing ammonia cracking systems for maritime fuel applications requiring novel impurity removal.
South Korea
Electronics manufacturing for memory and logic chips requires generator cooling hydrogen exceeding fuel cell purity standards by orders of magnitude. The MFDS and national hydrogen economy roadmap are shaping certification requirements for industrial gas systems. Gyeonggi-do and Chungcheong regions are adding electrolyzer capacity that demands integrated purification for grid-scale storage pilots.
Hydrogen Purifiers Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology depth. The vendor base spans multinational gas majors with integrated supply chains, diversified industrial conglomerates with cross-sector hydrogen exposure, and focused membrane or filtration specialists competing on technical performance. Three archetypes dominate: pipeline-network operators leveraging on-site gas supply contracts, cryogenic system providers serving aerospace and electronics test facilities, and porous metal membrane fabricators competing at sub-micron filtration levels. Consolidation pressure is building through strategic partnerships between electrolyzer OEMs and purification skid suppliers, while geographic expansion into India and Southeast Asia is accelerating.
Within the integrated gas supply tier, Air Products and Air Liquide exemplify archetypes built on pipeline infrastructure and long-term industrial contracts. Linde occupies a position bridging cryogenic expertise with aerospace test facility specialization. Among focused technology providers, Mott Corporation represents the porous metal membrane specialist segment competing on filtration efficiency metrics. These three anchors illustrate how competitive positioning fragments between scale-driven supply integration and technical differentiation in materials science.
| Leading Market Players |
|---|
| Mott Corporation |
| Cummins |
| Linde |
| Sinopec |
| Air Liquide |
| Air Products |
| FuelCell Energy |
| Ballard Power Systems |
| Shell |
| Others |
Supply & Pricing Matrix
Multi-hundred-ton PSA unit deployments in Germany's Rhine-Ruhr corridor generate scale economies that compress per-unit purification costs while simultaneously concentrating supplier bargaining power around Linde and Air Liquide. This capacity-utilization dynamic creates price floors that membrane system vendors must undercut through modular architecture rather than throughput competition.
Pricing Analysis
Prior-generation cryogenic distillation systems command 40-60% premiums over current-generation PSA units for equivalent throughput, while next-generation electrochemical separation modules price at mid-tier levels despite lower energy intensity. Three-tier pricing structure across premium cryogenic, standard PSA, and economy membrane tiers tracks certification grade and after-sales service bundling. Cost compression in the membrane tier is intensifying because palladium price volatility forces manufacturers to absorb metal cost swings. Fuel cell vehicle fleet operators exhibit highest price sensitivity, while semiconductor fabs prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
South Africa and Russia anchor palladium sponge and alloy production for membrane fabrication, while Germany and the United States concentrate cryogenic system manufacturing and precision vessel fabrication. Zeolite adsorbent production draws from specialized chemical processing in China and the United States, with activated carbon sourcing from Southeast Asian coconut shell processing. Single-source vulnerability in palladium supply creates project margin exposure that membrane OEMs hedge through long-term metal offtake contracts. Distribution runs through direct equipment sales for large chemical installations and rental-service models for distributed fuel cell infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as data center and semiconductor demand splinters the historically chemical-centric buyer base into purity-tiered segments with divergent procurement rhythms.
For Market Incumbents: Secure electrolyzer OEM qualification pipelines in Texas and Louisiana before PEM electrolyzer scale-up locks in purification skid partnerships. Lock in multi-year palladium supply contracts to neutralize Russian supply concentration risk. Prioritize sensor-integrated purifier development for blockchain-based hydrogen quality tracking pilots in Germany. For New Entrants and Emerging Players: ISO 14687 fast-track certification for PEM-compatible membrane modules opens California and German fuel cell logistics markets with lower incumbent saturation. Target ammonia cracking purification for Singapore and Rotterdam port pilots where established vendors lack purpose-built impurity removal systems. Pursue purity-as-a-service contracting models for Northern Virginia data center operators seeking to unbundle capital ownership from guaranteed uptime delivery. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among membrane specialists with sensor-integrated aftermarket service contracts tied to digital certification platforms. Five-to-ten year viability favors vendors with electrolyzer OEM partnerships and multi-standard certification capabilities spanning ISO 14687 and SEMI protocols. Monitor EU AI Act digital certification implementation timelines as inflection indicator for sensor-integrated purifier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer OEM Partnership | Qualification with Texas and Louisiana PEM electrolyzer manufacturers secures IRA tax credit-aligned project pipelines. |
| Palladium Supply Contracting | Long-term metal offtake agreements with South African producers neutralize price volatility exposure in membrane system margins. |
| Digital Certification Integration | Blockchain-compatible sensor development for German hydrogen quality tracking pilots opens aftermarket service contract expansion. |
| Ammonia Cracking Purification | Purpose-built impurity removal systems for Singapore and Rotterdam port pilots capture maritime fuel transition demand. |
| Purity-as-a-Service Model | Per-kilogram uptime guarantees for Northern Virginia data centers concentrate risk while generating recurring revenue streams. |
Research Methodology
A standing panel of hydrogen project developers, electrolyzer OEM procurement leads, semiconductor fab gas systems engineers, and fuel cell vehicle fleet operators provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC 10-K filings of listed gas majors, EPA hydrogen handling standard updates, EU F-Gas Regulation implementation guidance, and IEA hydrogen project databases. Bottom-up unit deployment tracking triangulated against top-down hydrogen demand projections from national roadmap documents.
Consistency checks validated volume and value outputs against IEA hydrogen demand scenarios and national electrolyzer deployment targets across the analysis window. Segmentation modeling incorporated product type, application purity tier, technology architecture, and end-user procurement pattern dimensions. CAGRs derived from logistic curve fitting to electrolyzer manufacturing capacity announcements and fuel cell vehicle fleet deployment schedules. Forecast inputs included IRA tax credit eligibility thresholds and EU Green Deal hydrogen mandate compliance timelines.
Underlying assumptions cover electrolyzer cost decline trajectories and fuel cell vehicle adoption rates, with deviation risk concentrated in palladium supply disruption and cryogenic technician training pipeline constraints. Recalibration cycles align with material shifts in national hydrogen roadmap revisions and digital certification regulatory finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Liquid Organic Hydrogen Carrier (LOHC) Market
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
On-Site Hydrogen Generator Market
Hydrogen Energy
Asia-Pacific Clean Hydrogen Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market