
 Hydrogen Ejector Market | 2026-2036
Hydrogen Ejector Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Ejector Market Insights
Fuel cell vehicle fleet expansion is realigning demand toward high-reliability hydrogen circulation components. Parker Hannifin Corporation leverages its fluid control heritage to anchor positions across refueling and fuel cell balance-of-plant applications. Robert Bosch GmbH sustains engineering intensity in precision gas handling systems for automotive OEM programs. Toyota Industries dominates captive supply chains through in-house production of hydrogen circulation equipment for its fuel cell platforms.
A hydrogen ejector is a passive fluid device that uses high-pressure hydrogen motive flow to entrain and compress lower-pressure hydrogen streams without moving mechanical parts, typically operating at pressures exceeding 350 bar in commercial refueling applications. Multi-stage ejector configurations achieve higher compression ratios for heavy-duty vehicle refueling, while compact designs address space-constrained onboard fuel cell systems where weight and envelope restrictions dictate component selection. Fuel cell systems represent the fastest-expanding application segment as stationary power and mobility deployments scale, with fixed installation types capturing the majority of early infrastructure spending.
The US Department of Energy hydrogen program coordinates with DOT and NHTSA to establish safety and performance benchmarks for high-pressure gas components, while Germany's KBA enforces type approval requirements that shape product development cycles for European suppliers. Japan's METI drives standardization through its Strategic Roadmap for Hydrogen and Fuel Cells, creating certification pathways that influence design priorities across Asian supply chains. Stakeholders must monitor evolving pressure-class requirements and interoperability standards as regional hydrogen economies mature at different speeds.
Market Dynamics
The hydrogen ejector market is being fundamentally restructured by the divergence between 350 bar and 700 bar refueling infrastructure deployment timelines, which is fragmenting equipment specifications and forcing manufacturers to maintain dual certification tracks.
Growth Catalysts
- EU Hydrogen Strategy:The framework's binding targets for hydrogen valleys and refueling corridors are creating dedicated procurement channels for certified high-pressure gas handling equipment across industrial clusters in Germany, the Netherlands, and Spain.
- Fuel cell heavy-duty trucking:Fleet operators in California and South Korea are scaling depot-based refueling systems that demand multi-stage ejector configurations capable of rapid tank fills for long-haul vehicles.
- Stationary power deployment:Data center operators and grid utilities are installing megawatt-scale fuel cell systems that require precision hydrogen circulation for load-following operations.
Market Restraints
- Stainless steel price volatility:Ejector body machining relies on 316L and specialty alloys whose cost swings compress margin predictability for precision fabricators.
- Japanese supply concentration:Critical nozzle machining capabilities and high-pressure sealing technologies remain concentrated among a narrow supplier base in Nagoya and Osaka industrial corridors.
- ASME BPVC Section VIII compliance:The certification timeline for pressure equipment creates 18-24 month product development cycles that lag behind evolving station operator specifications.
Strategic Opportunities
- Indian hydrogen hubs:The PLI scheme for electrolyzers and green hydrogen production is creating first-mover openings for ejector suppliers to establish local assembly partnerships before domestic certification requirements harden.
- Ammonia cracking integration:Ejectors optimized for hydrogen-nitrogen mixed gas streams from ammonia decomposition are opening equipment retrofit opportunities at port and industrial sites.
- ISO 19880-1 harmonization:Emerging global standards for gaseous hydrogen fueling protocols are enabling modular product architectures that reduce country-specific engineering overhead.
Industry Challenges
- High-pressure fluid dynamics simulation:The scarcity of engineers trained in compressible flow modeling for supercritical hydrogen states is extending R&D timelines and forcing reliance on expensive physical prototyping.
- Legacy natural gas infrastructure retrofit:Station operators are demanding drop-in ejector solutions compatible with existing piping envelopes, constraining design freedom for next-generation compression ratios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Ejector Market |
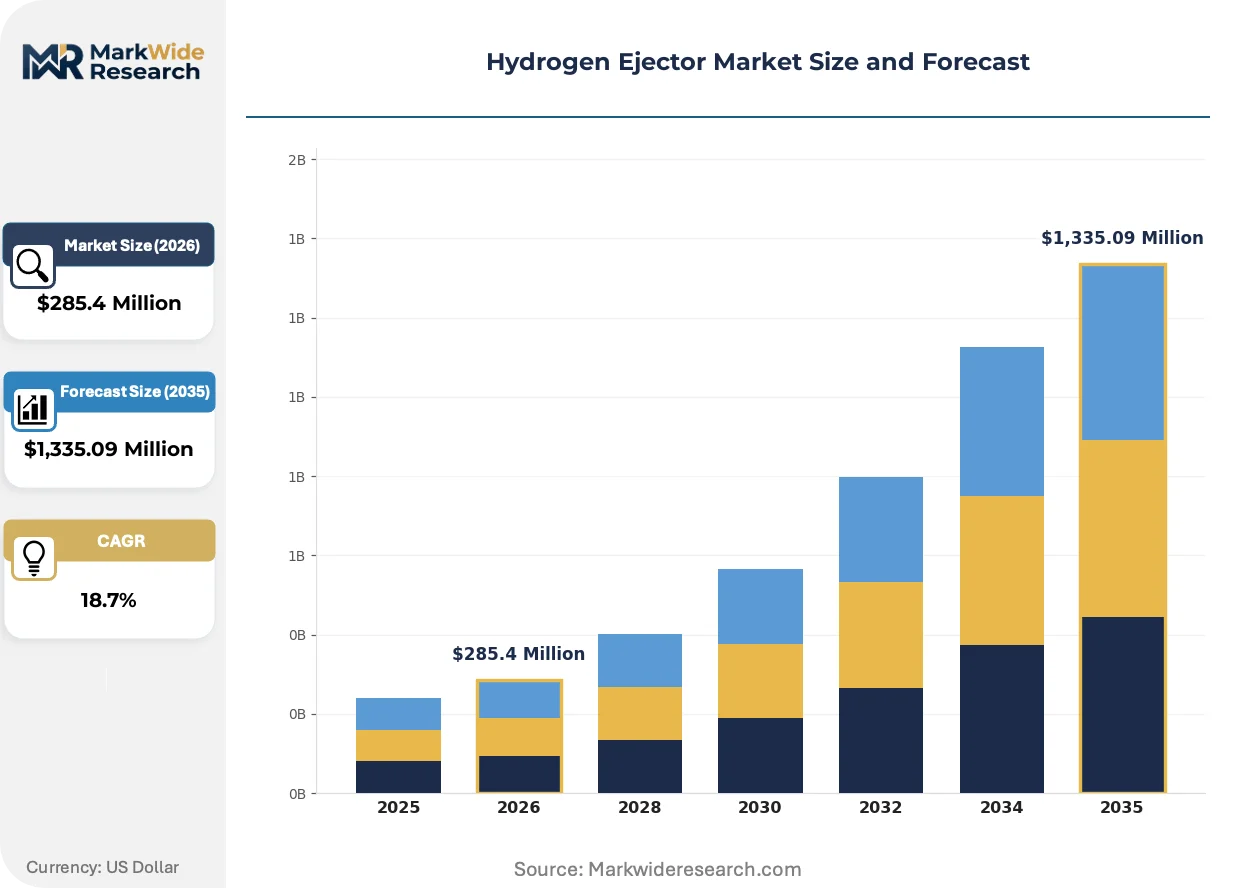
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,335.09 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Multi-Stage, Compact, Standard Application: Energy Generation, Chemical Processing, Waste Treatment, Fuel Cell Systems Installation: Fixed, Portable, Modular, Integrated End User: Industrial, Automotive, Aerospace, Research Institutions |
| Companies Covered | Parker Hannifin Corporation, Air Liquide, Busch Vacuum Solutions, Robert Bosch GmbH, Toyota Industries, Ogura, KNF Group, Air Squared, HYDAC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Ejector Market Trends and Innovations
Additive manufacturing of complex nozzle geometries is collapsing the traditional trade-off between compression efficiency and part count, enabling geometries impossible with conventional five-axis machining.
Multi-material 3D printing combining stainless steel cores with polymer thermal barriers is rewriting the thermal management constraints that previously limited ejector cycling frequency in high-throughput refueling applications. German station operators are piloting these units in 700 bar dispensing systems where rapid successive fills previously required extended cooldown periods. The technology is compressing equipment footprint requirements by eliminating external heat exchangers.
Japan's METI Strategic Roadmap for Hydrogen and Fuel Cells is mandating interoperability testing protocols that force ejector manufacturers to certify against multiple fuel cell vehicle inlet specifications simultaneously. The regulation is accelerating consolidation of test facility investments among mid-tier suppliers who cannot sustain parallel certification tracks. South Korean equipment providers are responding fastest, leveraging domestic vehicle OEM relationships to pre-validate designs against next-generation inlet standards.
Fleet operators are consolidating hydrogen procurement under long-term offtake agreements with integrated refueling service providers, displacing the previous model of station-by-station equipment purchasing. This bundling is compressing the vendor base accessible to independent ejector manufacturers and favoring suppliers with balance-of-plant integration capabilities. The shift is most visible in California's heavy-duty trucking corridors where logistics operators now contract fuel availability rather than infrastructure ownership.
Hydrogen Ejector Market Segmentation
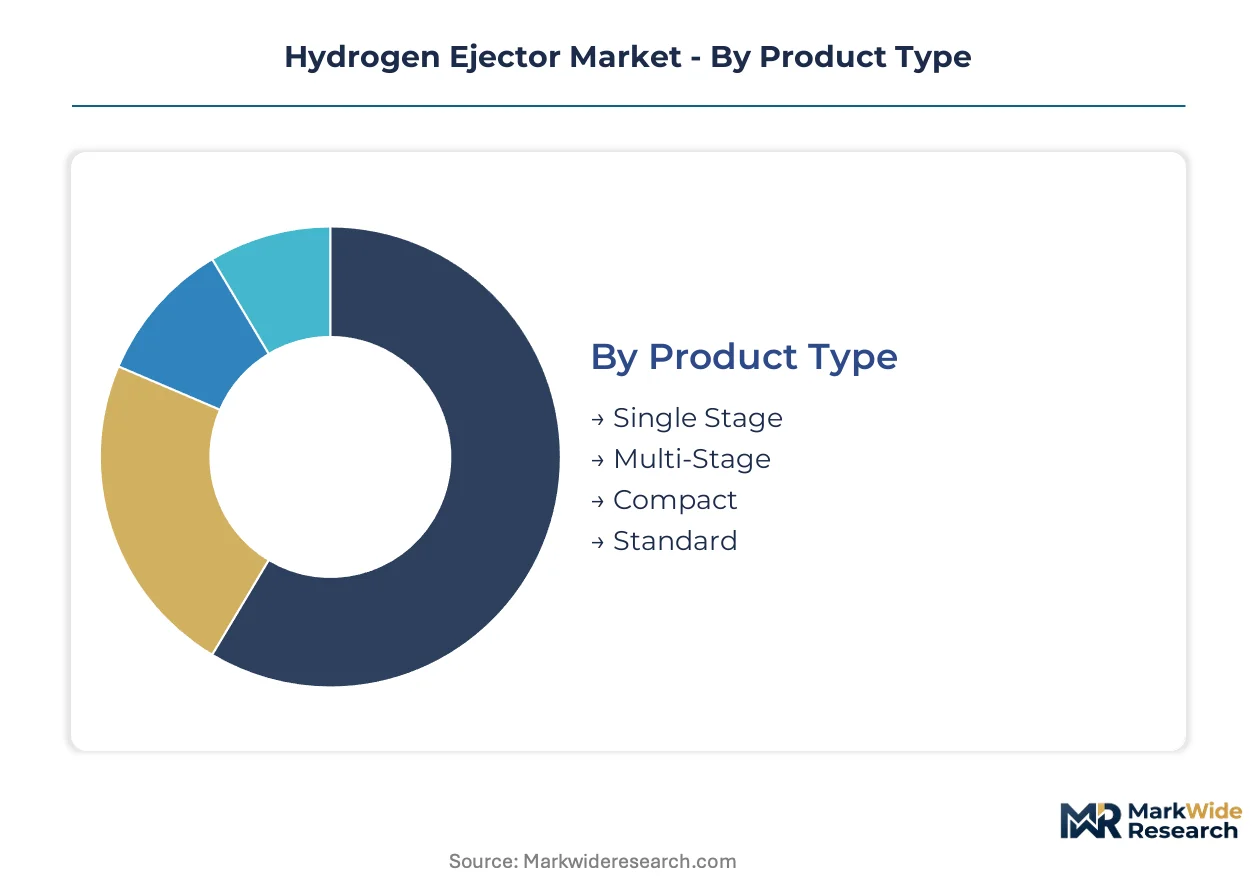
Hydrogen ejector procurement patterns diverge sharply across pressure classes, duty cycles, and integration architectures. Equipment specifications must reconcile automotive refueling speeds with industrial process tolerances, while installation constraints vary between greenfield hydrogen valleys and legacy facility retrofits.
Product Type:
Compression ratio requirements and envelope constraints dictate the fundamental ejector architecture selection across refueling and process applications.
- Single Stage:Single throat configurations achieve moderate compression ratios up to 5:1 using converging-diverging nozzle geometry machined from 316L stainless steel. Station operators in Germany's hydrogen corridors deploy these for 350 bar light-duty vehicle dispensing where fill times under five minutes satisfy fleet requirements. The design trades ultimate pressure gain against mechanical simplicity and maintenance accessibility.
- Multi-Stage:Series-coupled ejector arrays cascade motive flows to achieve compression ratios exceeding 20:1 for 700 bar heavy-duty tank fills. South Korean depot operators specify these configurations for long-haul trucking fleets where rapid successive fills demand thermal management across interstage cooling. The added complexity requires precision alignment of throat diameters and diffuser angles.
- Compact:Miniaturized envelope designs integrate thermal barriers and optimized flow paths for onboard fuel cell balance-of-plant applications.
- Standard:Conventional form factors serve stationary industrial processes with predictable duty cycles and moderate pressure differentials.
Multi-stage configurations lead on scale in refueling infrastructure; compact designs lead on momentum as automotive integration accelerates.
Application:
End-use thermal profiles and purity requirements reshape material selection and sealing strategies across deployment contexts.
- Fuel Cell Systems:Precision circulation at sub-ambient temperatures maintains stack humidity balance in proton exchange membrane architectures. Data center operators in Virginia and Singapore specify these for continuous-duty backup power where load-following response must stabilize within seconds. The application demands ultra-high purity hydrogen with particulate filtration below 0.01 micrometers.
- Energy Generation:Grid-scale fuel cell installations and hydrogen-fired turbine pilot projects require high-volume flow handling with wide turndown ratios. Utilities in Japan's Kansai region deploy these for seasonal peak shaving where hydrogen storage buffers renewable curtailment.
- Chemical Processing:Ammonia synthesis and refinery hydrotreating units utilize hydrogen recovery ejectors for pressure letdown and recycle compression.
- Waste Treatment:Biogas upgrading and wastewater hydrogen recovery applications exploit passive compression to avoid ignition risks in explosive atmospheres.
Energy generation commands the largest installed base; fuel cell systems are climbing the fastest as mobility and stationary power deployments scale.
Installation:
Capital deployment models and operational flexibility requirements determine the physical integration approach for hydrogen handling equipment.
- Fixed:Permanent skid-mounted assemblies anchor large-scale refueling stations and industrial process lines with dedicated foundation and utility connections. California's heavy-duty trucking corridors favor these for high-throughput hubs where twenty-year asset lifetimes justify civil engineering investment.
- Modular:Containerized plug-and-play units enable rapid deployment and capacity expansion without custom site engineering. Dutch port operators specify these for hydrogen import terminals where throughput requirements evolve with vessel scheduling.
- Portable:Trailer-mounted systems serve temporary construction sites and emergency backup applications with self-contained power and controls.
- Integrated:Factory-assembled packages combine ejectors with storage, cooling, and dispensing in unified enclosures for space-constrained urban installations.
Fixed installations dominate current infrastructure spending; modular formats are gaining share fastest where deployment speed determines project economics.
End User:
Procurement sophistication and technical specification authority vary dramatically across customer categories with differing in-house engineering capabilities.
- Automotive:OEM captive supply chains and tier-one system integrators drive standardization toward ISO 19880-1 protocols for vehicle refueling interoperability. Toyota's in-house production and Bosch's automotive programs concentrate specification authority with manufacturers possessing full fuel cell system expertise.
- Industrial:Petrochemical complexes and steel producers leverage existing high-pressure gas handling competencies to specify custom ejector trains for hydrogen injection and recovery loops. German industrial clusters in the Ruhr and Leuna coordinate procurement through shared engineering consortia.
- Aerospace:Aircraft fuel cell demonstrators and ground support equipment impose stringent weight and reliability requirements derived from aviation certification frameworks.
- Research Institutions:National laboratories and university test facilities purchase specialized configurations for fundamental compressible flow research and prototype validation.
Industrial buyers lead on scale through established process gas procurement channels; automotive demand is expanding most quickly as production fuel cell vehicle programs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as certification timelines and subsidy intensity diverge across jurisdictions. Suppliers are relocating final assembly to compress time-to-certification for high-pressure gas equipment.
Germany
KBA type-approval requirements and EU Hydrogen Strategy funding are concentrating precision fabrication in the Ruhr and Leuna industrial corridors. Station operators in the Rhine-Ruhr hydrogen valley deploy multi-stage ejectors for heavy-duty fleet refueling. The country's national hydrogen regulator enforces interoperability testing that shapes product development cycles for European suppliers.
United States
California's heavy-duty trucking corridors and DOE hydrogen program coordination with NHTSA are accelerating depot-based refueling deployments. The state's logistics operators now contract fuel availability rather than infrastructure ownership. Data center operators in Virginia specify precision circulation equipment for megawatt-scale fuel cell backup power.
Japan
METI's Strategic Roadmap for Hydrogen and Fuel Cells mandates interoperability protocols that force simultaneous certification against multiple vehicle inlet specifications. Nagoya and Osaka industrial corridors retain concentration in critical nozzle machining capabilities. Domestic vehicle OEM relationships enable pre-validation against next-generation inlet standards.
South Korea
Long-haul trucking fleet scaling and government hydrogen economy frameworks are driving demand for rapid successive fill capabilities. Equipment providers leverage domestic vehicle OEM relationships to accelerate design validation. The country's national industrial policy coordinates procurement through integrated refueling service providers.
India
PLI scheme incentives for electrolyzers and green hydrogen production are creating first-mover openings before domestic certification requirements harden. Port operators in Gujarat and Maharashtra pilot containerized modular units for hydrogen import terminals. The country's Bureau of Indian Standards is developing pressure equipment codes that will reshape supplier qualification timelines.
Hydrogen Ejector Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to compress certification timelines and secure captive demand channels. The vendor base fragments across precision fabricators with high-pressure gas heritage and automotive-tier system integrators with fuel cell platform relationships. Three archetypes define positioning: diversified fluid control conglomerates, automotive-captive suppliers, and specialized vacuum/compression specialists. Geographic expansion and technology licensing represent the dominant competitive moves as regional hydrogen economies mature at different speeds.
Within the diversified industrial tier, Parker Hannifin Corporation and Robert Bosch GmbH exemplify archetypes anchored in fluid control heritage and precision automotive systems respectively. Toyota Industries occupies a position representing captive supply chain integration for fuel cell platform production. Air Liquide sits within the industrial gas specialist tier, leveraging existing high-pressure handling competencies across refueling infrastructure deployments.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Air Liquide |
| Busch Vacuum Solutions |
| Robert Bosch GmbH |
| Toyota Industries |
| Ogura |
| KNF Group |
| Air Squared |
| HYDAC |
| Others |
Pricing and Supply Chain Analysis
Precision nozzle machining specialists in Nagoya and Osaka industrial corridors anchor labor-cost differentials that widen pricing-tier spreads between certified automotive-grade ejectors and standard industrial configurations. German fabricators in the Ruhr corridor absorb higher wage structures but offset through automation density in 316L stainless steel body machining.
Pricing Analysis
Distributor margins for hydrogen ejectors typically absorb 12-18 points before reaching station operators, while direct-to-OEM automotive programs command volume discounts that compress supplier net realization. Three-tier pricing structure across premium, standard, and economy levels stratifies by ASME BPVC Section VIII certification grade and motive flow capacity. Pricing pressure stems from stainless steel alloy cost volatility and extended 18-24 month certification timelines that delay revenue recognition. Fleet operators in California's heavy-duty trucking corridors exhibit highest price sensitivity due to consolidated procurement under long-term offtake agreements, while data center operators in Virginia prioritize reliability premiums over unit economics.
Supply Chain Analysis
High-pressure sealing technology and precision nozzle machining rest on concentrated capabilities in Japan's Nagoya-Osaka industrial belt, with secondary precision fabrication clusters in Germany's Ruhr and Leuna corridors. Critical inputs include 316L stainless steel bar stock, specialty elastomeric seals rated for supercritical hydrogen exposure, and five-axis CNC machining centers with sub-micron positioning accuracy. Single-source vulnerability in Japanese nozzle machining creates supply chain risk given METI-mandated interoperability testing protocols that accelerate certification demands. Distribution runs through industrial gas specialists and automotive Tier 1 system integrators rather than open merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
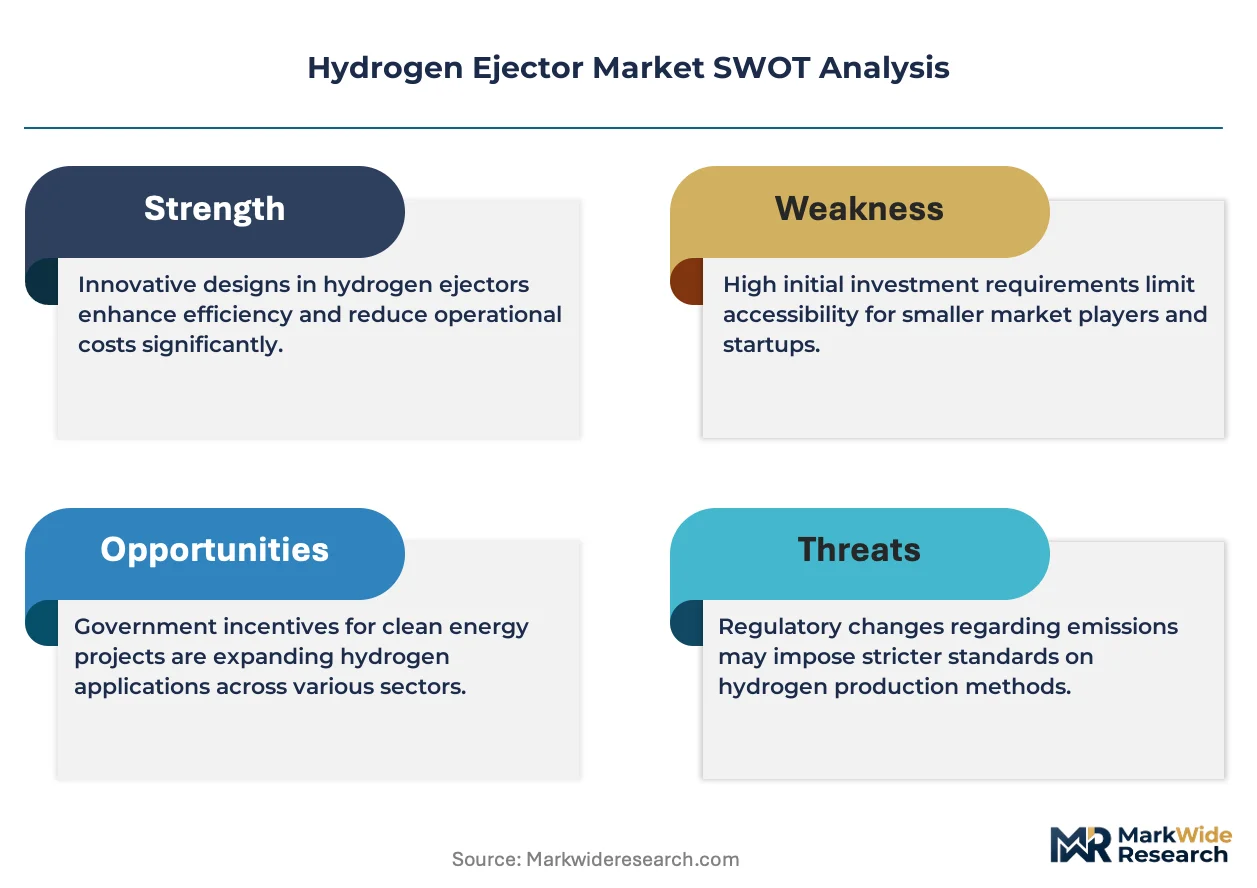
Margin expansion in hydrogen ejectors hinges on additive manufacturing adoption collapsing part-count economics and modular product architectures reducing country-specific engineering overhead across certification regimes.
For Market Incumbents: Deepen captive supply relationships with German hydrogen valley operators to secure dedicated procurement channels before KBA type-approval requirements harden. Accelerate in-house production of thermal barrier components to offset margin compression from stainless steel price volatility. Additive manufacturing investments in complex nozzle geometries represent the critical R&D lever for sustaining premium-tier positioning against emerging vacuum technology specialists. For New Entrants and Emerging Players: Capture first-mover positioning in India's PLI scheme corridors before BIS pressure equipment codes reshape supplier qualification timelines. Gujarat and Maharashtra port operators piloting containerized modular units present the most penetrable white-space target. Partner with electrolyzer OEMs for greenfield hydrogen hub deployments rather than competing for established refueling infrastructure retrofit slots. For Investors and Strategic Acquirers: Industrial gas specialists with existing high-pressure handling competencies are the most active acquirer in this space, seeking fuel cell balance-of-plant integration capabilities. Acquisition targets should exhibit precision fabrication heritage in 316L stainless steel and established KBA or METI certification tracks. ISO 19880-1 harmonization progress serves as the critical inflection indicator for modular product architecture viability and geographic expansion optionality.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Scale-Up | Multi-material 3D printing enables geometries impossible with five-axis machining, compressing thermal management footprints. |
| Backward Integration into Sealing Technology | In-house production of hydrogen-rated elastomers insulates margin from Japanese supply concentration risks. |
| Joint Venture with Port Operators | Dutch and Indian containerized modular deployments create anchor demand for rapid deployment capabilities. |
| Certification Pre-Validation Partnership | South Korean OEM relationships accelerate METI interoperability testing against next-generation vehicle inlet standards. |
| Long-Term Supply Agreement with Fleet Operators | California heavy-duty trucking offtake contracts displace station-by-station purchasing, securing volume visibility. |
Research Methodology
Bottom-up fuel cell system deployment modeling reconciled against top-down precision fabrication capacity tracking forms the analytical core of this study. Primary interviews with station operators in Germany's hydrogen valleys, automotive Tier 1 procurement teams, and industrial gas distribution specialists were validated against secondary sources including KBA type-approval filings, METI Strategic Roadmap implementation reports, and DOE hydrogen program technical targets. Trade data from EU hydrogen corridor deployments and California HVIP incentive disclosures provided cross-reference points for installation volume estimates.
Input-output matrices map hydrogen ejector demand to fuel cell vehicle fleet expansion, stationary power deployment, and refueling infrastructure buildout across the projection horizon. Segmentation dimensions include pressure class architecture, installation format, and end-user procurement sophistication. CAGRs derive from equipment replacement cycles, certification timeline compression, and regional subsidy intensity variations. Compressible flow simulation capability scarcity and ASME BPVC Section VIII compliance timelines represent industry-specific forecast inputs.
Stainless steel alloy price volatility, METI interoperability protocol revisions, and KBA type-approval timeline extensions are the dominant revision risks to installed base and revenue forecasts. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Solar Hydrogen Panel Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
Hydrogen Purification Market
Hydrogen Energy
Hydrogen for Mobility Market
Hydrogen Energy
PEM Water Electrolytic Hydrogen Production System Market
Hydrogen Energy
On-Site Hydrogen Generator Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
Europe Clean Hydrogen Market
Hydrogen Energy
India Hydrogen Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market