
 North America Cataract Surgery Devices Market | 2026-2036
North America Cataract Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cataract Surgery Devices Market Insights
Monofocal acrylic polymers is rebalancing cost structures across intraocular lens portfolios as silicone alternatives face procurement pressure. Alcon Inc. leverages vertical integration from raw polymer synthesis to finished lens packaging, sustaining margin control through captive supply chains. Johnson & Johnson Vision anchors its position in femtosecond laser-assisted platforms, while Carl Zeiss Meditec AG competes on optical coherence tomography-integrated surgical microscopes.
North America cataract surgery devices comprise precision ophthalmic instruments designed to extract clouded crystalline lenses and implant artificial replacements, with intraocular lenses typically measuring 6 mm unfolded diameter and 13 mm haptic span for capsular bag fixation. These systems restore refractive clarity in patients with age-related nuclear sclerosis or cortical opacification. Intraocular lenses generate the dominant revenue pool due to recurring implant consumption per procedure, while laser-assisted surgery technology captures the fastest expansion as femtosecond platforms displace manual capsulorhexis in premium service tiers. Phacoemulsification devices remain the mature workhorse segment, with equipment replacement cycles extending as ultrasonic handpiece reliability improves.
FDA 510(k) clearance pathways govern phacoemulsification system and intraocular lens introductions, while CMS national coverage determinations directly shape reimbursement-accessible device adoption across Medicare populations. The FDA's ongoing scrutiny of toric and multifocal intraocular lens post-market performance data elevates clinical evidence requirements for premium segment entrants. Stakeholders must monitor state-level certificate-of-need regulations affecting ambulatory surgery center expansion, as these facility approvals determine regional device procurement velocity.
Market Dynamics
Femtosecond laser platforms are compressing procedure times while elevating capital requirements for ambulatory surgical centers across the United States, forcing facility operators to restructure equipment financing around utilization guarantees rather than outright purchase models.
Growth Catalysts
- CMS Site-of-Service Reimbursement:Medicare payment differentials favoring ambulatory surgical centers over hospital outpatient departments accelerate capital deployment into freestanding facilities across Florida, Texas, and Arizona.
- Acrylic Polymer Lens Chemistry:Hydrophobic acrylic formulations with square-edge design reduce posterior capsular opacification rates, extending premium intraocular lens replacement cycles and patient satisfaction metrics.
- Southeastern Demographic Clustering:Retiree migration patterns concentrate procedure demand in metropolitan Atlanta, Charlotte, and Nashville, creating predictable volume pools for equipment vendors.
Market Restraints
- Femtosecond Platform Capital Intensity:Single-platform acquisition costs exceeding $500,000 per unit restrict deployment to high-volume centers, excluding smaller ophthalmology practices from laser-assisted workflows.
- Silicone Lens Material Displacement:Hydrophobic acrylic alternatives capture procurement preference, stranding silicone intraocular lens inventory and compressing margins for manufacturers without acrylic synthesis capability.
- FDA Post-Market Surveillance:Toric and multifocal lens performance tracking requirements extend regulatory review timelines for premium segment entrants, delaying commercialization windows.
Strategic Opportunities
- Optical Coherence Tomography Integration:Real-time biometric measurement during femtosecond laser docking enables intraoperative lens power refinement, reducing refractive surprise rates in premium service tiers.
- Certificate-of-Need Deregulation:State-level CON relaxation in North Carolina and Tennessee permits ambulatory surgery center expansion without capacity demonstration, accelerating regional device procurement velocity.
- Phacoemulsification Handpiece Refurbishment:Extended ultrasonic handpiece reliability creates aftermarket service revenue pools for third-party reprocessors serving cost-sensitive standard-tier facilities.
Industry Challenges
- Femtosecond Laser Technician Scarcity:Specialized training requirements for laser platform operation outpace certified technician supply in secondary metropolitan markets, constraining utilization rates.
- Intraoperative Aberrometry Workflow Integration:Real-time refractive measurement systems demand OR layout reconfiguration and staff retraining, delaying technology adoption despite clinical benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cataract Surgery Devices Market |
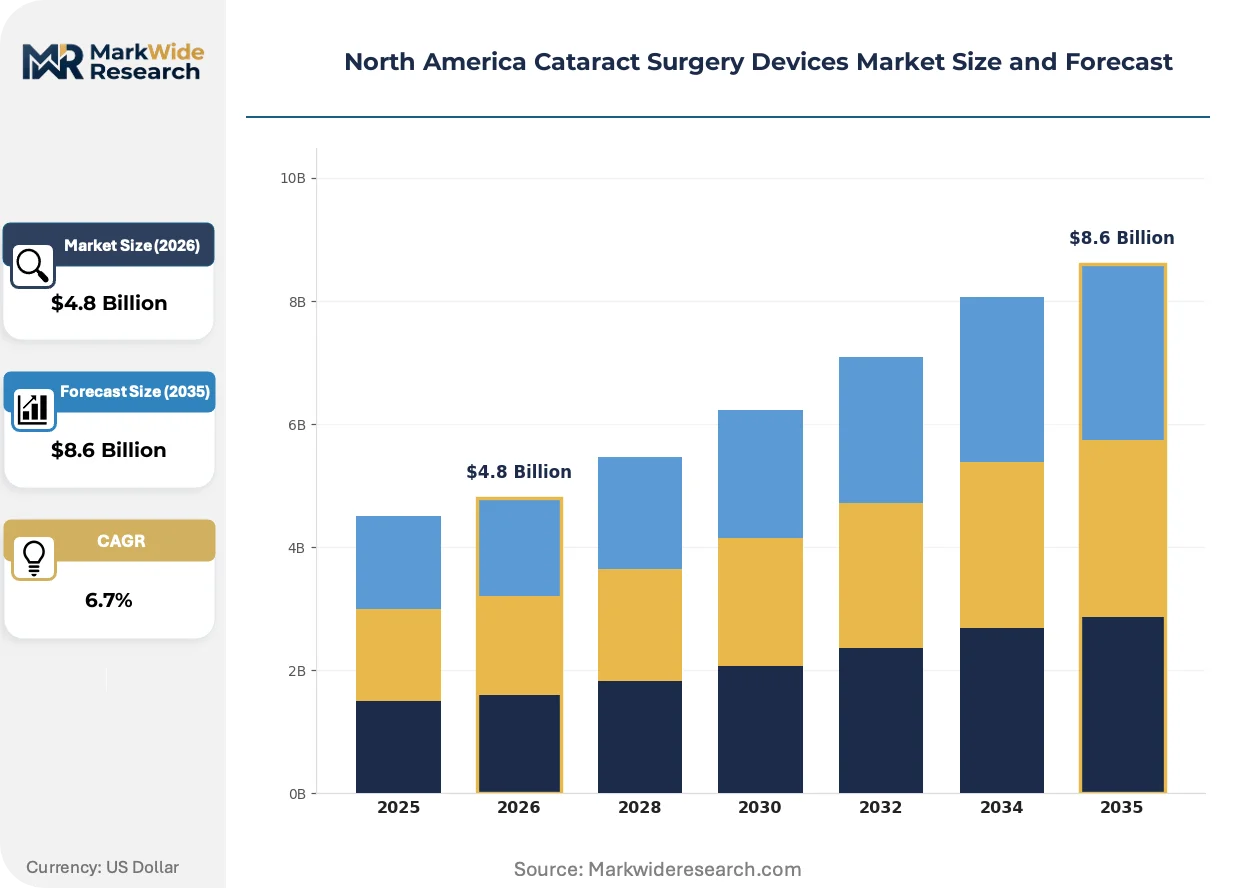
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraocular Lenses, Phacoemulsification Devices, Operating Microscopes, Capsulotomy Devices End User: Hospitals, Ophthalmology Clinics, Surgical Centers, Outpatient Facilities Technology: Manual Surgery, Laser-Assisted Surgery, Phacoemulsification, Traditional Surgery Application: Anterior Segment Surgery, Posterior Segment Surgery, Secondary Cataract Treatment, Pediatric Cataract |
| Companies Covered | Alcon Inc., Johnson & Johnson Vision, Carl Zeiss Meditec AG, Bausch & Lomb Inc., NIDEK Co. Ltd., Abbott Laboratories, ZEISS Group, Ziemer Ophthalmic Systems AG, Topcon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cataract Surgery Devices Market Trends and Innovations
Active surgical workflow redesign is redistributing procedural steps across facility types and technology platforms, compressing the boundary between diagnostic imaging and operative intervention.
Dispersed femtosecond laser platforms is decentralizing capsulorhexis execution from centralized hospital campuses to ambulatory surgical centers. High-volume ophthalmology groups in Texas and Florida deploy mobile laser units across multiple facilities. This geographic distribution of capital equipment is compressing patient travel burdens while elevating per-procedure equipment utilization tracking requirements.
FDA 510(k) clearance pathway modifications for toric intraocular lenses impose enhanced post-market performance documentation obligations on manufacturers. The agency's evolving evidentiary standards extend premarket submission preparation timelines. Premium lens developers respond by front-loading clinical trial enrollment to accelerate data accumulation for subsequent submissions.
Consolidated purchasing arrangements among multi-site ophthalmology platforms concentrate procurement authority at regional management entities. Independent ambulatory surgical centers surrender vendor selection autonomy to group purchasing organizations in exchange for standardized pricing tiers. This buyer-side aggregation is most pronounced in the southeastern United States, where retiree population density supports multi-facility ophthalmology network economics.
North America Cataract Surgery Devices Market Segmentation
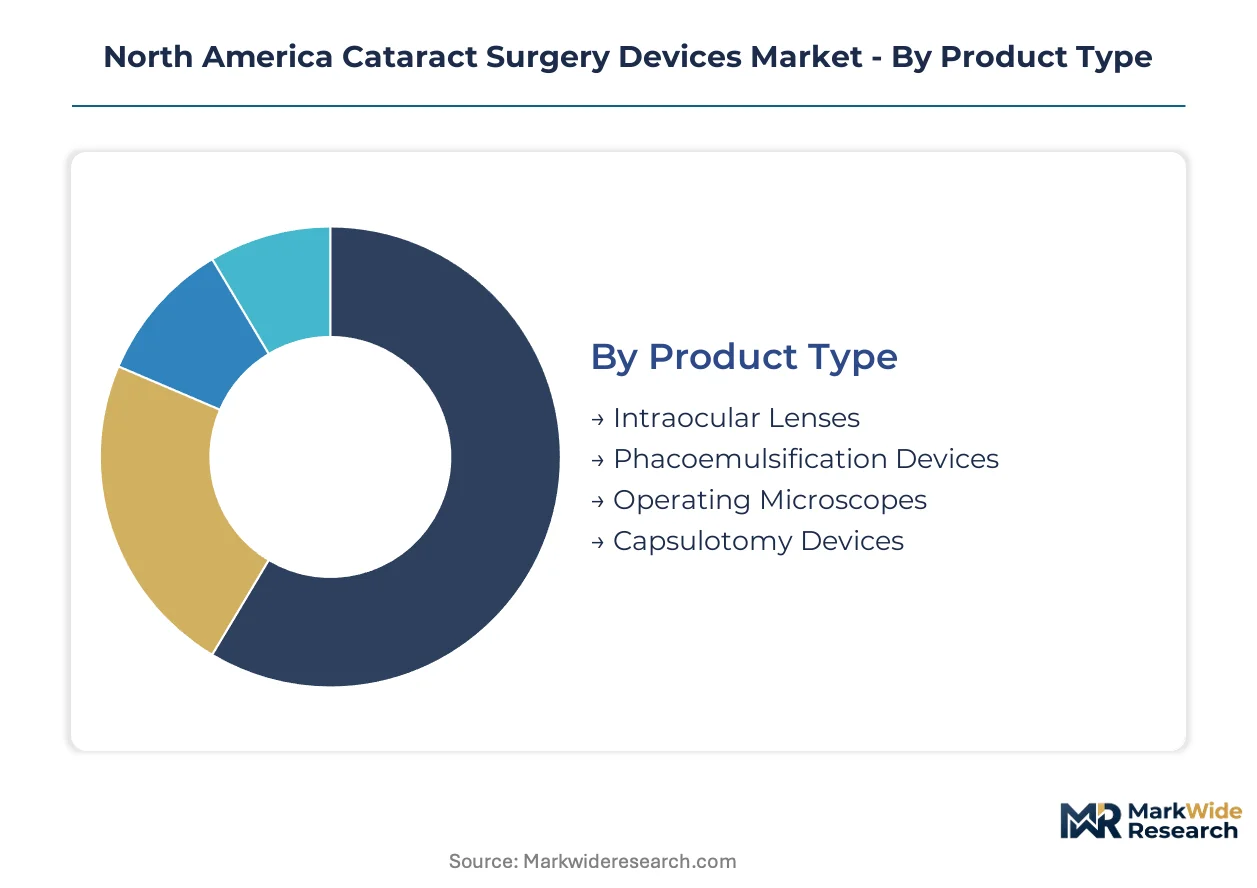
Segmentation reveals how cataract surgery devices align with distinct clinical workflows and facility economics across the United States, Canada, and Mexico. Each category exposes different pressure points for procurement decisions, from capital-intensive laser platforms to consumable lens inventories.
Product Type:
Customization intensity varies sharply across this category, with implantable consumables at one pole and durable capital equipment at the other.
- Intraocular Lenses:Hydrophobic acrylic formulations with square-edge design dominate procurement volumes. Demand clusters in ambulatory surgical centers across Florida and Texas, where retiree density supports high-throughput implant consumption and group purchasing organization consolidation.
- Phacoemulsification Devices:Ultrasonic handpiece systems with peristaltic or venturi fluidics represent the mature procedural backbone. Equipment replacement cycles extend as reliability improves, compressing new unit sales velocity in saturated southeastern metropolitan markets.
- Operating Microscopes:Optical coherence tomography-integrated platforms enable real-time surgical guidance.
- Capsulotomy Devices:Femtosecond laser systems and manual alternatives serve tiered service levels.
Leading the category by volume: Intraocular Lenses. Expanding most quickly: Capsulotomy Devices.
End User:
Site-of-service economics reshape procurement authority across facility types, with reimbursement differentials driving capital migration.
- Hospitals:Academic medical centers and community hospitals maintain emergency backup capabilities and complex case referral networks. Capital budgets concentrate in ophthalmology departments with residency training obligations, sustaining premium equipment acquisition despite higher per-procedure overhead.
- Surgical Centers:Freestanding ambulatory facilities capture Medicare reimbursement advantages under CMS site-of-service policies. Certificate-of-need deregulation in North Carolina and Tennessee accelerates greenfield construction, creating predictable device procurement pipelines.
- Ophthalmology Clinics:Single-specialty and multi-site group practices balance diagnostic and surgical workflows.
- Outpatient Facilities:Hospital outpatient departments face reimbursement compression relative to independent centers.
Procurement volume concentrates in Surgical Centers. Fastest facility expansion occurs in Ophthalmology Clinics.
Technology:
Technology selection stratifies across cost tiers, from premium laser-assisted workflows to standard manual approaches.
- Laser-Assisted Surgery:Femtosecond platforms automate capsulorhexis, lens fragmentation, and arcuate incisions. Capital intensity exceeding $500,000 per unit restricts deployment to high-volume southeastern centers with utilization guarantee financing.
- Phacoemulsification:Ultrasonic emulsification with coaxial or bimanual microincision techniques remains the universal standard. Equipment reliability improvements extend replacement cycles, shifting vendor revenue toward disposable tubing and handpiece refurbishment services.
- Manual Surgery:Conventional extracapsular and intracapsular techniques persist in resource-constrained settings.
- Traditional Surgery:Large-incision approaches retain niche application for dense cataracts.
Phacoemulsification anchors procedure volume. Laser-Assisted Surgery claims the steepest expansion trajectory.
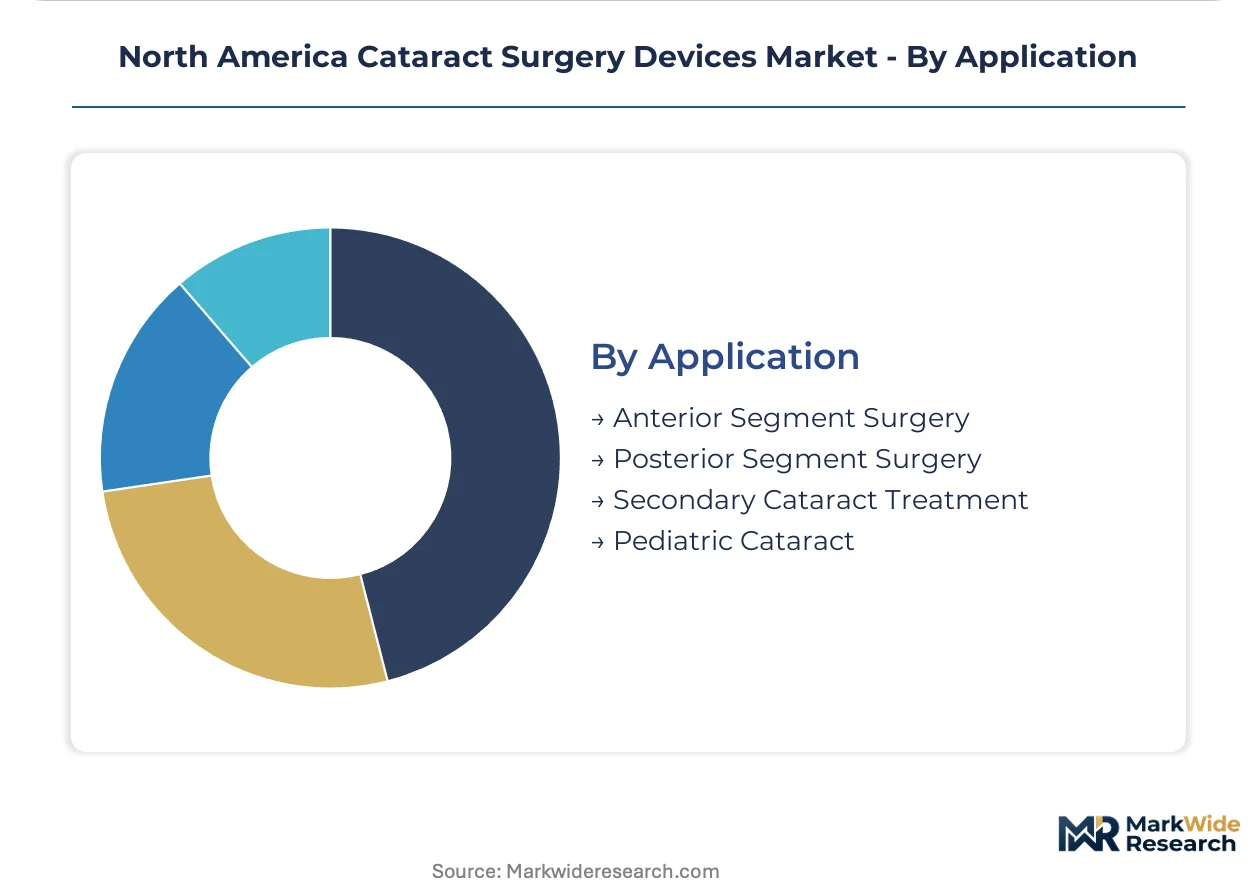
Application:
Application segmentation tracks anatomical complexity and patient population specialization, with reimbursement coding implications for each.
- Anterior Segment Surgery:Standard phacoemulsification with intraocular lens implantation constitutes the overwhelming procedure majority. Volume concentrates in metropolitan Atlanta, Charlotte, and Nashville, where aging demographics and expanding clinic networks create dense referral pools.
- Secondary Cataract Treatment:Nd:YAG laser capsulotomy addresses posterior capsular opacification following primary surgery. Procedure frequency rises with hydrophilic acrylic lens legacy implantations, creating follow-on revenue streams for outpatient laser facilities.
- Posterior Segment Surgery:Combined vitrectomy-cataract procedures serve diabetic retinopathy and macular pathology patients.
- Pediatric Cataract:Congenital and developmental lens extraction demands specialized instrumentation and anesthesia protocols.
Anterior Segment Surgery dominates procedure counts. Secondary Cataract Treatment generates the fastest-growing follow-on service demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procedure volumes concentrate in southeastern metropolitan corridors where retiree migration patterns intersect with ambulatory surgical center expansion. Medicare reimbursement differentials between hospital outpatient departments and freestanding centers reshape capital deployment geography across the continent.
United States
Florida, Texas, and Arizona drive procurement velocity as CMS site-of-service policies channel procedures toward lower-cost settings. FDA 510(k) clearance pathways govern phacoemulsification system introductions while CMS national coverage determinations shape device adoption across Medicare populations. Metropolitan Atlanta, Charlotte, and Nashville form dense procedure clusters where aging demographics and expanding ophthalmology clinic networks create predictable volume pools.
Southeastern Region
Retiree migration from the Northeast and Midwest concentrates demand in coastal Florida and inland Georgia markets. State-level certificate-of-need deregulation in North Carolina and Tennessee accelerates greenfield ambulatory surgery center construction. High-volume ophthalmology groups deploy mobile femtosecond laser units across multiple facilities, compressing patient travel burdens while elevating equipment utilization tracking requirements.
Canada
Provincial health authority procurement frameworks concentrate purchasing decisions at regional management entities. Health Canada medical device licensing requirements align with FDA predicate device pathways for intraocular lens approvals. Ontario and Quebec sustain the dominant procedure volumes as population aging accelerates cataract extraction demand in Toronto and Montreal metropolitan areas.
Mexico
Private healthcare networks in Mexico City and Monterrey drive premium device adoption for medical tourism and domestic affluent populations. COFEPRIS regulatory pathways for ophthalmic device registration create parallel approval tracks distinct from US FDA processes. Northern border states access cross-border supply chains for consumable lens inventories serving binational patient flows.
North America Cataract Surgery Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integration determining margin control in intraocular lens chemistry while capital equipment vendors compete on financing flexibility. The vendor base concentrates around ophthalmic-dedicated portfolios rather than diversified medical device conglomerates. Three archetypes dominate: polymer synthesis-integrated lens manufacturers, femtosecond laser platform developers, and phacoemulsification system incumbents with established installed bases. Competitive moves center on captive supply chain construction and utilization-guarantee equipment financing structures.
Among Swiss and German precision optics groups, Carl Zeiss Meditec AG and Ziemer Ophthalmic Systems AG occupy positions emphasizing optical coherence tomography integration and laser platform refinement. Alcon Inc. anchors the polymer-integrated archetype through upstream control over hydrophobic acrylic formulations. Johnson & Johnson Vision sits within the femtosecond-assisted surgery tier, representing capital-intensive workflow automation strategies.
| Leading Market Players |
|---|
| Alcon Inc. |
| Johnson & Johnson Vision |
| Carl Zeiss Meditec AG |
| Bausch & Lomb Inc. |
| NIDEK Co. Ltd. |
| Abbott Laboratories |
| ZEISS Group |
| Ziemer Ophthalmic Systems AG |
| Topcon Corporation |
| Others |
Pricing and Supply Chain Analysis
Certified femtosecond laser technicians concentrated in Texas and Florida metropolitan corridors create labor-cost differentials that widen pricing-tier spreads between premium laser-assisted procedures and standard phacoemulsification workflows. CMS reimbursement differentials between ambulatory surgical centers and hospital outpatient departments amplify these spreads as facilities pass through equipment financing burdens.
Pricing Analysis
High-volume intraocular lens consumption generates thin margins offset by premium femtosecond platform fees. Three-tier pricing structure across premium, standard, and economy levels separates laser-assisted workflows with OCT integration from conventional phacoemulsification and manual techniques. Price differentiation rests on FDA 510(k) clearance tier and GPO contract scale. Cost compression in standard-tier consumables is intensifying because acrylic polymer commoditization erodes brand premiums. Independent ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with residency obligations show lowest.
Supply Chain Analysis
Single-source vulnerability sits with hydrophobic acrylic polymer synthesis concentrated among vertically integrated manufacturers in the United States and Switzerland. Raw material dependencies include medical-grade acrylic monomers, precision optical glass for microscope objectives, and rare-earth elements for laser resonators. Supply chain risk centers on FDA post-market surveillance extending regulatory review timelines for premium lens entrants. Distribution runs through group purchasing organizations consolidating procurement authority across southeastern multi-site ophthalmology networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 510(k) clearance pathways and CMS national coverage determinations create barrier-to-entry moats favoring manufacturers with established regulatory affairs infrastructure and clinical trial enrollment capacity.
For Market Incumbents: Anticipate silicone lens inventory stranding by accelerating hydrophobic acrylic formulation transitions and captive polymer synthesis investments. Defend against femtosecond platform financing disruption by restructuring equipment leases around utilization guarantees rather than outright purchase models. Prioritize optical coherence tomography integration patents as competitive differentiation levers.
For New Entrants and Emerging Players: Enter via phacoemulsification handpiece refurbishment services serving cost-sensitive standard-tier facilities in certificate-of-need deregulated states. Target aftermarket consumables for legacy ultrasonic systems in North Carolina and Tennessee ambulatory surgery center expansions. Pursue GPO contract participation as primary go-to-market channel.
For Investors and Strategic Acquirers: Re-rating potential sits with ophthalmic-dedicated polymer synthesis specialists given CMS site-of-service reimbursement acceleration. Long-term viability favors manufacturers with backward integration into hydrophobic acrylic chemistry and established FDA predicate device portfolios. Watch femtosecond laser technician certification program expansion as inflection indicator for platform utilization rates.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Front-loaded clinical trial enrollment compresses premarket timelines for toric and multifocal lens entrants. |
| Certificate-of-Need Deregulation Response | Greenfield ambulatory surgery center construction in North Carolina and Tennessee creates predictable device procurement pipelines. |
| Optical Coherence Tomography Integration | Real-time biometric measurement during femtosecond docking reduces refractive surprise rates in premium tiers. |
| Group Purchasing Organization Consolidation | Multi-site ophthalmology networks in Florida and Texas surrender vendor autonomy for standardized pricing tiers. |
| Femtosecond Platform Financing Restructuring | Utilization guarantee models replace outright purchase for capital-intensive laser deployment in high-volume centers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cataract surgeons, ambulatory surgical center administrators, biomedical engineers, and GPO contracts managers combined with FDA 510(k) databases, CMS Medicare claims data, and hospital procurement records. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment tracking.
Data-stream reconciliation across product type, end user, technology, and application dimensions shaped the analytical framework. Segmentation modeling incorporated intraocular lens material chemistry, facility reimbursement tier, laser-assisted versus manual workflow, and anterior versus posterior segment application. CAGRs derived from equipment replacement cycle analysis and consumable consumption rates per procedure. Forecast inputs included retiree migration pattern projections and state-level certificate-of-need policy trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA post-market surveillance intensification or CMS reimbursement tier restructuring. Forecasts reflect documented assumptions regarding acrylic polymer substitution velocity and femtosecond platform adoption ceilings. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
Automated CPR Devices Market
Medical Devices
Artificial Disc Market
Medical Devices
Intrauterine Insemination Devices Market
Medical Devices
South Africa Respiratory Devices Market
Medical Devices
India Medical Devices Market
Medical Devices
Surgical Monitors Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Brachytherapy Market
Medical Devices
US Surgical Microscopes Market
Medical Devices
X-Ray Stretchers Market
Medical Devices
Digital Intraoral Camera Market
Medical Devices
Catheter Coatings Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
South America C-Arms Market
Medical Devices
Australia Respiratory Devices Market