
 Middle East and Africa Single-Use Medical Device Reprocessing Market | 2026-2036
Middle East and Africa Single-Use Medical Device Reprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Single-Use Medical Device Reprocessing Market Foresight
Subscription-based sterilization validation programs is pivoting how reprocessing vendors monetize relationships with hospitals. Medline Industries leverages its distribution infrastructure to bundle reprocessing contracts with consumable supply agreements across Gulf Cooperation Council states. Stryker anchors its regional position through direct service teams that manage device collection, cleaning, and quality documentation for cath labs. Steris competes by extending its sterilization-as-a-service model to outpatient surgical networks in Egypt and Kenya.
Single-use medical device reprocessing encompasses the collection, cleaning, functional testing, sterilization, and repackaging of devices originally manufactured for one patient use, with reprocessed catheters requiring validated endotoxin levels below 0.5 EU/ml and biological indicator kill confirmation. Catheters dominate device-type revenue due to high procedural volumes in cardiology and urology applications across the region. Reprocessing services capture the largest service-type share as hospitals outsource validation documentation and sterility assurance rather than maintaining in-house bioburden laboratories. Gastroenterology application demand is accelerating fastest, driven by expanding endoscopy screening programs in Saudi Arabia and the UAE.
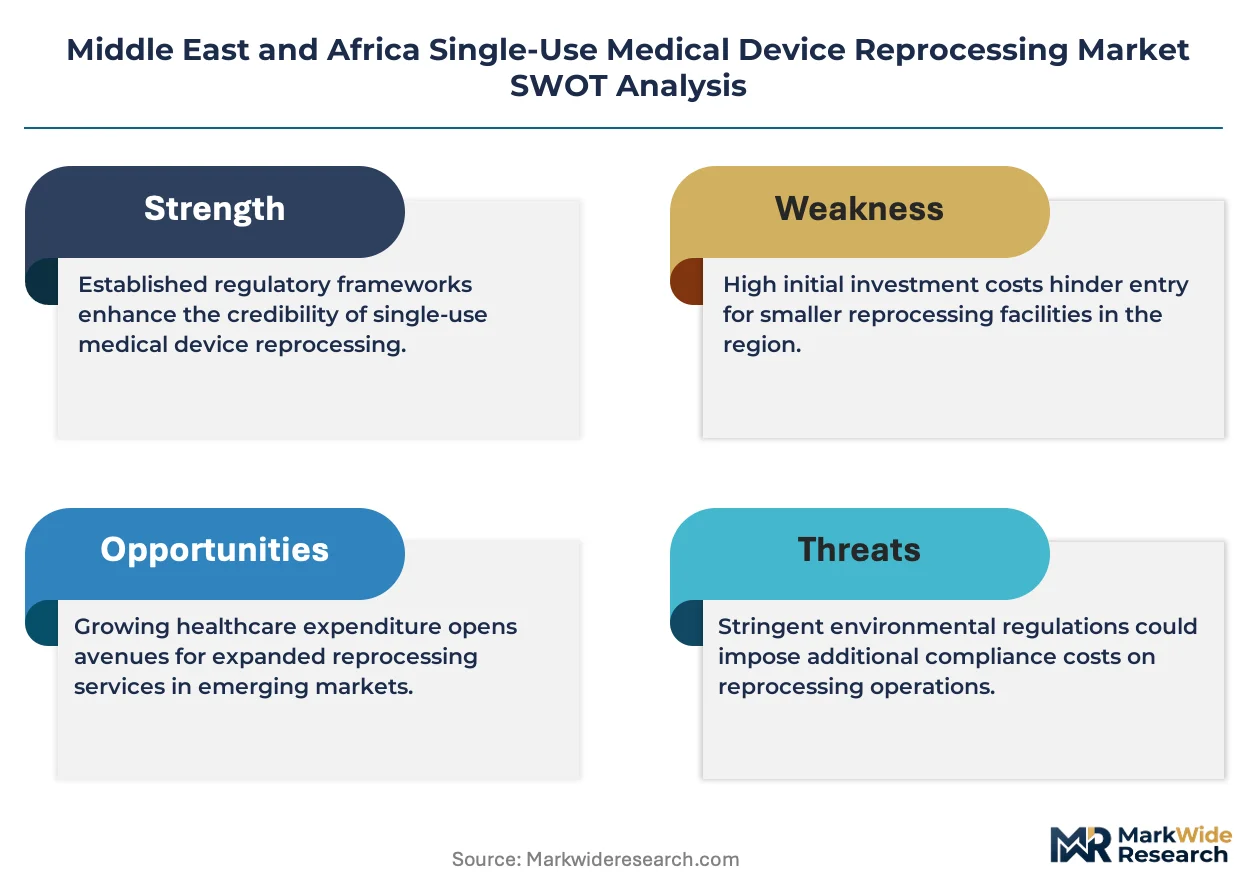
South Africa's SAHPRA, Saudi Arabia's SFDA, and the UAE's MOHAP each enforce distinct sterility assurance and traceability standards that determine which reprocessors gain hospital network access. SAHPRA's requirement for batch-level sterilization records creates compliance barriers for uncertified third-party operators, concentrating procurement among validated service providers. Stakeholders must monitor how SFDA's forthcoming reprocessing guidelines for class II devices reshape vendor qualification criteria and contract structures across the Gulf.
Market Dynamics
SAHPRA's batch-level sterilization record mandates are compressing vendor qualification timelines and forcing hospital procurement departments to consolidate reprocessing contracts among validated third-party operators.
Growth Catalysts
- SFDA Class II Guidelines:Saudi Arabia's forthcoming reprocessing framework for moderate-risk devices is accelerating hospital readiness assessments and pre-qualifying vendor partnerships ahead of enforcement.
- Endoscopy Screening Expansion:Saudi Arabia and UAE government screening programs for colorectal and gastric cancers are multiplying procedural volumes and device turnover rates in tertiary gastroenterology units.
- Consumable Supply Bundling:Integrated distribution contracts linking reprocessing services to catheter and guidewire procurement are reducing administrative overhead for cath lab managers across Gulf Cooperation Council states.
Market Restraints
- Ethylene Oxide Supply Volatility:Sterilant gas procurement disruptions and price spikes are compressing margins for reprocessors dependent on EO chamber sterilization in Egypt and Kenya.
- Traceability Infrastructure Gaps:Inadequate barcode and RFID systems in South African public hospitals are blocking SAHPRA-compliant batch documentation and limiting contract eligibility.
- Single-Use Device Innovation:Original manufacturers embedding sensors and electronics into cardiac catheters are rendering reprocessing technically unviable and shortening device lifecycles.
Strategic Opportunities
- Kenya Outpatient Surgical Networks:Private clinic chains in Nairobi and Mombasa lack in-house sterilization capacity and represent untapped demand for outsourced validation services.
- Low-Temperature Hydrogen Peroxide Convergence:Combining vapor-phase sterilization with automated cleaning validation is opening reprocessing to heat-sensitive endoscope channels previously excluded from reuse programs.
- MOHAP Quality Certification Incentives:UAE's preferential procurement scoring for ISO 13485-certified reprocessors is creating first-mover advantages for facilities achieving dual SAHPRA-MOHAP accreditation.
Industry Challenges
- Bioburden Laboratory Talent Scarcity:Certified microbiologists capable of endotoxin testing and biological indicator validation are concentrated in Johannesburg and Dubai, constraining regional expansion.
- Legacy Device Tracking Systems:Hospital information systems lacking unique device identifier integration are forcing manual reconciliation of reprocessed unit histories against patient records.
- Capex Intensity for Validated Facilities:ISO 14644 cleanroom construction and EO abatement systems require capital deployment that exceeds private hospital board risk appetites in secondary cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Single-Use Medical Device Reprocessing Market |
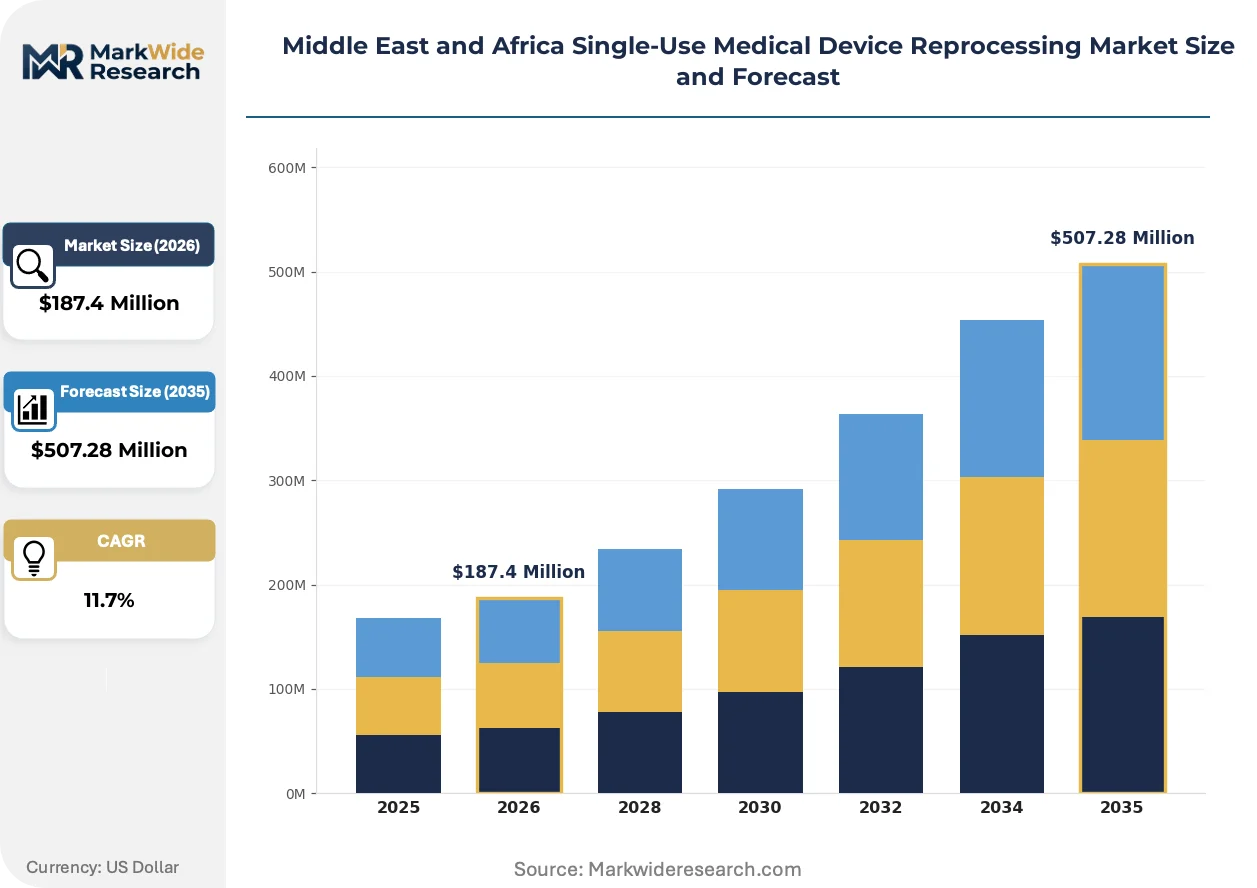
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Catheters, Surgical Instruments, Endoscopes, Dialyzers Service Type: Reprocessing Services, Cleaning Services, Sterilization Services, Packaging Services End User: Hospitals, Surgical Centers, Clinics, Outpatient Facilities Application: Cardiology, Orthopedics, Gastroenterology, Urology |
| Companies Covered | Medline Industries, ReNu Medical, NEScientific, Johnson & Johnson, SteriPro, Stryker, Innovative Health, SureTek Medical, Steris, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Single-Use Medical Device Reprocessing Market Shifts & Advancements
Automated cleaning validation platforms and regulatory data exchange standards are compressing quality assurance cycles and enabling real-time sterility documentation across hospital networks.
Radio-frequency identification tagging combined with blockchain ledger systems is unifying device lifecycle tracking from collection through repackaging. Cardiology departments in Saudi tertiary centers are piloting these integrated traceability stacks to satisfy SFDA audit requirements. The technology is unifying previously fragmented documentation workflows into single-source-of-truth platforms that reduce recall response times from days to hours.
SAHPRA's 2024 technical guidance on third-party reprocessor qualification is mandating annual on-site audits and real-time adverse event reporting. South African hospital groups are responding by consolidating vendor panels and requiring ISO 13485 certification as a baseline contracting condition. Private facilities in Cape Town and Johannesburg are most affected, with procurement departments rewriting RFP templates to embed compliance scoring.
Subscription-based sterilization validation is displacing per-procedure pricing in UAE and Saudi Arabia cath labs. Fixed-fee contracts covering annual device throughput are replacing transactional invoicing, transferring volume risk to reprocessors and stabilizing hospital opex forecasting. This model is most visible in Dubai's private healthcare cluster, where Medline and Stryker service teams anchor multi-year agreements.
Middle East and Africa Single-Use Medical Device Reprocessing Market Segmentation
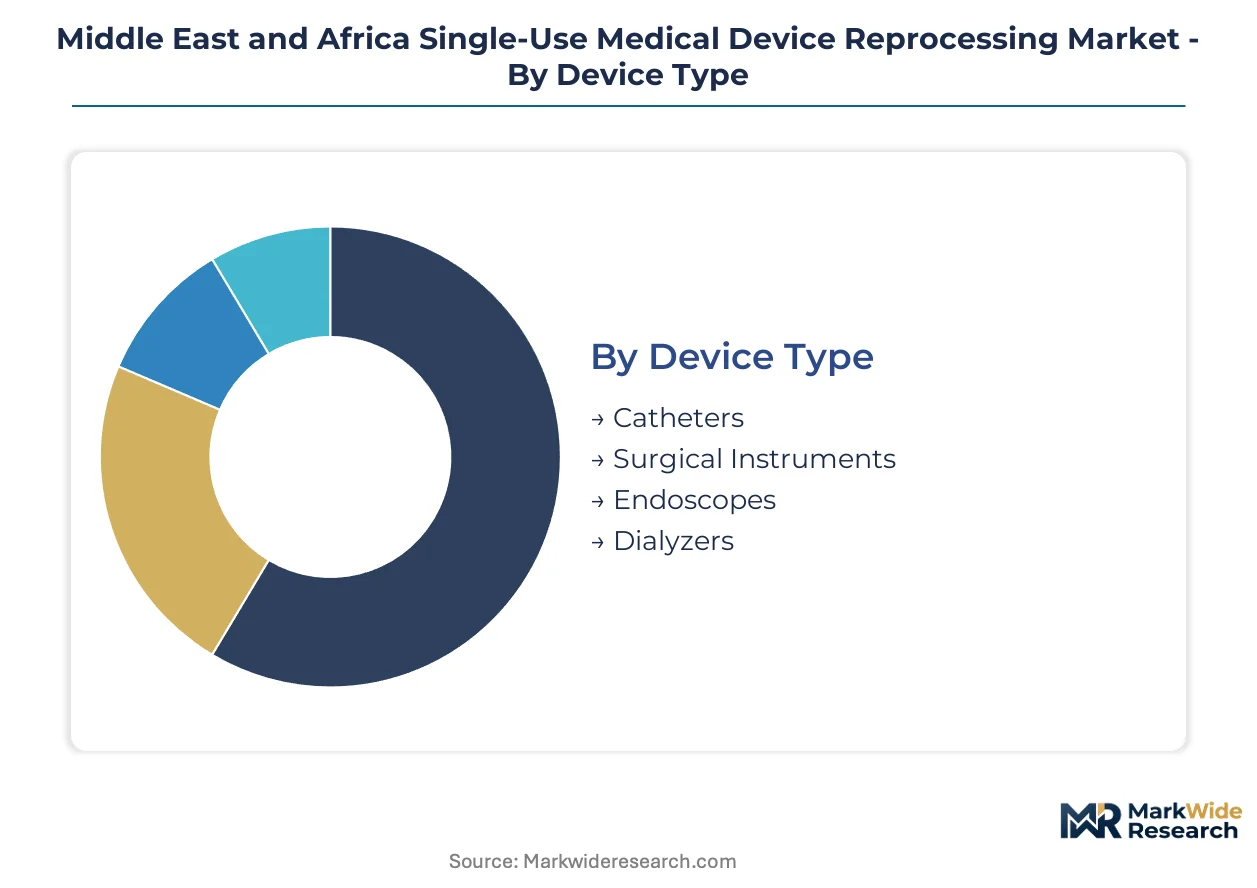
Segmentation in the Middle East and Africa Single-Use Medical Device Reprocessing Market reveals distinct capital requirements, regulatory exposure, and margin profiles across device categories and service tiers. Hospital procurement departments prioritize segments offering validated sterility assurance with minimal bioburden laboratory investment.
Device Type:
Capital intensity varies sharply across device categories, with endoscope reprocessing demanding ISO 14644 cleanroom infrastructure and automated channel cleaning systems that dwarf catheter reprocessing facility costs.
- Catheters:Polymer-based luminal devices undergo validated cleaning, endotoxin testing below 0.5 EU/ml, and EO or hydrogen peroxide sterilization. Cardiology and urology applications in South African tertiary centers and Saudi tertiary hospitals concentrate demand, driven by high procedural volumes and SFDA batch documentation requirements.
- Endoscopes:Flexible fiber-optic instruments with narrow internal channels require automated leak testing and brushless cleaning validation. Gastroenterology screening programs in Saudi Arabia and the UAE are multiplying device turnover, though heat-sensitive materials restrict sterilization modality options.
- Surgical Instruments:Metal and composite tools for open and minimally invasive procedures undergo ultrasonic cleaning and steam sterilization where materials permit.
- Dialyzers:Hollow-fiber membrane devices for renal replacement therapy require specialized pyrogen testing and membrane integrity verification before reuse.
Most installed capacity flows through catheters. Expansion is steepest in endoscopes.
Service Type:
Service tier selection tracks hospital bioburden laboratory capabilities, with facilities lacking certified microbiologists outsourcing complete validation chains.
- Reprocessing Services:Integrated collection-through-repackaging contracts covering cleaning, functional testing, sterilization, and batch documentation. Full-service partnerships dominate in South African private hospital groups facing SAHPRA third-party qualification mandates and traceability infrastructure gaps.
- Sterilization Services:Terminal sterilization using EO, steam, or vapor-phase hydrogen peroxide with biological indicator kill confirmation. Kenya and Egypt outpatient networks rely on external sterilization as capex constraints block in-house chamber installation.
- Cleaning Services:Automated and manual decontamination with bioburden reduction validation.
- Packaging Services:Sterile barrier system assembly with lot control and expiration dating.
Reprocessing services capture dominant contract value. Sterilization services are gaining share fastest in outsourced facility networks.
End User:
End-user segmentation reflects sterilization infrastructure maturity and regulatory audit exposure across facility types.
- Hospitals:Tertiary and secondary acute care facilities with cath labs, endoscopy suites, and operating theaters. South African hospital groups and Saudi tertiary centers anchor regional demand, consolidating vendor panels under SAHPRA and SFDA qualification pressure.
- Surgical Centers:Dedicated ambulatory surgery facilities performing high-volume ophthalmology, orthopedics, and gastroenterology. Dubai's private surgical cluster is adopting subscription-based sterilization validation to stabilize opex forecasting.
- Clinics:Primary care and specialist diagnostic facilities with limited procedural volume.
- Outpatient Facilities:Standalone endoscopy and dialysis centers without captive sterilization capacity.
Hospitals retain the deepest reprocessing integration. Surgical centers are expanding validation outsourcing most rapidly.
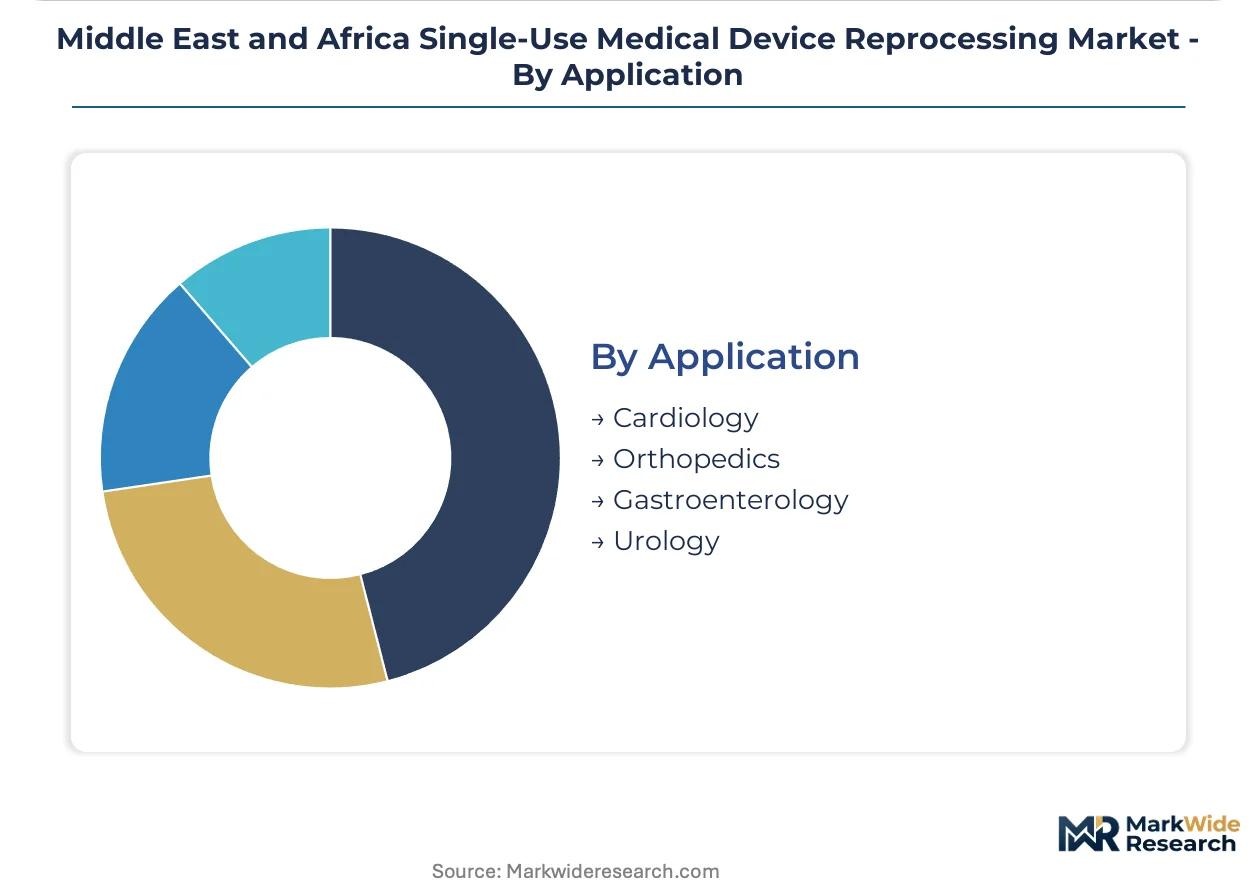
Application:
Application segmentation aligns with procedural volume growth and device innovation cycles that determine reprocessing technical viability.
- Gastroenterology:Colonoscopy and gastroscopy devices for cancer screening and therapeutic intervention. Government screening programs in Saudi Arabia and the UAE are accelerating endoscope turnover and reprocessing demand.
- Cardiology:Diagnostic and interventional catheters for angiography and electrophysiology. Original manufacturers embedding sensors and electronics are shortening reprocessable device lifecycles in tertiary cath labs.
- Orthopedics:Arthroscopic instruments and power tool attachments for joint procedures.
- Urology:Cystoscopes and ureteral access devices for stone and tumor management.
Gastroenterology applications command the steepest volume growth trajectory. Cardiology retains the largest installed reprocessing base despite technical headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping reprocessing facility placement across the Middle East and Africa, with capital migrating toward jurisdictions where sterilization validation costs compress against compliant output quality.
South Africa
Tertiary hospital groups in Johannesburg and Cape Town are consolidating reprocessing contracts under SAHPRA's third-party qualification mandates. The regulator's batch-level sterilization record requirements are disqualifying uncertified operators and concentrating procurement among validated service providers. Private facilities in Gauteng province are rewriting RFP templates to embed compliance scoring for ISO 13485-certified partners.
Saudi Arabia
Government-funded endoscopy screening programs for colorectal and gastric cancers are multiplying procedural volumes in Riyadh and Jeddah tertiary centers. SFDA's forthcoming Class II device reprocessing guidelines are accelerating hospital readiness assessments and pre-qualifying vendor partnerships ahead of enforcement. Cath labs in the Eastern Province are adopting subscription-based sterilization validation to stabilize operational expenditure forecasting.
United Arab Emirates
MOHAP's preferential procurement scoring for ISO 13485-certified reprocessors is creating first-mover advantages for facilities achieving dual SAHPRA-MOHAP accreditation. Dubai's private surgical cluster is displacing per-procedure pricing with fixed-fee contracts covering annual device throughput. Abu Dhabi hospital networks are piloting RFID-blockchain traceability stacks to satisfy audit requirements for real-time adverse event reporting.
Egypt
Ethylene oxide supply volatility is compressing margins for reprocessors dependent on EO chamber sterilization in Cairo and Alexandria. Outpatient surgical networks lack captive sterilization capacity and represent untapped demand for outsourced validation services. The country's national pharmaceutical regulator is assessing alignment with international sterility assurance standards to unlock Gulf Cooperation Council export eligibility.
Kenya
Private clinic chains in Nairobi and Mombasa are driving fastest expansion in sterilization services outsourcing as capex constraints block in-house chamber installation. Low-temperature hydrogen peroxide convergence is opening reprocessing to heat-sensitive endoscope channels previously excluded from reuse programs. Bioburden laboratory talent scarcity in East Africa is forcing reliance on Johannesburg and Dubai-based validation partners.
Middle East and Africa Single-Use Medical Device Reprocessing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated service providers capturing hospital network contracts while sterilization-focused operators serve outpatient facility demand. Market structure tilts toward consolidation among validated third-party reprocessors as SAHPRA, SFDA, and MOHAP qualification barriers compress vendor panels. Three archetypes dominate: distribution-anchored conglomerates bundling reprocessing with consumable supply, pure-play sterilization specialists with regional laboratory networks, and original equipment manufacturers extending service arms to defend device revenue. Competitive moves concentrate on strategic partnerships linking reprocessing validation to catheter procurement contracts, and geographic expansion into underpenetrated East African outpatient networks.
Within the distribution-anchored tier, Medline Industries exemplifies bundling strategy across Gulf Cooperation Council states, while Stryker occupies a position emphasizing direct service teams managing device collection and quality documentation. Among pure-play sterilization specialists, Steris represents the sterilization-as-a-service model extending into Egyptian and Kenyan outpatient surgical networks. These three companies anchor distinct competitive vectors without dominating share concentration, leaving room for mid-scale validated operators to defend niche positions in single-city hospital clusters.
| Leading Market Players |
|---|
| Medline Industries |
| ReNu Medical |
| NEScientific |
| Johnson & Johnson |
| SteriPro |
| Stryker |
| Innovative Health |
| SureTek Medical |
| Steris |
| Others |
Supply & Pricing Matrix
Vapor-phase hydrogen peroxide sterilization adoption is compressing facility capex requirements while redistributing procurement power toward reprocessors with validated low-temperature capabilities across Johannesburg, Riyadh, and Dubai hospital networks. This modality shift simultaneously lowers barrier-to-entry for heat-sensitive device reprocessing and intensifies price competition among established ethylene oxide operators facing sterilant gas procurement volatility.
Pricing Analysis
Distributor margins in Gulf Cooperation Council states absorb 15-25 point spreads between reprocessor gate prices and hospital contract rates, with subscription-based sterilization validation displacing per-procedure invoicing fastest in UAE cath labs. Price differentiation hinges on ISO 13485 certification tier and dual SAHPRA-MOHAP accreditation status, with uncertified operators excluded from tertiary center panels entirely. Cost compression in sterilization services is intensifying because ethylene oxide supply disruptions in Egypt and Kenya are forcing margin absorption or modality switching. Public hospital procurement committees in South Africa exhibit highest price sensitivity, while Dubai's private surgical clusters prioritize compliance scoring over unit economics.
Supply Chain Analysis
Certified microbiologist availability in Johannesburg and Dubai manufacturing geographies constrains regional laboratory network expansion, forcing East African facilities to rely on distant validation partners. Supply concentration centers on South Africa, Saudi Arabia, and the UAE for ISO 14644 cleanroom infrastructure and automated cleaning platforms. Raw material dependencies include ethylene oxide sterilant, hydrogen peroxide consumables, and sterile barrier packaging films. Single-source vulnerability runs through ethylene oxide abatement system suppliers serving Egyptian reprocessing facilities. Distribution runs through Medline's Gulf Cooperation Council logistics infrastructure and Stryker's direct service teams managing device collection and quality documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa single-use medical device reprocessing market represents a late-cycle quality story as SAHPRA, SFDA, and MOHAP qualification mandates filter procurement toward validated operators with documented sterility assurance. Demand is shifting toward premium specifications including real-time adverse event reporting and RFID-blockchain traceability stacks in Saudi tertiary centers.
For Market Incumbents: Deploy certification leverage by accelerating dual SAHPRA-MOHAP accreditation for Johannesburg and Dubai facilities before SFDA Class II guidelines enforce. Consolidate vendor panels through multi-year subscription contracts that transfer volume risk from hospital opex forecasting. Defend against emerging pure-play sterilization specialists by integrating automated cleaning validation platforms with existing cath lab service relationships. For New Entrants and Emerging Players: Begin with Nairobi and Mombasa outpatient surgical networks where capex constraints block in-house sterilization capacity and bioburden laboratory talent scarcity creates partnership dependency. Target Kenya's private clinic chains with low-temperature hydrogen peroxide convergence offerings for heat-sensitive endoscope channels previously excluded from reuse programs. Establish go-to-market presence through Steris-style sterilization-as-a-service contracts rather than capital-intensive facility builds. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale validated operators with single-city hospital cluster concentration and pending ISO 13485 certification gaps. Long-term viability over the next decade rests on regulatory qualification moats deepening as SAHPRA mandates annual on-site audits and real-time adverse event reporting. Acquisition targets should demonstrate existing SFDA pre-qualification progress or MOHAP quality certification incentives capture. The signal to watch is ethylene oxide supply stabilization in Egypt and Kenya, which would compress margins for hydrogen peroxide specialists and restore pricing power to modality-diversified operators.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Accreditation Investment | SAHPRA-MOHAP certification unlocks preferential procurement scoring in Dubai's private surgical cluster. |
| Subscription Contract Conversion | Fixed-fee annual throughput agreements stabilize hospital opex forecasting and transfer volume risk to reprocessors. |
| Low-Temperature Platform Deployment | Hydrogen peroxide vapor sterilization opens reprocessing to heat-sensitive endoscope channels in Kenyan outpatient networks. |
| RFID-Blockchain Traceability Integration | Unified device lifecycle tracking satisfies SFDA audit requirements and compresses recall response timelines. |
| East African Geographic Expansion | Nairobi and Mombasa clinic chains represent untapped demand for outsourced validation services amid bioburden laboratory scarcity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, GPO contracts managers, and third-party reprocessor operations directors with secondary validation against SAHPRA regulatory filings, SFDA guidance documents, hospital procurement databases, and GPO contract repositories. Bottom-up facility capacity modeling and top-down healthcare expenditure allocation triangulated market sizing across the analysis window.
Historical reference periods anchored volume and value projections, with segmentation modeling spanning device type, service tier, end-user facility category, and application area alongside regulatory jurisdiction clustering. CAGRs were derived from installed base turnover rates, procedural volume trajectories in cardiology and gastroenterology, and sterilization modality adoption curves. Forecast inputs incorporated ethylene oxide supply volatility patterns and government screening program expansion timelines in Saudi Arabia and the UAE.
Several conditions sit outside the modeled scope, including original manufacturer sensor embedding trends that may render cardiac catheter reprocessing technically unviable, and unforeseen regulatory harmonization across Gulf Cooperation Council jurisdictions. Forecasts reflect documented assumptions regarding SAHPRA, SFDA, and MOHAP enforcement intensity and hospital procurement committee risk appetite. Material deviation in ethylene oxide supply stabilization, bioburden laboratory talent migration, or Class II device guideline implementation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Graft Delivery Devices Market
Medical Devices
Capsular Tension Rings Market
Medical Devices
LAMEA Breast Pumps Market
Medical Devices
Vagal Nerve Stimulation (VNS) Market
Medical Devices
APAC AMH Market
Medical Devices
Asia-Pacific Medical Aesthetic Devices Market
Medical Devices
Breast Biopsy Marker Market
Medical Devices
Digital Impression System Market
Medical Devices
South America C-Arms Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Muscle Stimulator Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Chemotherapy Infusion Pumps Market