
 BFS Syringes Market | 2026-2036
BFS Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
BFS Syringes Market Outlook
Pharmaceutical contract manufacturing channels is reshaping how BFS syringes reach end users, with fill-finish service providers now controlling direct access to biologics developers. B. Braun leverages captive polymer extrusion capabilities to secure resin supply for high-volume BFS lines. Cytiva sustains technology leadership through its SA25 Aseptic Filling Workcell, which integrates blow-fill-seal processing into isolator-based workflows. Recipharm competes across European CDMO networks by offering dedicated BFS suites for complex biologics.
Blow-fill-seal (BFS) syringes represent single-unit containers formed, filled, and sealed within one continuous automated cycle using extruded pharmaceutical-grade polymer, typically polypropylene or polyethylene, under ISO 5 aseptic conditions. The process eliminates human intervention during filling, rendering BFS syringes critical for sterile injectable delivery of vaccines, biologics, and emergency medications. Pre-filled BFS syringes command premium positioning due to their ready-to-administer format reducing dosing errors and preparation time in clinical settings. Multi-chamber configurations represent the fastest-growing product type, enabling lyophilized drug reconstitution at point of care without separate diluent handling. Polypropylene dominates material selection for its chemical inertness, clarity, and compatibility with gamma sterilization protocols.
The FDA enforces container closure integrity standards through updated guidance on sterile product manufacturing, while the EMA's Annex 1 revision mandates stricter contamination control for aseptic processing, directly elevating BFS validation requirements. ISO 15378 and USP <1207> provide complementary frameworks for pharmaceutical packaging materials and package integrity evaluation, shaping supplier qualification protocols. Stakeholders must monitor evolving regulatory convergence between FDA and EMA aseptic guidelines, as harmonized standards will determine which BFS platform investments retain compliance advantage across dual-market supply strategies.
Market Dynamics
Biopharmaceutical fill-finish capacity conversion toward BFS platforms is restructuring procurement relationships, with contract manufacturers now capturing direct supplier relationships that previously ran through device distributors.
Growth Catalysts
- EMA Annex 1 Revision:Stricter contamination control mandates for aseptic processing elevate BFS validation as a compliance advantage over conventional filling lines.
- Vaccine cold-chain independence:Polypropylene BFS syringes withstand gamma sterilization and temperature excursions that compromise glass alternatives in tropical distribution.
- Multi-chamber configurations:Lyophilized drug reconstitution at point of care eliminates separate diluent handling, expanding BFS adoption in emergency medicine and field deployment.
Market Restraints
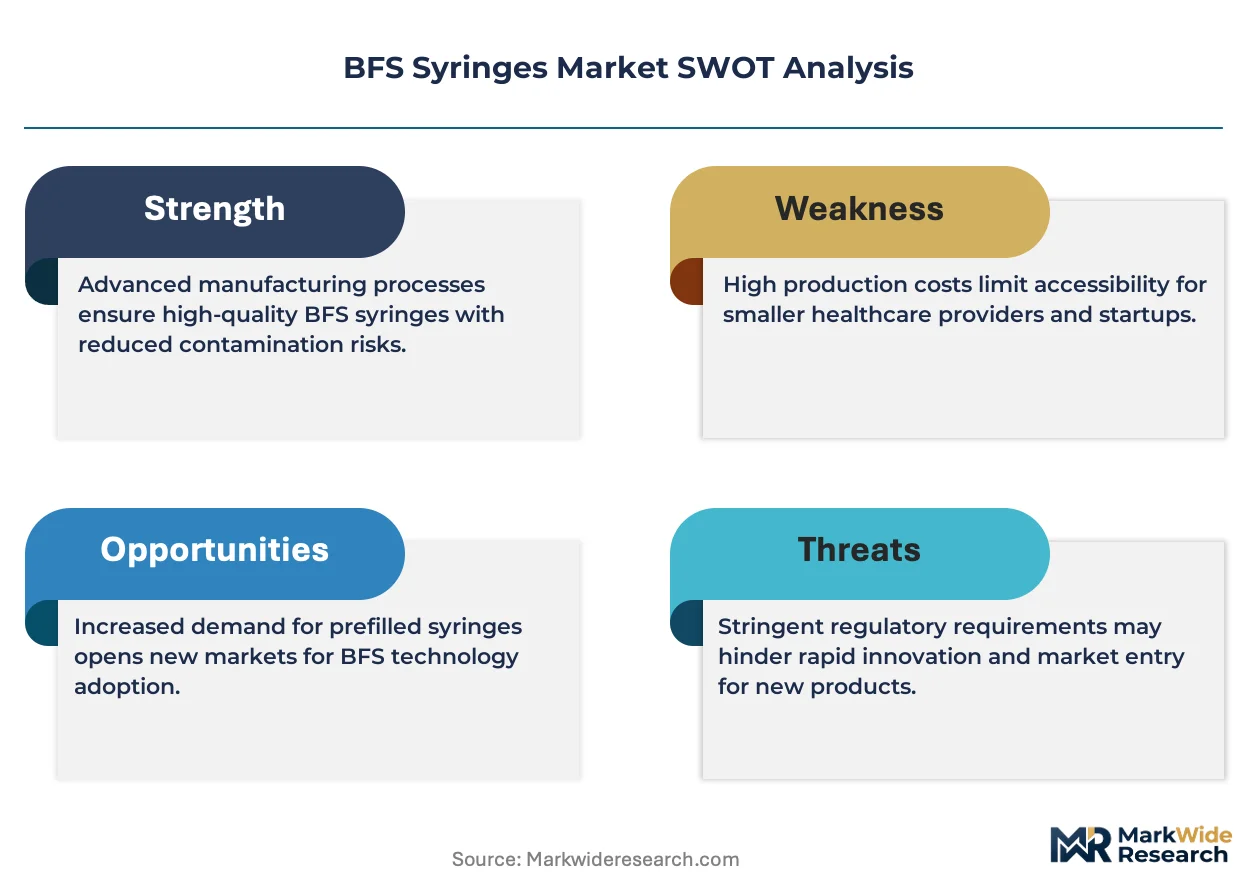
- Pharmaceutical-grade resin concentration:Polypropylene supply for medical applications concentrates among three polymer suppliers, exposing BFS lines to feedstock allocation constraints.
- Validation timeline friction:FDA container closure integrity testing requirements extend qualification cycles for new BFS formats beyond conventional syringe approvals.
- Glass pre-filled substitution:Established biologics developers retain glass syringe investments for high-value mAbs, limiting BFS penetration in premium therapeutic categories.
Strategic Opportunities
- India biologics manufacturing expansion:CDSCO accelerated approval pathways for aseptic processing create first-mover positioning for BFS suite investments serving export markets.
- Cell and gene therapy integration:Closed-system BFS filling aligns with CAR-T manufacturing requirements for contamination control in personalized medicine production.
- Home administration formats:Pre-filled BFS syringes with integrated needle safety systems address reimbursement shifts toward outpatient and self-injection therapies.
Industry Challenges
- Aseptic processing specialist scarcity:BFS equipment operation and validation require hybrid skill sets combining polymer extrusion knowledge with pharmaceutical GMP compliance.
- Legacy filling line retrofit complexity:Isolator integration with existing cleanroom infrastructure demands facility-specific engineering that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BFS Syringes Market |
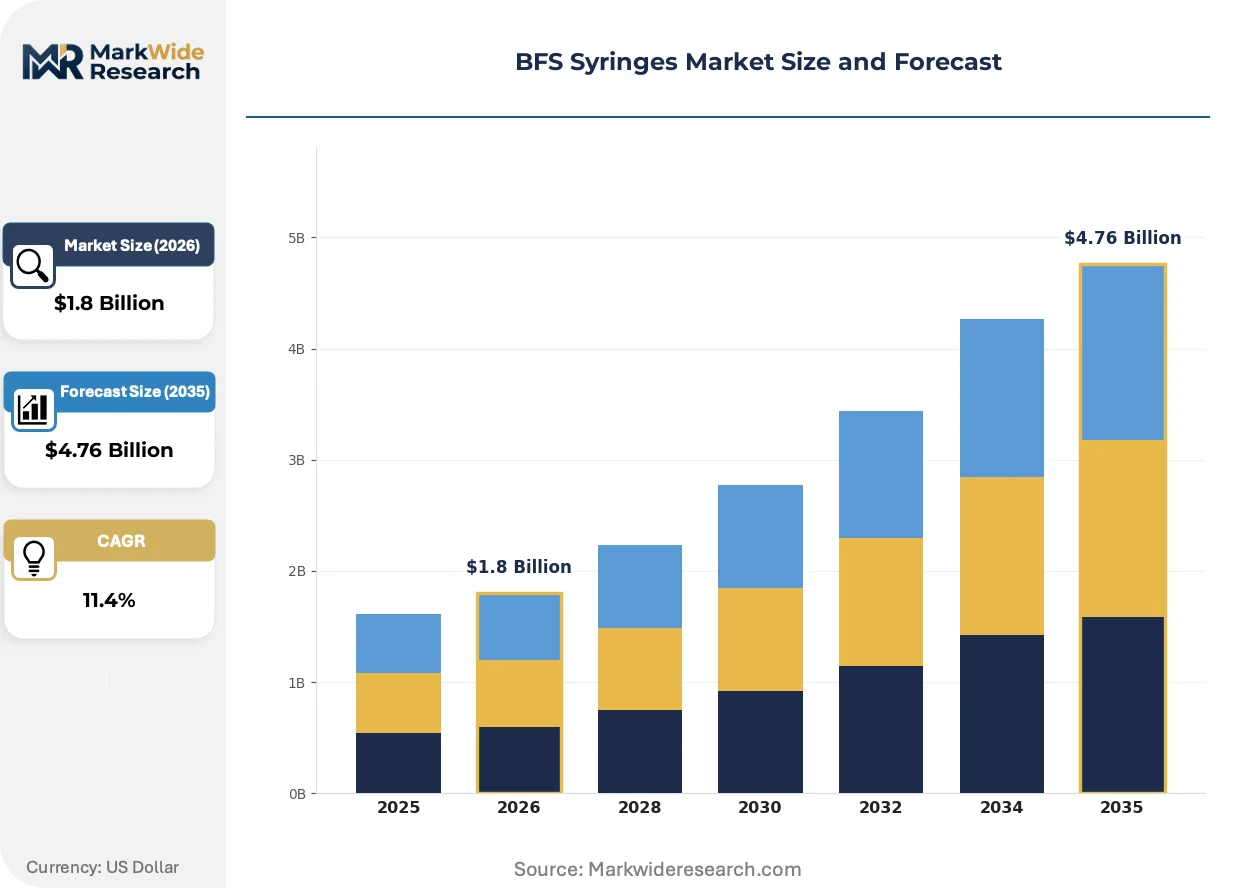
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Chamber, Multi-Chamber, Pre-Filled, Customizable Material: Polypropylene, Glass, Rubber, Silicone End User: Pharmacies, Hospitals, Research Labs, Biotechnology Firms Application: Vaccination, Insulin Delivery, Hormonal Therapy, Anesthesia |
| Companies Covered | Brevetti Angela, Unither Pharmaceuticals, The Ritedose, Optima, Cytiva, B. Braun, Nipro, Recipharm, ApiJect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BFS Syringes Market Strategic Shifts
Automation convergence with isolator technology is redefining aseptic processing boundaries, compressing the distinction between BFS and advanced fill-finish modalities while reshaping supplier competitive advantages.
Closed-vial BFS technology is migrating from standard liquid fill applications toward complex biologics handling, including shear-sensitive proteins and live virus vaccines. Biopharmaceutical developers in the United States and Germany are piloting these systems for parenteral formulations previously restricted to glass containment. This migration from conventional open processing is enabling facility footprint reduction while meeting EMA Annex 1 closed-system requirements.
FDA updated guidance on container closure integrity testing now mandates probabilistic detection methods over deterministic alternatives for sterile product validation. The industrial consequence is accelerated investment in helium leak detection and vacuum decay instrumentation for BFS production lines. High-value biologics and vaccines face the steepest compliance ramps, with sponsors in Massachusetts and North Carolina retrofitting existing suites ahead of enforcement timelines.
Biopharmaceutical procurement is consolidating supplier relationships around fill-finish service providers with captive BFS capabilities, displacing traditional device distributor intermediaries. CDMOs in Switzerland and Singapore now contract directly with polymer resin suppliers, capturing margin and technical specification control. This channel restructuring is most visible in mAb and vaccine segments where lot-size flexibility and rapid format changeover determine sourcing decisions.
BFS Syringes Market Segmentation
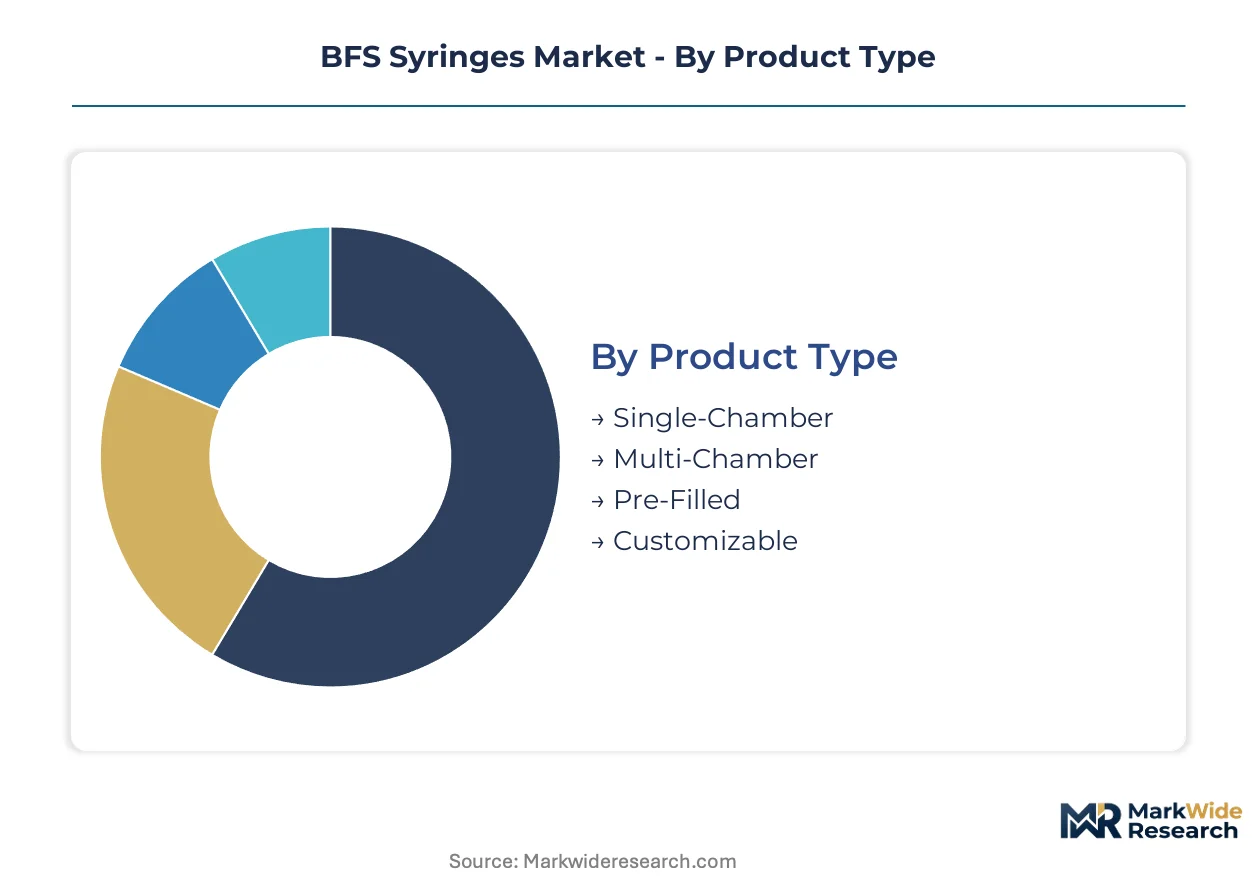
BFS syringe procurement varies sharply across use cases, with product configuration and material selection determining regulatory pathway complexity and manufacturing scale economics. Segment boundaries are blurring as multi-chamber formats penetrate vaccination while pre-filled designs expand into home administration settings.
Product Type:
Cost tier differentiation separates commodity single-unit containers from premium multi-chamber systems requiring specialized reconstitution engineering.
- Single-Chamber:Standard liquid-fill configuration dominates high-volume vaccine production with streamlined validation protocols. Demand concentrates in United States CDC stockpiling programs where unit cost minimization overrides feature complexity.
- Multi-Chamber:Dual-compartment design enables lyophilized drug reconstitution without separate diluent handling. European emergency medicine networks in Germany and Switzerland are adopting these formats for field deployment scenarios requiring cold-chain independence.
- Pre-Filled:Ready-to-administer format reduces dosing errors in clinical settings.
- Customizable:Tailored geometries accommodate novel biologic viscosities and delivery volumes.
Single-Chamber commands the established base. The steepest expansion runs through Multi-Chamber.
Material:
Application requirements dictate material selection, with gamma sterilization compatibility and chemical inertness filtering options for parenteral biologics.
- Polypropylene:Pharmaceutical-grade polymer offers clarity, chemical resistance, and seamless gamma sterilization integration. United States biopharmaceutical fill-finish lines specify this resin for mAb and vaccine containment due to temperature excursion tolerance exceeding glass alternatives.
- Glass:Borosilicate construction retains preference among established biologics developers for high-value monoclonal antibodies requiring oxygen barrier properties.
- Rubber:Elastomer components function as plunger stoppers in multi-chamber actuation mechanisms.
- Silicone:Lubricant coatings reduce break-loose and glide forces in pre-filled formats.
Polypropylene dominates volume throughput. Glass maintains premium positioning for oxygen-sensitive biologics.
End User:
Customer type determines order scale and specification complexity, with institutional procurement diverging from research-scale customization requirements.
- Pharmacies:Retail and hospital pharmacy networks drive pre-filled format adoption for outpatient injectable therapies. United States reimbursement shifts toward self-administration are accelerating unit-dose procurement through specialty pharmacy distributors.
- Hospitals:Acute care settings prioritize multi-chamber configurations for emergency medication reconstitution. German university hospital networks specify these formats for anesthesia and critical care protocols requiring rapid preparation.
- Research Labs:Clinical trial supply demands small-batch flexibility with rapid format changeover.
- Biotechnology Firms:Development-stage companies source customizable prototypes for formulation stability testing.
Hospitals anchor institutional demand. Biotechnology firms represent the most volatile order pattern with highest customization premium.
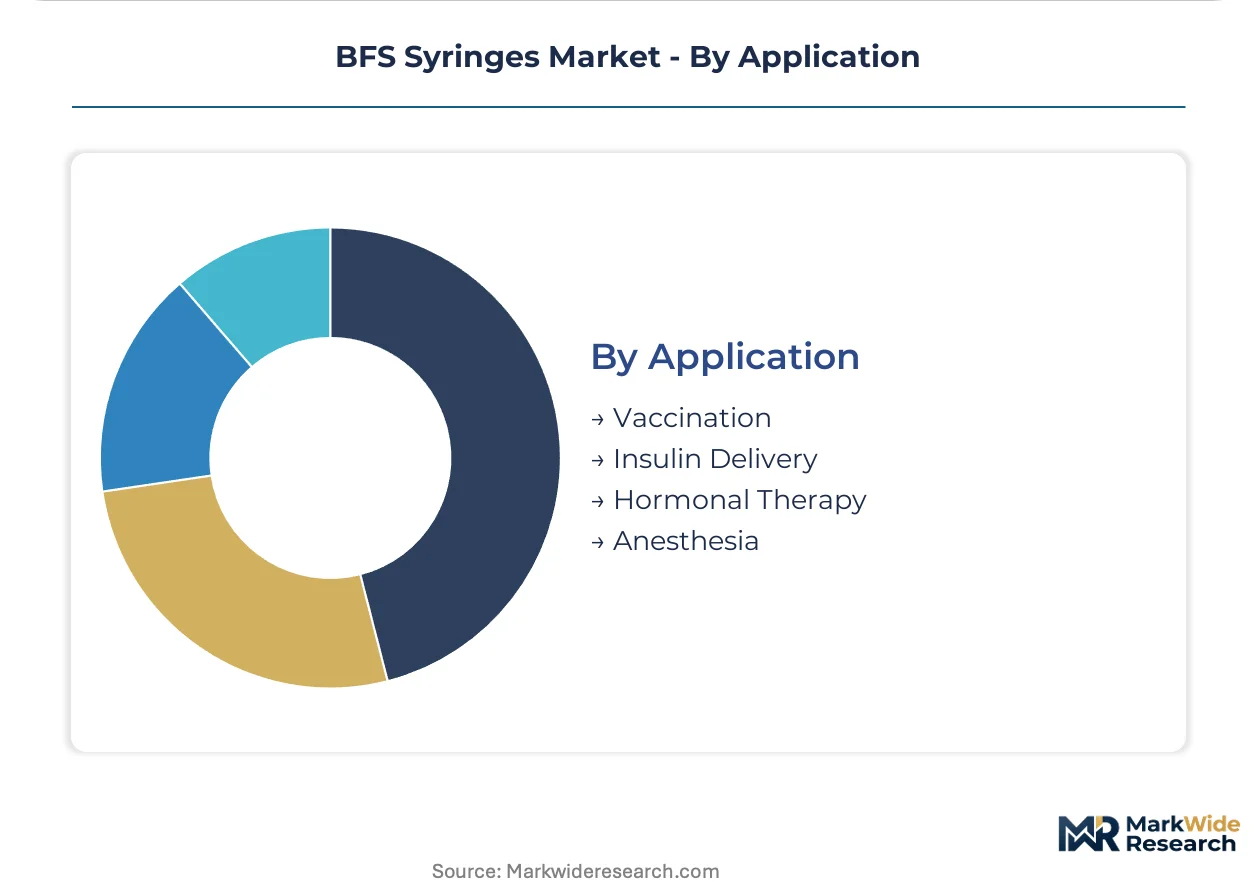
Application:
Volume scale and regulatory scrutiny vary by therapeutic category, with mass immunization programs imposing distinct manufacturing constraints from chronic disease management.
- Vaccination:Pandemic-era fill-finish capacity investments continue converting toward BFS platforms for aseptic bulk supply. United States government stockpiling contracts specify polypropylene single-chamber formats with multi-year stability requirements.
- Insulin Delivery:Diabetes management drives pre-filled format adoption for home administration compliance. Swiss and German reimbursement frameworks now favor ready-to-use systems over vial-and-syringe preparation.
- Hormonal Therapy:Fertility and endocrine treatments require precise dose accuracy in multi-dose regimens.
- Anesthesia:Operating room settings demand rapid-acting multi-chamber reconstitution for emergency induction sequences.
Vaccination generates the highest absolute unit volumes. Insulin Delivery is climbing the fastest as self-administration formats penetrate European and North American markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites Europe's BFS distribution hub status, while Singapore's Changi air cargo terminals anchor Asia-Pacific vaccine transit corridors.
United States
CDC stockpiling programs and BARDA pandemic preparedness contracts drive single-chamber polypropylene procurement at scale. FDA container closure integrity guidance tightens validation timelines for new BFS formats. Massachusetts and North Carolina biopharmaceutical clusters retrofit fill-finish suites ahead of enforcement deadlines.
Germany
University hospital networks specify multi-chamber BFS configurations for anesthesia and emergency medicine protocols. EMA Annex 1 revision mandates stricter contamination control for aseptic processing, elevating BFS platform compliance advantages. Baden-Württemberg and Bavaria CDMO networks compete across European biologics contract manufacturing.
Switzerland
Specialty pharmacy reimbursement frameworks favor ready-to-use pre-filled formats for outpatient injectable therapies. Swissmedic aligns with EMA aseptic guidelines while maintaining distinct national variation timelines. Basel and Zürich pharmaceutical clusters integrate BFS capabilities into existing biologics manufacturing infrastructure.
India
CDSCO accelerated approval pathways for aseptic processing create first-mover positioning for export-oriented BFS suite investments. PLI scheme incentives support domestic pharmaceutical packaging material manufacturing scale-up. Maharashtra and Gujarat pharmaceutical corridors attract contract manufacturing investments serving regulated markets.
Singapore
Temperature-controlled pharmaceutical logistics infrastructure supports regional vaccine distribution hub requirements. HSA regulatory convergence with FDA and EMA standards enables dual-market supply qualification from single facilities. Tuas biomedical manufacturing zone hosts fill-finish service providers with integrated BFS platform capabilities.
BFS Syringes Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in polymer extrusion and isolator technology. The vendor base stratifies across three tiers: multinational fill-finish equipment suppliers with captive polymer capabilities, regional contract manufacturers offering dedicated BFS suites, and specialized polymer resin suppliers controlling pharmaceutical-grade feedstock allocation. Strategic moves concentrate on backward integration into resin supply and isolator-based workflow integration with existing cleanroom infrastructure.
Within the platform integrator tier, Cytiva and B. Braun exemplify equipment suppliers with integrated blow-fill-seal processing capabilities. Among European contract manufacturing specialists, Recipharm occupies a position representing CDMO networks competing across dedicated BFS suites for complex biologics. These three anchors illustrate the competitive structure: technology licensors, captive manufacturers, and service providers each defending distinct value chain positions.
| Leading Market Players |
|---|
| Brevetti Angela |
| Unither Pharmaceuticals |
| The Ritedose |
| Optima |
| Cytiva |
| B. Braun |
| Nipro |
| Recipharm |
| ApiJect |
| Others |
Value Chain & Pricing Dynamics
The Port of Rotterdam's pharmaceutical cold-chain corridors transmit resin cost volatility directly into BFS syringe price differentiation, with polypropylene feedstock concentration among three polymer suppliers compressing margin structures for contract manufacturers while enabling premium capture by integrated producers.
Pricing Analysis
Three-tier pricing structure across premium multi-chamber systems, standard pre-filled formats, and economy single-chamber configurations separates validation complexity tiers. Price differentiation hinges on EMA Annex 1 compliance certification and captive polymer extrusion capabilities. Cost compression in standard pre-filled tiers is intensifying because CDMO procurement consolidation eliminates distributor markups. Government stockpiling programs exhibit lowest price sensitivity; research-scale biotechnology firms face acute budget constraints.
Supply Chain Analysis
Tariff exposure between the United States and China dominates pharmaceutical-grade resin sourcing risk for BFS manufacturers. Polypropylene supply concentrates in the United States, Germany, and Saudi Arabia; isolator technology components draw from Switzerland and Japan. Single-source vulnerability persists for gamma sterilization validation services. Distribution runs through fill-finish service providers with captive BFS suites, bypassing traditional device distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among biopharmaceutical contract manufacturers is shifting bargaining power upstream, with CDMO network expansion reducing supplier fragmentation and compressing margin capture opportunities for non-integrated BFS producers.
For Market Incumbents: Entrench polymer supply security through backward integration into pharmaceutical-grade resin extrusion or long-term offtake agreements with the three dominant suppliers. Isolator-based workflow certification investment defends against emerging platform competitors from Singapore and India. Channel control through direct CDMO relationships counters margin pressure from distributor displacement.
For New Entrants and Emerging Players: Pursue multi-chamber BFS configurations for lyophilized drug reconstitution, where European emergency medicine networks exhibit supply gap vulnerability. The most penetrable geography is India, where CDSCO accelerated approval pathways reward first-mover aseptic suite investments. Go-to-market positioning should emphasize cold-chain independence for tropical vaccine distribution.
For Investors and Strategic Acquirers: Regional CDMO networks with dedicated BFS suites for complex biologics represent the priority acquisition archetype, given their direct access to biopharmaceutical developers displacing distributor intermediaries. Long-term viability rests on EMA-FDA regulatory convergence enabling dual-market qualification from single facilities. The signal to watch is FDA enforcement timeline acceleration for container closure integrity testing mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Integration Investment | EMA Annex 1 compliance positioning captures European biologics contract manufacturing share from conventional filling lines. |
| Backward Integration into Polymer Extrusion | Captive resin supply secures allocation priority during pharmaceutical-grade polypropylene feedstock constraints. |
| Multi-Chamber Configuration Development | Lyophilized drug reconstitution capability penetrates German and Swiss emergency medicine procurement networks. |
| CDMO Direct Relationship Establishment | Bypassing device distributor channels captures margin and technical specification control in mAb sourcing decisions. |
| Regulatory Dual-Qualification Investment | Simultaneous FDA and EMA validation enables single-facility supply to United States and European biopharmaceutical developers. |
Study Parameters
A spread of perspectives from fill-finish operations directors, regulatory affairs leads at CDMOs, polymer procurement managers, and hospital pharmacy buyers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA guidance documents, EMA Annex 1 revision drafts, ISO 15378 certification databases, and USP container closure integrity standards. Bottom-up capacity modeling across BFS production lines triangulated against top-down biopharmaceutical fill-finish expenditure tracking.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product configuration complexity, material sterilization compatibility, end-user procurement scale, and regional regulatory cluster stringency. CAGRs were synthesized from facility commissioning timelines, validation cycle durations, and biopharmaceutical outsourcing trend trajectories. Forecast inputs incorporated CDSCO approval pathway acceleration rates and BARDA pandemic preparedness contract renewal patterns.
Sensitivities concentrate around FDA enforcement timeline shifts for container closure integrity testing and polypropylene feedstock allocation disruptions among the three dominant pharmaceutical-grade resin suppliers. Forecasts reflect documented assumptions regarding EMA-FDA regulatory convergence pace and CDMO procurement consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Patellar Implant Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Ultrasound Biometry Devices Market
Medical Devices
Sweden Ophthalmic Devices Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Global Pupillometer Market
Medical Devices
Transport Chairs Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Epistaxis Devices Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market