
 Air Ambulance Market | 2026-2036
Air Ambulance Market Size, Share, and Industry Trends Forecast 2026-2036
Air Ambulance Market Analytics
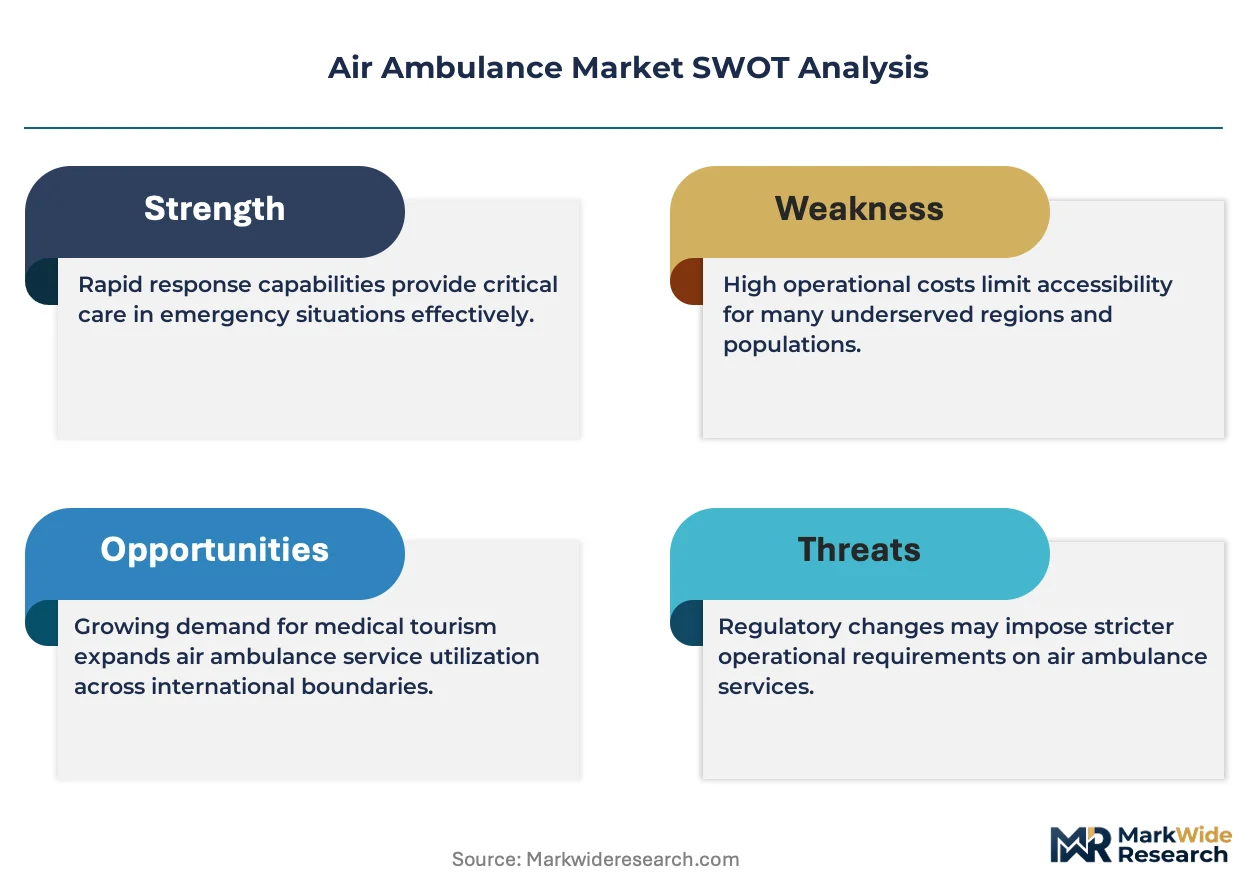
Lightweight carbon-fiber composite airframes is restructuring rotary-wing unit economics across the air ambulance sector. Air Methods Corporation leverages vertical integration across base operations and pilot training to sustain fleet utilization rates in mountainous terrain. Global Medical Response anchors its position through geographic dominance across contiguous US emergency networks. PHI specializes in offshore-to-tertiary-care corridors along the Gulf Coast.
An air ambulance constitutes a medically configured aircraft—rotary-wing or fixed-wing—equipped with ventilators, defibrillators, and pressurized cabin systems capable of sustaining patients at altitudes exceeding 10,000 feet during inter-facility transfer or scene response. Rotary-wing service dominates urban and trauma-scene missions due to vertical landing capability, while fixed-wing platforms command longer-range medical evacuation routes across international borders. Advanced Life Support technology captures premium margin pools as telemetry integration allows in-flight physician consultation. Telemedicine adoption is accelerating fastest among hospital-contracted fleets seeking to reduce unnecessary diversions.
FAA Part 135 operational specifications and EASA airworthiness directives for medical installations shape fleet retrofit cycles and new aircraft procurement timelines. The EU AI Act and FDA device-clearance pathways for airborne patient-monitoring equipment are tightening certification requirements for technology suppliers. Stakeholders must monitor evolving reimbursement frameworks from CMS and national health insurers that increasingly tie aeromedical coverage to demonstrated time-to-tertiary-care outcomes.
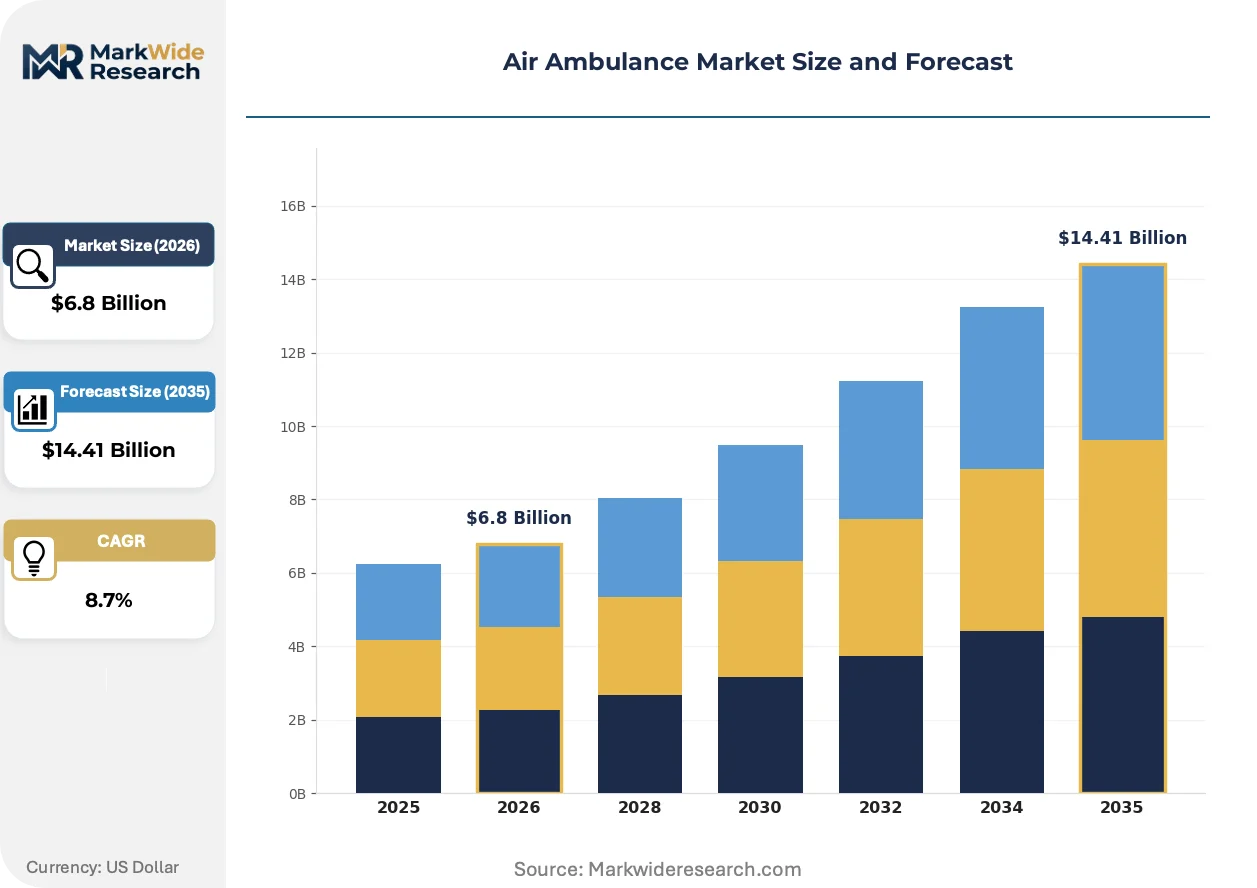
Market Dynamics
Carbon-fiber composite airframes are compressing operating costs per flight hour while FAA Part 135 certificate modernization forces fleet-wide retrofit investments that reshape competitive economics across rotary-wing and fixed-wing operators.
Growth Catalysts
- Rural Healthcare Access Gaps:Aging populations in the United States, Germany, and Australia sustain demand for rapid inter-facility transfers where ground transport times exceed clinical windows.
- EASA Medical Aircraft Certification:Upgraded EU-wide standards are accelerating hospital network contracting for dedicated aeromedical services with guaranteed response-time clauses.
- Advanced Life Support Telemetry:In-flight physician consultation capabilities via real-time patient monitoring are expanding reimbursable service tiers.
Market Restraints
- Jet Fuel Price Volatility:Rotary-wing turbine fuel exposure compresses margins for operators without long-term supply hedges.
- Pilot Training Pipeline Constraints:FAA instrument rating certification backlogs limit fleet expansion velocity regardless of aircraft availability.
- Ground-Based Critical Care Substitution:Regional hospital stroke-center networks and mobile ECMO units reduce dependency on air transport for time-sensitive cases.
Strategic Opportunities
- Telemedicine Integration:Hospital-contracted fleets are embedding airborne patient-monitoring equipment to reduce unnecessary diversions and capture CMS outcome-based reimbursement.
- Drone-Enabled Medical Payload Delivery:Automated defibrillator and blood-product distribution to remote locations converges with existing aeromedical dispatch infrastructure.
- Offshore Energy Corridor Expansion:Gulf Coast and North Sea fixed-platform medical evacuation contracts command premium day-rates with multi-year tenors.
Industry Challenges
- Specialized Aeromedical Crew Certification:Flight nurse and paramedic critical-care credentials require recurrent training that outpaces general aviation staffing pools.
- Legacy Avionics Integration:Retrofitting pressurized cabin systems with FDA-cleared patient-monitoring devices extends aircraft downtime beyond scheduled maintenance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Ambulance Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Medical Transport, Fixed-Wing, Rotary-Wing, Medical Evacuation End User: Hospitals, Clinics, Emergency Services, Insurance Providers Fuel Type: Jet Fuel, Aviation Gas, Diesel, Biofuel Technology: Telemedicine, Advanced Life Support, Navigation Systems, Communication Equipment |
| Companies Covered | Air Methods Corporation, Global Medical Response, Acadian Companies, PHI, REVA, AirMed International, Babcock Scandinavian AirAmbulance, Express Air Medical Transport, Native American Air Ambulance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Ambulance Market Evolving Landscape
Lightweight materials and real-time data transmission are compressing the cost-quality frontier in aeromedical transport while regulatory frameworks on both sides of the Atlantic tighten operational specifications.
Telemedicine-enabled patient monitoring is unifying in-flight care standards with ground-based ICU capabilities. Hospital-network procurement teams are mandating telemetry integration as a baseline contract requirement. This convergence is compressing the clinical gap between scene response and tertiary-care handoff, enabling more complex patient transport.
EU AI Act classification requirements for airborne diagnostic algorithms are extending software validation timelines for patient-monitoring equipment suppliers. EASA airworthiness directives now explicitly address machine-learning-enabled decision-support tools in medical aircraft installations. Fixed-wing operators on transcontinental routes face the steepest compliance burden as dual jurisdiction certification becomes standard.
Outcome-based contracting is displacing traditional per-flight reimbursement across Medicare Advantage and commercial payer networks. Hospital systems in the United States are consolidating aeromedical vendor panels to three or fewer preferred operators with guaranteed time-to-tertiary-care metrics. This concentration is most advanced in the Mountain West and Great Plains regions where rural hospital closures have eliminated alternative transport modes.
Air Ambulance Market Segmentation
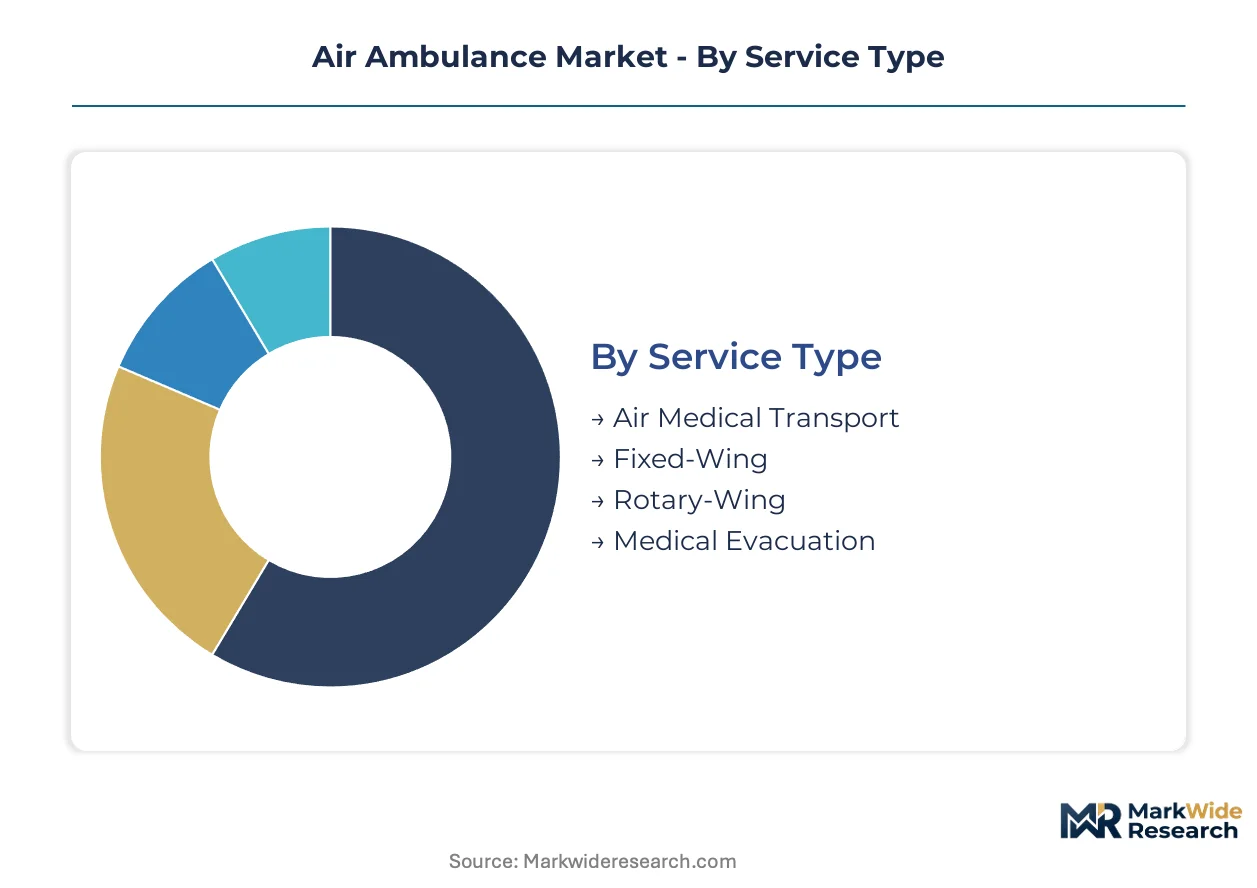
Air ambulance fleet configuration varies sharply across service models, patient acuity levels, and operational geographies. Technology integration and fuel economics now dominate procurement decisions as hospital networks consolidate vendor relationships around measurable clinical outcomes.
Service Type:
Rotary-wing platforms deploy distinct propulsion and landing specifications versus fixed-wing alternatives, with each architecture commanding separate FAA Part 135 operational certificates and EASA medical aircraft type ratings.
- Air Medical Transport:Comprehensive service contracts bundle aircraft, crew, and ground coordination into single-source agreements with hospital networks. Demand concentrates in the United States Mountain West where terrain eliminates ground-based alternatives for inter-facility transfers.
- Fixed-Wing:Pressurized cabin systems sustain patients above 10,000 feet across continental and international routes. Germany's rural hospital consolidation is accelerating long-range medical evacuation contracts from peripheral regions to tertiary centers in Munich and Berlin.
- Rotary-Wing:Vertical landing capability dominates trauma-scene response in urban corridors and offshore energy platforms. Australia's vast interior sustains helicopter fleet expansion for mining and agricultural emergency coverage.
- Medical Evacuation:Dedicated military-civilian hybrid contracts support disaster response and conflict-zone extraction. Procurement runs through defense ministries and humanitarian organizations with multi-year fleet leases.
Mature deployment sits with rotary-wing trauma response. Newer deployment is concentrated in fixed-wing international medical evacuation.
End User:
Reimbursement frameworks and patient volume thresholds determine which institutional categories sustain dedicated aeromedical contracts versus ad hoc charter arrangements.
- Hospitals:Tertiary-care centers in the United States anchor exclusive vendor panels with guaranteed time-to-tertiary-care clauses. Stroke-center certification requirements from CMS are mandating 90-minute door-to-needle windows that compress ground transport viability in rural catchments.
- Clinics:Federally qualified health centers and rural critical-access facilities contract for scheduled inter-facility transfers rather than emergency response. Australia's Royal Flying Doctor Service partnerships exemplify this operational model.
- Emergency Services:Fire departments and municipal EMS agencies operate hybrid ground-air dispatch protocols. Equipment interoperability with hospital telemetry systems is becoming a mandatory contract specification.
- Insurance Providers:Medicare Advantage and commercial payers are piloting outcome-based aeromedical reimbursement tied to demonstrated mortality reduction. Prior authorization requirements are extending pre-flight clinical review timelines.
Procurement authority is consolidating under hospital network central purchasing. Insurance-provider contracting is expanding fastest in value-based care markets.
Fuel Type:
Energy density specifications and supply chain infrastructure determine operational range and base location flexibility across fleet types.
- Jet Fuel:Turbine-engine rotary-wing and fixed-wing platforms consume Jet A or Jet A-1 with standardized airport distribution. Price volatility exposure concentrates margin pressure on operators without long-term supply hedges.
- Aviation Gas:Piston-engine aircraft in lighter medical transport roles use 100LL avgas with limited rural airport availability. Germany's general aviation infrastructure sustains regional distribution networks.
- Diesel:Ground support equipment and auxiliary power units at remote bases utilize diesel with localized storage requirements. Environmental compliance with EPA and EASA emissions directives is extending equipment replacement cycles.
- Biofuel:Sustainable aviation fuel blends are entering trial programs with hospital-network sustainability mandates. Certification timelines for medical aircraft installations lag commercial aviation adoption.
Jet fuel dominates rotary-wing and fixed-wing turbine operations. Biofuel adoption is climbing the fastest among hospital-contracted fleets with net-zero commitments.
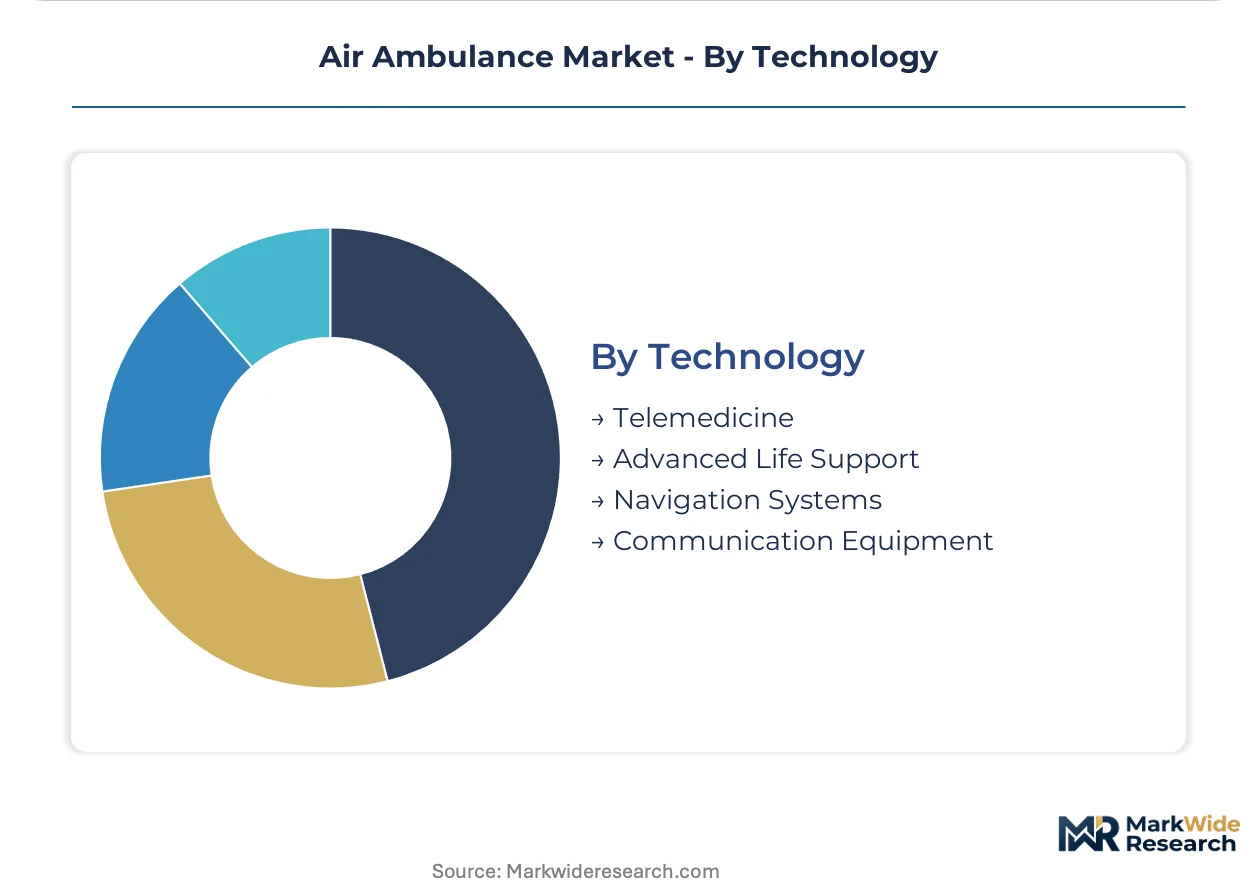
Technology:
Regulatory clearance pathways for airborne medical devices are extending software validation timelines as FDA and EASA tighten integration standards.
- Telemedicine:Real-time patient monitoring with ground-based physician consultation reduces unnecessary diversions. Australia's remote health infrastructure has pioneered satellite-enabled telemetry for outback operations.
- Advanced Life Support:Ventilators, defibrillators, and infusion pumps with pressurized-cabin certification command premium equipment margins. FDA 510(k) clearance for airborne installations requires electromagnetic interference testing.
- Navigation Systems:GPS augmentation and terrain-awareness systems support instrument flight rules in mountainous terrain. FAA WAAS coverage gaps in the Rocky Mountain region limit all-weather dispatch reliability.
- Communication Equipment:Satellite voice and data links enable continuous hospital contact beyond terrestrial radio range. EU AI Act classification requirements for algorithm-enabled decision support are extending procurement review timelines.
Navigation and communication systems represent mature fleet standards. Telemedicine integration is gaining share fastest as hospital networks mandate telemetry-enabled contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for aerospace manufacturing in the United States, Germany, and Australia concentrate air ambulance fleet assembly and MRO capacity. Hospital network procurement clusters in these jurisdictions drive regional demand concentration.
United States
Rural hospital closures across the Mountain West and Great Plains sustain rotary-wing demand for inter-facility transfers exceeding ground transport windows. FAA Part 135 certificate modernization tightens operational specifications for existing fleet retrofits. Denver and Phoenix anchor base operations for Rocky Mountain and Southwest corridor coverage.
Germany
Rural hospital consolidation to tertiary centers in Munich and Berlin accelerates fixed-wing medical evacuation contracts from peripheral regions. EASA medical aircraft certification upgrades mandate guaranteed response-time clauses in hospital network agreements. Bavaria hosts Europe's densest helicopter emergency medical service infrastructure.
Australia
Vast interior distances and mining sector emergency coverage sustain helicopter fleet expansion for agricultural and resource extraction regions. TGA oversight of airborne patient-monitoring equipment aligns with FDA pathways for telemedicine integration. Queensland and Western Australia concentrate Royal Flying Doctor Service partnerships with remote clinics.
Canada
Indigenous community health access gaps in northern territories sustain dedicated aeromedical contracts for fly-in-only settlements. Health Canada regulatory harmonization with FAA Part 135 standards facilitates cross-border fleet certification. Alberta and British Columbia anchor base networks for Arctic and Pacific coastal response.
Air Ambulance Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital-network exclusive contracts concentrating procurement authority among vertically integrated operators. The vendor base organizes around three strategic archetypes: full-service aeromedical providers bundling aircraft, crew, and ground coordination; fixed-wing specialists commanding long-range international evacuation routes; and rotary-wing operators dominating trauma-scene response and offshore energy corridors. Dominant competitive moves include geographic consolidation through exclusive hospital panel appointments and telemetry integration mandates that raise rival compliance costs.
Among North American full-service providers, Air Methods Corporation and Global Medical Response occupy positions as archetypal integrated operators, while PHI exemplifies the offshore-specialist tier serving energy corridor contracts. These entities anchor competitive dynamics through base density advantages and long-term hospital network relationships rather than episodic charter arrangements.
| Leading Market Players |
|---|
| Air Methods Corporation |
| Global Medical Response |
| Acadian Companies |
| PHI |
| REVA |
| AirMed International |
| Babcock Scandinavian AirAmbulance |
| Express Air Medical Transport |
| Native American Air Ambulance |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialists dominating the United States aeromedical sector impose capital discipline that compresses supplier payment terms while sustaining premium pricing for hospital-network exclusive contracts. This ownership concentration concentrates procurement leverage among Air Methods Corporation and Global Medical Response, forcing airframe OEMs and avionics suppliers to absorb extended receivables cycles in exchange for multi-year fleet commitments.
Pricing Analysis
Short lead-time premiums dominate contract structures, with hospital networks paying 15-25% markups for guaranteed 90-minute response windows versus standard inter-facility scheduling. Three-tier pricing structure across premium ALS telemetry, standard medical transport, and economy repositioning flights reflects certification grade differentiation and volume scale. Cost compression in economy-tier piston-aircraft segments is intensifying because of avgas distribution gaps at rural airports. Federally qualified health centers exhibit highest price sensitivity, while tertiary-care stroke centers accept premium telemetry bundling without negotiation.
Supply Chain Analysis
Dual-sourcing requirements from FAA Part 135 operators mandate qualified backup suppliers for pressurized cabin systems and patient-monitoring devices, extending procurement timelines. Manufacturing concentrates in the United States, Germany, and Canada for airframe assembly, avionics integration, and MRO capacity. Fleet expansion draws from carbon-fiber composite airframes, turbine engines, and FDA-cleared medical devices. Single-source vulnerability sits with specialized flight nurse training programs that outpace general aviation staffing pools. Distribution runs through hospital network central purchasing committees with exclusive panel appointments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pilot certification pipeline constraints represent the binding capacity bottleneck, propping pricing power for incumbent operators with established training academies regardless of aircraft availability.
For Market Incumbents: Hedge fuel price exposure through long-term Jet A supply hedges and backward integration into sustainable aviation fuel trial programs. Consolidate telemetry-enabled fleet standards to raise rival compliance costs as EU AI Act software validation timelines extend. Defend hospital panel positions by embedding real-time patient monitoring as non-negotiable contract terms. For New Entrants and Emerging Players: Enter via drone-enabled medical payload distribution partnerships with existing aeromedical dispatch infrastructure, bypassing crew certification barriers. Target Australia's Royal Flying Doctor Service clinic networks for scheduled inter-facility transfers rather than emergency response competition. Pursue fixed-wing international evacuation routes from Germany's peripheral regions where EASA certification upgrades disadvantage legacy operators. For Investors and Strategic Acquirers: Distressed-cycle entries favor rotary-wing specialists with mountainous terrain operational certificates in the United States Mountain West, where rural hospital closures eliminate ground transport alternatives. Long-term viability hinges on exclusive hospital network relationships with guaranteed time-to-tertiary-care clauses rather than episodic charter revenue. Monitor CMS reimbursement rulemaking on outcome-based aeromedical coverage as the decisive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Integration Mandate | Hospital procurement committees now require real-time patient monitoring as baseline contract specification. |
| FAA Part 135 Certificate Modernization | Retrofit investments reshape competitive economics for rotary-wing and fixed-wing operators alike. |
| Sustainable Aviation Fuel Adoption | Hospital network net-zero commitments accelerate biofuel certification for medical aircraft installations. |
| Exclusive Hospital Panel Consolidation | Vendor reduction to three preferred operators concentrates procurement authority among integrated providers. |
| Offshore Energy Corridor Expansion | Gulf Coast and North Sea fixed-platform contracts command premium day-rates with multi-year tenors. |
Research Methodology
Document review covered FAA Part 135 operational specifications, EASA medical aircraft certification directives, and CMS reimbursement frameworks, complemented by interviews with aeromedical base operations directors, hospital procurement committee chairs, flight nurse training program administrators, and GPO contracts managers. Secondary validation drew from FDA 510(k) device clearance databases, EASA airworthiness directives, and hospital network exclusive panel agreements. Bottom-up fleet deployment modeling triangulated against top-down hospital network contracting value analysis.
Market size outputs reflect installed base projections across rotary-wing trauma response, fixed-wing international evacuation, and hospital-contracted telemetry-enabled fleets, segmented by service type, end user institutional category, fuel propulsion architecture, and technology integration tier. CAGRs were derived from patient volume elasticity to rural hospital closure rates and demonstrated time-to-tertiary-care outcome metrics. Forecast inputs incorporated pilot training pipeline throughput constraints and EASA EU AI Act compliance timeline assumptions.
Revisions become necessary when FAA instrument rating certification backlogs worsen, jet fuel price volatility exceeds hedging program coverage, or CMS reimbursement shifts from per-flight to outcome-based models materialize. Deviation in hospital network consolidation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
Air Ambulance Services Market
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
US Urgent Care Centers Market
Emergency Medical Services
Global Ambulance Stretchers Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
Emergency Medical Supplies Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
Chest Compressors Market
Emergency Medical Services
Emergency Medical Services Market
Emergency Medical Services
Cardiopulmonary Resuscitation Market
Emergency Medical Services
Adrenal Crisis Management Market
Emergency Medical Services
First Aid Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
North America Ambulance Services Market