
 Global Laboratory Equipment and Disposables Market | 2026-2036
Global Laboratory Equipment and Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laboratory Equipment and Disposables Market Foresight
EU MDR is repositioning the cost-of-entry calculus for analytical instrument suppliers serving European pharmaceutical quality control facilities. Thermo Fisher Scientific leverages its captive supply of chromatography consumables to sustain margin pools across diagnostic and bioproduction workflows. Danaher Corporation anchors its competitive position through in-house production of precision filtration and separation technologies that dominate life science manufacturing plants.
Laboratory equipment and disposables encompass precision instruments and single-use materials engineered to tolerances of microliters and nanometers, manufactured through injection molding, precision machining, and sterile cleanroom assembly for experimental reproducibility and contamination control in regulated environments. Spectrophotometers and chromatography systems occupy the highest capital intensity tier within product type segmentation, while consumables generate recurring revenue streams that stabilize vendor cash flows across economic cycles. Biotechnology and pharmaceutical analysis applications command premium pricing due to GMP validation requirements, whereas academic testing segments compete on procurement cost and instrument versatility.
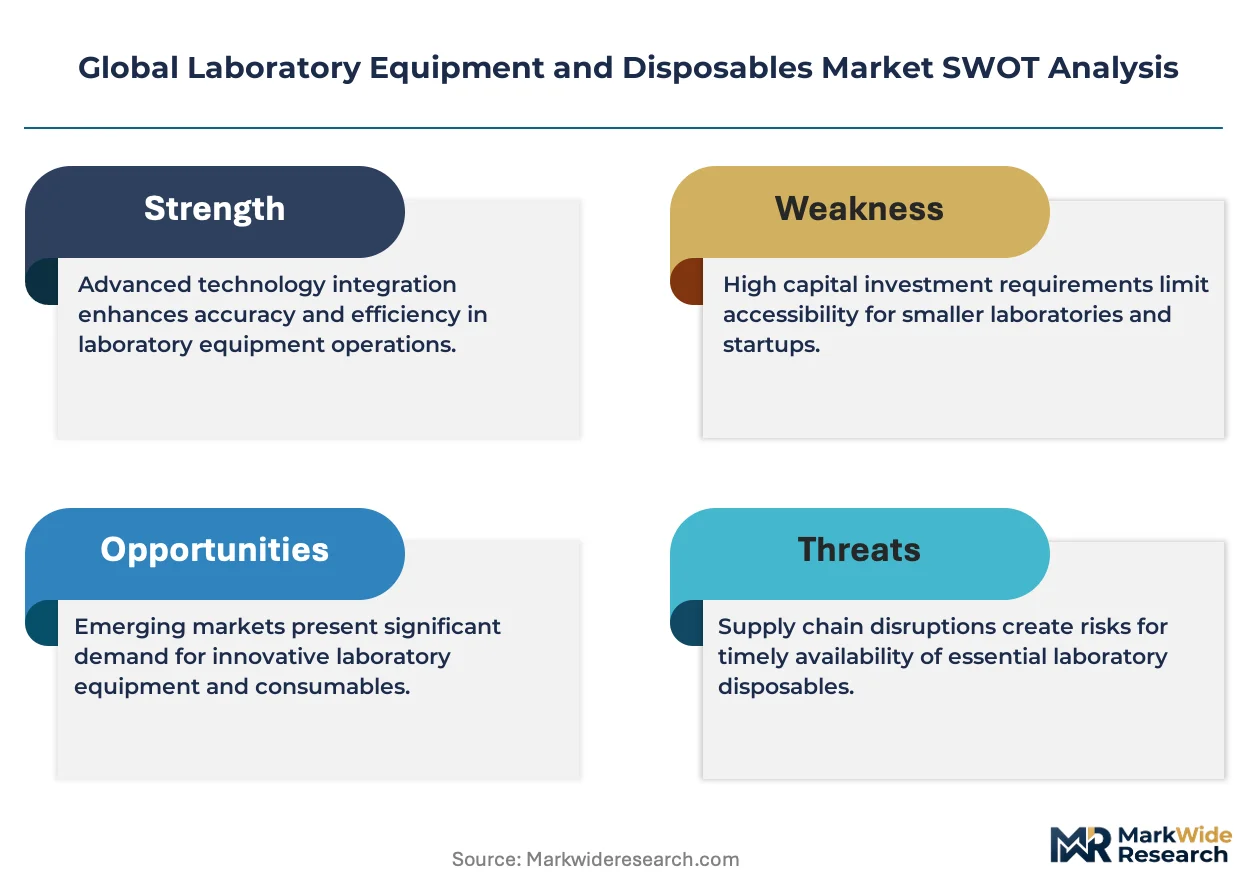
FDA 21 CFR Part 11, EU MDR, and ISO 13485 collectively shape equipment qualification protocols, electronic record integrity standards, and quality management system mandates that determine market access for suppliers across the United States, European Union, and international export markets. China's NMPA and Japan's PMDA impose parallel but non-identical conformity assessment pathways that fragment certification costs for manufacturers seeking multi-regional placement. Stakeholders must monitor divergence between FDA digital validation guidance and EU AI Act risk classification for automated analytical systems as these frameworks mature and potentially reshape competitive compliance burdens.
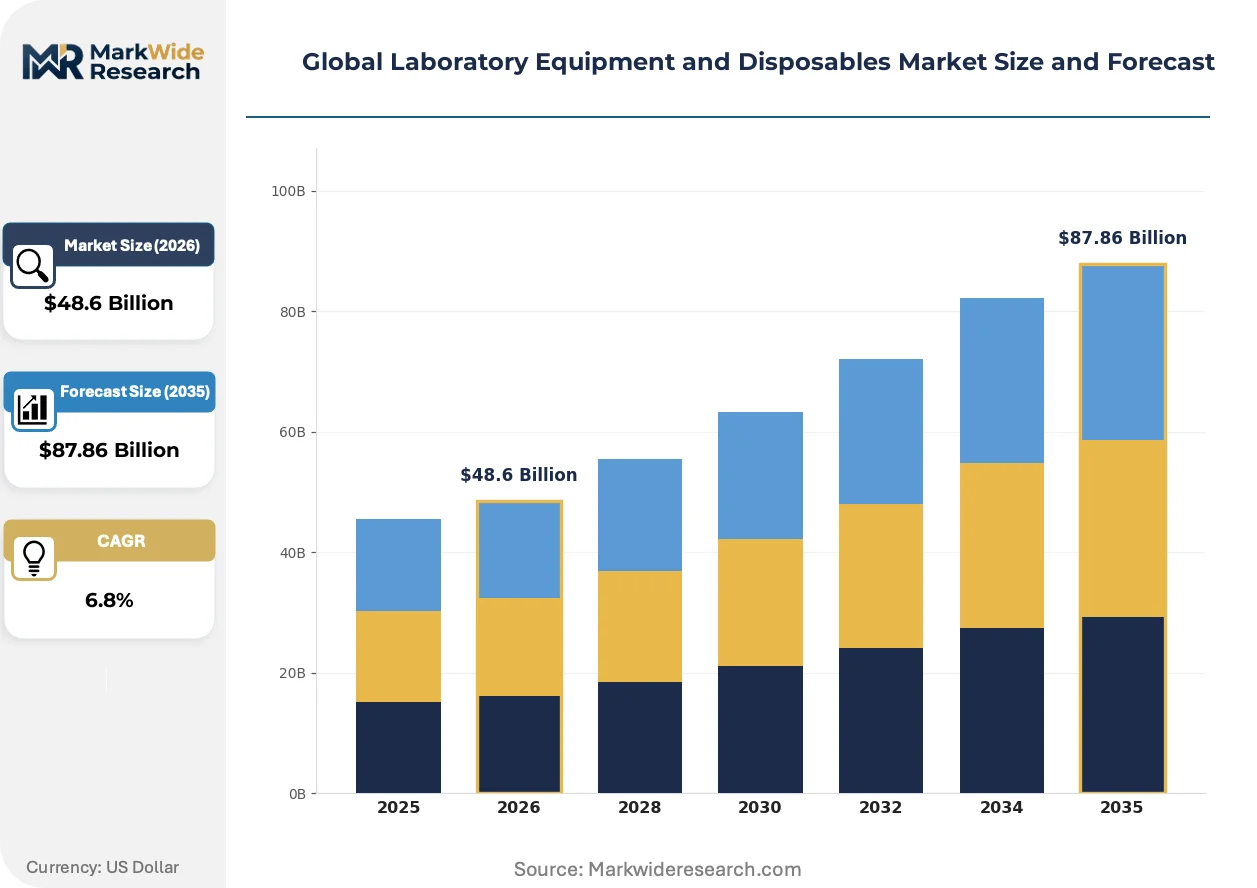
Market Dynamics
Automated liquid handling systems are compressing manual pipetting workflows across pharmaceutical quality control facilities, forcing equipment suppliers to embed software validation capabilities that satisfy FDA 21 CFR Part 11 and EU MDR traceability mandates.
Growth Catalysts
- EU MDR compliance deadlines:Pharmaceutical manufacturers in Germany and France are accelerating equipment replacement cycles to meet validation documentation requirements for analytical instruments.
- Biopharma manufacturing clusters:Capital expenditure on GMP-compliant infrastructure is deepening in the United States, China, and Germany as cell therapy production scales.
- Single-use technologies:Pre-sterilized disposable components are eliminating cleaning validation burdens in multi-product bioprocessing facilities.
Market Restraints
- Specialized polymer supply concentration:Medical-grade polypropylene and fluoropolymers for precision consumables depend on concentrated petrochemical feedstock suppliers in the US Gulf Coast and Middle East.
- Extended equipment qualification timelines:FDA 21 CFR Part 11 software validation and EU MDR technical documentation requirements stretch procurement cycles from months to years.
- Optical component import dependency:Spectrophotometer and chromatography detector manufacturers rely on precision gratings and lasers from limited Japanese and German suppliers.
Strategic Opportunities
- India's CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore are importing automated systems to serve export markets under US FDA and EU MDR standards.
- AI-integrated analytical platforms:Convergence of machine learning algorithms with chromatography data systems is enabling real-time impurity detection in continuous manufacturing.
- China's NMPA harmonization:Streamlined medical device registration pathways are reducing market entry friction for qualified foreign equipment suppliers.
Industry Challenges
- Cross-functional validation expertise:Biopharma manufacturers face acute shortages of professionals combining GMP compliance knowledge with software quality assurance skills.
- Legacy system integration:Automated liquid handlers must interface with 15-20 year-old laboratory information management systems lacking modern API architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laboratory Equipment and Disposables Market |
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $87.86 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microscopes, Centrifuges, Spectrophotometers, Autoclaves, Pipettes, Consumables Application: Clinical Research, Biotechnology, Pharmaceutical Analysis, Environmental Testing, Food Safety, Academic Testing End User: Diagnostic Centers, Contract Research Organizations, Academic Institutions, Government Labs, Manufacturing Plants, Quality Control Facilities Distribution Channel: Direct Sales, Online Retailers, Distributors, Specialty Dealers, E-commerce Platforms, Value-added Resellers |
| Companies Covered | Waters Corporation, PerkinElmer, Thermo Fisher Scientific, Sartorius AG, Merck KGaA, Danaher Corporation, Bruker Corporation, Bio-Rad Laboratories, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laboratory Equipment and Disposables Market Shifts & Advancements
Digital validation architectures and miniaturized detection technologies are restructuring how analytical laboratories configure capital equipment and consumable procurement.
Acoustic droplet ejection technology is electrifying non-contact liquid transfer workflows in high-throughput screening operations. Pharmaceutical discovery groups at contract research organizations are adopting these systems to eliminate cross-contamination risks in compound library management. The technology is electrifying competitive positioning by enabling nanoliter-scale dispensing precision that manual pipetting cannot replicate.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of hydrophobic coatings used in pipette tips and microplates. Equipment manufacturers must qualify alternative surface chemistries that maintain liquid handling accuracy without fluoropolymer additives. Chromatography consumables suppliers serving European pharmaceutical quality control facilities face the steepest revalidation burden.
Consolidated procurement through group purchasing organizations is compressing vendor margins on capital equipment while elevating consumables contract terms as negotiation leverage. Academic medical centers and mid-sized biotechs are migrating toward multi-year bundled agreements that wrap service, validation support, and disposables into single-source relationships. This pattern is most visible in the United States, where hospital system consolidation has concentrated buying power among fewer procurement decision-makers.
Global Laboratory Equipment and Disposables Market Segmentation
Segmentation in laboratory equipment and disposables reveals divergent margin architectures across precision instruments versus recurring consumables, with regulatory compliance intensity varying sharply between pharmaceutical manufacturing and academic research end-uses.
Product Type:
Volume concentrates in single-use consumables while premium pricing accrues to capital-intensive analytical instruments requiring extensive qualification documentation.
- Consumables:Single-use pipette tips, microplates, and chromatography vials manufactured from medical-grade polypropylene under ISO 13485 protocols. Demand clusters in United States and German biopharma manufacturing plants where pre-sterilized disposables eliminate cleaning validation burdens for multi-product facilities.
- Spectrophotometers:UV-Vis and fluorescence detection systems requiring precision optical gratings and stabilized laser sources. German and Japanese pharmaceutical quality control facilities drive procurement as EU MDR technical documentation requirements extend replacement cycles.
- Microscopes:Optical and electron microscopy systems for cellular imaging applications.
- Centrifuges:Refrigerated and high-speed separation equipment for sample preparation workflows.
- Autoclaves:Steam sterilization systems for reusable glassware and media preparation.
- Pipettes:Manual and electronic liquid handling instruments spanning research to GMP environments.
Today's leader: Consumables. Tomorrow's challenger: Spectrophotometers as AI-integrated detection platforms gain regulatory traction.
Application:
Margin differentiation follows validation burden intensity, with GMP-compliant applications commanding three-tier pricing separation from cost-sensitive academic segments.
- Pharmaceutical Analysis:Quality control and release testing workflows subject to FDA 21 CFR Part 11 and EU MDR traceability mandates. United States and German facilities concentrate capital expenditure on automated liquid handling systems with embedded software validation architectures.
- Biotechnology:Cell therapy and bioproduction process analytics requiring continuous monitoring capabilities. Chinese manufacturing clusters in Suzhou and Shanghai are expanding procurement of single-use sensor technologies under NMPA harmonization pathways.
- Clinical Research:Diagnostic assay development and clinical trial sample management.
- Environmental Testing:Regulatory compliance monitoring for water and air quality parameters.
- Food Safety:Pathogen detection and contaminant screening for supply chain verification.
- Academic Testing:Fundamental research applications competing on instrument versatility and procurement cost.
Pharmaceutical Analysis captures the steepest margin premiums. Biotechnology represents the fastest volume expansion as cell therapy manufacturing scales.
End User:
Procurement authority concentrates in integrated manufacturing networks while fragmented academic purchasing limits vendor pricing power.
- Manufacturing Plants:Biopharma production facilities requiring GMP-validated equipment with complete IQ/OQ/PQ documentation. United States, German, and Chinese cell therapy producers anchor demand for closed-system processing technologies.
- Contract Research Organizations:Outsourced discovery and development services competing on throughput and regulatory compliance credentials. Indian CDMOs in Hyderabad and Bangalore are importing automated systems to serve export markets under US FDA and EU MDR standards.
- Diagnostic Centers:Clinical laboratory networks processing patient samples under accreditation requirements.
- Academic Institutions:University research laboratories with constrained capital budgets and extended replacement cycles.
- Government Labs:National research facilities and regulatory reference laboratories.
- Quality Control Facilities:Standalone analytical service providers supporting manufacturing compliance.
Manufacturing Plants dictate premium equipment specifications. Contract Research Organizations are gaining procurement influence through consolidated outsourcing trends.
Distribution Channel:
Channel selection reflects equipment complexity, with capital instruments requiring validation support while consumables migrate toward digital procurement platforms.
- Direct Sales:Manufacturer-led engagement for spectrophotometers and chromatography systems requiring installation qualification and application training. Thermo Fisher Scientific and Danaher Corporation deploy field service organizations across United States, German, and Chinese biopharma clusters.
- Distributors:Regional inventory and logistics networks spanning mid-sized laboratories with standardized equipment needs. European distributors face margin compression as REACH restrictions on fluoropolymer coatings force consumables reformulation and revalidation costs.
- Online Retailers:Digital procurement platforms for standard laboratory supplies and replacement parts.
- Specialty Dealers:Niche providers serving specific analytical techniques or geographic markets.
- E-commerce Platforms:Aggregated marketplaces for consumables with transparent pricing and rapid fulfillment.
- Value-added Resellers:Systems integrators combining hardware with custom software and validation documentation.
Direct Sales dominates capital equipment placement. E-commerce Platforms are capturing consumables volume through consolidated procurement contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized validation engineers and GMP compliance specialists concentrate in pharmaceutical manufacturing corridors across the United States, Germany, and China, anchoring equipment procurement authority within these talent-dense clusters.
United States
FDA 21 CFR Part 11 validation requirements and cell therapy manufacturing expansion drive equipment procurement in Greater Boston and the San Francisco Bay Area. Biopharma manufacturers in these clusters prioritize automated liquid handling systems with embedded software qualification architectures. Massachusetts and California anchor demand for GMP-compliant infrastructure as gene therapy production scales.
Germany
EU MDR technical documentation mandates and REACH fluoropolymer restrictions are compressing equipment replacement cycles in pharmaceutical quality control facilities. The country's national pharmaceutical regulator enforces stringent qualification protocols for analytical instruments. Bavaria and Baden-Württemberg concentrate chromatography system deployment as manufacturers revalidate surface chemistries for consumables.
China
NMPA harmonization pathways and bioproduction capacity expansion are accelerating import of automated analytical platforms. Suzhou and Shanghai manufacturing clusters scale single-use sensor technologies for cell therapy process analytics. The national medical products administration streamlines registration for qualified foreign equipment suppliers serving domestic biopharma producers.
India
CDSCO export compliance requirements and contract manufacturing growth are driving automated system imports in Hyderabad and Bangalore. CDMOs in these cities deploy GMP-validated equipment to serve US FDA and EU MDR-regulated markets. The national pharmaceutical regulator's alignment with international standards enables contract research organizations to compete on regulatory credentials.
Japan
PMDA conformity assessment pathways and precision optical component manufacturing anchor spectrophotometer demand in the Kanto and Kansai regions. Tokyo and Osaka pharmaceutical quality control facilities drive procurement of detection systems requiring Japanese-sourced gratings and laser sources. The national regulator maintains parallel but non-identical certification requirements that fragment multi-regional market entry costs.
Global Laboratory Equipment and Disposables Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment and consumables segments, creating a tiered market structure where scale-driven portfolios face pressure from niche validation expertise. Consolidated procurement through group purchasing organizations compresses margins on capital instruments while elevating consumables contract terms as negotiation leverage. Three archetypes dominate: full-service analytical platform providers, precision consumables specialists, and systems integrators bundling hardware with validation documentation. Strategic moves center on backward integration into polymer supply chains and geographic expansion into India's CDMO corridor.
Among diversified analytical platform providers, Thermo Fisher Scientific and Danaher Corporation occupy positions exemplifying scale-driven portfolio breadth, while Sartorius AG represents the focused pure-play archetype specializing in filtration and separation technologies. These three entities anchor competitive dynamics across GMP-compliant manufacturing segments where validation documentation capabilities determine procurement outcomes. Their collective positioning illustrates how captive supply of consumables stabilizes cash flow cycles against capital equipment revenue volatility.
| Leading Market Players |
|---|
| Waters Corporation |
| PerkinElmer |
| Thermo Fisher Scientific |
| Sartorius AG |
| Merck KGaA |
| Danaher Corporation |
| Bruker Corporation |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Others |
Supply & Pricing Matrix
Medical-grade polypropylene resin indices cascade through three distinct pricing tiers as raw material volatility concentrates margin pressure on consumables manufacturers serving EU MDR-regulated facilities. REACH fluoropolymer restrictions compound input cost uncertainty, forcing reformulation investments that stratify vendor pricing power across German pharmaceutical quality control clusters.
Pricing Analysis
Bundled service contracts versus unbundled equipment-only procurement separates premium-tier vendors from commodity competitors. Three-tier pricing structure across premium, standard, and economy levels reflects validation documentation intensity, with GMP-compliant manufacturing plants showing lowest price sensitivity and academic testing segments driving hardest negotiation. Cost compression in standard-tier consumables intensifies as group purchasing organizations consolidate procurement leverage across United States hospital systems. Price differentiation hinges on embedded software qualification capabilities and multi-year validation support terms.
Supply Chain Analysis
China's NMPA domestic-content preferences and India's PLI scheme for medical devices are reshaping sourcing patterns for precision optical components and polymer feedstocks. Manufacturing concentrates in Germany, Japan, and the United States for spectrophotometer gratings and stabilized laser sources, while medical-grade polypropylene production anchors in the US Gulf Coast and Middle East petrochemical corridors. Single-source vulnerability around fluoropolymer additives exposes European consumables suppliers to REACH regulatory disruption. Distribution runs through direct sales for capital equipment requiring IQ/OQ/PQ documentation, with e-commerce platforms capturing standardized consumables volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as pharmaceutical manufacturers prioritize GMP-validated automation over cost-optimized alternatives. Cell therapy manufacturing expansion in Massachusetts and California clusters anchors demand-shift toward premium specifications with complete software validation architectures.
For Market Incumbents: To counter margin compression from consolidated procurement through group purchasing organizations, deepen backward integration into medical-grade polymer compounding and expand captive supply of chromatography consumables. Anchor competitive position through in-house production of precision filtration membranes that dominate bioproduction workflows. Prioritize certification investment in EU MDR technical documentation capabilities to extend replacement cycle capture. For New Entrants and Emerging Players: CDSCO alignment with US FDA standards in India opens a window for automated liquid handling system penetration among Hyderabad and Bangalore CDMOs serving export markets. Target contract research organizations with validation documentation gaps as the most penetrable segment. Pursue value-added reseller partnerships bundling hardware with custom software qualification packages. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional distributors face REACH reformulation costs without scale to absorb revalidation burdens. Five-to-ten-year viability favors pure-play consumables specialists with ISO 13485 manufacturing depth and recurring revenue stability. Watch NMPA harmonization pace as inflection indicator for Chinese market entry friction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of medical-grade polypropylene insulates margin pools from Gulf Coast feedstock volatility. |
| Software Validation Architecture Development | FDA 21 CFR Part 11-compliant data systems differentiate capital equipment placement in GMP facilities. |
| CDMO Partnership Expansion | Indian contract manufacturers under CDSCO oversight import automated platforms for US FDA-regulated exports. |
| Alternative Surface Chemistry Qualification | REACH-compliant hydrophobic coatings replace fluoropolymers in pipette tips without sacrificing accuracy. |
| Group Purchasing Organization Contracting | Multi-year bundled agreements wrap service, validation support, and disposables into single-source relationships. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with GMP compliance officers, laboratory procurement managers, biomedical engineers, and aftermarket service directors with secondary validation against FDA 510(k) filings, EMA technical documentation databases, ISO 13485 audit records, and NMPA registration pathways. Bottom-up equipment shipment analysis and top-down pharmaceutical capital expenditure triangulation anchored volume estimates.
Segment-weighting applied product type, application intensity, end-user procurement authority, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from equipment replacement cycle modeling, consumables attach-rate analysis, and biopharma manufacturing capacity expansion tracking. Forecast inputs incorporated EU MDR compliance deadline phasing and cell therapy production scale trajectories.
Revisions become necessary when REACH restriction scope expands, NMPA harmonization reverses, or fluoropolymer supply disruption materializes beyond current contingency planning. Forecasts reflect documented assumptions about regulatory stability and polymer feedstock availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Global Hematology Instruments and Reagents Market
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Global Laboratory Grinders Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Portable Hemoglobin Analyzer Market
Laboratory Equipment
Global Laboratory Hoods and Enclosure Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Blood Volume Analyzer Market