
 Annuloplasty System Market | 2026-2036
Annuloplasty System Market Size, Share, and Industry Trends Forecast 2026-2036
Annuloplasty System Market Outlook
Hospital procurement consortiums is reshaping how annuloplasty systems reach surgical suites across integrated delivery networks. Medtronic leverages its broad cardiovascular portfolio to sustain deep relationships with cardiac surgery departments. Edwards Lifesciences Corporation anchors its position through specialized expertise in transcatheter mitral technologies. Abbott competes by extending its structural heart footprint into emerging valve repair segments.
An annuloplasty system comprises implantable devices designed to restore or reinforce the annular geometry of diseased heart valves, typically fabricated from biocompatible metals, biological tissues, or synthetic polymers and delivered via open surgical or transcatheter approaches to correct regurgitation. These systems functionally reduce annular dilatation and improve coaptation in patients with degenerative or functional valve insufficiency. Annular rings and surgical repair devices command established revenue streams due to decades of clinical validation and surgeon familiarity. Transcatheter valves and hybrid systems represent the fastest-expanding technology categories as minimally invasive procedures displace conventional sternotomy in eligible patient populations.
The FDA governs annuloplasty devices through the premarket approval and de novo pathways, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for CE marking of implantable cardiovascular products. ISO 13485 quality management standards and ASTM material specifications further constrain design validation and biocompatibility testing protocols. Stakeholders must monitor how evolving reimbursement determinations for transcatheter procedures reshape investment priorities across product development pipelines.
Market Dynamics
Transcatheter delivery platforms are compressing the addressable patient pool for conventional surgical annuloplasty, forcing manufacturers to recalibrate R&D budgets toward minimally invasive architectures while defending installed bases in open-heart centers.
Growth Catalysts
- FDA De Novo Pathway:Streamlined premarket review for novel transcatheter repair devices accelerates commercialization timelines for breakthrough annuloplasty technologies.
- Structural Heart Program Expansion:Tertiary cardiac centers in the United States are building dedicated valve repair capabilities, creating concentrated demand for hybrid surgical-transcatheter systems.
- Aging Demographics:Degenerative mitral valve disease prevalence rises sharply among patients over 75, expanding the eligible population for annuloplasty interventions.
Market Restraints
- Platinum-Iridium Alloy Costs:Volatility in precious metal prices for radiopaque marker bands compresses gross margins on implantable ring systems.
- EU MDR Clinical Evidence Burden:Strengthened post-market surveillance requirements for CE marking extend validation timelines and inflate regulatory compliance expenditures.
- Transcatheter Valve Substitution:Percutaneous mitral valve replacement systems capture functional regurgitation cases previously routed to repair, constraining annuloplasty volume growth.
Strategic Opportunities
- Japan's Super-Aged Society:PMDA's priority review designation for geriatric cardiovascular devices creates expedited access for annuloplasty innovations targeting patients over 80.
- India's PLI Scheme:Production-linked incentives for medical device manufacturing attract capital toward domestic assembly of surgical repair rings.
- Digital Surgical Planning Convergence:Integration of preoperative CT modeling with 3D-printed sizing tools enables patient-specific annuloplasty selection, differentiating premium system offerings.
Industry Challenges
- Interventional Imaging Specialist Scarcity:Transcatheter annuloplasty deployment demands echocardiographers with advanced 3D guidance proficiency, creating procedural throughput bottlenecks.
- ISO 13485 Certification Complexity:Quality management system audits for multi-site manufacturing networks impose 18-24 month compliance timelines for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Annuloplasty System Market |
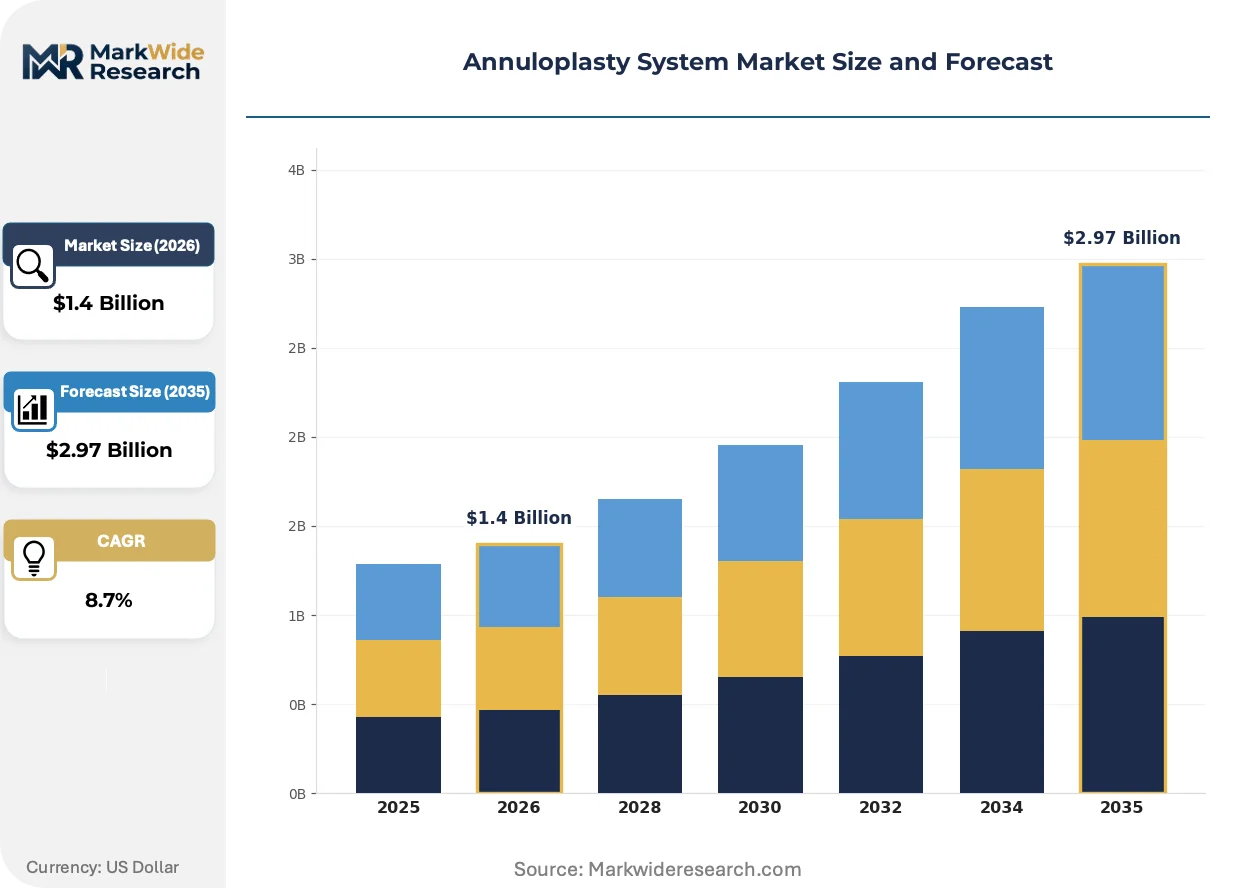
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transcatheter Valves, Surgical Repair Devices, Annular Rings, Support Technologies End User: Cardiac Hospitals, Specialty Clinics, Research Laboratories, Healthcare Systems Application: Mitral Valve Repair, Tricuspid Valve Repair, Aortic Regurgitation, Heart Valve Replacement Technology: Mechanical Devices, Biological Prostheses, Hybrid Systems, 3D-Printed Solutions |
| Companies Covered | Corcym, Affluent Medical, Medtronic, Braile Biomédica, Valcare Medical, Edwards Lifesciences Corporation, Boston Scientific Corporation, Labcor Laboratories Ltda, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Annuloplasty System Market Strategic Shifts
Computational modeling and real-time intraoperative feedback systems are redefining how surgeons select and deploy annuloplasty devices, shifting competitive advantage toward data-integrated platform ecosystems.
Shape-memory nitinol annuloplasty rings with integrated strain sensors are digitizing intraoperative annular tension mapping. Cardiac surgery departments at academic medical centers are piloting these systems to quantify repair durability predictions. The technology is digitizing subjective surgeon tactile assessment into reproducible biomechanical parameters that feed predictive algorithms.
The EU Medical Device Regulation's post-market clinical follow-up requirements are mandating decade-long implant registries for cardiovascular devices. Manufacturers must now architect data infrastructure capable of capturing real-world performance metrics across distributed hospital networks. High-volume mitral repair centers in Germany and the Netherlands are negotiating preferred vendor status in exchange for structured outcomes data contribution.
Hospital procurement consortiums are consolidating annuloplasty system purchasing across integrated delivery networks, displacing individual surgeon preference as the dominant selection criterion. Value analysis committees now evaluate total episode cost rather than device price alone. This behavioral shift is most pronounced in United States multi-hospital systems where catheterization lab throughput metrics determine contract awards.
Annuloplasty System Market Segmentation
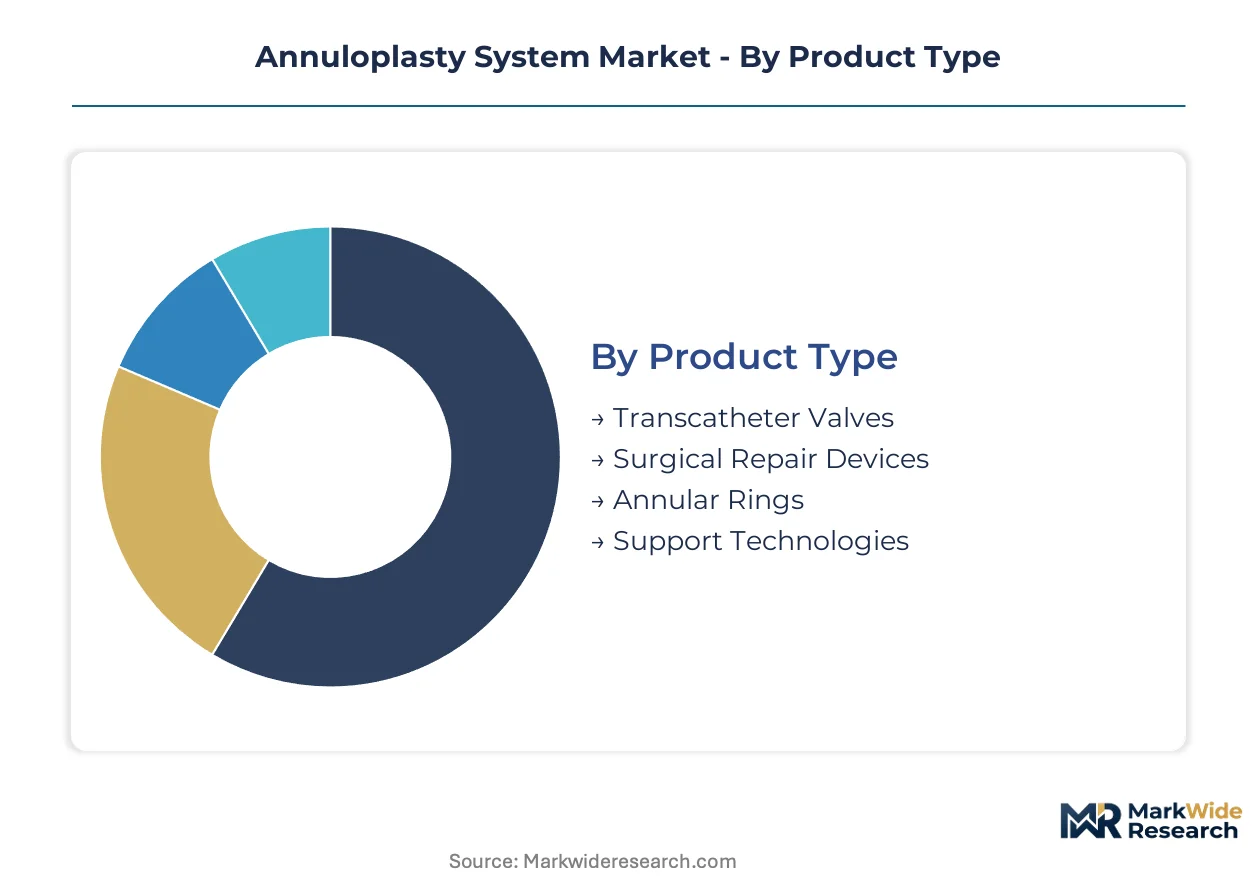
Annuloplasty system manufacturers must align product architectures with distinct clinical workflows and procurement hierarchies. Each segmentation dimension reveals divergent margin structures, regulatory pathways, and customer concentration patterns that reshape commercial strategy.
Product Type:
Cost tier stratification across implantable categories determines R&D allocation and manufacturing footprint decisions.
- Transcatheter Valves:Self-expanding nitinol frames with pericardial leaflets deploy via transfemoral access. Tertiary cardiac centers in the United States prioritize these systems to reduce ICU length-of-stay and accelerate catheterization lab turnover.
- Surgical Repair Devices:Rigid or flexible annuloplasty rings secured with interrupted sutures dominate open-heart procedures. Established revenue streams persist where sternotomy remains clinically indicated for complex degenerative pathologies.
- Annular Rings:Partial or complete bands fabricated from polyester fabric over silicone or metal cores reinforce native valve geometry. Decades of surgeon familiarity sustain procurement volume across hybrid surgical programs.
- Support Technologies:Sizing instruments, chordal replacement kits, and intraoperative imaging adjuncts complete procedural ecosystems. These ancillaries generate recurring revenue tied to implantable device utilization rates.
Surgical Repair Devices hold installed capacity. Transcatheter Valves is rotating up the share rankings.
End User:
Customer type concentration shapes contract negotiation leverage and service bundling requirements across procurement channels.
- Cardiac Hospitals:High-volume structural heart programs with dedicated valve teams drive system standardization. These institutions negotiate enterprise pricing across catheterization lab and surgical suites simultaneously.
- Specialty Clinics:Outpatient-focused centers concentrate on diagnostic workup and patient selection for referral. Their procurement influence operates through physician preference cards rather than formal value analysis committees.
- Research Laboratories:Academic medical centers with NIH-funded cardiovascular engineering programs source preclinical evaluation units. Early access agreements with manufacturers shape subsequent clinical adoption trajectories.
- Healthcare Systems:Integrated delivery networks consolidate purchasing across 10-50 affiliated facilities. Their value analysis committees evaluate total episode cost including readmission risk rather than device price alone.
Healthcare Systems concentrates procurement volume. Specialty Clinics is gaining influence through ambulatory surgery migration.
Application:
Anatomical target selection determines regulatory trial design, reimbursement coding, and competitive positioning against alternative interventions.
- Mitral Valve Repair:Annuloplasty rings and transcatheter edge-to-edge devices address degenerative and functional regurgitation. The FDA's breakthrough device designation pathway accelerates review for novel repair technologies in this indication.
- Tricuspid Valve Repair:Transcatheter coaptation devices and annuloplasty systems target an undertreated patient population. European registries in Germany and the Netherlands generate real-world evidence supporting expanded indications.
- Aortic Regurgitation:Surgical aortic valve repair with annuloplasty stabilization remains niche against replacement dominance. Specialized centers in Japan and Switzerland maintain expertise for young patients seeking valve-sparing alternatives.
- Heart Valve Replacement:Mechanical and tissue prostheses supplant repair when annular destruction or calcification precludes reconstruction. Transcatheter delivery platforms are displacing surgical replacement in intermediate-risk patients.
Mitral Valve Repair commands procedural volume. Tricuspid Valve Repair is climbing the fastest as device innovation unlocks previously ineligible patients.
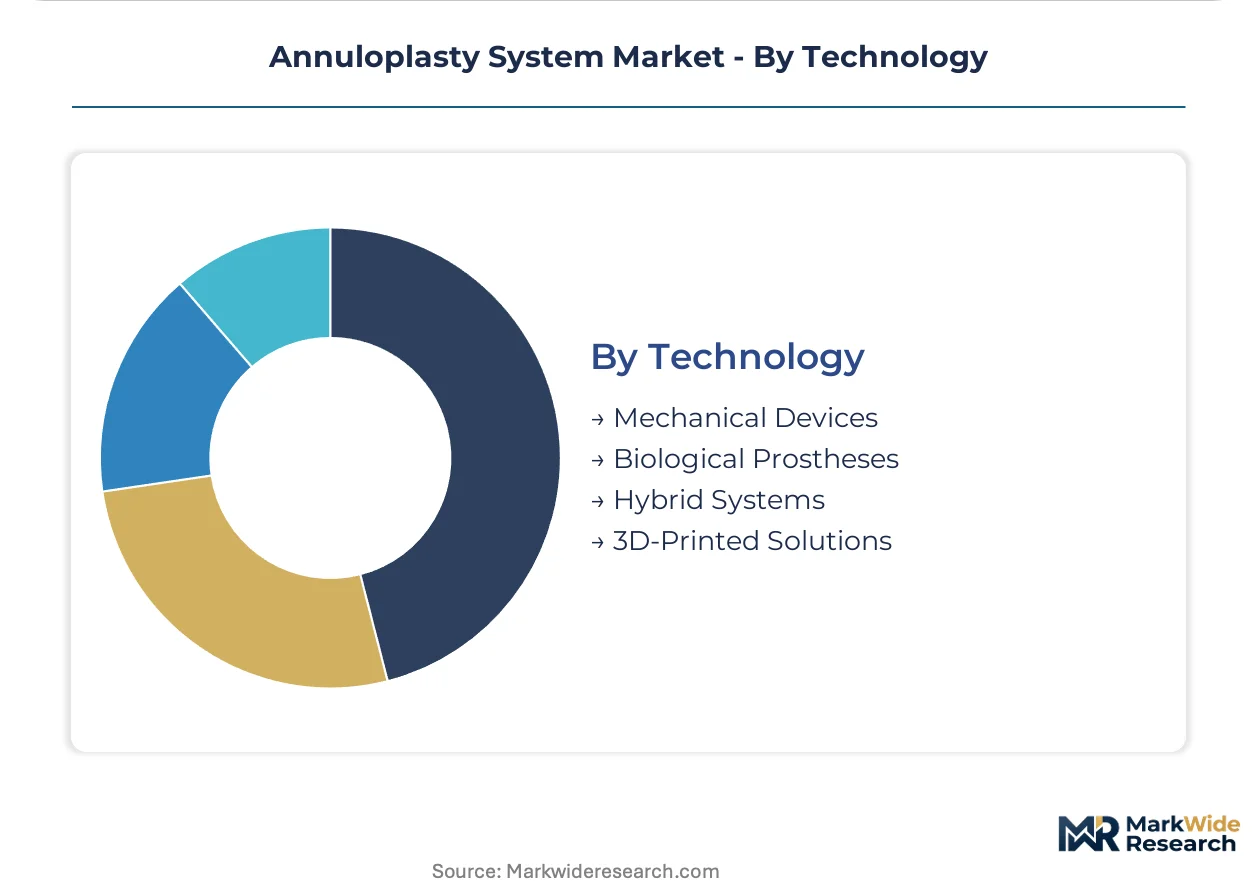
Technology:
Material science and manufacturing maturity differentiate premium positioning from commodity competition.
- Mechanical Devices:Rigid titanium or cobalt-chromium rings with polyester fabric sewing cuffs provide durable annular stabilization. Long-term implant registries in Sweden and the United Kingdom validate 15-20 year durability profiles.
- Biological Prostheses:Glutaraldehyde-fixed bovine or porcine pericardium mounted on flexible frames enables adaptive annular motion. These systems appeal to patients seeking anticoagulation-sparing alternatives to mechanical valves.
- Hybrid Systems:Transcatheter delivery of surgical-grade repair components bridges open and percutaneous approaches. PMDA priority review in Japan accelerates commercialization for super-aged patient cohorts.
- 3D-Printed Solutions:Patient-specific annuloplasty rings fabricated from biocompatible polymers enable geometric customization. Academic medical centers in the United States and Belgium pilot these systems for complex reoperative cases.
Mechanical Devices anchors revenue stability. Hybrid Systems is expanding most quickly through minimally invasive program adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic's cardiovascular surgical corridor anchors United States demand for annuloplasty systems, with its transcatheter program serving as a training hub for midwestern cardiac centers. Germany's Duisburg-Ruhr industrial belt supplies precision-forged nitinol components to European device manufacturers. Japan's Kobe-Akashi medical device cluster accelerates PMDA review cycles through embedded regulatory consultation.
United States
Tertiary cardiac centers in Cleveland, Houston, and New York City deploy hybrid surgical-transcatheter systems at scale. The FDA's breakthrough device designation pathway compresses premarket review timelines for novel repair technologies. The Texas Medical Center in Houston hosts the highest procedural volume for mitral valve repair in the western hemisphere.
Germany
University hospitals in Heidelberg and Leipzig generate real-world evidence registries that satisfy EU MDR post-market surveillance mandates. The national reimbursement authority maintains distinct procedure codes for transcatheter annuloplasty, preserving physician autonomy in device selection. The Stuttgart-Tübingen corridor concentrates precision metalworking capacity for nitinol frame fabrication.
Japan
Super-aged patient cohorts in Osaka and Fukuoka drive demand for minimally invasive alternatives to sternotomy. PMDA's priority review designation for geriatric cardiovascular devices accelerates commercialization timelines. The Kobe-Akashi medical device cluster integrates regulatory consultation into product development workflows.
India
Domestic assembly of surgical repair rings expands through production-linked incentives in Gujarat and Karnataka. CDSCO's streamlined import licensing for cardiovascular implants reduces clearance delays at Mumbai and Chennai ports. The Andhra Pradesh MedTech Zone near Visakhapatnam attracts contract manufacturing for polyester sewing cuff components.
Switzerland
Specialized aortic valve repair centers in Zurich and Geneva maintain expertise for young patients seeking valve-sparing alternatives. Swissmedic's abbreviated review pathway for well-established device categories reduces time-to-market for iterative ring designs. The Basel-Lucerne corridor concentrates polymer engineering competence for biocompatible implant materials.
Annuloplasty System Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in materials and manufacturing. The vendor base stratifies between diversified cardiovascular conglomerates with catheterization lab footprints and focused ring manufacturers defending surgical installed bases. Three archetypes dominate: full-procedure platform owners, annular ring pure-plays, and transcatheter delivery innovators. Consolidation pressures concentrate on mid-scale European manufacturers lacking minimally invasive portfolios; strategic partnerships between nitinol suppliers and catheter platform developers accelerate.
Among diversified platform owners, Medtronic and Abbott anchor the structural heart tier through integrated catheterization lab and surgical suite relationships. Edwards Lifesciences Corporation occupies a position exemplifying specialized transcatheter expertise. Corcym represents the European pure-play archetype focused on surgical repair devices.
| Leading Market Players |
|---|
| Corcym |
| Affluent Medical |
| Medtronic |
| Braile Biomédica |
| Valcare Medical |
| Edwards Lifesciences Corporation |
| Boston Scientific Corporation |
| Labcor Laboratories Ltda |
| Abbott |
| Others |
Value Chain & Pricing Dynamics
The Duisburg-Ruhr freight corridor's volatile logistics costs compress margins on precision-forged nitinol components while amplifying price differentiation between integrated delivery networks and standalone cardiac centers. Supply concentration in German precision metalworking and Japanese polymer engineering creates tiered procurement leverage that rewards volume commitment with preferential unit economics.
Pricing Analysis
Volume-discount tiering structures dominate annuloplasty system procurement, with healthcare systems negotiating enterprise pricing across 10-50 affiliated facilities while standalone hospitals pay standard list rates. Price differentiation hinges on GPO contract scale and ISO 13485 certification tier, with FDA breakthrough-designated devices commanding modest premiums. Cost compression in surgical repair rings intensifies due to platinum-iridium alloy volatility, though transcatheter platforms retain pricing resilience. Integrated delivery networks exhibit lowest price sensitivity; specialty clinics and research laboratories face highest budget constraints.
Supply Chain Analysis
Upstream feedstock flows for nitinol shape-memory alloys concentrate in Germany, Japan, and the United States, with polyester fabric sewing cuffs sourcing from India's Andhra Pradesh MedTech Zone and silicone cores from Swiss polymer specialists. Raw material dependencies span nickel-titanium ingots, glutaraldehyde-fixed bovine pericardium, and radiopaque platinum-iridium marker bands. Single-source vulnerability in nitinol forging capacity threatens frame production continuity. Distribution runs through hospital procurement consortiums and GPO channels that consolidate purchasing across catheterization lab and surgical suite categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Annuloplasty system incumbents confront acute substitution pressure from percutaneous mitral valve replacement platforms that capture functional regurgitation cases previously routed to repair procedures.
For Market Incumbents: Insulate surgical installed bases through backward integration into nitinol forging capacity in Germany or Japan, securing supply continuity while capturing margin from precision component production. Deepen FDA breakthrough device pipeline investments to accelerate transcatheter repair timelines before substitution effects harden. Lock in exclusive data-sharing agreements with high-volume mitral repair centers to satisfy EU MDR post-market surveillance mandates and create switching costs. For New Entrants and Emerging Players: Build out tricuspid valve repair capabilities as the most penetrable anatomical segment, where device innovation unlocks previously ineligible patients and European registries generate reimbursable real-world evidence. Target India's production-linked incentive zones for domestic assembly of surgical repair rings, leveraging CDSCO's streamlined import licensing to establish cost-competitive manufacturing. Pursue PMDA priority review designation in Japan as the primary go-to-market accelerant for super-aged patient cohorts. For Investors and Strategic Acquirers: Nitinol component specialists with embedded regulatory consultation capabilities represent the highest-conviction acquisition archetype, offering upstream control over frame production and accelerated PMDA or FDA pathways. Long-term viability across the analysis window depends on manufacturers bridging open surgical and transcatheter architectures as hybrid procedures displace pure sternotomy. Watch transcatheter valve replacement penetration rates in functional regurgitation cases as the critical inflection signal for repair market erosion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket review timelines for novel transcatheter repair technologies competing against replacement platforms. |
| EU MDR Post-Market Clinical Follow-Up | Mandates decade-long implant registries that reshape data infrastructure investments across German and Dutch hospital networks. |
| Hospital System Partnership | Secures preferred vendor status through structured outcomes data contribution at high-volume mitral repair centers. |
| Software Companion Development | Integrates preoperative CT modeling with 3D-printed sizing tools to differentiate premium annuloplasty offerings. |
| Reimbursement Strategy | Navigates CMS and private payer determinations for transcatheter procedures that reshape investment priorities. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with cardiac surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) and PMA filings, EU MDR notified body submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up triangulation across product type and end-user segments converged with top-down macro validation against structural heart procedure registries.
Forecast inputs incorporated product type evolution, end-user procurement consolidation, application-specific regulatory trial design, and technology material science maturation across the projection horizon. Segmentation dimensions modeled include implant category, customer concentration pattern, anatomical target, and manufacturing maturity tier. CAGRs were derived from procedure volume trajectories, device ASP elasticity, and replacement-to-repair substitution dynamics informed by real-world evidence generation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or breakthrough device acceleration by diversified cardiovascular conglomerates would shift outcomes beyond modeled bounds. Cross-checking against hospital cath lab throughput metrics and GPO contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Smart Syringe Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
North America Medical Devices Market
Medical Devices
Artificial Disc Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Tinnitus Maskers Market
Medical Devices
Helium Free MRI Scanners Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Trocars Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Non-Invasive Brain Stimulation System Market
Medical Devices
Specimen Retrieval Market
Medical Devices
Liver-On-Chip Market
Medical Devices
US Wearable Medical Devices Market