
 Condylar Plate Fixation System Market | 2026-2036
Condylar Plate Fixation System Market Size, Share, and Industry Trends Forecast 2026-2036
Condylar Plate Fixation System Market Intelligence
The capability gap between capital-heavy integrated manufacturers and specialized component suppliers is redrawing competitive boundaries in orthopedic trauma. Zimmer Biomet leverages captive forging capacity to control titanium alloy sourcing costs across its condylar plate portfolio. Stryker anchors its position through dense trauma center contracts in North America and Western Europe. DePuy Synthes differentiates via proprietary screw-plate interface geometries that reduce construct failure rates in distal femur applications.
A condylar plate fixation system is an orthopedic implant comprising a contoured metal plate with screw holes positioned to align with the lateral aspect of the distal femur condyle, typically manufactured from titanium alloy or stainless steel through CNC machining and surface passivation to achieve biocompatibility per ISO 5832 standards; its primary purpose is to stabilize supracondylar and intercondylar fractures while permitting early joint mobilization. Locking plates command the dominant revenue share due to angular stability advantages in osteoporotic bone, while bioabsorbable polymer variants represent the fastest-expanding material segment as surgeons seek to eliminate secondary removal procedures. Trauma surgery applications generate the deepest margin pools because emergency settings prioritize reliability over price sensitivity and drive recurring instrument tray purchases.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations compel manufacturers to maintain exhaustive clinical evidence libraries for each plate-screw combination. ISO 13485 quality management certification functions as a baseline market access filter that excludes smaller forging houses from direct OEM relationships. Stakeholders must monitor evolving biodegradability standards for polymer-based plates and assess whether captive polymer synthesis capabilities warrant capital deployment.
Market Dynamics
Locking plate architectures are compressing the addressable market for conventional compression plating systems as trauma centers standardize on angular stability constructs for osteoporotic fracture populations.
Growth Catalysts
- EU MDR Technical Documentation:The expanded clinical evidence requirements for legacy plate-screw combinations are accelerating hospital procurement of next-generation systems with pre-validated biocompatibility dossiers per ISO 5832.
- Trauma Center Consolidation:United States health systems are centralizing orthopedic emergency services into designated Level I trauma hubs that standardize on locked construct protocols.
- Titanium Alloy Forging:Advances in near-net-shape forging of Ti-6Al-4V ELI are reducing raw material waste in plate blank production and compressing downstream machining cycles.
Market Restraints
- Sponge Titanium Price Volatility:Spot market fluctuations for aerospace-grade titanium sponge concentrate in Ukrainian and Russian supply corridors are pressuring input cost stability for forged plate blanks.
- MDR Notified Body Bottleneck:The contracted pool of EU MDR-designated conformity assessment bodies is extending certification timelines for new plate geometries beyond thirty-six months.
- Distal Femoral Nail Substitution:Intramedullary nail systems with poller screw augmentation are capturing intertrochanteric fracture volume previously assigned to lateral condylar plates.
Strategic Opportunities
- India Orthopedic Infrastructure:The country's PLI scheme for medical device manufacturing is attracting forging capacity investments to serve underserved trauma surgery networks in Maharashtra and Tamil Nadu.
- 3D-Printed Patient-Specific Plates:Convergence of electron beam melting with preoperative CT-based topological optimization is opening anatomically contoured plate segments for complex periarticular fractures.
- Bioabsorbable Polymer Mandates:France's ANSM guidance favoring implant removal reduction is creating reimbursement preference for magnesium-alloy and PLLA-based condylar constructs in pediatric populations.
Industry Challenges
- Orthopedic Trauma Surgeon Training:The specialized skill set for minimally invasive plate osteosynthesis through submuscular approaches is concentrating in academic medical centers and creating access disparities.
- Instrument Tray Capital Burden:Each new plate-screw system requires dedicated sterilizable instrument sets that strain hospital capital budgets and storage capacity.
- Legacy System Interoperability:Proprietary screw head geometries from established manufacturers block cross-compatibility with third-party locking mechanisms, complicating surgeon preference card standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Condylar Plate Fixation System Market |
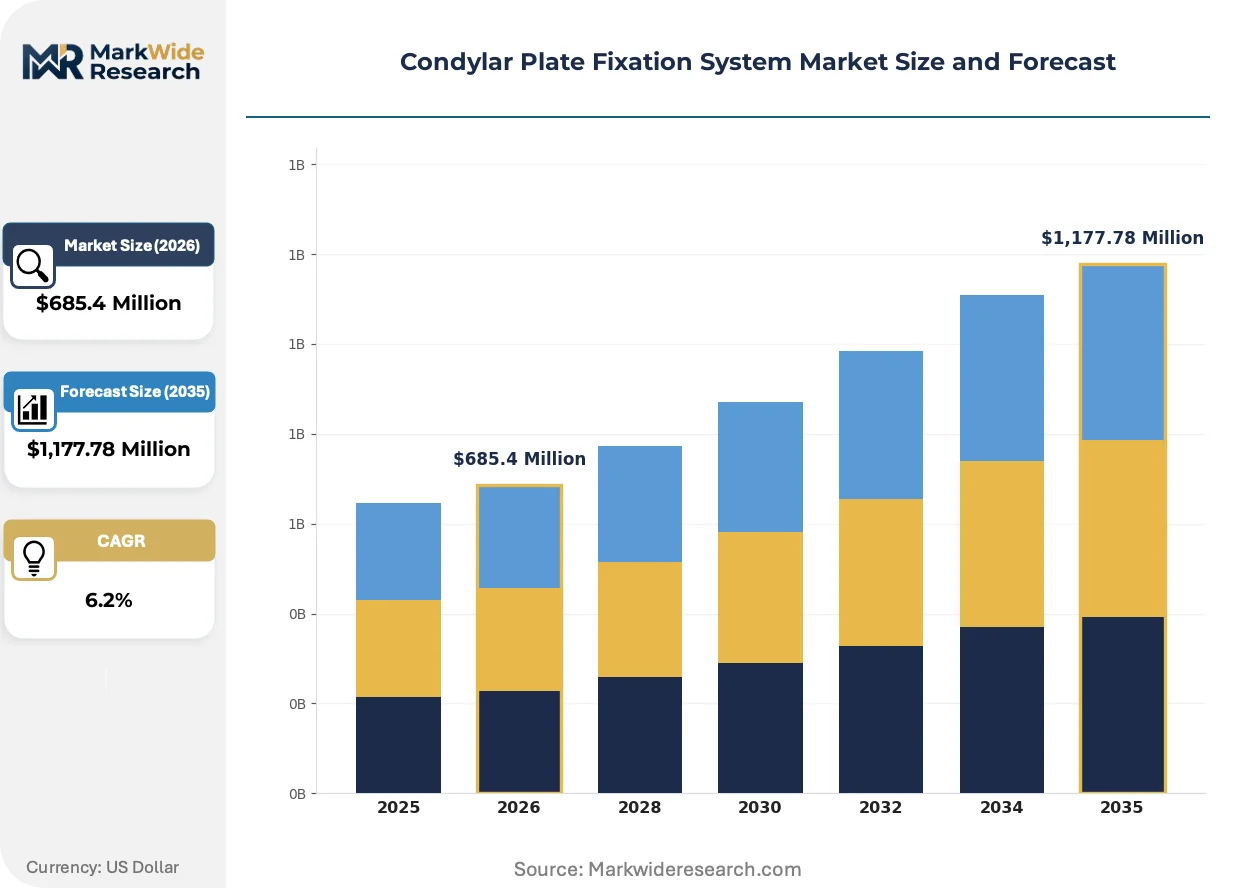
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locking Plates, Non-locking Plates, Hybrid Plates, Anatomical Plates, Reconstruction Plates Application: Fracture Fixation, Osteotomy, Trauma Surgery, Joint Reconstruction, Bone Realignment End User: Orthopedic Clinics, Trauma Centers, Surgical Hospitals, Ambulatory Surgical Centers, Rehabilitation Facilities Material: Titanium Alloy, Stainless Steel, Bioabsorbable Polymers, Cobalt-Chrome Alloy |
| Companies Covered | Aesculap, Auxein Medical, Zimmer Biomet, Medtronic, Stryker, DePuy Synthes, B. Braun, Procter & Gamble, Arthrex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Condylar Plate Fixation System Market Strategic Shifts & Innovations
Digital preoperative planning platforms are rewiring how plate selection and screw trajectory decisions occur before incision, compressing operative time and reducing fluoroscopy exposure.
Patient-specific instrumentation derived from preoperative CT segmentation is decomposing the traditional one-size-fits-all plate contouring workflow. Academic trauma centers in Germany and Switzerland are adopting these guides for complex intra-articular fracture patterns. The technology is decomposing inventory carrying costs for hospitals that previously stocked multiple plate sizes per anatomical variant.
FDA's evolving guidance on 3D-printed medical devices is tightening quality system expectations for additively manufactured plate architectures. Manufacturers must now demonstrate layer-wise porosity control and fatigue performance equivalence to wrought counterparts. Smaller OEMs without captive electron beam melting capacity are outsourcing to specialized AM service bureaus in Pennsylvania and Ohio.
Hospital purchasing committees are consolidating vendor relationships into single-source agreements that bundle plate systems with trauma instrument trays and sterilization case management. Distributors serving independent orthopedic practices are losing share to manufacturer-direct sales forces that embed clinical specialists within trauma call rotations. This concentration is most visible in the United States, where integrated delivery networks now control sixty percent of condylar plate procurement decisions.
Condylar Plate Fixation System Market Segmentation
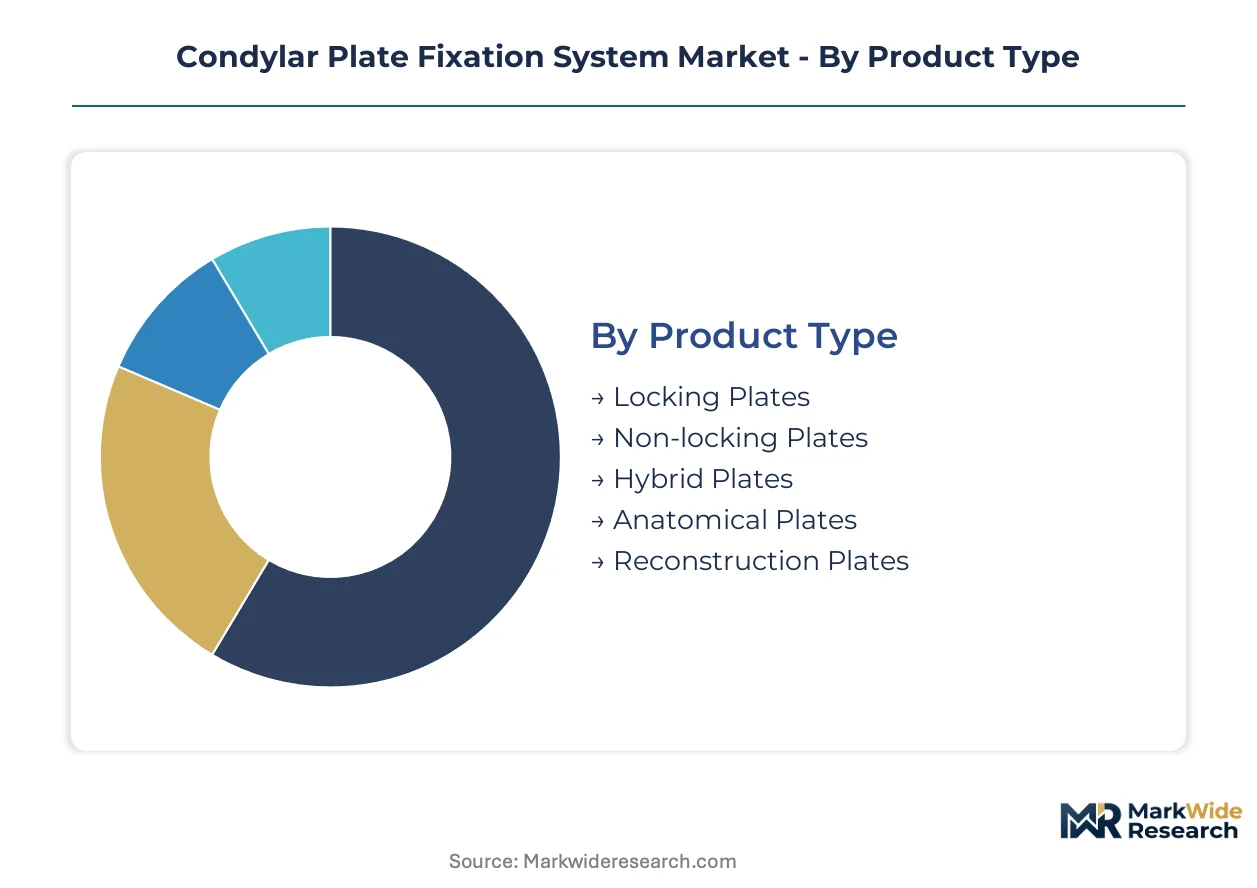
Condylar plate fixation systems fragment across four functional dimensions that determine procurement patterns and margin architecture. Product type and material composition drive technical differentiation, while application setting and end-user category dictate pricing power and instrument tray economics.
Product Type:
Domestic manufacturing concentrates locking and hybrid plate variants in Germany, Switzerland, and the United States, where precision forging infrastructure supports angular stability engineering. Export-led segments like anatomical and reconstruction plates flow from contract manufacturers in India and China serving price-sensitive trauma networks.
- Locking Plates:These constructs incorporate threaded screw holes that create fixed-angle stability between plate and bone, eliminating reliance on friction-based compression. Trauma centers in the United States and Germany prioritize locked constructs for osteoporotic distal femur fractures where screw pullout resistance determines clinical success. The segment captures premium pricing through proprietary thread geometries that block cross-manufacturer compatibility.
- Hybrid Plates:Combining locking and compression screw options in a single plate blank, hybrid architectures accommodate intraoperative flexibility when fracture patterns defy preoperative classification. Academic medical centers in Switzerland and trauma hubs in Maharashtra deploy hybrid systems for complex periarticular fractures where construct adaptability reduces revision rates. Manufacturers position these as bridge products between conventional and fully locked portfolios.
- Non-locking Plates:Compression plating systems rely on axial screw tightening to generate friction between plate and bone surface.
- Anatomical Plates:Pre-contoured geometries match specific distal femur morphologies without intraoperative bending.
- Reconstruction Plates:Malleable blanks permit manual contouring for non-standard fracture patterns or revision scenarios.
Locking plates command the established base. The steepest expansion runs through hybrid plates.
Application:
Emergency volume concentrates in trauma surgery and fracture fixation, where time-to-implantation protocols and surgeon call schedules determine vendor selection. Elective applications like osteotomy and joint reconstruction flow through scheduled surgical calendars with different capital equipment requirements.
- Trauma Surgery:Emergency stabilization of supracondylar and intercondylar fractures demands immediate plate availability and dedicated instrument tray sterilization. Level I trauma centers in the United States maintain consignment inventory with manufacturers who embed clinical specialists within call rotations. The segment generates recurring revenue through instrument set purchases and sterilization case management contracts.
- Fracture Fixation:Distal femur fracture management represents the core volume driver for condylar plate systems, spanning high-energy trauma in younger populations and low-energy fragility fractures in osteoporotic elderly. Surgical hospitals in Germany and trauma networks in Tamil Nadu report divergent preferences—locked constructs dominate European protocols while cost constraints in India sustain compression plating volume.
- Osteotomy:Elective bone realignment procedures for deformity correction utilize condylar plates for temporary stabilization during healing.
- Joint Reconstruction:Periprosthetic fracture fixation around total knee arthroplasty components employs specialized low-profile plates.
- Bone Realignment:Pediatric and adult deformity correction applies condylar plates to maintain mechanical axis restoration.
Trauma surgery anchors procurement volume. Osteotomy applications are climbing the fastest as deformity correction volumes rise in aging populations.
End User:
Capital intensity stratifies end users—trauma centers and surgical hospitals deploy comprehensive instrument systems while ambulatory settings concentrate on high-volume, low-complexity procedures.
- Trauma Centers:Designated Level I and II facilities in the United States consolidate orthopedic emergency services and standardize on locked construct protocols. These centers negotiate single-source agreements bundling plate systems with instrument trays, sterilization logistics, and clinical specialist coverage. Procurement committees prioritize reliability metrics and surgeon preference card standardization over unit pricing.
- Surgical Hospitals:General acute care facilities with orthopedic service lines perform scheduled fracture fixation and elective osteotomy procedures. German surgical hospitals exhibit strong preference for anatomical pre-contoured plates that reduce operative time and fluoroscopy exposure. Capital budgets constrain these facilities from maintaining multiple vendor instrument systems.
- Orthopedic Clinics:Outpatient settings focus on preoperative planning and postoperative rehabilitation rather than implant delivery.
- Ambulatory Surgical Centers:Limited to low-complexity fracture patterns suitable for same-day discharge protocols.
- Rehabilitation Facilities:Post-acute settings manage weight-bearing progression after plate fixation but do not perform implantation.
Trauma centers concentrate pricing power. Ambulatory surgical centers are expanding most quickly as fracture care decentralizes.
Material:
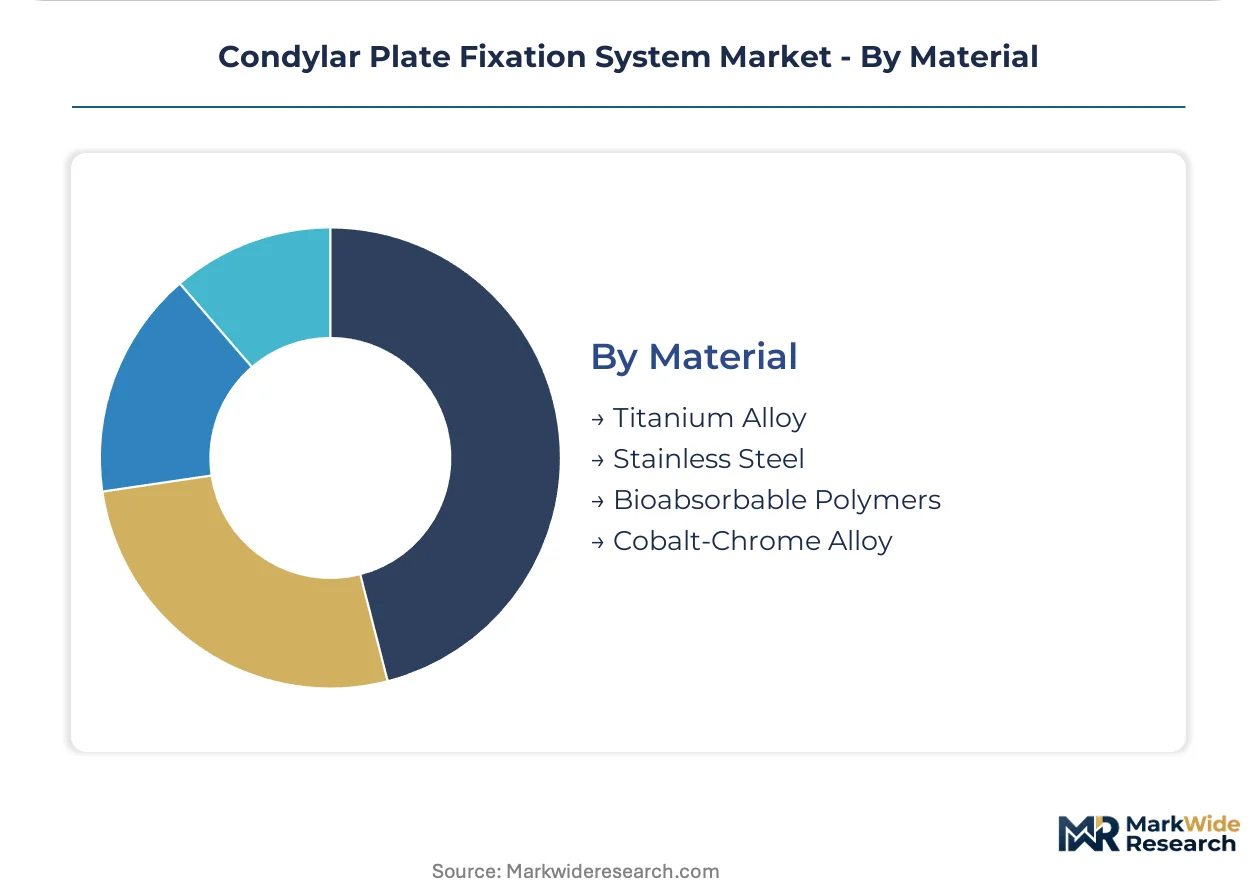
Titanium alloy forging capacity clusters in aerospace-adjacent supply chains across the United States, Germany, and Japan, while stainless steel processing remains geographically dispersed. Bioabsorbable polymer synthesis represents the most concentrated supply base, with limited qualified manufacturers meeting ISO 5832 implant standards.
- Titanium Alloy:Ti-6Al-4V ELI grade dominates condylar plate manufacturing through superior strength-to-weight ratio and MRI compatibility. Near-net-shape forging advances in Pennsylvania and Ohio are compressing raw material waste in plate blank production. Spot market volatility for Ukrainian and Russian sponge titanium concentrate threatens input cost stability.
- Bioabsorbable Polymers:Magnesium-alloy and PLLA-based constructs eliminate secondary removal procedures in pediatric and geriatric populations. France's ANSM guidance favoring implant removal reduction creates reimbursement preference for these materials. Polymer degradation kinetics and inflammatory response profiles remain under active clinical investigation.
- Stainless Steel:316L grade persists in cost-sensitive markets and revision scenarios requiring plate removal.
- Cobalt-Chrome Alloy:Limited application in condylar plating due to modulus mismatch with bone and machining complexity.
Titanium alloy holds the installed base. Bioabsorbable polymers are gaining share fastest on pediatric demand and removal-reduction mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in condylar plate fixation systems tilt toward manufacturing surplus in Germany, Switzerland, and the United States against rising import dependency in India and China. Titanium alloy forging capacity concentrates in aerospace-adjacent supply corridors, creating regional specialization in precision-machined plate blanks.
United States
Level I trauma hub consolidation in Texas, Florida, and California drives procurement standardization on locked construct protocols. FDA 510(k) premarket notification requirements enforce exhaustive clinical evidence libraries for each plate-screw combination. Pennsylvania and Ohio host electron beam melting service bureaus supplying patient-specific plate architectures to academic medical centers.
Germany
Surgical hospitals in Bavaria and North Rhine-Westphalia exhibit strong preference for anatomical pre-contoured plates that reduce operative time. EU MDR technical documentation obligations compel manufacturers to maintain validated biocompatibility dossiers per ISO 5832. The Stuttgart precision forging cluster supplies near-net-shape Ti-6Al-4V ELI blanks to domestic OEMs.
China
Trauma surgery networks in Shanghai and Beijing are scaling orthopedic emergency infrastructure under hospital tier-upgrading programs. NMPA medical device registration requirements are tightening quality system expectations for imported plate systems. The Yangtze River Delta concentrates CNC machining capacity for cost-sensitive reconstruction plate exports.
India
Underserved trauma networks in Maharashtra and Tamil Nadu are attracting forging capacity investments under the PLI scheme for medical device manufacturing. CDSCO medical device rules mandate registration for all implantable orthopedic products. Tamil Nadu's medical device park in Oragadam is onboarding contract manufacturers serving domestic price-sensitive segments.
Switzerland
Academic trauma centers in Zurich and Geneva are adopting patient-specific instrumentation for complex intra-articular fracture patterns. Swissmedic conformity assessment requirements align with EU MDR for market access. The Solothurn precision manufacturing corridor anchors hybrid plate production for European export markets.
Condylar Plate Fixation System Market Key Industry Players
Concentration sits with integrated orthopedic conglomerates that command captive forging capacity and trauma center contract density. The vendor base stratifies across three tiers: capital-heavy integrated manufacturers controlling titanium alloy supply chains, mid-scale specialists focusing on anatomical pre-contoured geometries, and regional contract fabricators serving price-sensitive markets. Dominant competitive moves include backward integration into titanium sponge sourcing and single-source agreements bundling plate systems with instrument tray logistics.
Among integrated orthopedic conglomerates, Zimmer Biomet and Stryker exemplify archetypes that anchor market structure through dense trauma center relationships. DePuy Synthes occupies a position emphasizing proprietary screw-plate interface geometries. Swiss-based B. Braun and German-domiciled Aesculap represent European precision manufacturing heritage in locking plate architectures.
| Leading Market Players |
|---|
| Aesculap |
| Auxein Medical |
| Zimmer Biomet |
| Medtronic |
| Stryker |
| DePuy Synthes |
| B. Braun |
| Procter & Gamble |
| Arthrex |
| Others |
Cost & Logistics Intelligence
Sixty-day instrument tray sterilization cycles at Level I trauma hubs concentrate purchasing leverage with manufacturers who bundle plate systems with logistics support, compressing margin capture for standalone component suppliers. This inventory velocity differential between integrated vendors and specialized fabricators is redrawing pricing power across the condylar plate fixation system value chain.
Pricing Analysis
The customization-premium spread between patient-specific 3D-printed plates and standard anatomical geometries reaches multiples of base catalog pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification tier and trauma center contract density. Cost compression in stainless steel reconstruction plates is intensifying because Indian contract manufacturers are scaling CNC machining capacity under PLI scheme incentives. Ambulatory surgical centers exhibit acute price sensitivity, while Level I trauma centers prioritize reliability metrics and surgeon preference card standardization over unit economics.
Supply Chain Analysis
Ukrainian and Russian sponge titanium corridors constitute a chokepoint that exposes forged plate blank producers to input cost volatility. Geographic supply concentration clusters in Germany, Switzerland, and the United States for precision forging, with CNC machining capacity expanding in India and China. Raw material dependencies center on Ti-6Al-4V ELI titanium alloy, electron beam melting powder stocks, and biocompatible polymer feedstocks. Single-source vulnerability runs through aerospace-adjacent titanium sponge processors. Distribution runs through manufacturer-direct sales forces embedding clinical specialists within trauma call rotations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
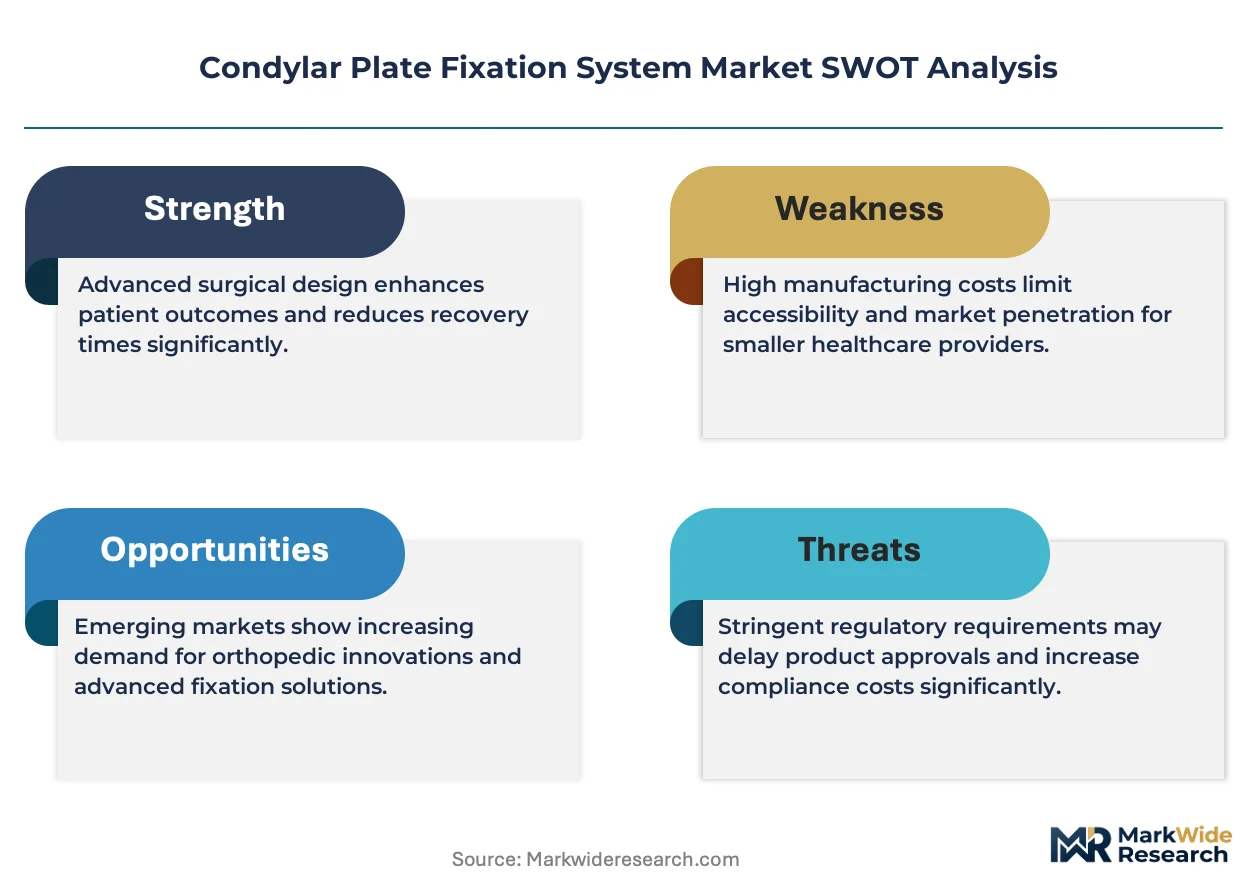
The condylar plate fixation system market sits at a platform-economics inflection where proprietary screw-plate interface geometries are locking in trauma center ecosystems and blocking cross-manufacturer interoperability, consolidating vendor power around integrated instrument-and-implant bundles.
For Market Incumbents: Compound trauma center contract density through captive electron beam melting capacity additions in Pennsylvania and Ohio, while accelerating FDA 510(k) pathway investments to outpace MDR Notified Body bottlenecks. Distal femoral nail substitution with poller screw augmentation threatens lateral condylar plate volume in intertrochanteric applications. Backward integration into Ukrainian and Russian sponge titanium sourcing alternatives insulates margin stability against spot market volatility. For New Entrants and Emerging Players: CDSCO fast-track registration for medical device manufacturing under India's PLI scheme opens Maharashtra and Tamil Nadu trauma networks previously captured by import-dependent distributors. Bioabsorbable polymer condylar plates for pediatric populations in France represent the most penetrable white-space segment given ANSM removal-reduction guidance. A go-to-market angle anchored to sterilizable instrument tray leasing rather than capital purchase addresses hospital budget constraints. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because trauma center single-source agreements and instrument tray capital burdens are raising barriers to independent vendor viability. Acquisition targets cluster around electron beam melting service bureaus with FDA quality system documentation and European MDR technical file readiness. The signal to watch is 3D-printed patient-specific plate reimbursement coding adoption by CMS and major German statutory insurers.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Bundled plate-instrument-sterilization contracts lock in Level I trauma hub procurement committees. |
| CE Marking Pathway | MDR technical documentation investments accelerate hospital adoption of pre-validated biocompatibility dossiers. |
| Backward Integration into Titanium Forging | Captive Ti-6Al-4V ELI blank production compresses raw material waste and insulates sponge price volatility. |
| Software Companion Development | Digital preoperative planning platforms reduce fluoroscopy exposure and shorten operative time for trauma surgeons. |
| Reimbursement Strategy | ANSM-aligned bioabsorbable polymer coding secures pediatric preference in France's removal-reduction mandate environment. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across orthopedic trauma surgeons, hospital purchasing committee members, biomedical engineers at Level I trauma centers, GPO contracts managers, and precision forging plant managers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement contract registries, and titanium sponge trade flow records. Bottom-up trauma center inventory audits triangulated against top-down OEM revenue segment disclosures.
Across the analysis window, the forecasting framework modeled product type segmentation by locking, hybrid, and anatomical plate architectures; application settings spanning trauma surgery, fracture fixation, and osteotomy; end-user categories from Level I trauma centers to ambulatory surgical centers; and material composition across titanium alloy, bioabsorbable polymer, and stainless steel grades. CAGRs were derived from surgical procedure volume projections, instrument tray replacement cycles, and material substitution elasticity estimates. Industry-specific inputs incorporated MDR Notified Body certification timeline data and PLI scheme manufacturing capacity announcements.
Underlying assumptions cover sustained trauma center consolidation in Texas, Florida, and California, with deviation risk concentrated in sponge titanium supply corridor disruptions and EU MDR conformity assessment body capacity constraints. Forecasts reflect these documented assumptions. Revision becomes warranted when 3D-printed plate fatigue performance equivalence thresholds cross regulatory acceptance thresholds or when bioabsorbable polymer inflammatory response profiles trigger safety review protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Respirator Market
Medical Devices
Radial Compression Devices Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Digital BTE Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Mexican Intraocular Lens Market
Medical Devices
Intrauterine Insemination Devices Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Middle East and Africa Vagus Nerve Stimulation Market
Medical Devices
Japan Ultrasound Devices Market
Medical Devices
Balloon Valvuloplasty Device Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
Medication Dispensing and Packaging Systems Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
Hearing Devices 3D Printing Market