
 Global Extracorporeal Shock Wave Lithotripsy Market | 2026-2036
Global Extracorporeal Shock Wave Lithotripsy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Extracorporeal Shock Wave Lithotripsy Market Foresight
After-sales maintenance contracts and software-defined waveform calibration is pivoting how lithotripsy vendors monetize installed bases. Boston Scientific Corporation leverages its integrated urology portfolio to bundle service agreements with capital equipment placements. Dornier MedTech anchors its competitive stance through deep specialization in electromagnetic shock wave generation. STORZ Medical differentiates via proprietary focus tracking systems that reduce retreatment rates in renal calculi procedures.
Extracorporeal shock wave lithotripsy employs focused acoustic pulses generated outside the body to fragment urinary and biliary calculi without incision, typically operating at 0.2 to 0.5 mJ/mm² energy density with pulse frequencies between 60 and 120 Hz. The technology serves urologists and gastroenterologists seeking non-invasive alternatives to percutaneous nephrolithotomy or endoscopic retrieval. Electromagnetic lithotripters command the largest installed base due to reliable focal zone stability and lower consumable costs than electrohydraulic equivalents. Piezoelectric systems occupy premium positioning in ambulatory settings where compact footprint and reduced anesthesia requirements attract outpatient clinics. Mobile deployment configurations represent the fastest-expanding category as health systems prioritize equipment utilization across multiple facility sites.
FDA 510(k) premarket notification requirements govern electromagnetic and piezoelectric lithotripter introductions in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for CE marking renewal across European markets. Japan's PMDA evaluates shock wave devices under its pharmaceutical and medical safety framework, creating additional documentation burdens for manufacturers seeking reimbursement eligibility. China's NMPA has tightened electromagnetic compatibility testing protocols for imported lithotripsy systems, lengthening registration timelines for multinational suppliers. Stakeholders must monitor how evolving electromagnetic emissions standards in major markets reshape product architecture and certification investment priorities.
Market Dynamics
Electromagnetic lithotripter manufacturers face intensifying pressure from ambulatory surgery centers demanding mobile configurations that maximize equipment utilization across distributed facility networks.
Growth Catalysts
- Outpatient procedure migration:Ambulatory surgery centers in the United States are expanding lithotripsy capacity as payors incentivize same-day discharge protocols for renal calculi treatment.
- Electromagnetic focal stability:Improved shock wave focusing technology reduces retreatment rates, driving replacement demand for aging electrohydraulic installed bases.
- FDA 510(k) pathway efficiency:Streamlined premarket notification procedures accelerate electromagnetic lithotripter introductions compared to novel device validation timelines.
Market Restraints
- Capital intensity barriers:Electromagnetic lithotripter systems require substantial upfront investment, limiting penetration in underfunded public hospital systems.
- Specialized technician dependency:Precise waveform calibration demands trained biomedical engineers, creating operational bottlenecks in resource-constrained settings.
- Reimbursement compression:Medicare physician fee schedule adjustments for outpatient urology procedures constrain capital equipment purchasing cycles.
Strategic Opportunities
- Mobile service deployment:Equipment-as-a-service models enable lithotripter access for rural hospital networks lacking dedicated capital budgets.
- Biliary application expansion:Shock wave technology is penetrating gastroenterology practices for choledocholithiasis management beyond traditional urology dominance.
- EU MDR clinical evidence requirements:Stricter CE marking renewal standards create competitive moats for manufacturers with robust clinical documentation portfolios.
Industry Challenges
- Legacy system integration:New electromagnetic lithotripters must interface with existing hospital information systems and imaging archives, complicating deployment timelines.
- Electromagnetic compatibility certification:China's NMPA has tightened EMC testing protocols for imported systems, extending registration timelines and requiring architectural redesigns.
- Anesthesiology coordination:Procedure scheduling depends on limited anesthesia availability in outpatient settings, constraining throughput optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Extracorporeal Shock Wave Lithotripsy Market |
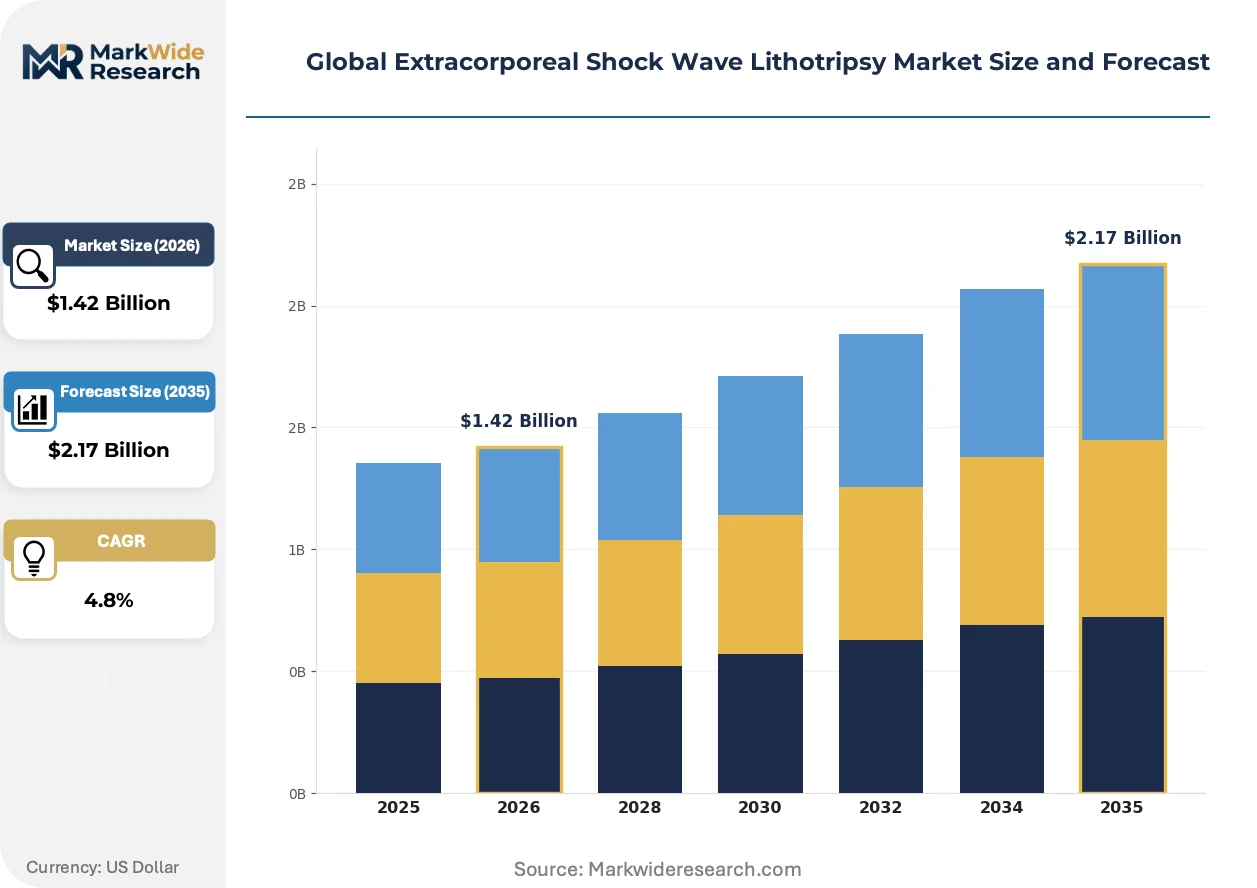
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrohydraulic, Electromagnetic, Piezoelectric, Electroconductive Application: Nephrolithiasis, Ureterolithiasis, Cholelithiasis, Pancreaticolithiasis, Biliary Calculi End User: Urology Clinics, Diagnostic Centers, Specialty Hospitals, Ambulatory Surgery Centers, Rehabilitation Facilities Deployment: Stationary Units, Mobile Units, Portable Devices, Hybrid Systems |
| Companies Covered | Boston Scientific Corporation, Dornier MedTech, Olympus Corporation, STORZ Medical, Cook Group, EDAP TMS, Siemens Healthineers, Richard Wolf, DirexGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Extracorporeal Shock Wave Lithotripsy Market Shifts & Advancements
Software-defined waveform control and real-time imaging fusion are compressing treatment durations while expanding treatable patient populations beyond traditional stone size thresholds.
Artificial intelligence-integrated targeting systems are automating focal zone alignment during renal calculi procedures. Academic medical centers in Germany and Japan are piloting these platforms to reduce operator-dependent variability. The technology is automating retreatment prediction algorithms that adjust energy delivery based on real-time fragmentation feedback.
The EU Medical Device Regulation now mandates post-market clinical follow-up studies for electromagnetic lithotripters seeking CE marking renewal. Manufacturers must establish systematic registries tracking long-term stone-free rates and adverse events. European urology clinics are responding by consolidating purchasing decisions around vendors with established clinical evidence programs.
Hospital procurement committees are unbundling service contracts from capital equipment purchases, creating independent negotiations for maintenance and software updates. This shift fragments vendor revenue streams and pressures after-sales margins. The pattern is most pronounced in United States health systems pursuing operational expenditure optimization over traditional capital ownership models.
Global Extracorporeal Shock Wave Lithotripsy Market Segmentation
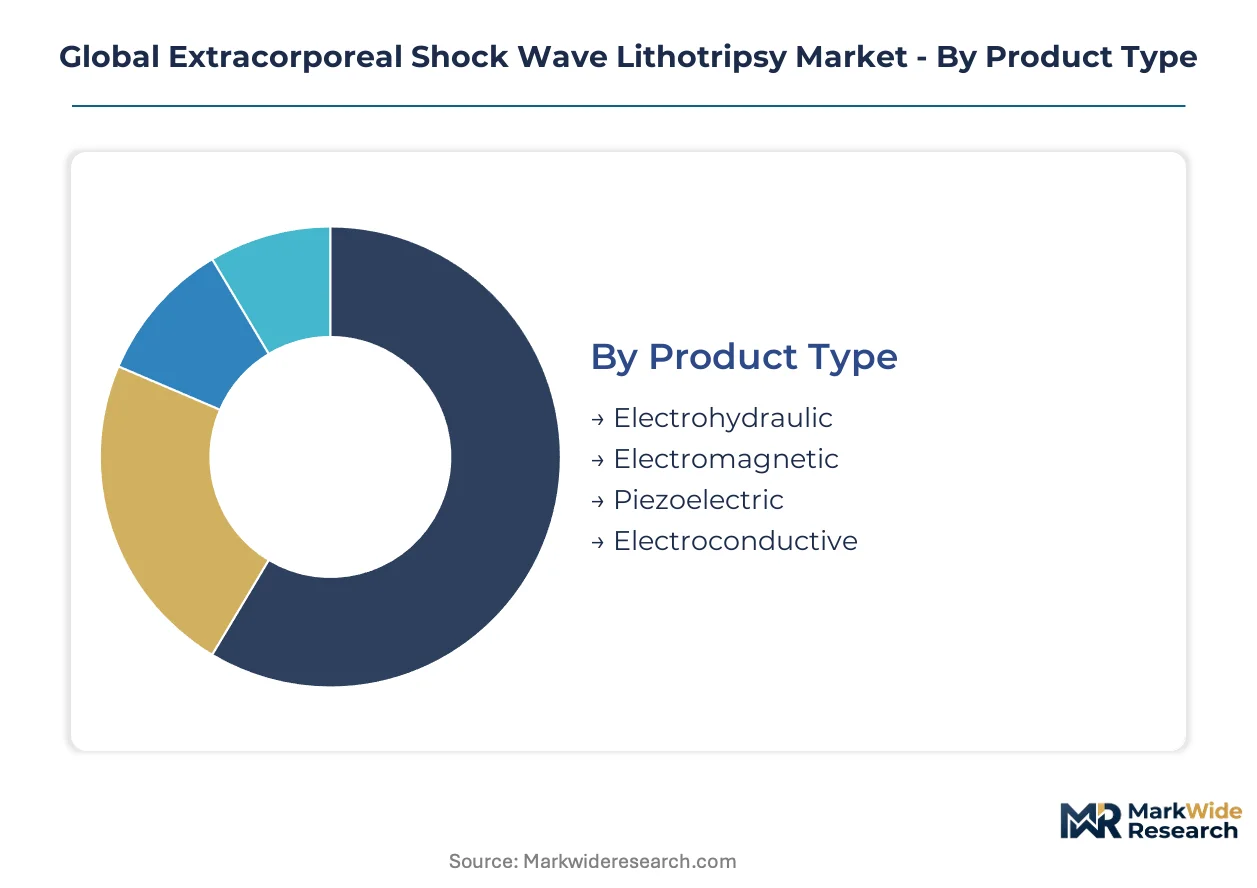
Technology selection in lithotripsy equipment hinges on focal zone precision, consumable economics, and facility infrastructure constraints. Procurement committees evaluate electromagnetic stability against piezoelectric compactness when aligning capital budgets with procedural throughput targets.
Product Type:
Capital allocation decisions prioritize total cost of ownership across shock wave generation architectures.
- Electromagnetic:Coil-driven membrane systems generate acoustic pulses through electromagnetic induction, delivering consistent focal zone geometry across treatment sessions. United States hospital networks favor this architecture for high-volume renal stone programs where retreatment minimization justifies premium capital outlay.
- Piezoelectric:Ceramic crystal arrays produce shock waves through rapid piezoelectric expansion, enabling compact system footprints with reduced anesthesia requirements. German outpatient urology clinics deploy these systems where space constraints and same-day discharge protocols dominate procurement criteria.
- Electrohydraulic:Spark-gap electrode systems fragment stones through underwater spark discharge, representing legacy installed bases now targeted for replacement cycles.
- Electroconductive:Emerging conductive membrane technologies promise simplified maintenance protocols with fewer consumable components than electrohydraulic equivalents.
Electromagnetic systems lead on installed base scale; piezoelectric configurations gain share fastest in ambulatory expansion.
Application:
Clinical indication drives energy density calibration and imaging integration requirements.
- Nephrolithiasis:Renal calculi fragmentation commands the dominant procedure volume, with electromagnetic lithotripters optimized for kidney stone localization through fluoroscopic or ultrasound guidance. Japanese academic medical centers emphasize real-time imaging fusion for complex staghorn calculus presentations.
- Ureterolithiasis:Distal ureter stone management requires modified focal depth settings and patient positioning protocols, with piezoelectric systems preferred for lower ureteral segments where anesthesia minimization improves patient tolerance.
- Cholelithiasis:Gallstone lithotripsy remains restricted to select patient populations with bile duct patency, limiting penetration outside specialized hepatobiliary centers.
- Pancreaticolithiasis:Pancreatic duct stone fragmentation demands precise energy modulation to avoid parenchymal injury, constraining adoption to tertiary referral institutions.
- Biliary Calculi:Common bile duct stone management through shock wave therapy competes with endoscopic retrieval, with gastroenterology practices in France evaluating hybrid approaches.
Nephrolithiasis anchors revenue concentration; biliary applications demonstrate the steepest expansion trajectory as gastroenterology adoption accelerates.
End User:
Facility type dictates mobility requirements, staffing models, and reimbursement capture strategies.
- Ambulatory Surgery Centers:Freestanding outpatient facilities prioritize mobile lithotripter configurations enabling equipment rotation across distributed sites, with United States payor incentives for same-day discharge reinforcing capital commitment to these settings.
- Specialty Hospitals:Dedicated urology institutions integrate stationary electromagnetic systems with comprehensive imaging suites, capturing complex stone cases requiring multidisciplinary management.
- Urology Clinics:Private practice settings emphasize compact piezoelectric systems for office-based stone management where procedure volume supports dedicated equipment investment.
- Diagnostic Centers:Imaging-focused facilities deploy lithotripsy as ancillary service, constrained by anesthesia availability and procedural scheduling limitations.
- Rehabilitation Facilities:Post-acute settings explore shock wave therapy for musculoskeletal applications beyond traditional stone disease, representing emerging demand outside core urology.
Specialty hospitals dominate absolute equipment value; ambulatory surgery centers drive volume expansion through distributed deployment models.
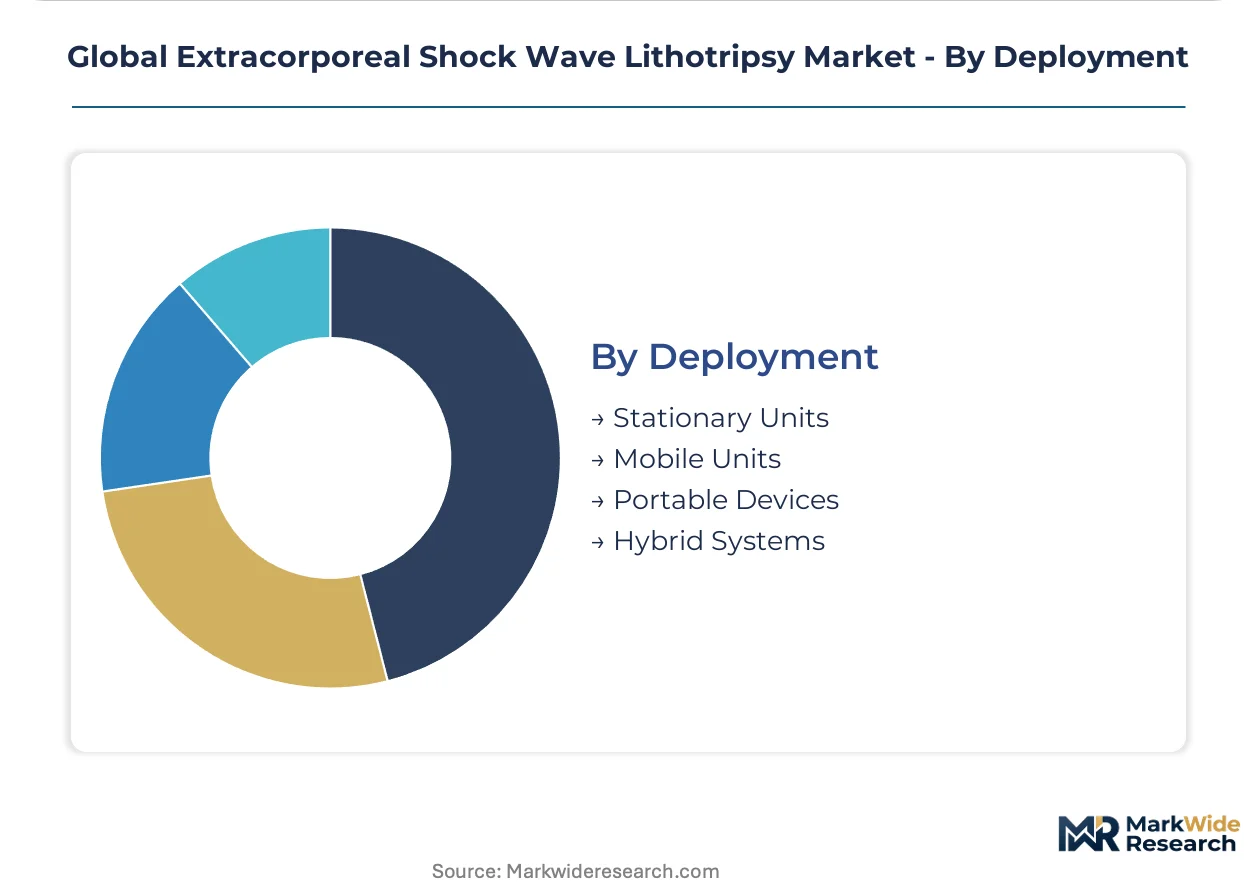
Deployment:
Physical configuration determines utilization economics and geographic coverage capabilities.
- Mobile Units:Truck-mounted or trailer-based lithotripters rotate across hospital networks, enabling rural United States facilities to access shock wave technology without dedicated capital expenditure. Service-based contracting models align vendor revenue with procedure throughput rather than equipment ownership.
- Stationary Units:Fixed-installation electromagnetic systems anchor high-volume stone centers in urban United States markets, with dedicated procedure rooms optimizing anesthesia scheduling and imaging integration.
- Portable Devices:Compact cart-based systems target satellite clinic deployment where space constraints preclude full stationary installation.
- Hybrid Systems:Modular architectures combine stationary treatment capabilities with limited mobility for intra-facility repositioning, appealing to mid-sized European hospitals seeking flexibility without full mobile service commitment.
Stationary units retain the largest revenue base; mobile configurations expand most quickly as health systems prioritize asset utilization over capital ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where lithotripter manufacturers establish certification and service operations, with cost-of-compliance gaps between the FDA's 510(k) pathway and the EU MDR's clinical evidence requirements driving strategic facility placement decisions.
United States
Aging demographics and high procedural volumes sustain installed base upgrades across hospital networks, with Medicare reimbursement policies incentivizing outpatient migration to ambulatory surgery centers. The FDA's streamlined 510(k) premarket notification accelerates electromagnetic lithotripter introductions compared to novel device pathways. Boston Scientific Corporation anchors its integrated urology portfolio through service agreement bundling in metropolitan health systems.
Germany
Academic medical centers pilot artificial intelligence-integrated targeting systems to reduce operator-dependent variability in renal calculi procedures. The EU Medical Device Regulation mandates post-market clinical follow-up studies for CE marking renewal, creating competitive moats for manufacturers with robust documentation portfolios. STORZ Medical leverages its proprietary focus tracking systems from its Tägerwilen headquarters to minimize retreatment rates across European urology clinics.
Japan
PMDA evaluation of shock wave devices under pharmaceutical and medical safety frameworks creates additional documentation burdens for reimbursement eligibility. Real-time imaging fusion for complex staghorn calculus presentations drives technology adoption at tertiary institutions in Tokyo and Osaka. Domestic procurement preferences favor electromagnetic systems with demonstrated focal zone stability for high-volume stone centers.
China
NMPA tightening of electromagnetic compatibility testing protocols for imported systems lengthens registration timelines and requires architectural redesigns for multinational suppliers. Provincial hospital networks in Yangtze River Delta and Pearl River Delta regions prioritize mobile deployment configurations to maximize equipment utilization across distributed facilities. Local manufacturers capture share in mid-tier segments through simplified maintenance protocols.
India
Capital intensity barriers limit electromagnetic lithotripter penetration in underfunded public hospital systems, creating demand for equipment-as-a-service models. CDSCO regulatory pathways for imported medical devices require local clinical trial data, extending market entry timelines for foreign manufacturers. Private urology chains in Maharashtra and Karnataka deploy compact piezoelectric systems for office-based stone management where procedure volume supports dedicated equipment investment.
Global Extracorporeal Shock Wave Lithotripsy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated urology portfolios commanding premium positioning in hospital networks while regional fabricators capture mid-tier ambulatory deployments. The vendor base concentrates around electromagnetic shock wave generation specialists and diversified medical technology conglomerates with imaging integration capabilities. Three archetypes dominate: full-stack urology platform providers, lithotripter pure-plays with deep acoustic engineering heritage, and diversified imaging equipment manufacturers extending into therapeutic modalities. Competitive moves center on unbundling service contracts from capital sales and mobile equipment-as-a-service deployment to capture rural network access.
Within the full-stack urology tier, Boston Scientific Corporation and Cook Group exemplify platform bundling strategies that combine capital equipment with disposable consumables and maintenance agreements. Dornier MedTech anchors the lithotripter pure-play archetype through electromagnetic shock wave specialization. Siemens Healthineers occupies a position bridging imaging dominance with therapeutic extension, leveraging installed radiology relationships for cross-selling opportunities.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Dornier MedTech |
| Olympus Corporation |
| STORZ Medical |
| Cook Group |
| EDAP TMS |
| Siemens Healthineers |
| Richard Wolf |
| DirexGroup |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in electromagnetic coil manufacturing anchor tier-two component supply, transmitting disciplined pricing power through to finished lithotripter systems while constraining margin compression for integrated vendors.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for piezoelectric ceramic arrays, pressuring legacy Japanese suppliers. Three-tier pricing structure across premium electromagnetic, standard piezoelectric, and economy electrohydraulic levels stratifies by focal zone precision and imaging integration depth. Cost compression in mid-tier configurations is intensifying because ambulatory surgery centers unbundle service contracts from capital purchases. Hospital procurement committees exhibit highest price sensitivity, while academic medical centers prioritize retreatment minimization over acquisition cost.
Supply Chain Analysis
Electromagnetic membrane supply rests on German and Swiss specialty metalworking producers for precision coil winding substrates. Ceramic crystal arrays draw from Japanese and South Korean piezoelectric material specialists, with copper electromagnetic coils sourced from Chinese wire-drawing facilities. Single-source vulnerability concentrates in high-purity ceramic substrates for focal zone stability. Distribution runs through regional medical device distributors with biomedical engineer training capabilities, extending to direct hospital contracting for high-volume stone centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with demand shifting toward electromagnetic systems with demonstrated retreatment rate superiority over aging electrohydraulic installed bases.
For Market Incumbents: Lock in service contract renewal rates by embedding software-defined waveform calibration as mandatory subscription components, defending against unbundling pressure from United States health systems pursuing operational expenditure optimization. Deepen backward integration into electromagnetic coil manufacturing to secure supply continuity against China's NMPA electromagnetic compatibility testing delays. Prioritize CE marking renewal documentation investments ahead of EU MDR post-market clinical follow-up mandates. For New Entrants and Emerging Players: AI-integrated targeting systems offer a technology-first wedge for academic medical center pilot programs in Germany and Japan, where operator-dependent variability reduction commands premium positioning. Mobile equipment-as-a-service deployment represents the most penetrable avenue for rural United States hospital networks lacking dedicated capital budgets. Pursue GPO contracting relationships that bundle procedure throughput guarantees with equipment access fees rather than traditional capital sales. For Investors and Strategic Acquirers: Valuations sit cheapest among lithotripter pure-plays with deep acoustic engineering heritage but limited imaging integration capabilities, as full-stack urology platforms capture procurement committee attention. Five-to-ten year viability hinges on software companion development and real-time imaging fusion capabilities rather than hardware differentiation alone. Watch mobile service deployment penetration rates in United States rural networks as inflection indicator for asset-light business model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Real-time waveform calibration subscriptions from Boston Scientific and STORZ Medical transform capital sales into recurring revenue streams. |
| CE Marking Pathway Investment | Robust clinical documentation portfolios under EU MDR create competitive moats for electromagnetic lithotripter manufacturers seeking renewal. |
| Hospital System Partnership | Integrated urology platform bundling by Cook Group and Olympus Corporation secures multi-year service agreements with metropolitan networks. |
| Mobile Service Deployment | Equipment-as-a-service models enable Dornier MedTech access to rural United States facilities without dedicated capital expenditure. |
| Reimbursement Strategy | Medicare physician fee schedule navigation determines ambulatory surgery center purchasing cycles for outpatient urology procedures. |
Research Methodology
Multiple input streams — primary interviews with urology department chairs, biomedical engineering directors, and GPO contracts managers, plus secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records — were reconciled through bottom-up equipment shipment tracking and top-down healthcare expenditure triangulation.
Data-stream reconciliation across technology type, application indication, end-user facility category, and geographic regulatory cluster enabled projection modeling throughout the forecast period. CAGRs were derived from installed base replacement cycles and ambulatory migration patterns. Electromagnetic focal stability improvements and mobile deployment adoption curves served as primary demand-side inputs, while regulatory timeline compression in China and Europe shaped supply-side constraints.
The model holds under stable reimbursement policy conditions; deviation in Medicare outpatient procedure coding or EU MDR enforcement intensity would shift equipment replacement timelines. A small set of named triggers — NMPA registration delays, anesthesia staffing shortages in ambulatory settings, and electromagnetic compatibility standard revisions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Cyberknife Technology Market
Medical Devices
Asia-Pacific Vagus Nerve Stimulation Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Dose Monitoring Devices Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Global Enteral Feeding Tubes Market
Medical Devices
Steerable Needles Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
Hormonal Implants Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Asia-Pacific Biosurgery Market
Medical Devices
Global Automatic Stair Climbing Wheelchair Market
Medical Devices
Transcatheter Pulmonary Valve Replacement Market