
 Interventional Cardiology and Peripheral Vascular Devices Market | 2026-2036
Interventional Cardiology and Peripheral Vascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Interventional Cardiology and Peripheral Vascular Devices Market Analysis
A shift from single-source to multi-source component procurement is restructuring supply economics for catheter and guidewire manufacturers. Boston Scientific Corporation leverages vertically integrated balloon molding capabilities across its cardiovascular portfolio. Abbott Laboratories anchors its competitive position through drug-eluting stent polymer science developed in-house. Medtronic dominates structural heart delivery systems through captive supply of nitinol components.
Interventional cardiology and peripheral vascular devices encompass minimally invasive instruments—typically constructed from stainless steel, cobalt-chromium alloys, or nickel-titanium shape-memory materials with catheter shaft diameters ranging from 3 French to 14 French—designed to restore blood flow through percutaneous access rather than open surgery. Stent platforms generate the largest revenue pool within product type segmentation, though bioabsorbable variants remain commercially constrained by strut thickness limitations and extended follow-up requirements. Coronary intervention applications retain the highest procedure frequency, while peripheral intervention represents the fastest-expanding application segment driven by femoropopliteal and below-the-knee disease prevalence.
FDA premarket notification and premarket approval pathways govern device commercialization in the United States, while EU MDR technical documentation and clinical evidence requirements have extended conformity assessment timelines for stent and balloon manufacturers. Japan's PMDA shonin approval process imposes additional local clinical study obligations that filter market entrants. Stakeholders must monitor reimbursement coding revisions for transcatheter procedures and evolving health technology assessment criteria that determine hospital procurement budgets.
Market Dynamics
Multi-source procurement mandates from hospital systems are compressing margins for catheter and guidewire suppliers while reshaping contract structures across the cardiovascular device value chain.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways accelerate commercialization timelines for novel structural heart interventions, compressing time-to-revenue for innovators targeting high-risk patient populations.
- Femoropopliteal Disease Prevalence:Rising below-the-knee intervention volumes in Germany and Japan drive demand for low-profile balloon platforms and drug-coated balloon alternatives.
- Nitinol Shape-Memory Alloys:Self-expanding stent platforms leveraging superelastic properties enable treatment of tortuous peripheral anatomy previously inaccessible to balloon-expandable systems.
Market Restraints
- Cobalt-Chromium Alloy Concentration:Supply vulnerability concentrates in a limited number of specialty melt shops, exposing stent manufacturers to input cost volatility and allocation risk.
- EU MDR Clinical Evidence Requirements:Extended conformity assessment timelines for legacy stent systems delay renewal certifications and freeze product line extensions.
- Surgical Revascularization Persistence:Coronary artery bypass grafting retains preference for multi-vessel disease in specific patient cohorts, capping percutaneous intervention share.
Strategic Opportunities
- India Peripheral Vascular Underpenetration:Diabetic foot ulcer complications and limited vascular surgeon density create whitespace for catheter-based limb salvage procedures.
- Bioresorbable Scaffold Polymer Science:Magnesium alloy platforms and tyrosine-derived polymers promise temporary scaffolding without permanent metal caging.
- Japan PMDA Sakigake Pathway:Priority review incentives for first-in-class devices accelerate market entry for novel bioabsorbable stent technologies.
Industry Challenges
- Nitinol Processing Talent Scarcity:Laser cutting and electropolishing expertise for shape-memory components concentrates among a limited pool of specialized technicians.
- EU MDR Technical Documentation Burden:Legacy product line recertification demands substantial clinical data generation for devices with decade-long commercial histories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interventional Cardiology and Peripheral Vascular Devices Market |
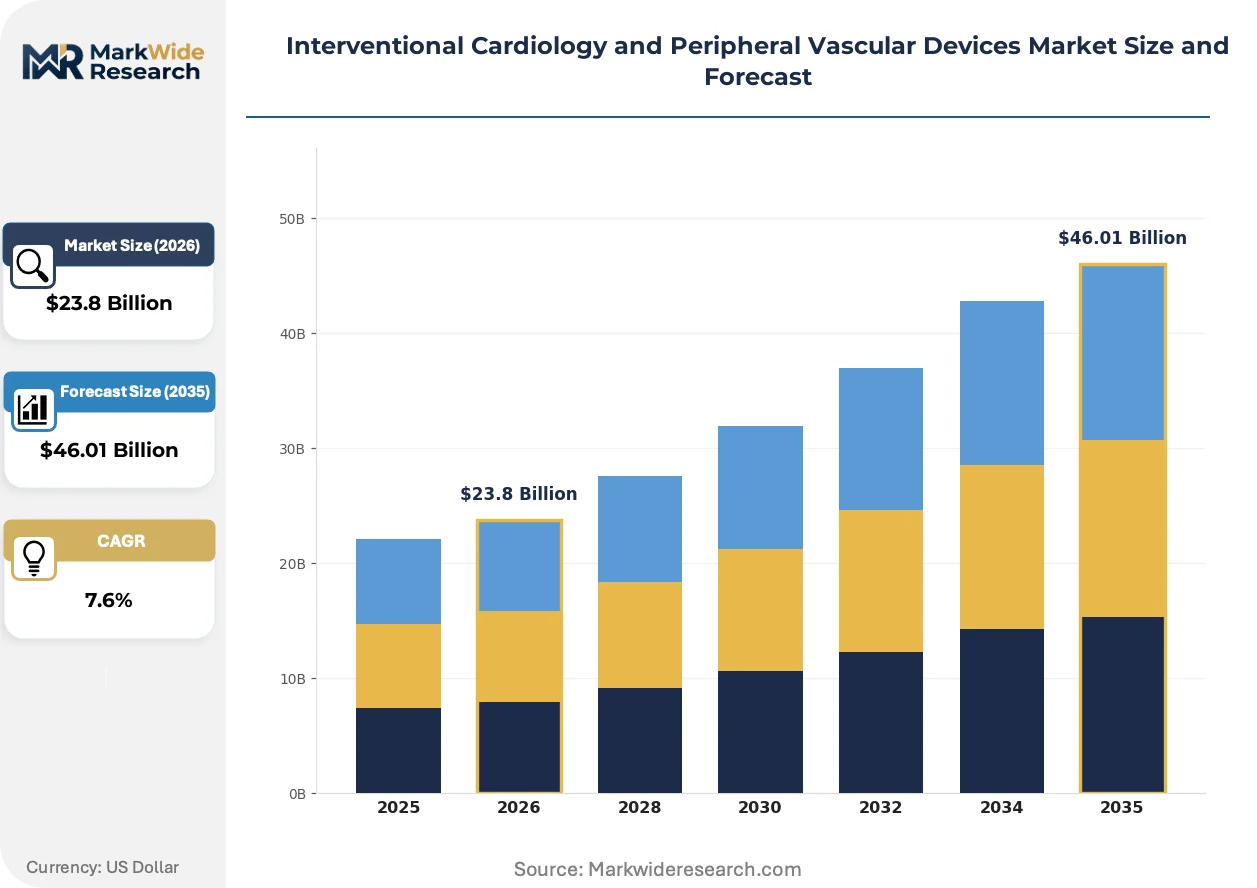
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $46.01 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Balloons, Catheters, Guidewires End User: Hospitals, Ambulatory Surgical Centers, Cardiology Clinics, Rehabilitation Centers Technology: Drug-Eluting Stents, Bioabsorbable Stents, Angioplasty Balloons, Vascular Closure Devices Application: Coronary Intervention, Peripheral Intervention, Structural Heart Diseases, Congenital Heart Defects |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott Laboratories, Johnson & Johnson, Terumo Corporation, B. Braun Melsungen AG, Edwards Lifesciences Corporation, Koninklijke Philips N.V., Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interventional Cardiology and Peripheral Vascular Devices Market Emerging Trajectories
Computational modeling and advanced materials science are compressing product development cycles while enabling patient-specific device geometries previously unattainable through conventional manufacturing.
Intravascular imaging modalities including optical coherence tomography and intravascular ultrasound are converging with robotic catheter navigation systems to enable precise lesion characterization and stent placement optimization. Interventional cardiologists in high-volume United States centers increasingly demand integrated imaging-therapeutic platforms. This convergence is compressing the learning curve for complex PCI while raising capital equipment requirements for competitive catheterization laboratory operations.
EU MDR post-market surveillance requirements now mandate systematic literature review and periodic safety update reporting for all class III cardiovascular devices. Manufacturers face expanded clinical follow-up obligations and notified body audit frequency. Stent and balloon producers with legacy product portfolios bear disproportionate compliance costs as they regenerate technical documentation for devices commercialized under prior directives.
Hospital procurement committees increasingly unbundle device selection from physician preference item status, centralizing vendor negotiations through value analysis teams. Cardiovascular service line administrators in Germany and Japan now mandate head-to-head clinical evidence comparisons for stent platform selection. This behavioral shift concentrates purchasing power among integrated delivery networks while compressing price differentiation opportunities for manufacturers lacking robust health economic data.
Interventional Cardiology and Peripheral Vascular Devices Market Segmentation
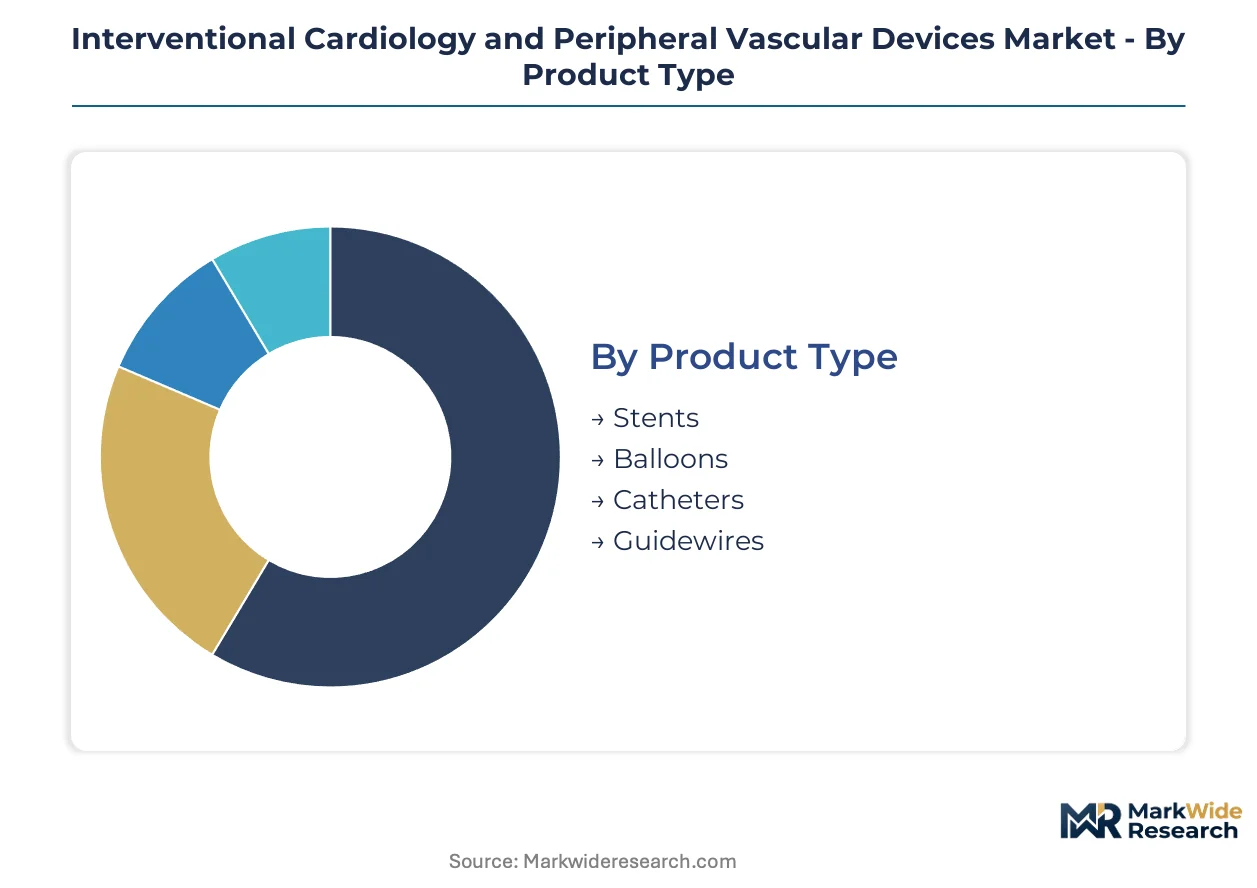
Device segmentation in interventional cardiology and peripheral vascular markets reflects divergent technical requirements across anatomical territories. Material specifications, delivery system profiles, and therapeutic mechanisms determine product-market fit and reimbursement positioning.
Product Type:
Component engineering specifications dictate manufacturing complexity and supply chain configuration.
- Stents:Laser-cut metallic platforms from cobalt-chromium or platinum-chromium alloys provide radial strength for vessel scaffolding. Demand concentrates in United States hospitals where transcatheter procedures dominate revascularization protocols, though bioabsorbable variants face commercial constraints from extended follow-up requirements.
- Balloons:Polyamide or polyethylene terephthalate balloon membranes undergo blow-molding to achieve precise compliance curves for lesion dilatation. Germany and Japan drive demand for low-profile and drug-coated balloon alternatives in below-the-knee interventions.
- Catheters:Multi-layer shaft constructions combining stainless steel hypotubes with polymer jacketing enable torque transmission through tortuous anatomy.
- Guidewires:Nitinol core wires with hydrophilic or hydrophobic coatings provide trackability across calcified lesions.
Stents lead on scale; balloons lead on momentum.
End User:
Procurement authority and capital equipment requirements shape vendor contracting dynamics.
- Hospitals:Integrated catheterization laboratories with fixed angiography systems generate the highest procedure volumes and device consumption. Value analysis committees in United States health systems increasingly centralize vendor negotiations away from physician preference item status.
- Ambulatory Surgical Centers:Lower-acuity peripheral interventions migrate to outpatient settings where reimbursement differentials favor same-day discharge protocols. United States ASCs expand catheter-based limb salvage capabilities as surgeon ownership models proliferate.
- Cardiology Clinics:Diagnostic angiography and follow-up care concentrate in specialty practice settings without interventional capabilities.
- Rehabilitation Centers:Post-interventional monitoring and secondary prevention programs manage patient compliance.
Hospitals dominate absolute volume; ambulatory surgical centers climb fastest.
Technology:
Therapeutic mechanism and biocompatibility profile determine regulatory pathway and clinical evidence burden.
- Drug-Eluting Stents:Polymer matrices incorporating sirolimus analogs or paclitaxel inhibit neointimal hyperplasia. FDA premarket approval pathways govern commercialization in the United States, while EU MDR clinical evidence requirements extend conformity assessment timelines.
- Bioabsorbable Stents:Magnesium alloy or polymeric scaffolds provide temporary scaffolding without permanent metal caging. Japan's PMDA Sakigake pathway accelerates priority review for first-in-class devices in this category.
- Angioplasty Balloons:Plain old balloon angioplasty and drug-coated alternatives address distinct lesion morphologies.
- Vascular Closure Devices:Collagen plugs, suture-mediated systems, and clip-based technologies enable femoral access site hemostasis.
Drug-eluting stents lead on scale; bioabsorbable stents lead on momentum.
Application:
Anatomical territory and disease pathology dictate device selection and operator training requirements.
- Coronary Intervention:Percutaneous coronary intervention for atherosclerotic disease retains the highest procedure frequency globally. United States academic medical centers drive demand for intravascular imaging-integrated platforms.
- Peripheral Intervention:Femoropopopliteal and below-the-knee disease treatment represents the steepest expansion trajectory. Germany and Japan demonstrate rising intervention volumes driven by diabetic foot ulcer complications and aging demographics.
- Structural Heart Diseases:Transcatheter aortic valve replacement and mitral repair procedures require specialized delivery systems.
- Congenital Heart Defects:Pediatric interventional procedures demand size-scaled device platforms.
Coronary intervention leads on scale; peripheral intervention leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production and clinical trial operations toward jurisdictions offering streamlined regulatory pathways and differentiated reimbursement structures. The FDA's Breakthrough Device Designation and Japan's PMDA Sakigake pathway attract development investment despite higher absolute compliance costs. Germany's EU MDR implementation timeline and India's emerging procedural volume create divergent market entry strategies.
United States
Academic medical centers in Cleveland and Houston drive demand for intravascular imaging-integrated platforms and robotic catheter navigation systems. FDA premarket approval pathways govern commercialization of drug-eluting stents and structural heart delivery systems, with Breakthrough Device Designation compressing review timelines for novel interventions. The Minneapolis-St. Paul corridor hosts concentrated nitinol processing and catheter shaft manufacturing capabilities serving the cardiovascular device value chain.
Germany
Rising femoropopliteal and below-the-knee intervention volumes in Bavaria and Baden-Württemberg propel demand for low-profile balloon platforms and drug-coated alternatives. EU MDR technical documentation requirements and extended conformity assessment timelines delay renewal certifications for legacy stent systems. The Rhine-Main cluster around Frankfurt maintains specialized electropolishing and laser-cutting capabilities for shape-memory alloy components.
Japan
Aging demographics and diabetic foot ulcer complications in the Kanto and Kansai regions accelerate peripheral vascular procedure adoption. PMDA shonin approval processes impose local clinical study obligations that filter market entrants, while the Sakigake pathway accelerates priority review for first-in-class bioabsorbable stent technologies. Tokyo-based medical device distributors increasingly mandate head-to-head clinical evidence comparisons for stent platform selection.
India
Limited vascular surgeon density and rising diabetic foot ulcer complications in Maharashtra and Gujarat create whitespace for catheter-based limb salvage procedures. CDSCO medical device regulations and import licensing requirements shape product registration strategies for multinational manufacturers. The Hyderabad-Bengaluru corridor attracts contract manufacturing investment for polymer-jacketed catheter shafts and guidewire core wire processing.
Switzerland
Swissmedic regulatory frameworks and proximity to EU markets position Basel and Zurich as strategic headquarters for cardiovascular device development. Precision polymer science and bioresorbable scaffold research concentrate in the Lake Geneva region, leveraging established pharmaceutical manufacturing infrastructure. Swiss notified bodies serve as conformity assessment intermediaries for EU MDR certification of class III cardiovascular devices.
Interventional Cardiology and Peripheral Vascular Devices Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bioabsorbable scaffold platforms and integrated imaging-therapeutic systems. The market structure concentrates among diversified medical technology conglomerates with captive supply of nitinol components and in-house polymer science capabilities. Three archetypes dominate: vertically integrated device manufacturers controlling critical raw material processing, imaging-therapy convergence specialists, and regional contract manufacturers serving unbranded distribution channels. Competitive dynamics center on M&A activity targeting specialized electropolishing and laser-cutting capabilities, alongside strategic partnerships between stent platform developers and intravascular imaging system manufacturers.
Among US-based diversified medical technology corporations, Medtronic, Boston Scientific Corporation, and Abbott Laboratories anchor the competitive landscape through their representation of distinct strategic archetypes. Medtronic exemplifies vertical integration into structural heart delivery systems through captive nitinol component supply. Boston Scientific Corporation occupies a position emphasizing balloon molding capabilities and catheter shaft manufacturing integration. Abbott Laboratories anchors the drug-eluting stent segment through in-house polymer matrix development. These three entities collectively illustrate the range of backward integration strategies and therapeutic platform diversification patterns characterizing the standard tier.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Johnson & Johnson |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Edwards Lifesciences Corporation |
| Koninklijke Philips N.V. |
| Cook Medical |
| Others |
Supply Flow & Price Mechanics
Computational modeling adoption in catheter shaft design is compressing prototyping cycles while concentrating manufacturing expertise among nitinol processing specialists in the Minneapolis-St. Paul corridor. This dual effect simultaneously reduces per-unit development overhead and reinforces supplier pricing power for shape-memory alloy components.
Pricing Analysis
Hospital GPO contract structures anchor the dominant pricing model, with three-tier pricing stratification across premium imaging-integrated platforms, standard drug-eluting stent systems, and economy bare-metal alternatives. FDA Breakthrough Device Designation and EU MDR certification tier create the primary price differentiation drivers, alongside volume scale commitments from integrated delivery networks. Cost compression in the standard tier is intensifying because multi-source procurement mandates from United States health systems force head-to-head clinical evidence comparisons. Ambulatory surgical centers exhibit the highest price sensitivity due to reimbursement differentials favoring same-day discharge protocols, while academic medical centers prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Nitinol shape-memory alloy supply rests on specialty melt shops concentrated in the United States, Germany, and Japan, with laser-cutting and electropolishing capabilities further narrowing to the Minneapolis-St. Paul and Rhine-Main clusters. Raw material dependencies span cobalt-chromium alloys for stent platforms, polyamide balloon membranes, and polymer jacketing compounds for catheter shafts. Single-source vulnerability for electropolishing expertise creates structural risk as technician scarcity limits capacity expansion. Distribution runs through hospital value analysis committees and GPO contracting vehicles, with direct-to-hospital arrangements gaining share among high-volume academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between the FDA's expedited Breakthrough Device pathway and Japan's PMDA Sakigake priority review, where differential regulatory timelines compress time-to-revenue for innovators willing to absorb higher absolute compliance costs.
For Market Incumbents: Cement captive supply of nitinol components through acquisition of specialized laser-cutting and electropolishing capabilities in the Minneapolis-St. Paul corridor. Secure EU MDR technical documentation regeneration for legacy stent portfolios before conformity assessment bottlenecks freeze product line extensions. Bioabsorbable scaffold platforms from emerging polymer science specialists threaten drug-eluting stent market share; backward integration into magnesium alloy processing is the critical defensive lever. For New Entrants and Emerging Players: Begin with India's underpenetrated peripheral vascular segment, where limited vascular surgeon density and rising diabetic foot ulcer complications in Maharashtra and Gujarat create whitespace for catheter-based limb salvage procedures. Target ambulatory surgical centers in the United States with low-profile balloon platforms optimized for same-day discharge reimbursement protocols. A software companion development strategy integrating intravascular imaging data with robotic navigation systems offers the strongest go-to-market angle against entrenched imaging-therapy convergence specialists. For Investors and Strategic Acquirers: Valuations sit cheapest among regional contract manufacturers serving unbranded distribution channels in the Hyderabad-Bengaluru corridor, where CDSCO regulatory alignment with EU MDR standards creates export-ready capacity. The five-to-ten year viability window favors acquisition targets with demonstrated nitinol processing expertise and established notified body relationships for class III cardiovascular device certification. Watch EU MDR post-market surveillance enforcement intensity as the inflection indicator for compliance cost repricing across legacy product portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Expedited review compresses commercialization timelines for novel structural heart interventions targeting high-risk patient populations. |
| EU MDR Technical Documentation Regeneration | Legacy stent system recertification demands substantial clinical data generation for decade-long commercial histories. |
| Hospital System Partnership Formation | Value analysis committee relationships secure vendor status as procurement authority centralizes away from physician preference items. |
| Software Companion Development | Intravascular imaging-therapeutic platform integration raises capital equipment requirements for competitive catheterization laboratory operations. |
| Reimbursement Strategy Investment | Coding revisions for transcatheter procedures and health technology assessment criteria determine hospital procurement budgets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA premarket approval filings, EU MDR technical documentation databases, CMS Medicare procedure volume data, and Japanese PMDA shonin approval records. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Segment-weighting approaches distributed value across stent platforms, balloon systems, catheter shafts, and guidewire categories, with further stratification by drug-eluting versus bioabsorbable technology tiers, coronary versus peripheral application territories, and hospital versus ambulatory surgical center end-use settings. CAGRs were derived from procedure volume elasticity to aging demographic penetration and reimbursement access expansion across the analysis window. Forecast inputs incorporated EU MDR conformity assessment timeline delays and Japan PMDA Sakigake pathway utilization rates.
Several conditions sit outside the modeled scope, including cobalt-chromium alloy spot price volatility, sudden FDA guidance revisions for bioabsorbable scaffolds, and geopolitical disruptions to nitinol raw material flows. Forecasts reflect documented assumptions about regulatory pathway stability and hospital capital expenditure continuity. A small set of named triggers warrants ongoing watch: EU MDR notified body capacity constraints, India CDSCO import licensing acceleration, and United States Medicare reimbursement coding shifts for transcatheter structural heart procedures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electrophysiology Market
Medical Devices
Smart Wheelchairs Market
Medical Devices
Global Hernia Mesh Devices Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
Indonesia Devices Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Global Medical Loupes Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
France Respiratory Devices Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Peripheral Interventions Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Automatic Pill Dispenser Machine Market