
 Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market | 2026-2036
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market Outlook
Hospital procurement channels across the Asia-Pacific region is fragmenting as public tender systems decentralize and private hospital chains build direct manufacturer relationships. Medtronic Corporation leverages its established service infrastructure to sustain long-term equipment contracts across tertiary hospitals. Fisher & Paykel Healthcare Limited anchors its position through specialized humidification technology integrated into ventilation circuits. GE Healthcare competes on imaging-ventilation convergence platforms that occupy the premium tier of integrated critical care suites.
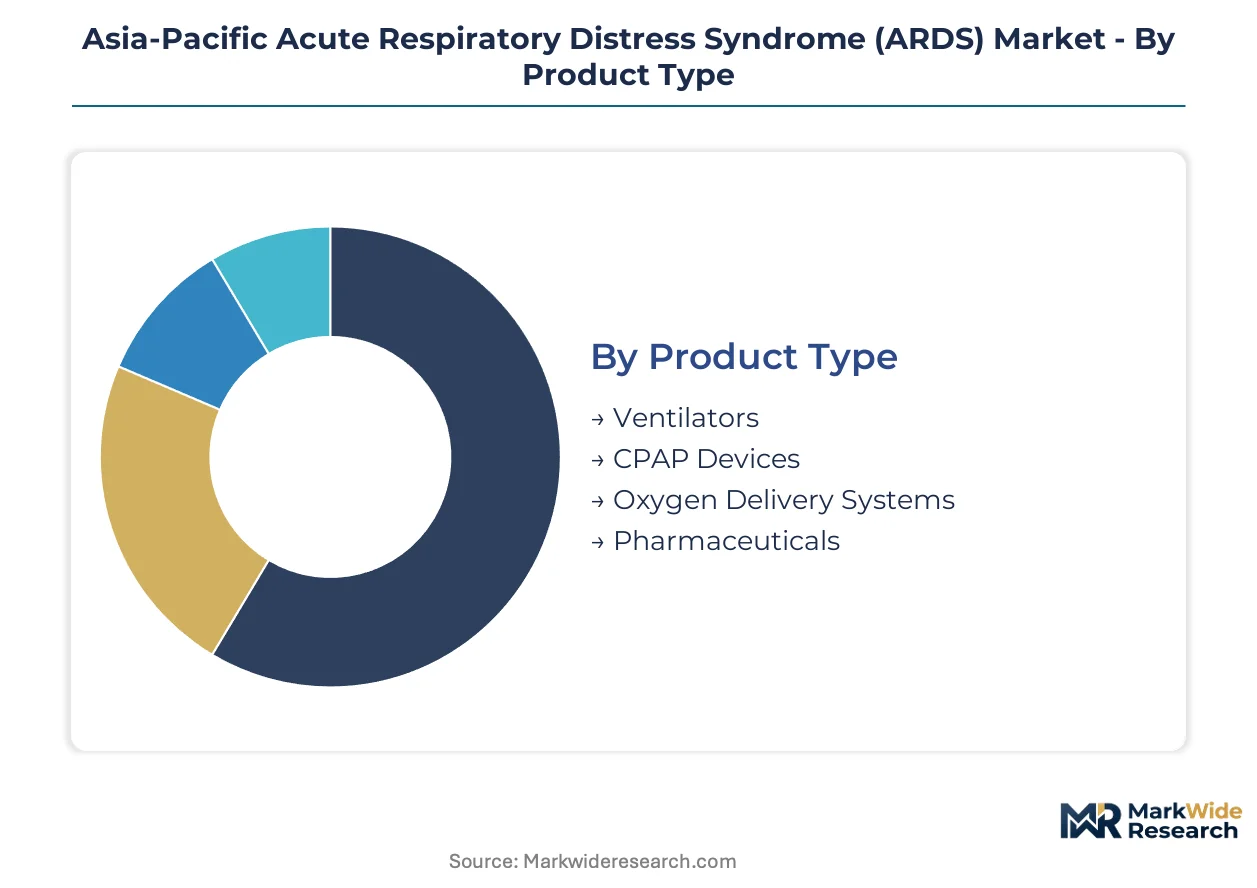
Acute Respiratory Distress Syndrome constitutes a life-threatening inflammatory lung injury characterized by bilateral pulmonary infiltrates, severe hypoxemia with a PaO2/FiO2 ratio below 300 mmHg, and non-cardiogenic pulmonary edema requiring positive pressure mechanical ventilation. The syndrome demands rapid intervention through lung-protective ventilation strategies, prone positioning, and adjunctive pharmacotherapy to reduce mortality in intensive care settings. Ventilators command the largest revenue share among product types due to capital intensity and recurring consumables revenue, while oxygen delivery systems represent the fastest-expanding category as point-of-care and transport applications multiply. Hospitals absorb the dominant share of end-user spending, though home care providers are gaining traction in Japan and Australia where post-ICU respiratory rehabilitation protocols are extending care continuity beyond acute facilities.
Japan's PMDA, Australia's TGA, and India's CDSCO collectively shape device approval pathways, with PMDA's stringent clinical evidence requirements filtering market access for novel ventilation modes while CDSCO's accelerated emergency use pathways compress time-to-market for essential respiratory equipment. The EU-MDR alignment pressures from Australia's TGA are raising documentation burdens for European manufacturers serving the region. Stakeholders must monitor divergent reimbursement timelines across national health insurance schemes as these determine effective addressable market expansion regardless of regulatory clearance status.
Market Dynamics
Post-pandemic respiratory preparedness mandates across Southeast Asia are forcing accelerated ICU infrastructure replacement cycles, compressing equipment procurement timelines from 18-24 months to 8-12 months while elevating technical specifications for ventilator performance and interoperability.
Growth Catalysts
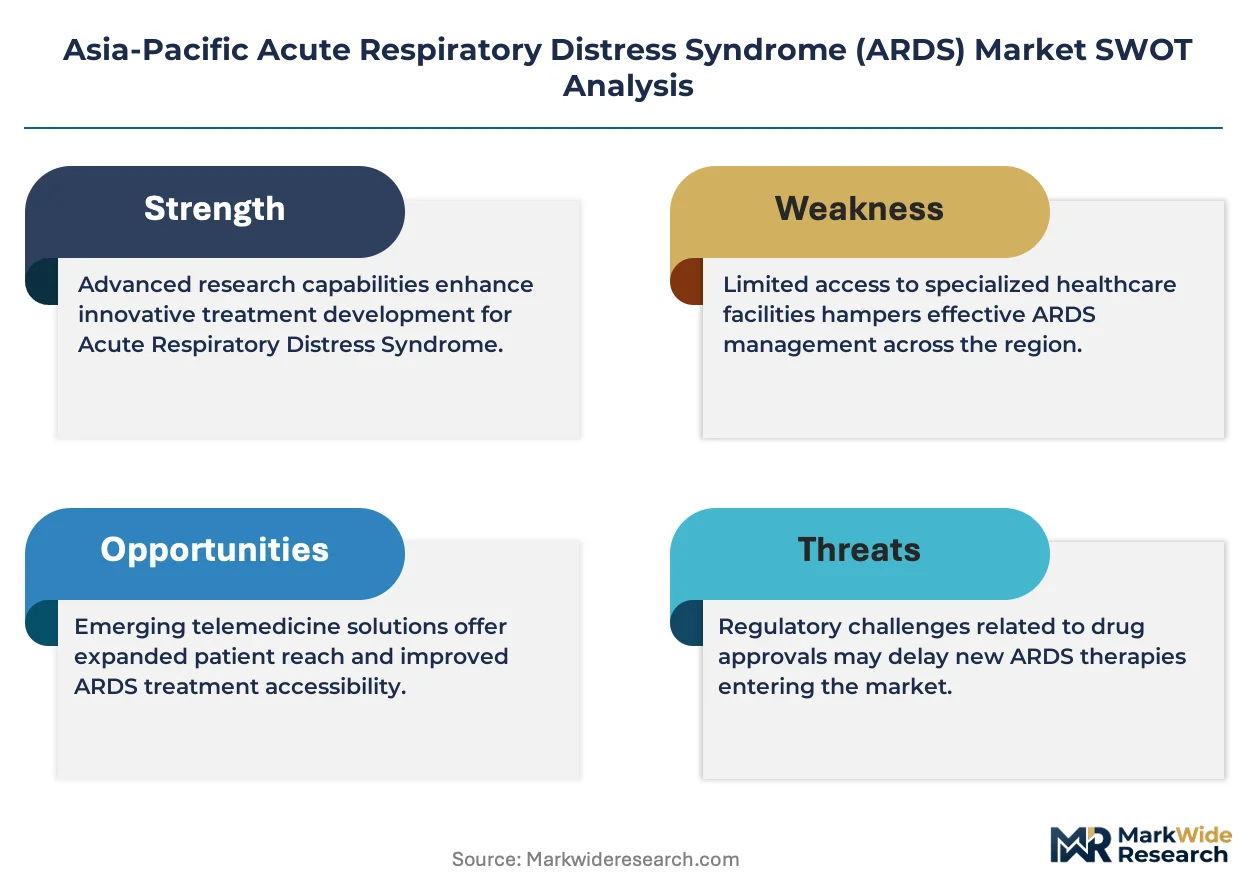
- Japan's PMDA ventilator performance standards:Tightened technical requirements are accelerating replacement demand across tertiary hospitals as legacy equipment fails new compliance thresholds.
- India's ICU infrastructure tenders:Centralized government procurement is consolidating fragmented demand into high-volume contracts that reshape manufacturer access patterns.
- Humidification-integrated ventilation circuits:Specialized respiratory circuit technology is reducing ventilator-associated pneumonia rates and driving premium equipment specification in critical care suites.
Market Restraints
- Semiconductor component concentration:Ventilator control systems depend on concentrated Asian semiconductor supply nodes, creating vulnerability to input disruption and price volatility.
- PMDA clinical evidence requirements:Japan's stringent pre-market approval pathways filter access for novel ventilation modes, extending time-to-revenue for innovative products.
- High-fidelity simulation substitution:Advanced respiratory simulation platforms are reducing live-patient training ventilator demand in academic medical centers.
Strategic Opportunities
- Indonesia's archipelago logistics gap:Underpenetrated outer island hospital networks present white space for portable oxygen delivery system deployment.
- Home care channel expansion:Post-ICU respiratory rehabilitation protocols in Japan and Australia are extending equipment rental and service revenue beyond acute facilities.
- EU-MDR alignment by Australia's TGA:Documentation burden harmonization creates competitive opening for European manufacturers already compliant with convergent standards.
Industry Challenges
- Critical care respiratory therapist scarcity:Specialized ventilation management expertise shortages in India and Southeast Asia constrain effective equipment utilization rates.
- Legacy system integration complexity:New ventilation platforms face interoperability friction with existing hospital information systems and patient monitoring architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market |
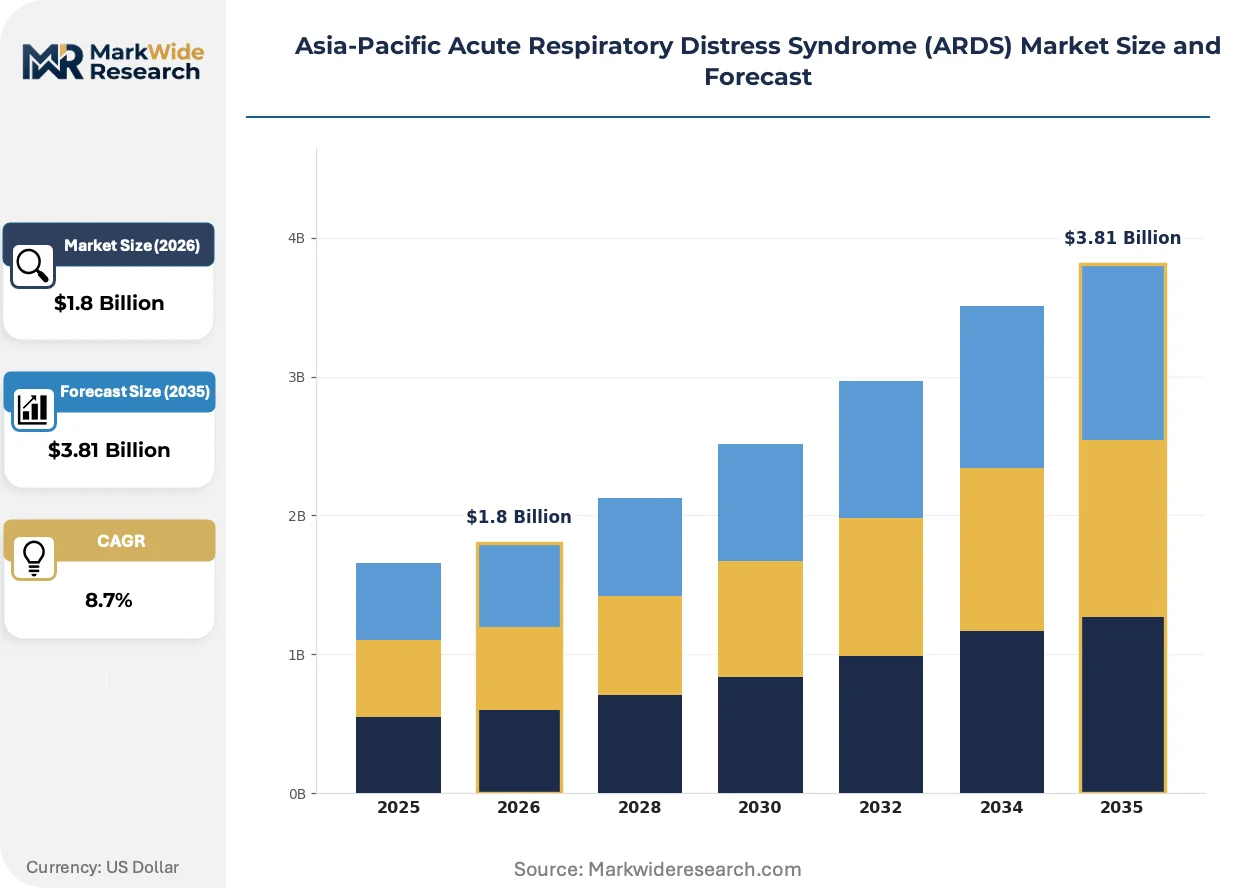
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, CPAP Devices, Oxygen Delivery Systems, Pharmaceuticals End User: Hospitals, Home Care Providers, Long-term Care Facilities, Emergency Services Delivery Mode: Intravenous, Inhalation, Enteral, Topical Indication: Infection, Trauma, Aspiration, Cardiogenic Shock |
| Companies Covered | Medtronic Corporation, GE Healthcare, Fisher & Paykel Healthcare Limited, LivaNova PLC, Drägerwerk AG & Co. KGaA, Getinge AB, Hamilton Company, HEALIOS K.K., Faron Pharmaceuticals, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market Strategic Shifts
Ventilation technology is converging with imaging and data analytics platforms, while regulatory frameworks and procurement architectures undergo parallel transformation across the Asia-Pacific region.
Adaptive lung-protective ventilation algorithms are hybridizing conventional pressure-control modes with real-time compliance monitoring. Tertiary hospitals in Japan and South Korea are adopting these systems at accelerated pace. This convergence is compressing differentiation margins for standalone ventilator manufacturers while elevating integrated critical care suite providers.
Australia's TGA is implementing EU-MDR documentation alignment requirements that raise technical file burdens for European device suppliers. This regulatory friction is filtering market access for smaller manufacturers lacking dedicated regulatory affairs capacity. Australian hospital procurement teams are responding by consolidating supplier lists toward established multinationals with pre-existing MDR compliance infrastructure.
Public tender decentralization across Southeast Asian health systems is fragmenting historically centralized procurement authority. Provincial health offices in Vietnam and Thailand are gaining direct contracting autonomy, displacing national ministry-level purchasing. This behavioral shift is most visible in Indonesia, where regional hospital associations now negotiate manufacturer-direct relationships bypassing traditional distributor networks.
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market Segmentation
ARDS treatment pathways fragment across acute intervention, chronic management, and transitional care stages. Equipment replacement cycles and reimbursement eligibility vary dramatically by segment, reshaping manufacturer portfolio priorities across the Asia-Pacific region.
Product Type:
Ventilators turn over slowest due to capital intensity and service contract lock-in, while oxygen delivery systems refresh fastest as portable technology advances.
- Ventilators:Positive pressure mechanical ventilation systems with lung-protective algorithms dominate ICU capital budgets. Japanese tertiary hospitals drive replacement demand as PMDA compliance deadlines force legacy equipment retirement.
- Oxygen Delivery Systems:Nasal cannulas, high-flow nasal oxygen devices, and portable concentrators are expanding fastest across Southeast Asian district hospitals. Indonesia's outer island logistics gaps create urgent demand for battery-powered transportable units.
- CPAP Devices:Non-invasive ventilation support for pre-ARDS respiratory failure bridges hospital and home settings in Australia and Japan.
- Pharmaceuticals:Neuromuscular blockade agents, corticosteroids, and pulmonary surfactants complete the adjunctive therapy arsenal in intensive care protocols.
Ventilators anchor the volume base while oxygen delivery systems gain share at the steepest rate.
End User:
Customer concentration spans centralized government procurement in India, fragmented private hospital chains in Thailand, and emerging home care rental networks in Japan.
- Hospitals:Tertiary critical care suites absorb the dominant equipment spend across the region. India's centralized ICU infrastructure tenders consolidate demand into high-volume contracts that reshape manufacturer access patterns.
- Home Care Providers:Post-ICU respiratory rehabilitation protocols in Japan and Australia extend equipment rental revenue beyond acute facilities. Long-term oxygen therapy and non-invasive ventilation home programs are expanding fastest.
- Long-term Care Facilities:Sub-acute respiratory step-down units in South Korea and Taiwan manage ventilator weaning and tracheostomy-dependent patients.
- Emergency Services:Pre-hospital airway management and transport ventilation capability varies widely across Southeast Asian ambulance networks.
Hospitals retain the dominant spend share while home care providers expand most quickly as post-acute protocols lengthen.
Delivery Mode:
Route selection depends on patient consciousness level, gastrointestinal function, and required drug pharmacokinetics in critical care settings.
- Intravenous:Direct vascular administration of sedatives, neuromuscular blockers, and vasoactive agents achieves rapid effect in hemodynamically unstable ARDS patients.
- Inhalation:Nebulized bronchodilators, corticosteroids, and pulmonary surfactants target alveolar deposition with reduced systemic exposure.
- Enteral:Nasogastric or post-pyloric feeding tubes deliver nutrition and selected medications in ventilated patients with preserved gut perfusion.
- Topical:Limited application for chest physiotherapy adjuncts and skin integrity management in prolonged prone positioning protocols.
Intravenous administration dominates acute intervention while inhalation therapy climbs fastest as targeted lung delivery technology advances.
Indication:
Underlying etiology shapes prognosis, ventilation strategy selection, and mortality risk stratification in intensive care triage.
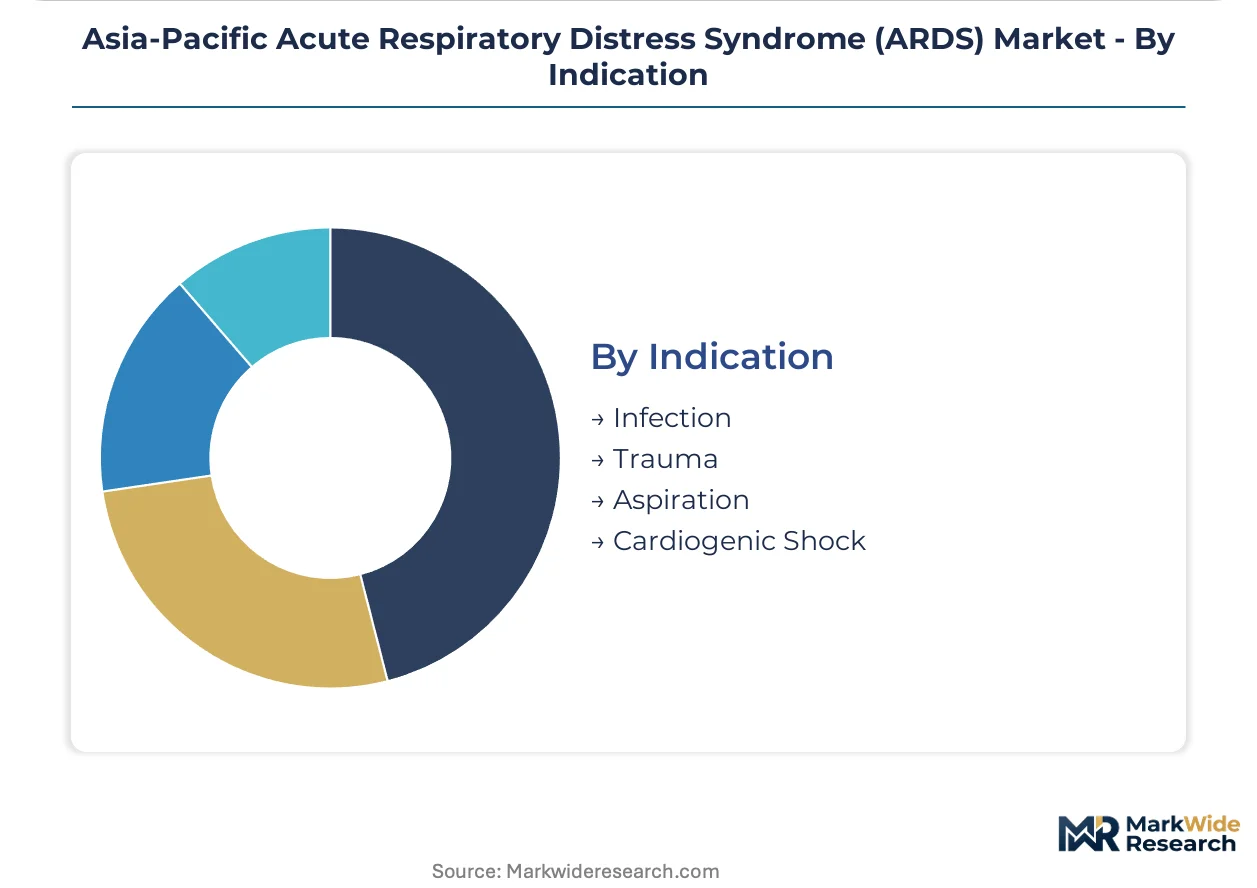
- Infection:Pneumonia and sepsis-related ARDS constitutes the predominant presentation across tropical Southeast Asia. Viral respiratory pathogens and hospital-acquired bacterial infections drive seasonal demand surges.
- Trauma:Pulmonary contusion, fat embolism, and massive transfusion-related lung injury concentrate in tertiary referral centers with trauma surgery capability.
- Aspiration:Gastric content aspiration events require rapid airway protection and bronchoscopic clearance in emergency departments.
- Cardiogenic Shock:Differentiation from hydrostatic pulmonary edema demands echocardiographic assessment and invasive hemodynamic monitoring.
Infection-related ARDS anchors the patient volume base while trauma indication gains share fastest as regional trauma system maturity advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-ASEAN Gas Pipeline network and Singapore-Johor Bahru high-capacity grid interconnection underpin respiratory equipment distribution across Southeast Asian hospital networks. Japan's Kanto region and Australia's eastern seaboard anchor premium-tier demand through advanced critical care infrastructure.
Japan
PMDA ventilator performance standards are accelerating replacement cycles across tertiary hospitals in Tokyo and Osaka. METI's medical device quality certification program filters market access for novel ventilation modes. The Kanto cluster concentrates procurement authority for lung-protective ventilation platforms.
India
Centralized ICU infrastructure tenders are consolidating fragmented demand into high-volume government contracts. CDSCO's accelerated emergency use pathways compress time-to-market for essential respiratory equipment. Maharashtra and Karnataka state health authorities drive district hospital oxygen delivery system deployment.
Australia
TGA's EU-MDR documentation alignment is raising technical file burdens for European device suppliers. Post-ICU respiratory rehabilitation protocols extend equipment rental revenue beyond acute facilities. New South Wales and Victoria health networks lead home care channel expansion for long-term oxygen therapy.
South Korea
MFDS medical device approval pathways shape ventilator market access timelines for integrated critical care suites. Sub-acute respiratory step-down units in Seoul Capital Area manage ventilator weaning and tracheostomy-dependent patients. The Busan-Ulsan corridor concentrates manufacturing capacity for humidification-integrated ventilation circuits.
Indonesia
Regional hospital associations negotiate manufacturer-direct relationships bypassing traditional distributor networks. Underpenetrated outer island hospital networks present white space for portable oxygen delivery system deployment. Java-Bali logistics infrastructure supports battery-powered transportable unit distribution to district facilities.
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market Competitive Environment
On the supply side, the industry is consolidating around integrated critical care suite providers and specialized respiratory technology developers. Three strategic archetypes dominate: multinational conglomerates with service infrastructure depth, specialized humidification and ventilation circuit innovators, and regional champions with government tender relationships. Competitive moves center on imaging-ventilation convergence platform development and direct procurement relationship cultivation with decentralized health authorities.
Within the multinational service infrastructure tier, Medtronic Corporation and GE Healthcare exemplify established tertiary hospital contract models. Fisher & Paykel Healthcare Limited occupies a specialized position through respiratory circuit technology integration. These three anchors demonstrate how equipment manufacturers leverage distinct capability configurations—service networks, imaging convergence, and humidification specialization—to secure procurement channel access across fragmented Asia-Pacific health systems.
| Leading Market Players |
|---|
| Medtronic Corporation |
| GE Healthcare |
| Fisher & Paykel Healthcare Limited |
| LivaNova PLC |
| Drägerwerk AG & Co. KGaA |
| Getinge AB |
| Hamilton Company |
| HEALIOS K.K. |
| Faron Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Semiconductor fabrication concentration across Taiwan and South Korea anchors ventilator control system costs, concentrating margin capture upstream while downstream equipment manufacturers absorb input price volatility through long-term service contract structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the Asia-Pacific ARDS equipment market. PMDA-certified lung-protective ventilation platforms command premium positioning against CDSCO-registered essential equipment and unbranded economy alternatives. Price differentiation rests on regulatory certification tier and bundled after-sales service depth. Cost compression in the economy tier is intensifying because India's centralized tenders consolidate volume purchasing power. Government procurement committees exhibit highest price sensitivity; Japanese tertiary hospitals demonstrate lowest sensitivity due to compliance-driven replacement mandates.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for semiconductor-dependent ventilator manufacturers. Component sourcing concentrates in Taiwan, South Korea, and Japan for precision sensors and control modules. Raw material dependencies span medical-grade aluminum for chassis fabrication, silicone polymers for respiratory circuits, and rare earth elements for magnetic motor assemblies. Single-source vulnerability persists for specialized humidification membranes. Distribution runs through regional hospital procurement consortia and government tender platforms rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through India's centralized ICU infrastructure tenders and Japan's PMDA-mandated replacement waves, fragmenting procurement access for manufacturers lacking direct government relationships.
For Market Incumbents: Harden service infrastructure lock-in through multi-year preventive maintenance contracts that extend equipment lifecycle revenue. Deepen backward integration into humidification circuit manufacturing to capture component margin pools. Emerging portable oxygen system specialists threaten standalone ventilator market share; certification investment in CDSCO fast-track pathways defends access to India's tender-driven volume. For New Entrants and Emerging Players: Indonesia's outer island district hospitals represent the most penetrable entry point for battery-powered oxygen delivery systems bypassing Java-centric distributor networks. Australia's home care respiratory rehabilitation channel offers secondary white-space for rental-based service models. A direct procurement relationship strategy with provincial health offices in Vietnam and Thailand circumvents entrenched national distributor structures. For Investors and Strategic Acquirers: Capital is best deployed toward specialized respiratory circuit technology developers with established PMDA technical files and existing OEM supply relationships. The long-term viability window favors platforms converging ventilation with imaging and analytics rather than standalone mechanical systems. Watch CDSCO emergency use pathway expansion velocity as the signal indicating India's procurement acceleration or deceleration.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Compliance Certification Investment | Accelerates replacement-driven revenue capture across Tokyo and Osaka tertiary hospital networks. |
| CDSCO Emergency Use Pathway Registration | Compresses time-to-revenue for essential respiratory equipment in India's government tenders. |
| Humidification Circuit Backward Integration | Captures component margin pools and reduces ventilator-associated pneumonia liability exposure. |
| Provincial Health Office Direct Contracting | Bypasses fragmented distributor networks in Indonesia's decentralized procurement environment. |
| Home Care Rental Service Platform Development | Extends revenue continuity beyond acute episodes in Japan's post-ICU rehabilitation protocols. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the primary research phase. Intensive care physicians, hospital biomedical engineers, and GPO contracts managers provided clinical utilization and procurement pattern insights. Ventilator manufacturer product managers and respiratory circuit engineering directors supplied technical specification and cost structure perspectives. Secondary validation drew from CDSCO device registration databases, PMDA approval summaries, Indian government e-procurement portals, and hospital capital expenditure disclosures. Bottom-up equipment unit forecasts triangulated against top-down healthcare infrastructure spending projections.
Calibration against historical replacement cycle data and regulatory deadline schedules anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user facility tier, delivery mode, and underlying ARDS etiology. CAGRs were derived from equipment installed base turnover rates and consumables attachment ratios. Forecast inputs incorporated PMDA compliance deadline phasing and India's district hospital oxygen system deployment targets.
Macroeconomic conditions sit as an overlay; deviation in public health emergency frequency, semiconductor input pricing, or national health insurance reimbursement timelines would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and procurement decentralization velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Lung Injury Market
Respiratory Care
Asthma and COPD Drugs Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Lung Management Products Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Chronic Refractory Cough Treatment Market
Respiratory Care
Ventilator-Associated Pneumonia (VAP) Market
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Global Respiratory Care Devices Market