
 Plethysmograph Market | 2026-2036
Plethysmograph Market Size, Share, and Industry Trends Forecast 2026-2036
Plethysmograph Market Outlook
Direct hospital procurement is narrowing as group purchasing organizations consolidate plethysmograph contracting across multi-hospital systems. Vyaire Medical leverages its intensive care ventilation heritage to anchor high-acuity plethysmography placements in academic medical centers. COSMED srl competes through portable body plethysmography systems that extend reach into outpatient pulmonology clinics. SCHILLER AG sustains European market presence through cardiopulmonary diagnostics integration that positions combined stress testing and plethysmography platforms.
A plethysmograph measures volume changes in body compartments, typically employing sealed chambers with pressure transducers detecting thoracic displacement during respiration at sensitivities reaching 0.1 mL resolution. The device serves clinical and research applications requiring precise lung volume determination, including airway resistance quantification and functional residual capacity measurement. Digital product architecture dominates installed bases while wearable plethysmography segments attract R&D investment for ambulatory respiratory monitoring. Optical technology leads technology segmentation due to pulse oximetry adjacency, though pneumatic whole-body systems retain margin concentration in hospital settings where reimbursement ties to complete pulmonary function test bundles.
FDA 510(k) premarket notification requirements govern plethysmograph device authorization in the United States, while the EU Medical Device Regulation mandates notified body conformity assessment for European market access. ISO 26782 standards for spirometer and plethysmograph interoperability shape product development roadmaps across jurisdictions. Stakeholders must monitor evolving CPT code valuations for complete pulmonary function testing as reimbursement granularity determines equipment replacement cycles and capital allocation priorities.
Market Dynamics
Consolidation of hospital purchasing through group purchasing organizations is compressing vendor margins and forcing plethysmograph manufacturers to restructure their sales organizations around multi-hospital contract negotiations rather than individual facility placements.
Growth Catalysts
- Perioperative respiratory screening mandates:Surgical protocols at major health systems now require preoperative lung function assessment, embedding plethysmography into standard anesthesia workflows.
- ISO 26782 interoperability standards:Unified data formats between spirometers and plethysmographs reduce integration costs for pulmonary function test laboratories.
- Ambulatory monitoring demand:Wearable respiratory sensors enable continuous lung volume tracking outside hospital settings, expanding addressable patient populations.
Market Restraints
- Pressure transducer supply concentration:High-sensitivity displacement sensors rely on specialized MEMS foundries concentrated in East Asian manufacturing corridors.
- EU MDR conformity assessment bottlenecks:Extended notified body review timelines delay product launches and freeze R&D roadmaps for eighteen to twenty-four months.
- Optical pulse oximetry substitution:Low-cost fingertip sensors capture basic respiratory metrics for screening applications, eroding entry-level plethysmograph demand.
Strategic Opportunities
- Outpatient pulmonology clinic expansion:Portable body plethysmography systems reach community-based practices previously excluded by capital constraints.
- Home-based chronic disease management:Telehealth reimbursement codes now cover remote respiratory monitoring, creating direct-to-patient distribution channels.
- Cardiopulmonary stress testing convergence:Integrated platforms combining exercise protocols with complete lung function assessment command premium pricing in cardiac rehabilitation centers.
Industry Challenges
- Clinical engineering talent scarcity:Hospitals lack specialized biomedical technicians capable of calibrating sealed-chamber systems to 0.1 mL resolution specifications.
- 510(k) clinical evidence requirements:FDA demands extensive predicate device comparisons for novel plethysmograph designs, extending development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plethysmograph Market |
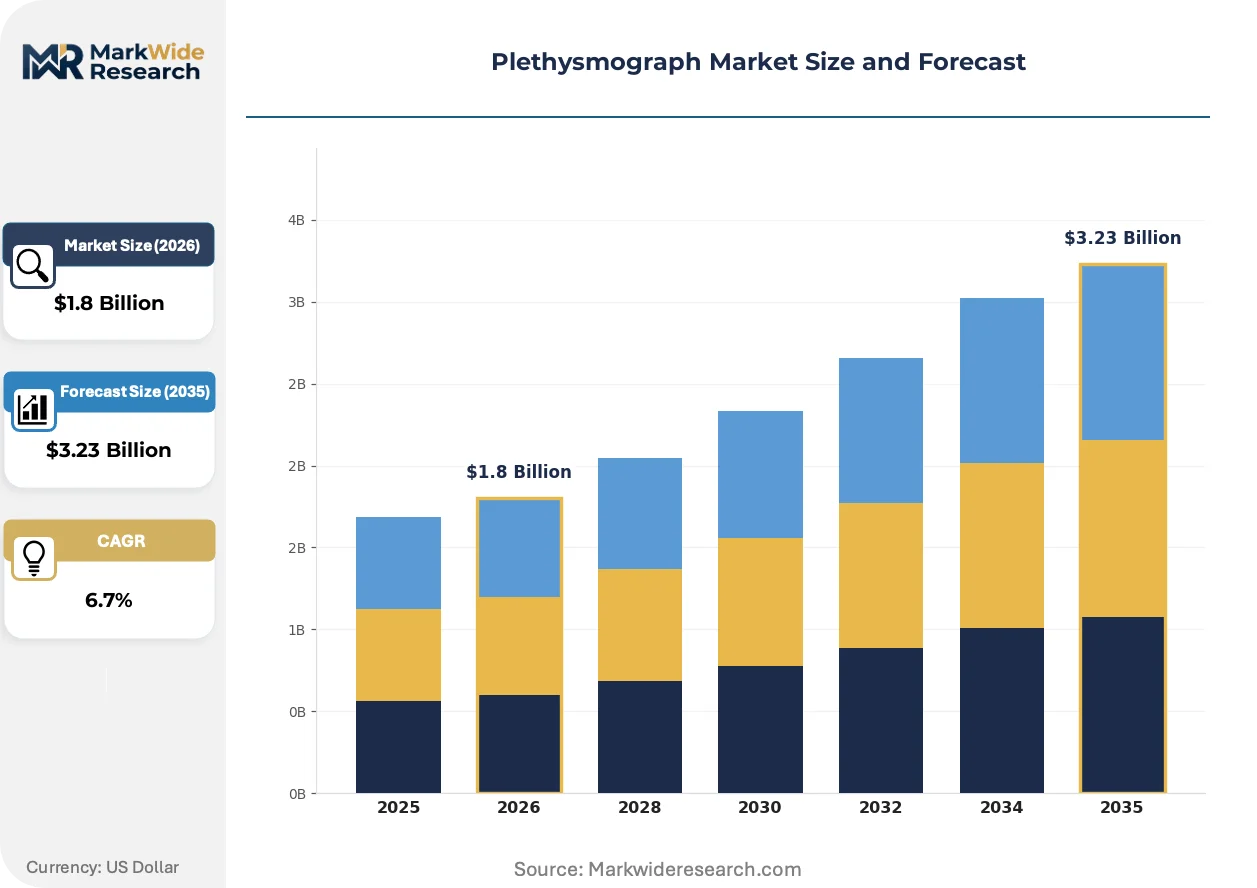
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Analog, Portable, Wearable End User: Hospitals, Clinics, Research Labs, Homecare Technology: Optical, Pneumatic, Electrical, Ultrasonic Application: Cardiology, Pulmonology, Sports Medicine, Rehabilitation |
| Companies Covered | Vyaire Medical Inc., COSMED srl, ACI Medical LLC, Geratherm Medical AG, MGC Diagnostics Corporation, Becton, Dickinson and Company, emka TECHNOLOGIES, D. E. Hokanson Inc., SCHILLER AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plethysmograph Market Strategic Shifts
Digital architecture and wearable form factors are fragmenting the traditional hospital-centric plethysmograph market, creating parallel demand tracks for high-acuity laboratory systems and decentralized ambulatory monitors.
Pneumatic whole-body plethysmography is hybridizing with optical sensing arrays to create dual-modality respiratory diagnostics. Academic medical centers in the United States deploy these hybrid systems for research protocols requiring simultaneous thoracic displacement and tissue oxygenation data. The convergence compresses capital equipment replacement cycles as institutions consolidate multiple diagnostic modalities onto single platforms.
The EU Medical Device Regulation's post-market surveillance requirements impose real-world performance tracking obligations on plethysmograph manufacturers. Device registries must capture clinical outcomes data across installed bases, increasing compliance overhead. European pulmonary function laboratories respond by standardizing on vendor platforms with embedded connectivity infrastructure.
Health system procurement committees now bundle plethysmography acquisitions with multi-year service contracts and predictive maintenance analytics. Group purchasing organizations negotiate these combined offerings across twenty to fifty hospital networks. The United States exhibits the most advanced bundling practices, with integrated delivery networks treating diagnostic equipment as managed service expenditures rather than capital assets.
Plethysmograph Market Segmentation
Plethysmograph procurement cycles vary dramatically across product architectures, with digital installations persisting seven to ten years while wearable formats refresh every eighteen to twenty-four months. Equipment replacement velocity shapes vendor revenue predictability and service contract structuring across the installed base.
Product Type:
Replacement cadence separates this category: sealed-chamber systems endure decade-long depreciation schedules while portable and wearable formats turn over fastest as sensor miniaturization accelerates.
- Digital:Microprocessor-controlled systems with integrated pressure transducers achieve 0.1 mL resolution for complete pulmonary function test suites. Hospital laboratories in the United States concentrate demand here as integrated delivery networks standardize on networked diagnostic platforms with embedded calibration protocols.
- Portable:Battery-powered body plethysmography units with reduced chamber volumes enable outpatient pulmonology clinic deployment. Community-based practices in Germany and France drive uptake where capital constraints previously excluded whole-body plethysmography from secondary care settings.
- Analog:Electromechanical displacement sensors with chart recorder outputs persist in research environments requiring raw signal access. Academic medical centers maintain limited procurement for physiological research protocols.
- Wearable:Strain-gauge and optical sensor arrays enable ambulatory respiratory monitoring outside clinical facilities. Telehealth reimbursement expansion in the United States accelerates home-based chronic disease management applications.
Digital systems anchor the volume base while wearable formats gain share at the steepest rate.
End User:
Capital intensity and reimbursement sophistication stratify demand tiers, with hospitals absorbing high-acuity systems and homecare representing the emerging frontier for distributed monitoring.
- Hospitals:Academic medical centers and tertiary care facilities deploy multi-station pulmonary function laboratories with pneumatic whole-body chambers. FDA 510(k) clearance pathways shape procurement timelines as clinical engineering departments validate predicate device equivalency.
- Clinics:Outpatient pulmonology practices in the United States and Germany adopt portable systems to capture complete lung function testing revenue previously referred to hospital networks.
- Research Labs:Physiology departments and pharmaceutical contract research organizations utilize plethysmography for respiratory pharmacology studies. ISO 26782 interoperability requirements dominate equipment selection for multi-site trial standardization.
- Homecare:Direct-to-patient distribution channels emerge as remote patient monitoring CPT codes expand coverage. Chronic obstructive pulmonary disease management programs in the United States pilot continuous respiratory volume tracking outside institutional settings.
Hospitals command the installed base while homecare climbs the fastest as reimbursement frameworks adapt.
Technology:
Measurement physics determine application suitability and margin structure, with optical methods leveraging pulse oximetry supply chain scale and pneumatic systems retaining premium positioning in diagnostic reimbursement bundles.
- Optical:Photoplethysmography employs near-infrared light absorption to detect blood volume changes in peripheral tissues. Pulse oximetry adjacency drives manufacturing scale and cost reduction for screening applications.
- Pneumatic:Sealed whole-body chambers with pressure transducers quantify thoracic displacement for functional residual capacity measurement. EU MDR conformity assessment requirements extend development timelines for European market entry.
- Electrical:Impedance plethysmography measures tissue conductivity changes for limb blood flow assessment. Vascular surgery departments maintain specialized demand for deep vein thrombosis evaluation.
- Ultrasonic:Doppler-based displacement detection enables non-contact respiratory monitoring. Neonatal intensive care units evaluate contact-free alternatives for fragile patient populations.
Pneumatic systems dominate revenue concentration while optical methods expand most quickly through adjacency economies.
Application:
Clinical workflow integration depth varies by specialty, with pulmonology embedding plethysmography into standard diagnostic protocols while sports medicine represents emerging demand for performance optimization.
- Pulmonology:Chronic obstructive pulmonary disease and asthma diagnosis require complete lung volume quantification including airway resistance and functional residual capacity. Perioperative respiratory screening mandates at United States health systems embed these systems into anesthesia pre-assessment workflows.
- Cardiology:Combined cardiopulmonary stress testing platforms integrate exercise protocols with respiratory gas analysis. Cardiac rehabilitation centers in Germany and Switzerland command premium pricing for integrated diagnostic modalities.
- Sports Medicine:Athlete respiratory performance assessment drives demand for portable systems with rapid test protocols. Olympic training facilities evaluate wearable respiratory sensors for continuous monitoring during exertion.
- Rehabilitation:Post-surgical and chronic disease respiratory therapy programs utilize plethysmography for treatment response quantification. Pulmonary rehabilitation centers in the United States track forced vital capacity improvements for insurance authorization documentation.
Pulmonology anchors procedure volume while sports medicine gains share at the steepest rate through performance optimization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the dominant geography for plethysmograph procurement, while EU MDR conformity assessments reshape European market entry timelines. Hospital consolidation and integrated delivery network purchasing concentrate demand in specific metropolitan clusters across advanced economies.
United States
Integrated health networks in Texas and the Northeast Corridor consolidate plethysmograph purchasing through group purchasing organizations that negotiate multi-hospital contracts spanning twenty to fifty facilities. FDA 510(k) premarket notification requirements govern device authorization, with predicate device comparisons extending development cycles for novel designs. Academic medical centers in Boston and Houston deploy multi-station pulmonary function laboratories with embedded calibration protocols.
Germany
Outpatient pulmonology practices in Bavaria and North Rhine-Westphalia adopt portable body plethysmography systems to capture complete lung function testing revenue previously referred to hospital networks. EU Medical Device Regulation notified body conformity assessments delay product launches by eighteen to twenty-four months. Cardiac rehabilitation centers in Baden-Württemberg command premium pricing for integrated cardiopulmonary stress testing platforms.
China
Domestic manufacturing of pressure transducers and MEMS sensors concentrates in Yangtze River Delta industrial corridors serving both local plethysmograph assembly and export markets. NMPA medical device registration requirements establish parallel pathways for imported versus domestically manufactured respiratory diagnostic equipment. Shanghai-based pulmonary function laboratories standardize on vendor platforms with embedded connectivity infrastructure to satisfy post-market surveillance obligations.
Japan
PMDA pharmaceutical and medical device agency reviews prioritize clinical evidence packages demonstrating equivalence to predicate devices in respiratory diagnostics. METI industrial policy supports miniaturization R&D for wearable respiratory sensors targeting home-based chronic obstructive pulmonary disease management. Tokyo and Osaka metropolitan hospitals anchor demand for high-acuity whole-body plethysmography systems with research protocol capabilities.
India
CDSCO medical device registration timelines compress as domestic production incentives accelerate local manufacturing of pulmonary function test equipment. Secondary care pulmonology clinics in Maharashtra and Karnataka deploy portable systems where capital constraints previously excluded whole-body plethysmography. Delhi-NCR academic medical centers evaluate hybrid optical-pneumatic systems for respiratory pharmacology research protocols.
Plethysmograph Market Competitive Environment
Intensive care heritage specialists and portable diagnostics innovators split the market into distinct competitive spheres with limited overlap in customer touchpoints. Hospital procurement consolidation favors vendors with established service infrastructure and multi-year maintenance contracts. Three archetypes dominate: ventilation-heritage incumbents anchoring academic medical centers, portable system specialists penetrating outpatient clinics, and cardiopulmonary integrators commanding premium positioning in combined diagnostic platforms. Competitive moves center on predictive maintenance analytics bundling and backward integration into sensor manufacturing to secure supply chain resilience.
Within the ventilation-heritage tier, Vyaire Medical Inc. represents the archetype of intensive care equipment manufacturers leveraging anesthesia workflow relationships for high-acuity placements. Among European precision diagnostics specialists, COSMED srl and SCHILLER AG occupy positions exemplifying portable system innovation and cardiopulmonary integration respectively. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Vyaire Medical Inc. |
| COSMED srl |
| ACI Medical LLC |
| Geratherm Medical AG |
| MGC Diagnostics Corporation |
| Becton, Dickinson and Company |
| emka TECHNOLOGIES |
| D. E. Hokanson Inc. |
| SCHILLER AG |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in East Asian MEMS foundries is compressing pressure transducer pricing while simultaneously constraining supplier willingness to expand capacity for high-sensitivity displacement sensors, creating asymmetric pricing power that favors buyers of standard-grade components but penalizes purchasers of 0.1 mL resolution specifications.
Pricing Analysis
United States hospital procurement commands 40-60% premiums over German outpatient clinic pricing for identical pneumatic whole-body systems, reflecting bundled service contract structures and FDA 510(k) compliance costs embedded in capital equipment quotes. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center configurations from community hospital deployments and research-grade analog systems. Cost compression in the portable segment is intensifying because COSMED and portable specialists are flooding European outpatient markets with battery-powered alternatives. Price sensitivity concentrates among independent pulmonology clinics in India and secondary care settings, while integrated delivery networks in Texas and the Northeast Corridor prioritize total cost-of-ownership over acquisition price.
Supply Chain Analysis
Export control regimes limiting MEMS sensor technology flows from United States and Japanese suppliers to Chinese manufacturers are fragmenting sourcing strategies and accelerating domestic capacity buildout in Yangtze River Delta industrial corridors. Supply concentration centers on China for pressure transducer assembly, Japan for high-precision displacement sensors, and Germany for pneumatic chamber fabrication. Raw material dependencies include specialized aluminum alloys for sealed chambers, medical-grade silicone membranes, and rare-earth elements in MEMS fabrication. Single-source vulnerability persists for 0.1 mL resolution pressure transducers where only three qualified foundries maintain validated production lines. Distribution runs through group purchasing organizations in the United States, specialized medical device distributors in Germany, and direct hospital procurement in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biomedical engineering talent capable of calibrating sealed-chamber systems to sub-milliliter precision is thinning across hospital clinical engineering departments, creating a capability gap that threatens equipment utilization rates and service contract profitability for manufacturers dependent on institutional placements.
For Market Incumbents: Pre-empt portable system erosion by anchoring high-acuity placements through predictive maintenance analytics bundling that locks academic medical centers into multi-year service relationships. Backward integration into MEMS sensor manufacturing mitigates East Asian supply concentration risks threatening production continuity for 0.1 mL resolution specifications. Defend against optical pulse oximetry substitution by embedding hybrid optical-pneumatic capabilities into next-generation platforms before low-cost screening sensors capture outpatient referral volumes. For New Entrants and Emerging Players: Build out direct-to-patient distribution channels exploiting telehealth reimbursement expansion for remote respiratory monitoring in United States chronic obstructive pulmonary disease management programs. Target homecare segments where FDA 510(k) pathways remain less congested than hospital laboratory equipment categories and incumbent service infrastructure is underdeveloped. Pursue wearable form factor specialization with rapid regulatory clearance strategies, partnering with pulmonary rehabilitation centers for real-world performance validation that satisfies EU MDR post-market surveillance obligations without legacy installed base burdens. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across wearable plethysmography sub-segments as sensor miniaturization R&D yields transferable component platforms, improving capital efficiency for specialized entrants versus sealed-chamber system manufacturers. Five-to-ten year viability favors vendors with embedded connectivity infrastructure capable of satisfying EU MDR device registry requirements without compliance overhead penalties. Acquisition target archetype: portable system specialists with validated outpatient clinic placements in Germany and telehealth reimbursement pathway expertise in United States markets. Monitor CPT code valuation decisions for complete pulmonary function testing as the critical inflection signal determining equipment replacement cycle velocity and capital allocation priorities across hospital procurement committees.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Group purchasing organization contracts with integrated delivery networks lock twenty-to-fifty facility placements. |
| CE Marking Pathway | EU MDR notified body conformity assessments compress competitive entry for eighteen-to-twenty-four month windows. |
| Software Companion Development | Predictive maintenance analytics bundling transforms capital equipment into recurring revenue service relationships. |
| FDA Submission Strategy | 510(k) predicate device comparisons for novel plethysmograph designs extend development cycles and raise barriers. |
| Reimbursement Strategy | Remote patient monitoring CPT code expansion creates direct-to-patient distribution channels outside institutional procurement. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, hospital procurement contracts, and ISO 26782 interoperability standard documentation. Primary interviews engaged pulmonary function laboratory directors, clinical engineering managers, group purchasing organization contracts specialists, and biomedical equipment procurement officers across United States, German, and Japanese health systems. Secondary validation drew from CMS Medicare reimbursement schedules, GPO contract disclosure filings, and medical device regulatory agency submission tracking. Bottom-up installed base modeling triangulated against top-down capital expenditure surveys from integrated delivery networks.
Forecast inputs include equipment replacement velocity by product architecture, reimbursement code valuation trajectories, and regulatory clearance timeline distributions across FDA, EU MDR, PMDA, and NMPA pathways. Segmentation dimensions span product type, end user, technology, and application with geographic regulatory cluster overlays. CAGRs derive from logistic diffusion modeling of digital versus wearable format adoption curves, calibrated against historical pulmonary function test procedure volume elasticities. Industry-specific inputs incorporate perioperative respiratory screening mandate adoption rates at United States health systems and telehealth reimbursement expansion velocity for remote monitoring.
Stress conditions across EU MDR notified body capacity constraints, MEMS foundry utilization swings, and CPT code valuation revisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway durations and reimbursement stability. Material shifts in FDA 510(k) predicate device equivalence standards or EU MDR post-market surveillance enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
Breathing Exercise Devices Market
Medical Devices
Facial Implant Market
Medical Devices
Skull Clamp Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Sacroiliac Joint Fusion Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Dose Monitoring Devices Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Oral Appliance Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Cytology Brush Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Digital Intraoral Camera Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market