
 Catheter Introducer Sheaths Market | 2026-2036
Catheter Introducer Sheaths Market Size, Share, and Industry Trends Forecast 2026-2036
Catheter Introducer Sheaths Market Outlook
Specialized polymer engineering talent is reorganizing competitive dynamics in catheter introducer sheath manufacturing. Medtronic leverages backward integration into precision extrusion to control polyurethane supply chains. Boston Scientific anchors its position through R&D intensity focused on hydrophilic coating platforms. Terumo Corporation dominates Asian manufacturing scale with vertically integrated facilities in Japan.
Catheter introducer sheaths are hollow, tapered conduits manufactured from thermoplastic elastomers such as polyurethane or ethylene vinyl acetate via multi-layer extrusion and tip-forming processes, designed to establish percutaneous access while minimizing vascular trauma during device insertion. Single-lumen configurations occupy the largest revenue pool due to standardization across diagnostic angiography, while specialty sheaths represent the fastest-growing category as electrophysiology and structural heart procedures demand deflectable and steerable access platforms. Hospitals command the dominant end-user channel through centralized procurement tied to cath lab accreditation standards.
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern product entry in the United States, while the EU Medical Device Regulation enforces stricter clinical evidence thresholds for CE marking across European markets. Japan's PMDA maintains distinct biocompatibility testing protocols that shape regional product development priorities. Stakeholders must monitor evolving polymer regulations and cath lab reimbursement frameworks to align portfolio investments with shifting access economics.
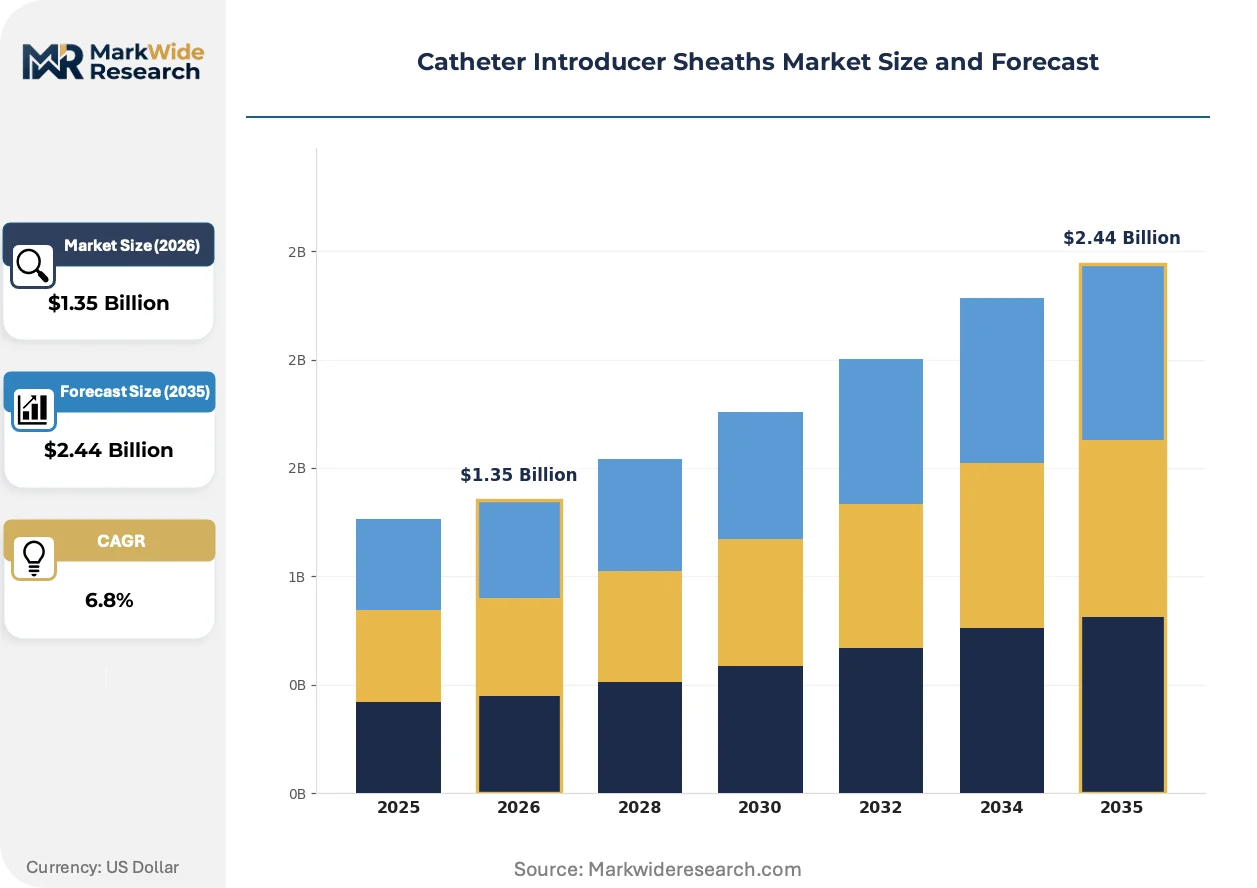
Market Dynamics
Polymer supply concentration in Asia-Pacific is compressing margin structures for Western manufacturers while accelerating localization mandates from FDA and PMDA regulators. This supply asymmetry is forcing catheter introducer sheath producers to reconfigure extrusion partnerships and captive material strategies.
Growth Catalysts
- Structural Heart Procedure Volume:Transcatheter aortic valve replacement programs in United States tertiary hospitals are expanding sheath diameter requirements and driving demand for large-bore access platforms.
- FDA 510(k) Streamlining:Expedited review pathways for substantially equivalent polymer formulations are compressing time-to-market for next-generation hydrophilic coated devices.
- Electrophysiology Lab Expansion:Japan's reimbursement reforms for atrial fibrillation ablation are accelerating deflectable sheath adoption in Tokyo and Osaka metropolitan hospital networks.
Market Restraints
- Polyurethane Feedstock Volatility:Price instability in medical-grade thermoplastic elastomer resins sourced from German and Japanese chemical suppliers is compressing gross margins.
- Single-Source Extrusion Concentration:Precision multi-layer tubing manufacturing capacity concentrates in southern China, creating supply vulnerability for North American device OEMs.
- Biocompatibility Testing Burden:ISO 10993 cytotoxicity and hemocompatibility validation requirements extend development timelines for novel polymer blends.
Strategic Opportunities
- Indian Cath Lab Infrastructure:Government-funded cardiac care centers in Maharashtra and Tamil Nadu present underpenetrated demand for standard diagnostic introducer sheaths.
- EU MDR Clinical Evidence Pathways:Stricter post-market surveillance requirements create competitive advantage for manufacturers with established real-world performance databases.
- Robotic-Assisted Integration:Convergence of steerable sheath technology with magnetic navigation systems enables precision positioning in complex electrophysiology procedures.
Industry Challenges
- Polymer Engineering Talent Scarcity:Specialized expertise in medical-grade polyurethane formulation and multi-layer co-extrusion is concentrated among a narrow cohort of aging specialists in Massachusetts and Shizuoka prefecture.
- Cleanroom Manufacturing Intensity:ISO Class 7 extrusion and tip-forming facilities require capital deployment exceeding typical mid-cap medical device budgets.
- PMDA Localization Timelines:Japan's distinct biocompatibility testing protocols and domestic clinical trial requirements extend market entry schedules for foreign manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catheter Introducer Sheaths Market |
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lumen, Double-Lumen, Side-Arm, Specialty Sheaths End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare Providers Material: Polyurethane, PVC, Silicone, Ethylene Vinyl Acetate Application: Cardiology, Urology, Neurology, Radiology |
| Companies Covered | Medtronic, Boston Scientific, Terumo Corporation, Stryker, Merit Medical, Cardinal Health, Abbott, Teleflex, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catheter Introducer Sheaths Market Strategic Shifts
Material science advances and regulatory harmonization pressures are reshaping competitive advantage in catheter introducer sheath manufacturing. Three distinct vectors are altering product development priorities and go-to-market economics.
Multi-layer polymer construction is bifurcating performance expectations across the catheter introducer sheath market. Advanced polyurethane-PEBAX composites deliver kink resistance and torque transmission for interventional cardiology suites in Cleveland Clinic and Mayo Clinic networks. This material transition is compressing demand for conventional single-layer sheaths in diagnostic applications while expanding premium pricing power in structural heart segments.
EU Medical Device Regulation enforcement is elevating clinical evidence requirements for CE marking across European markets. Manufacturers must now submit post-market clinical follow-up plans and periodic safety update reports for polymer-based vascular access devices. German notified bodies in Tübingen and Munich are applying heightened scrutiny to hydrophilic coating durability claims, forcing reformulation investments from suppliers serving Charité and Heidelberg University Hospital procurement channels.
Hospital procurement consolidation is centralizing purchasing authority for catheter introducer sheaths within integrated delivery networks. United States health systems like HCA Healthcare and CommonSpirit Health are negotiating multi-year supply agreements that bundle diagnostic and interventional access products. This channel compression is displacing distributor intermediaries in Texas and Florida markets while rewarding manufacturers with comprehensive vascular access portfolios and direct logistics capabilities.
Catheter Introducer Sheaths Market Segmentation
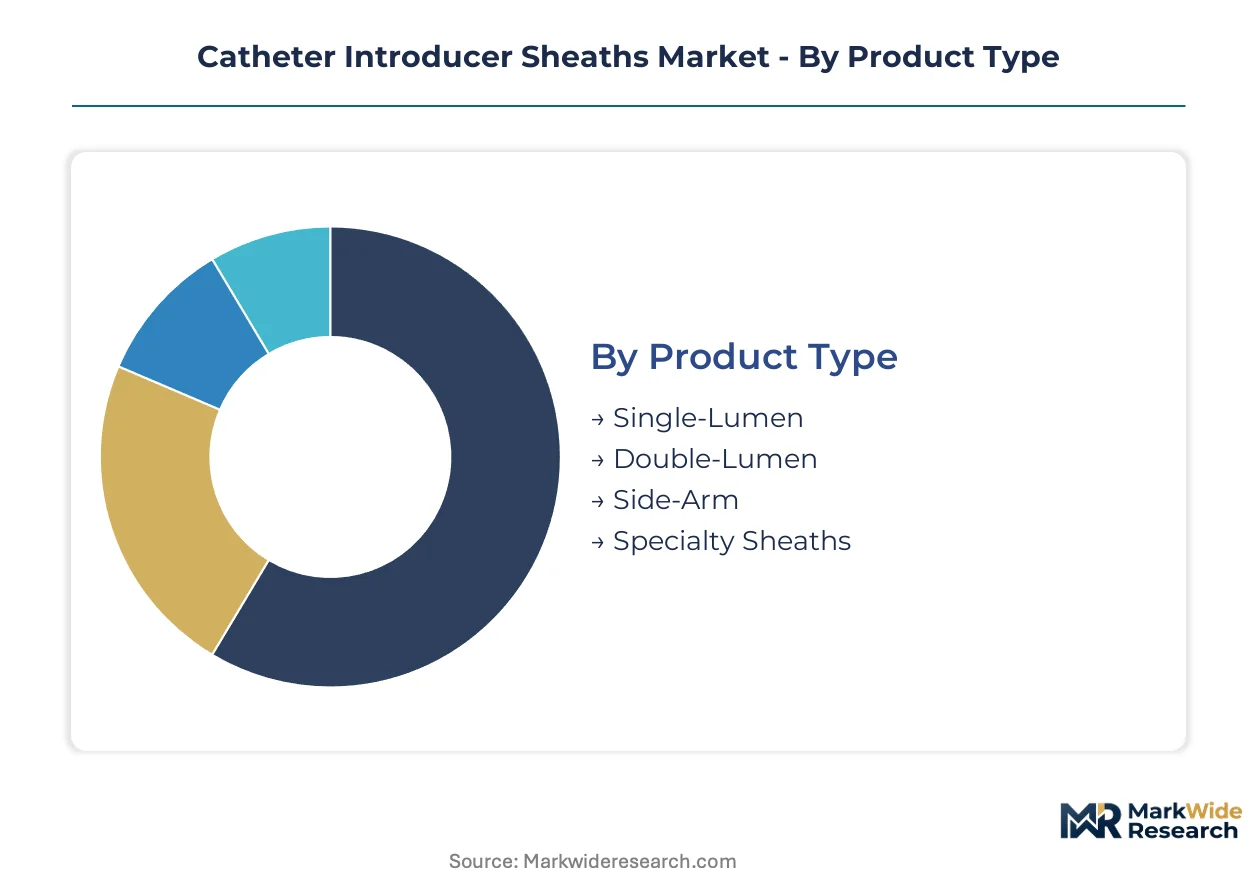
Catheter introducer sheath segmentation reveals distinct regulatory pathways and reimbursement frameworks that shape commercial strategy across each dimension. Manufacturers must align product portfolios with FDA 510(k) clearance requirements, EU MDR clinical evidence thresholds, and PMDA biocompatibility protocols governing specific configurations and materials.
Product Type:
FDA 510(k) predicates for single-lumen sheaths differ substantially from specialty deflectable platforms, creating divergent time-to-market economics across this category.
- Single-Lumen:Standard hollow tapered conduits manufactured via single-layer polyurethane extrusion dominate diagnostic angiography throughput. United States tertiary hospitals in Cleveland and Houston concentrate procurement through integrated delivery networks, with cath lab accreditation standards driving volume consolidation.
- Specialty Sheaths:Deflectable and steerable access platforms incorporate braided stainless steel torque layers and hydrophilic coating systems for electrophysiology and structural heart procedures. Tokyo metropolitan hospital networks in Japan are accelerating adoption following reimbursement reforms for atrial fibrillation ablation.
- Double-Lumen:Dual-channel configurations enable simultaneous pressure monitoring and device delivery during complex interventions.
- Side-Arm:Auxiliary port designs facilitate contrast injection and pressure sensing without main lumen compromise.
Single-Lumen handles the majority of throughput; Specialty Sheaths is the fastest mover on share.
End User:
Cost tier differentiation separates capital-intensive hospital procurement from ambulatory channel economics.
- Hospitals:Centralized purchasing authority within United States health systems like HCA Healthcare and CommonSpirit Health bundles diagnostic and interventional access products. Multi-year supply agreements displace distributor intermediaries in Texas and Florida markets while rewarding manufacturers with comprehensive vascular access portfolios.
- Ambulatory Surgical Centers:Medicare reimbursement shifts toward site-neutral payment are redirecting select cardiac catheterization volumes to freestanding facilities in Arizona and North Carolina.
- Clinics:Office-based diagnostic procedures drive demand for standard single-lumen configurations.
- Homecare Providers:Peripheral vascular access maintenance creates niche demand for silicone-based indwelling platforms.
Hospitals command dominant procurement scale; Ambulatory Surgical Centers are climbing the fastest on volume trajectory.
Material:
Supply concentration in Asia-Pacific extrusion capacity shapes regional sourcing strategies and margin structures.
- Polyurethane:Medical-grade thermoplastic elastomer formulations deliver kink resistance and biocompatibility for interventional cardiology suites. German chemical suppliers in Leverkusen and Japanese resin producers in Shizuoka prefecture concentrate feedstock manufacturing, creating price volatility exposure for Western device OEMs.
- Ethylene Vinyl Acetate:Flexible copolymer compositions enable low-durometer tips minimizing vascular trauma during device insertion. Cleveland Clinic and Mayo Clinic networks specify EVA-blend constructions for large-bore structural heart access platforms.
- PVC:Cost-competitive formulations serve diagnostic applications with limited flexural demands.
- Silicone:Platinum-cured elastomer systems provide extended indwelling compatibility for chronic access.
Polyurethane commands the majority of formulation volume; Ethylene Vinyl Acetate is gaining share fastest in premium segments.
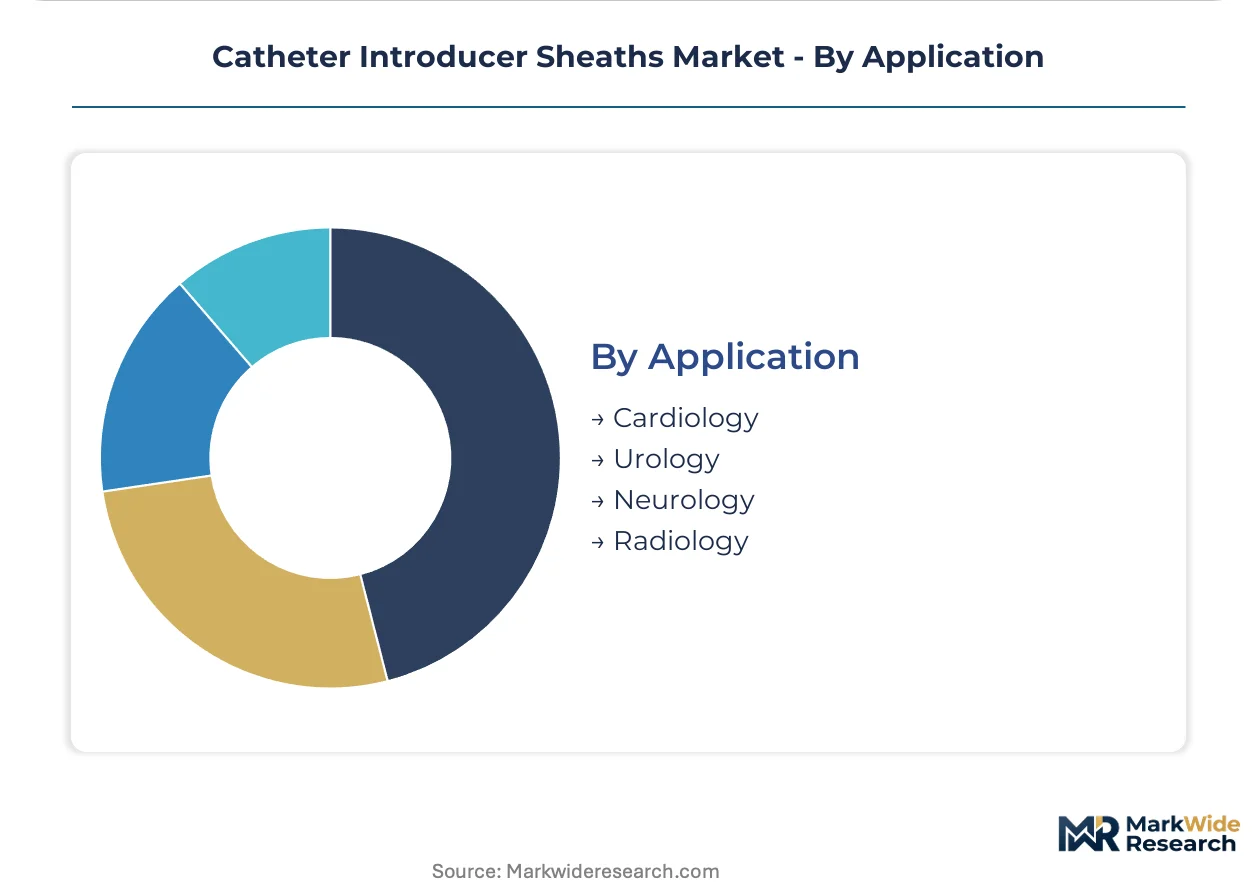
Application:
Procedure volume concentration in cardiology creates volume leverage distinct from specialty clinical economics.
- Cardiology:Transcatheter aortic valve replacement programs in United States tertiary hospitals are expanding sheath diameter requirements and driving demand for large-bore access platforms. Structural heart procedure volume is reshaping product development priorities across polyurethane-PEBAX composite engineering.
- Radiology:Diagnostic angiography standardization maintains steady demand for conventional single-lumen configurations. Interventional radiology suites in Germany's Charité and Heidelberg University Hospital procurement channels apply heightened scrutiny to hydrophilic coating durability claims.
- Urology:Endourological access procedures utilize smaller-diameter sheaths for nephrostomy and ureteral interventions.
- Neurology:Neurovascular access demands ultra-thin wall constructions for tortuous intracranial navigation.
Cardiology handles the majority of procedural throughput; Radiology maintains the steepest expansion trajectory in diagnostic standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catheter introducer sheath consumption patterns diverge sharply across geographies: United States hospitals prioritize large-bore platforms for structural heart interventions, while Japanese networks emphasize deflectable systems for electrophysiology, and German procurement channels apply rigorous coating durability standards.
United States
Transcatheter aortic valve replacement volume in Cleveland Clinic and Mayo Clinic networks is expanding sheath diameter requirements beyond 20 French. FDA 510(k) clearance pathways for hydrophilic-coated devices are compressing time-to-market for novel polymer formulations. Texas and Florida health systems are consolidating cath lab purchasing through HCA Healthcare and CommonSpirit Health networks.
Germany
Charité and Heidelberg University Hospital procurement channels enforce heightened scrutiny of hydrophilic coating durability claims for interventional radiology suites. EU Medical Device Regulation post-market surveillance requirements are elevating clinical evidence thresholds for CE marking. Tübingen and Munich notified bodies are applying stricter polymer biocompatibility validation standards.
Japan
Tokyo and Osaka metropolitan hospital networks are accelerating deflectable sheath adoption following PMDA reimbursement reforms for atrial fibrillation ablation. METI industrial policy is reinforcing domestic manufacturing scale through vertically integrated facilities in Shizuoka prefecture. PMDA maintains distinct biocompatibility testing protocols that shape regional product development priorities.
India
Maharashtra and Tamil Nadu government-funded cardiac care centers present underpenetrated demand for standard diagnostic introducer sheaths. CDSCO medical device registration requirements are evolving toward harmonization with ISO 13485 quality management standards. Karnataka medical device clusters are emerging as assembly hubs for multinational OEM supply chains.
China
Yangtze River Delta hospital networks are expanding cath lab infrastructure for coronary and peripheral interventions. NMPA Class III medical device registration pathways are extending clinical trial requirements for imported polymer-based vascular access devices. Precision multi-layer tubing manufacturing capacity concentrates in southern China extrusion facilities.
Catheter Introducer Sheaths Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in catheter introducer sheath manufacturing. The upper tier commands captive polyurethane supply chains and direct hospital contracting relationships, while mid-scale players compete through coating technology differentiation and regional distribution partnerships. Strategic archetypes include backward-integrated material controllers, hydrophilic coating platform specialists, and Asia-Pacific manufacturing scale operators. Dominant competitive moves center on extrusion partnership reconfiguration and multi-year integrated delivery network supply agreements.
Among the integrated leaders, Medtronic and Boston Scientific exemplify divergent material control strategies, with the former emphasizing precision extrusion capabilities and the latter anchoring position through R&D intensity in surface engineering. Terumo Corporation occupies a distinct position as the scale-driven Asian manufacturer with vertically integrated Japanese production facilities. Merit Medical and Cook Medical represent mid-tier specialists competing through focused vascular access portfolios rather than comprehensive device ecosystems.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Terumo Corporation |
| Stryker |
| Merit Medical |
| Cardinal Health |
| Abbott |
| Teleflex |
| Cook Medical |
| Others |
Value Chain & Pricing Dynamics
Sixty-day resin inventory buffers at German polyurethane suppliers now govern pricing leverage across the catheter introducer sheath market, compressing margin structures for North American device OEMs while amplifying cost pass-through power for Asian extrusion houses serving Tokyo metropolitan hospital networks.
Pricing Analysis
Long-term offtake contracts dominate procurement between United States health systems and integrated device manufacturers, with multi-year supply agreements bundling diagnostic and interventional access products through HCA Healthcare and CommonSpirit Health networks. Price differentiation rests on hydrophilic coating certification grade and cath lab accreditation tier, with Cleveland Clinic and Mayo Clinic procurement channels commanding premium positioning for large-bore structural heart platforms. Cost compression in standard single-lumen configurations is intensifying because polyurethane feedstock volatility from Leverkusen and Shizuoka prefecture suppliers is squeezing gross margins. Ambulatory surgical centers in Arizona and North Carolina exhibit highest price sensitivity due to Medicare site-neutral reimbursement shifts, while tertiary hospital networks remain least sensitive given bundled payment structures.
Supply Chain Analysis
Port congestion along Shanghai-Ningbo trade lanes is elevating inbound logistics costs for precision multi-layer tubing components destined for North American device assembly facilities. Manufacturing gravity centers on China, Japan, and Germany, with southern China extrusion houses supplying braided torque layers, Shizuoka prefecture facilities controlling medical-grade polyurethane resin production, and Leverkusen chemical suppliers anchoring specialty elastomer formulations. Raw material dependencies span medical-grade thermoplastic elastomers, stainless steel braiding wire, and hydrophilic coating polymers. Single-source concentration in Yangtze River Delta extrusion capacity creates structural vulnerability for FDA 510(k) clearance timelines. Distribution runs through integrated delivery network procurement offices in Texas and Florida, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The catheter introducer sheath market functions as a defensive-moat arena where regulatory entrenchment through FDA 510(k) predicate libraries and PMDA biocompatibility protocols erects formidable switching costs against displacement.
For Market Incumbents: Consolidate backward integration into precision extrusion capabilities to neutralize polyurethane feedstock volatility from German and Japanese chemical suppliers. Deepen captive supply chain control over medical-grade thermoplastic elastomer formulations while accelerating ISO 13485 certification investments to defend against emerging Asia-Pacific manufacturing scale operators. Priority lever centers on reconfiguring extrusion partnerships to reduce single-source dependence on southern China capacity.
For New Entrants and Emerging Players: Lead with government-funded cardiac care center procurement in Maharashtra and Tamil Nadu, where underpenetrated diagnostic angiography volume creates accessible white-space for standard single-lumen configurations. Target CDSCO registration harmonization as the regulatory entry mechanism, positioning through Karnataka medical device cluster assembly partnerships to serve multinational OEM supply chains without direct hospital contracting requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive polymer extrusion assets but lacking dedicated medical device commercial infrastructure. Long-term viability over the next decade hinges on hydrophilic coating platform durability validated through EU MDR post-market clinical follow-up databases. Signal to monitor: PMDA reimbursement reform acceleration for atrial fibrillation ablation procedures in Tokyo and Osaka metropolitan networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Extrusion | Medtronic's captive polyurethane supply chains neutralize German and Japanese resin price volatility. |
| Hydrophilic Coating Platform Investment | Boston Scientific's R&D intensity targets FDA 510(k) clearance compression for next-generation devices. |
| Vertically Integrated Asian Manufacturing Scale | Terumo Corporation's Shizuoka prefecture facilities dominate PMDA-compliant production for domestic hospital networks. |
| Integrated Delivery Network Supply Agreement | Multi-year contracts with HCA Healthcare and CommonSpirit Health displace distributor intermediaries in Texas and Florida. |
| EU MDR Clinical Evidence Pathway Development | Post-market surveillance databases create competitive advantage for CE marking across German notified body channels. |
Study Parameters
A standing panel of cath lab directors, biomedical engineers, GPO contracts managers, and polymer extrusion specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) clearance databases, PMDA approval registries, EU MDR notified body documentation, hospital procurement contract disclosures, and ISO 13485 certification records. Bottom-up volume estimates from individual cath lab throughput data triangulated against top-down health system expenditure aggregates.
Consistency checks against external benchmarks validated projection outputs across the analysis window. The analytical framework modeled segmentation dimensions spanning product type configuration, end-user channel tier, material formulation grade, and application procedure volume. CAGRs were derived from procedure growth trajectories and cath lab infrastructure expansion patterns. Industry-specific forecast inputs incorporated structural heart procedure volume curves and electrophysiology lab reimbursement reform schedules.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) clearance pathway stability, polyurethane feedstock supply continuity, and tertiary hospital capital expenditure commitment would require recalibration. Forecasts reflect assumptions regarding cath lab accreditation standard maintenance and polymer biocompatibility protocol harmonization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Glucometer Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Medical Manifolds Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Left Atrial Appendage Devices Market
Medical Devices
Knotless Suture Anchors Market
Medical Devices
Middle East and Africa Sperm Separation Devices Market
Medical Devices
India Diabetes Devices Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Global Prosthetics Market
Medical Devices
Spherical IOL Market
Medical Devices
Medical Device Tester Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Steerable Needles Market