
 South Korea Endoscopy Devices Market | 2026-2036
South Korea Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Endoscopy Devices Market Analytics
The South Korean endoscopy device market is pivoting on a widening gap between premium robotic-assisted systems and conventional flexible scopes. Olympus Corporation leverages its optical heritage to dominate image-enhanced endoscopy platforms. Karl Storz SE & Co. KG anchors the rigid endoscope segment through surgical precision instruments. Fujifilm Holdings Corp. differentiates via AI-integrated diagnostic software embedded in video processor units.
Endoscopy devices are tubular instruments equipped with fiber-optic or digital imaging systems, typically 2-15mm in diameter, designed for minimally invasive internal visualization and therapeutic intervention. These instruments transmit real-time video to external monitors while enabling biopsy, polypectomy, or stent deployment through working channels. Flexible endoscopes lead the product landscape due to established reimbursement pathways for gastrointestinal screening procedures. Image-enhanced endoscopy technology is displacing conventional white-light systems in premium hospital installations. Capsule endoscopy occupies a narrow niche for small-bowel examination where conventional scope passage proves technically challenging.
MFDS approval requirements and Korea's Medical Device Act govern product registration, clinical evidence standards, and post-market surveillance obligations for all manufacturers. MFDS Good Manufacturing Practice audits and Ministry of Health and Welfare reimbursement listings collectively determine commercial viability for new entrants. Stakeholders must monitor how MFDS digital health guidance evolves for AI-diagnostic software bundled with endoscope systems.
Market Dynamics
MFDS reimbursement mandates for gastric cancer screening are compressing procurement cycles while single-use endoscope manufacturing concentrates in Seoul's Songdo and Pangyo biotech clusters, creating a dual-speed market structure.
Growth Catalysts
- NFHS Screening Protocols:National Health Insurance Service mandates for biennial gastric cancer screening in adults over 40 sustain procedural volume at tertiary hospitals and specialized endoscopy centers.
- Single-Use Manufacturing Scale-Up:Domestic producers in Gyeonggi Province are achieving cost parity with reprocessing for gastrointestinal scopes, accelerating hospital conversion.
- AI Diagnostic Integration:Real-time polyp detection algorithms embedded in video processors are expanding reimbursable procedure codes under MFDS digital health guidance.
Market Restraints
- Optical Component Import Dependency:High-resolution CMOS sensors and specialized lens assemblies originate from Japanese and German suppliers, exposing margins to currency volatility.
- Reprocessing Infrastructure Sunk Costs:Hospitals with automated endoscope reprocessor investments face stranded asset risk when evaluating single-use conversions.
- MFDS Clinical Evidence Thresholds:Novel AI-diagnostic software requires prospective validation studies that extend registration timelines by 18-24 months versus conventional devices.
Strategic Opportunities
- Busan-Ulsan Medical Cluster Expansion:Southeast Korea's underpenetrated secondary hospital network presents whitespace for mobile endoscopy service models.
- Telemedicine-Enabled Screening:Remote diagnostic consultation protocols under Korea's Digital New Deal are creating channel access for rural health centers lacking on-site specialists.
- Capsule-Robotic Convergence:Magnetically steerable capsule systems combined with robotic positioning platforms address small-bowel segments unreachable by conventional flexible scopes.
Industry Challenges
- Specialized Technician Shortage:Endoscope reprocessing certification requirements under MFDS Good Manufacturing Practice exceed available trained personnel in provincial hospitals.
- Legacy System Integration Friction:AI-enhanced video processors require PACS architecture upgrades that disrupt established workflow patterns in older facilities.
- Cross-Border IP Licensing Complexity:Patent thickets around narrow-band imaging and blue-light technologies complicate domestic manufacturer R&D roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Endoscopy Devices Market |
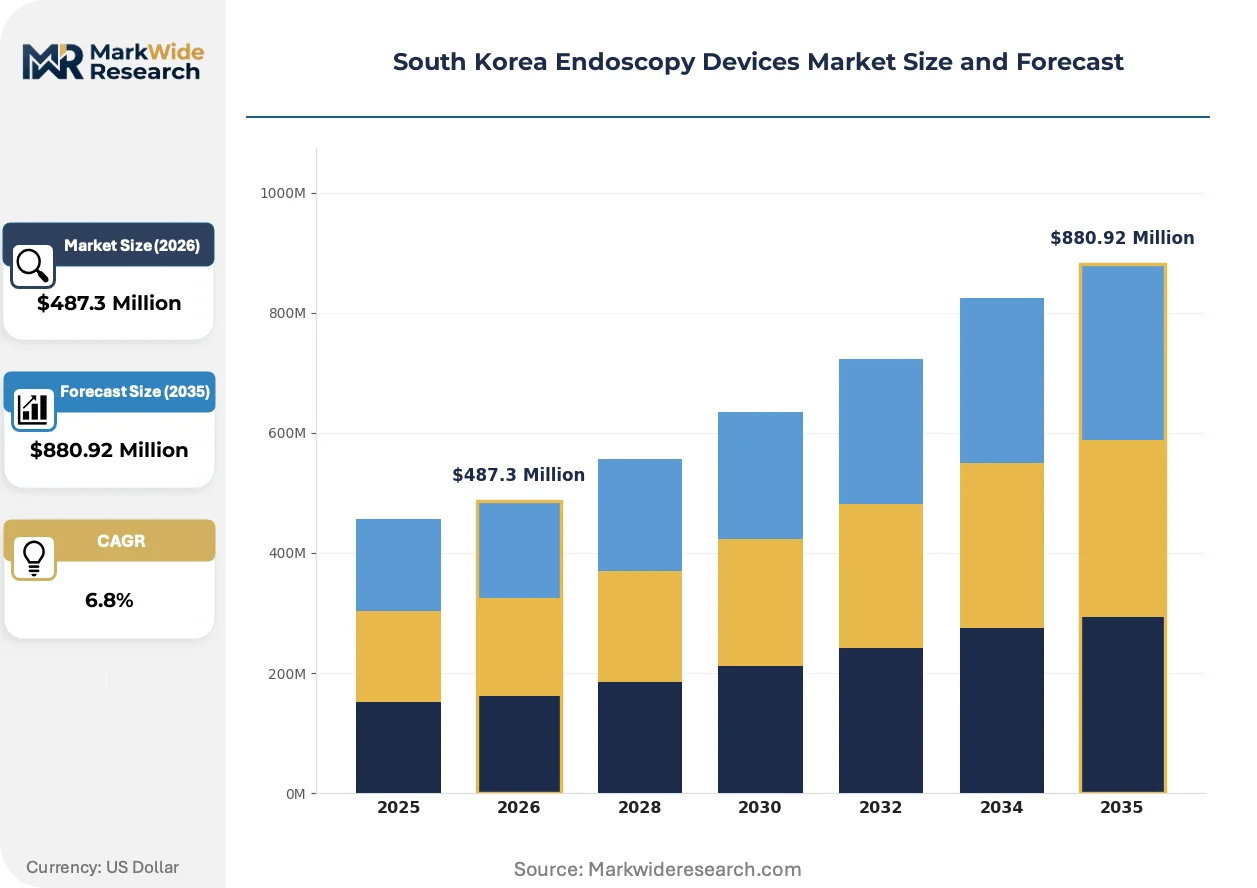
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Endoscopes, Rigid Endoscopes, Flexible Endoscopes, Surgical Endoscopes Application: Gastroenterology, Pulmonology, Urology, Gynecology End User: Hospitals, Clinics, Specialty Centers, Research Institutions Technology: Conventional Endoscopy, Robotic-Assisted Endoscopy, Capsule Endoscopy, Image-Enhanced Endoscopy |
| Companies Covered | Karl Storz SE & Co. KG, Stryker Corporation, Olympus Corporation, SUNGYONG MEDITECH, Boston Scientific Corporation, Fujifilm Holdings Corp., Medtronic plc, TECHCORD Co., Ltd., HOYA Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Endoscopy Devices Market Evolving Landscape
Disposable endoscope manufacturing is compressing the traditional reprocessing service model while regulatory frameworks accelerate software-as-medical-device classifications. Three developments are restructuring competitive positioning.
Single-use flexible endoscopes are unifying infection control liability reduction with operational simplicity. Tertiary hospitals in Seoul's Gangnam district are adopting these devices for high-turnover screening procedures. This technology is unifying supply chain control for domestic manufacturers who previously relied on imported reprocessing chemicals and maintenance contracts.
MFDS digital health guidance for AI-diagnostic software is mandating prospective clinical validation for real-time polyp detection algorithms. Endoscope manufacturers must now submit software updates as supplemental premarket notifications. Gastroenterology departments at university hospitals are most affected, restructuring procurement specifications to require modular processor architectures that accommodate iterative algorithm deployment.
Hospital procurement committees are consolidating vendor relationships around full-service contracts that bundle devices, disposables, and maintenance. Independent service organizations are losing share to manufacturer-captive service arms. This concentration is most visible in Daegu and Gwangju metropolitan areas where hospital networks are standardizing on single-platform ecosystems to reduce training variability and spare part inventory complexity.
South Korea Endoscopy Devices Market Segmentation
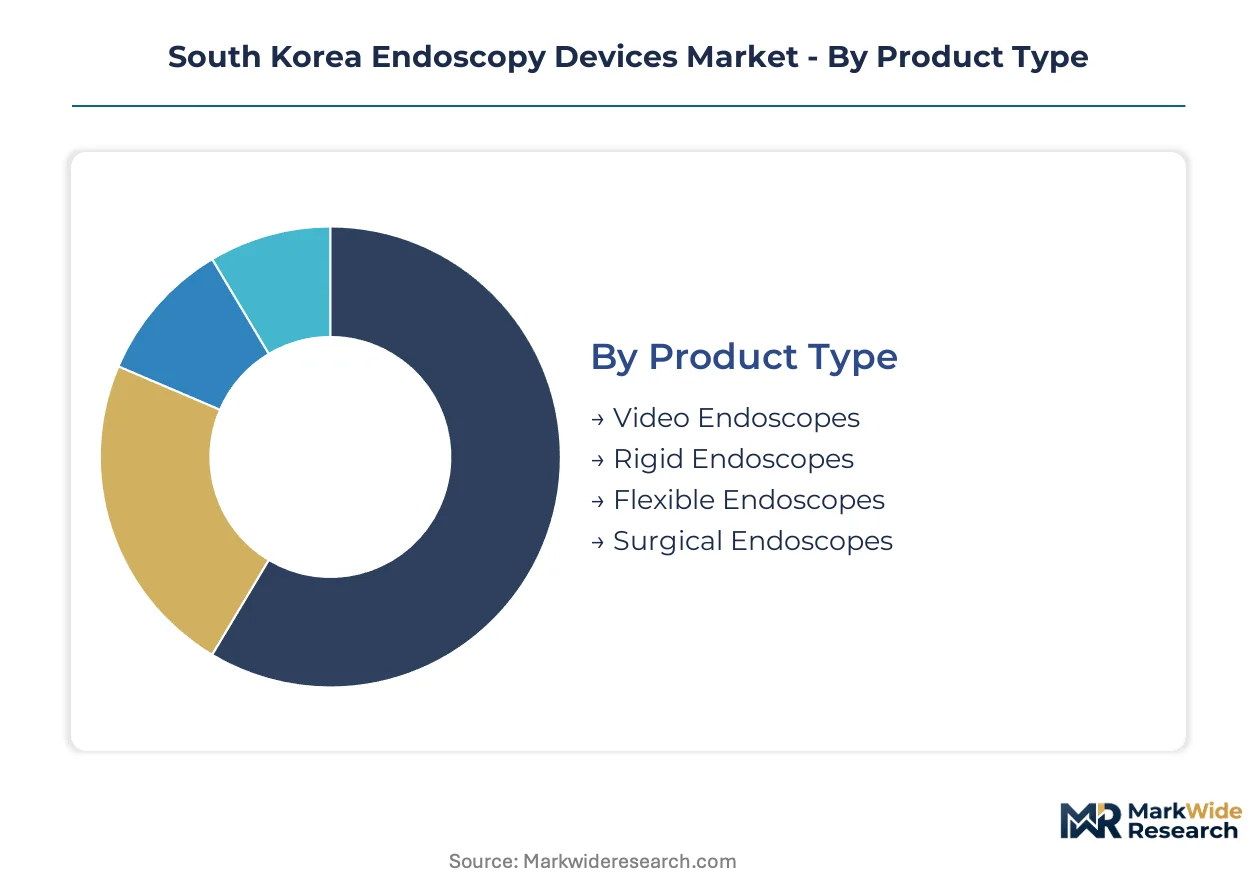
Endoscopy device segmentation in South Korea reveals divergent investment profiles across product architectures and clinical settings. Procurement committees weigh capital intensity against procedural throughput when allocating budgets across tertiary hospital networks and specialized screening centers.
Product Type:
Capital intensity varies dramatically across product architectures, with video processor systems requiring the heaviest upfront outlay while rigid scopes demand minimal infrastructure investment.
- Flexible Endoscopes:Fiber-optic or digital insertion tubes with articulating distal tips enable navigation through tortuous gastrointestinal anatomy. Seoul's Gangnam district tertiary hospitals concentrate demand for high-definition flexible systems as gastric cancer screening volumes surge under National Health Insurance Service mandates.
- Video Endoscopes:Integrated CMOS sensor systems at the distal tip eliminate fiber-optic image degradation. Busan metropolitan clusters are absorbing expanded manufacturing capacity for these devices as domestic producers achieve vertical integration into sensor module assembly.
- Rigid Endoscopes:Stainless steel optical systems for arthroscopy, laparoscopy, and ENT applications. Standardized lens and light-guide configurations reduce per-unit production costs.
- Surgical Endoscopes:Hybrid designs combining rigid shafts with flexible articulation for NOTES and single-incision procedures. Emerging adoption in Daegu university hospital networks.
Most installed capacity flows through flexible endoscopes. Expansion is steepest in video endoscope systems as image sensor costs decline.
Application:
Procedure reimbursement rates determine capital recovery timelines across clinical specialties, with gastrointestinal screening offering the shortest payback periods.
- Gastroenterology:Esophagogastroduodenoscopy and colonoscopy dominate procedural volume. MFDS-mandated biennial screening for adults over 40 sustains equipment utilization rates above 85% in Seoul's specialized endoscopy centers.
- Pulmonology:Bronchoscopy for lung cancer staging and interventional procedures. Gwangju metropolitan hospitals are expanding interventional pulmonology units with electromagnetic navigation systems.
- Urology:Cystoscopy and ureterorenoscopy for stone disease and bladder cancer surveillance. Reimbursement compression limits capital refresh cycles.
- Gynecology:Hysteroscopy and laparoscopy for diagnostic and operative procedures. Smaller addressable market constrains manufacturer R&D investment.
Gastroenterology absorbs the dominant share of installed base. Pulmonology is climbing the fastest as lung cancer screening protocols expand.
End User:
Customer scale dictates purchasing power and service contract terms, with hospital networks extracting steeper discounts than independent clinics.
- Hospitals:Tertiary and secondary general hospitals with dedicated endoscopy suites. MFDS Good Manufacturing Practice audits and Ministry of Health and Welfare reimbursement listings shape procurement specifications.
- Specialty Centers:Dedicated endoscopy and digestive disease clinics. Concentrated in Seoul's Songdo and Pangyo biotech corridors with high procedural throughput.
- Clinics:Primary care and small specialty practices. Price sensitivity drives demand for refurbished equipment and extended financing terms.
- Research Institutions:University hospitals and clinical trial centers. Require modular platforms supporting investigational device protocols.
Hospital networks command the largest procurement volumes. Specialty centers are gaining share fastest as screening decentralization accelerates.
Technology:
Software and hardware integration depth separates premium tiers from commodity offerings, with AI-embedded systems commanding substantial price premiums.
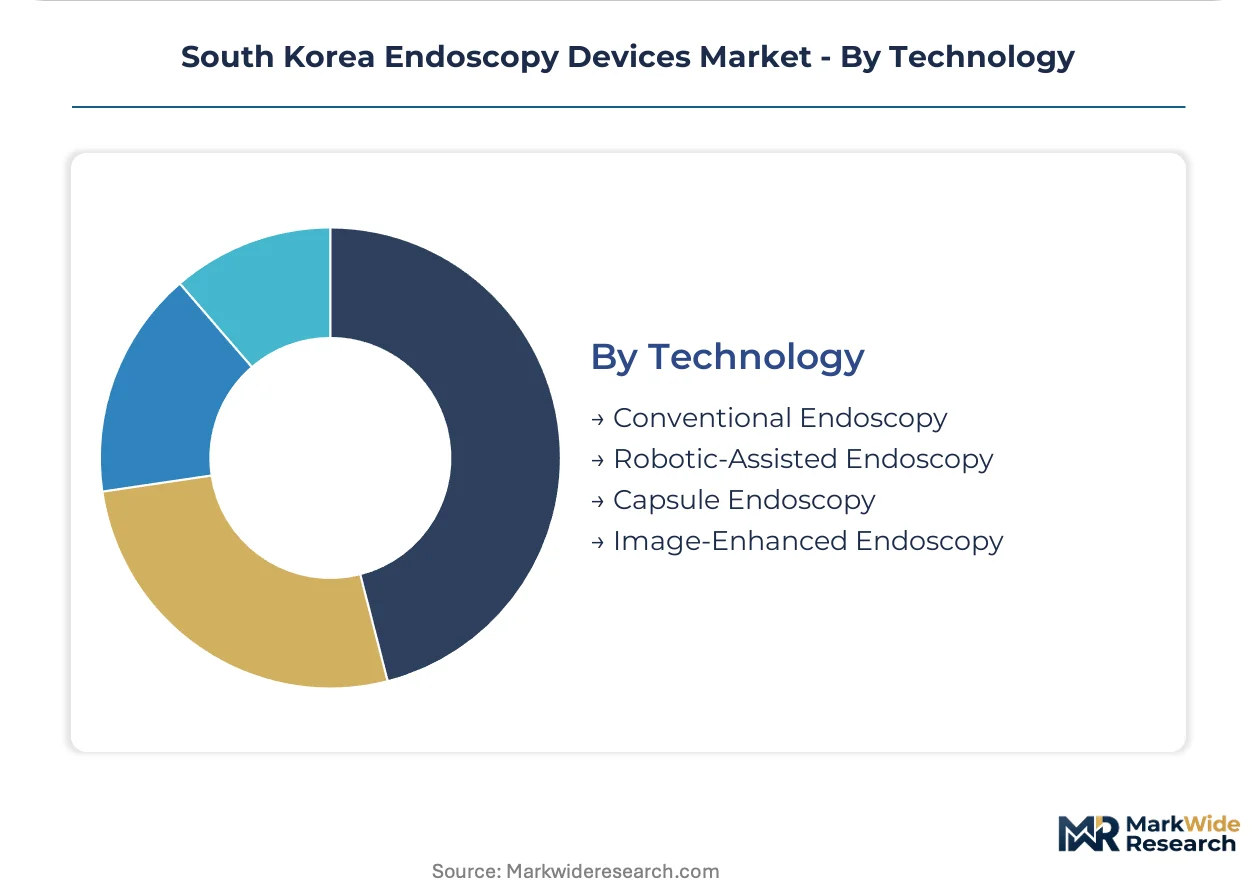
- Image-Enhanced Endoscopy:Narrow-band imaging and blue-light technologies improve mucosal surface visualization. MFDS digital health guidance now mandates prospective validation for algorithm updates bundled with these processors.
- Robotic-Assisted Endoscopy:Motorized scope positioning and instrument manipulation. Seoul National University Hospital anchors adoption for complex interventional procedures.
- Conventional Endoscopy:White-light illumination without computational enhancement. Declining share as reimbursement differentials favor advanced imaging.
- Capsule Endoscopy:Ingestible camera systems for small-bowel examination. Limited to cases where conventional scope passage fails technically.
Image-enhanced systems dominate new installations. Robotic-assisted platforms are expanding most quickly as surgical precision requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gastroenterology specialists cluster in Seoul's tertiary hospitals and Busan's medical complexes, anchoring procedural volume and equipment procurement decisions across South Korea's metropolitan corridors.
Seoul Capital Area
Gangnam district university hospitals drive demand for image-enhanced endoscopy systems as gastric cancer screening volumes surge. MFDS reimbursement mandates for biennial examinations sustain equipment utilization above 85%. Songdo and Pangyo biotech clusters concentrate domestic single-use endoscope manufacturing capacity.
Busan-Ulsan
Southeast Korea's secondary hospital network presents whitespace for mobile endoscopy service models. Regional lung cancer screening protocols expand pulmonology procedural volume. Ulsan's industrial base supplies precision optical components to device assemblers.
Daegu-Gyeongbuk
University hospital networks standardize on single-platform ecosystems to reduce training variability. NOTES and single-incision surgical endoscopy adoption concentrates here. Gyeongbuk Province hosts automated endoscope reprocessor distribution facilities serving provincial hospitals.
Daejeon-Sejong
Government research institutes anchor clinical validation studies for AI-diagnostic software. Korea's Digital New Deal telemedicine protocols originate from Sejong administrative city. Regional health centers pilot remote diagnostic consultation for rural screening access.
Gwangju-Honam
Interventional pulmonology units expand with electromagnetic navigation bronchoscopy systems. Price sensitivity in primary care clinics drives refurbished equipment demand. Honam region's agricultural economy limits capital refresh cycles compared to metropolitan counterparts.
South Korea Endoscopy Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South Korea's endoscopy device market. The structure consolidates around optical heritage conglomerates and specialized surgical instrument fabricators. Three archetypes dominate: integrated imaging system vendors, component-focused scope manufacturers, and disposable technology specialists. Strategic moves center on full-service contract bundling and AI software validation partnerships.
Within the integrated imaging tier, Olympus Corporation and Fujifilm Holdings Corp. occupy positions exemplifying optical-to-digital platform evolution. Karl Storz SE & Co. KG represents precision surgical instrument heritage. Among domestic specialists, SUNGYONG MEDITECH and TECHCORD Co., Ltd. sit within the emerging disposable endoscope manufacturing segment.
| Leading Market Players |
|---|
| Karl Storz SE & Co. KG |
| Stryker Corporation |
| Olympus Corporation |
| SUNGYONG MEDITECH |
| Boston Scientific Corporation |
| Fujifilm Holdings Corp. |
| Medtronic plc |
| TECHCORD Co., Ltd. |
| HOYA Corporation |
| Others |
Value Network & Pricing Analysis
High-resolution CMOS sensor procurement from Japanese and German suppliers cascades through three distinct pricing tiers for South Korean endoscopy device buyers, with tertiary hospital networks extracting volume discounts while provincial clinics absorb currency-adjusted premiums on imported optical assemblies.
Pricing Analysis
Bundled full-service contracts dominate procurement for integrated imaging systems, while unbundled per-unit transactions persist for rigid scopes and refurbishment markets. Three-tier pricing structure across premium, standard, and economy levels separates AI-embedded video processors from conventional fiber-optic systems and refurbished legacy equipment. Pricing pressure stems from domestic single-use manufacturers achieving cost parity with reprocessed scopes in Seoul's metropolitan clusters. Independent clinics in Gwangju and Honam exhibit highest price sensitivity, driving demand for extended financing and certified refurbished devices.
Supply Chain Analysis
Reverse logistics for endoscope reprocessing equipment creates secondary refurbishment flows from tertiary hospitals to provincial secondary facilities, extending asset lifecycles across Korea's hospital network. Upstream optical component supply concentrates in Japan, Germany, and the United States for specialized lens assemblies and CMOS sensors. Raw material dependencies include medical-grade stainless steel, fiber-optic glass bundles, and silicone-based insertion tube sheathing. Single-source vulnerability in high-resolution sensor supply exposes margins to yen-euro exchange volatility. Distribution runs through manufacturer-captive service arms and authorized distributors serving hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea endoscopy devices market functions as a stable compounder anchored by MFDS-mandated biennial gastric cancer screening protocols that sustain procedural volume regardless of economic cycles.
For Market Incumbents: Hedge against single-use technology disruption by securing backward integration into domestic sensor module assembly in Busan manufacturing clusters. Prioritize certification investment for AI-diagnostic software under evolving MFDS digital health guidance to maintain premium positioning against emerging disposable specialists. For New Entrants and Emerging Players: Begin with mobile endoscopy service models targeting Busan-Ulsan's underpenetrated secondary hospital network, where procedural volume growth outpaces capital equipment budgets. Pursue telemedicine-enabled screening partnerships under Korea's Digital New Deal as the primary go-to-market channel for rural health center access. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented domestic disposable manufacturers lack vertical integration into optical component supply. Long-term viability favors platforms combining hardware manufacturing with validated AI software pipelines. Monitor MFDS reimbursement code expansions for real-time diagnostic algorithms as the inflection signal for premium-tier valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS AI Software Validation Partnership | Accelerates regulatory clearance for real-time polyp detection algorithms embedded in video processors. |
| Domestic Sensor Module Assembly Scale-Up | Reduces import dependency on Japanese CMOS suppliers while capturing margin from vertical integration. |
| Hospital System Full-Service Contract | Locks in multi-year procurement commitments across device, disposable, and maintenance spend categories. |
| Telemedicine Screening Platform Development | Aligns with Korea's Digital New Deal reimbursement pathways for remote diagnostic consultation protocols. |
| Single-Use Manufacturing Capacity Expansion | Captures conversion demand from reprocessing infrastructure as cost parity achieves tipping point in Seoul clusters. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with gastrointestinal clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from MFDS registration databases, National Health Insurance Service reimbursement filings, and Korea Medical Device Industry Association trade statistics. Triangulation across these sources ensures segmentation integrity for flexible scopes, video processors, and disposable alternatives.
Historical trendline analysis of procedural volume and equipment replacement cycles informs the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, clinical application specialty, end-user scale tier, and technology integration depth. CAGRs derive from fitted growth curves applied to procedure reimbursement trends and capital equipment depreciation schedules. Forecast inputs incorporate MFDS digital health guidance evolution and domestic manufacturing capacity buildout in Gyeonggi Province biotech corridors.
Several conditions sit outside the modeled scope, including potential shifts in National Health Insurance Service screening age thresholds and unforeseen supply disruptions in Japanese optical component exports. Forecasts reflect documented assumptions about reimbursement stability and sensor cost decline trajectories. Practitioners should monitor MFDS algorithm validation timelines and single-use manufacturing cost curves for early signals of competitive inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Bronchoscopes Market
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
Netherlands Endoscopy Devices Market
Endoscopy
High-Resolution Anoscopy Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Capsule Endoscopy Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Endotherapy Devices Market
Endoscopy
Europe Disposable Endoscopes Market
Endoscopy
US Colonic Stents Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
ENT Endoscopy Market
Endoscopy
Endoscopic Ultrasound (EUS) Market
Endoscopy
Colonic Stents Market