
 Australia Respiratory Devices Market | 2026-2036
Australia Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Respiratory Devices Market Outlook
TGA conformity assessment is reorganizing competitive access for imported respiratory equipment, raising barriers for manufacturers without local quality management certification. ResMed Inc leverages its Sydney-based R&D campus to sustain design authority over sleep apnea interfaces and cloud-connected therapy platforms. Fisher & Paykel Healthcare Ltd anchors humidification technology leadership across acute and home ventilation segments. Koninklijke Philips NV competes through integrated diagnostic-to-therapy workflows spanning sleep labs and remote patient monitoring.
Respiratory devices encompass mechanical, pneumatic, and software-integrated systems engineered to assist, monitor, or replace pulmonary function through controlled gas delivery, aerosol generation, or airway pressure modulation; these systems typically incorporate flow sensors, pressure transducers, and filtration media rated to ISO 18562 biocompatibility standards for breathing gas pathways. Their primary purpose is to sustain oxygenation, reduce work of breathing, or administer pharmaceutical aerosols across acute care, chronic disease management, and preventive diagnostic settings. CPAP Devices dominate value capture given recurring mask and tubing consumables, while Smart Inhalers represent the fastest-expanding technology segment as Bluetooth-enabled dose tracking reshapes adherence protocols and reimbursement logic. Oxygen Concentrators occupy a mature margin pool where portable molecular sieve units command premium positioning against stationary alternatives.
TGA medical device regulations, aligned with MDSAP audit requirements, govern pre-market inclusion and post-market vigilance for all therapeutic respiratory equipment supplied in Australia. The Therapeutic Goods (Medical Devices) Regulations impose essential principles on electrical safety, electromagnetic compatibility, and clinical evidence that manufacturers must satisfy before ARTG listing. Stakeholders must monitor how TGA's evolving software-as-a-medical-device guidance intersects with AI-enabled diagnostic features in next-generation respiratory platforms, as this convergence will determine which product architectures secure sustained market access.
Market Dynamics
TGA's software-as-a-medical-device guidance is compressing product development timelines for cloud-connected inhalers and remote monitoring platforms, forcing manufacturers to front-load clinical validation costs before ARTG listing.
Growth Catalysts
- New South Wales hospital-to-home transitions:State health procurement frameworks now mandate portable oxygen concentrators and connected nebulizers for chronic obstructive pulmonary disease discharge protocols.
- MDSAP audit harmonization:TGA alignment with international quality management standards reduces redundant certification costs for manufacturers already holding FDA or Health Canada approvals.
- Molecular sieve miniaturization:Advances in portable oxygen concentrator weight reduction below 2.5 kilograms enable patient mobility and expand addressable homecare populations.
Market Restraints
- Software validation costs:TGA's tightened post-market surveillance for Bluetooth-enabled dose counters imposes recurring firmware audit burdens on mid-tier device manufacturers.
- Lithium-ion battery supply:Concentration of cell production in East Asian contract manufacturers creates input cost volatility and extended lead times for portable concentrator assemblers.
- Biocompatibility testing backlogs:ISO 18562 breathing gas pathway certification queues at Australian notified bodies extend product launch timelines by eight to fourteen months.
Strategic Opportunities
- Tasmania and South Australia regional expansion:Underserved rural respiratory clinics present first-mover advantages for telehealth-integrated device distributors with field service networks.
- Reimbursement code expansion:Medicare Benefits Schedule review processes for remote patient monitoring create pathway for connected inhaler adherence data to qualify for chronic disease management payments.
- AI-enabled diagnostic convergence:Integration of machine learning cough pattern analysis with existing spirometry hardware opens adjacent revenue streams in early COPD detection.
Industry Challenges
- Embedded systems engineering scarcity:Firmware developers with ISO 62304 medical device software lifecycle experience command premium salaries and extended recruitment cycles in Sydney and Melbourne labor markets.
- Legacy hospital IT integration:Cloud-connected respiratory platforms face interoperability friction with state-wide electronic medical record systems that lack standardized API architectures for real-time therapy data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Respiratory Devices Market |
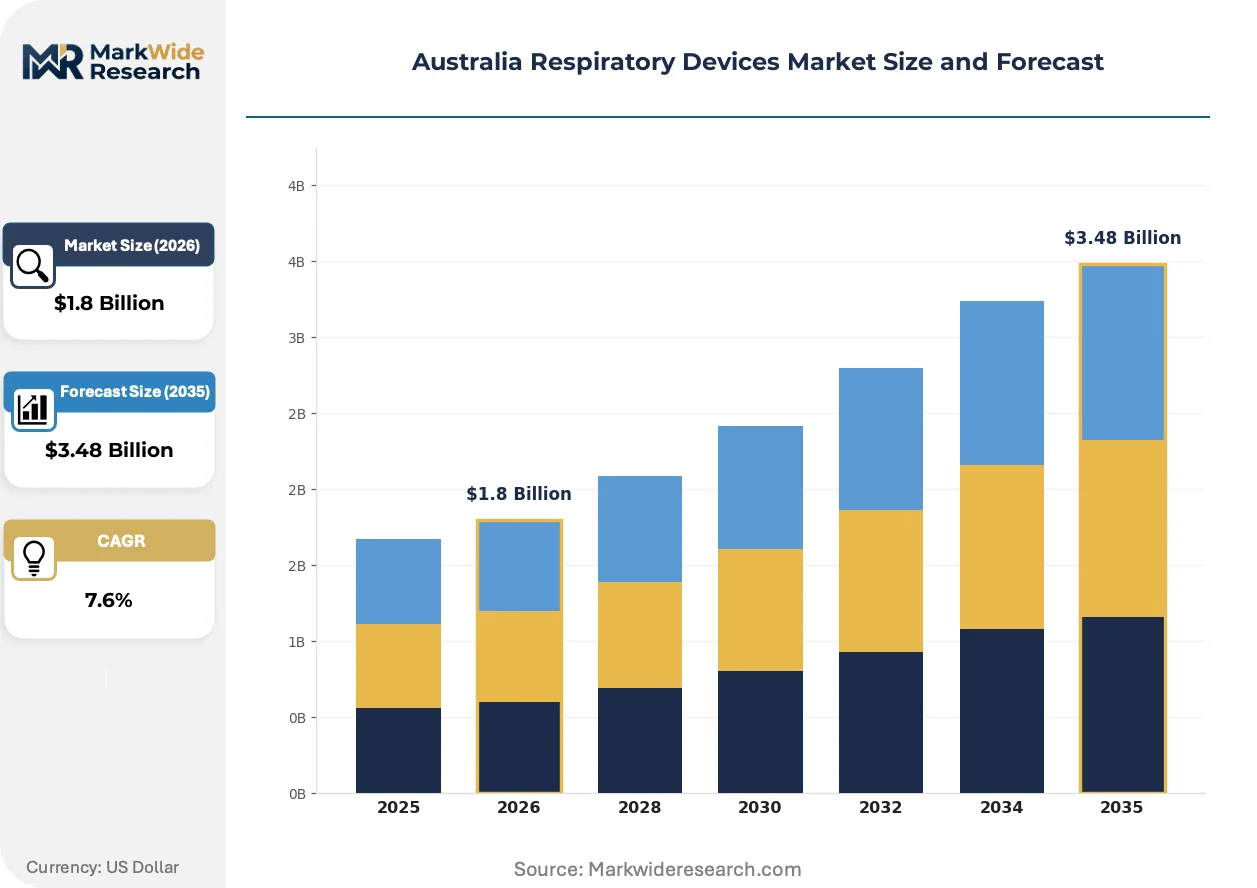
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oxygen Concentrators, CPAP Devices End User: Hospitals, Clinics, Homecare, Long-Term Care Facilities Technology: High-Frequency Oscillation, Portable Devices, Smart Inhalers, Biomedical Sensors Distribution Channel: Pharmacies, Online Retail, Medical Supply Stores, Direct Sales |
| Companies Covered | ResMed Inc, Koninklijke Philips NV, Fisher & Paykel Healthcare Ltd, GE Healthcare, Drägerwerk AG & Co. KGaA, Medtronic PLC, Invacare Corporation, Drive Medical, GSK plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Respiratory Devices Market Strategic Shifts
Digital biomarker extraction from everyday respiratory device use is displacing episodic clinical assessment, embedding diagnostic capability directly into therapy hardware and reshaping how pharmaceutical adherence is measured and reimbursed.
Smart inhaler technology is fragmenting the traditional pharmaceutical-aerosol market by capturing granular dose-timing data that payers now require for prior authorization of biologic asthma therapies. Victorian hospital networks are piloting Bluetooth-enabled propellant devices that transmit usage patterns to centralized pharmacy dashboards. This data layer is compressing margins for conventional metered-dose inhalers while creating subscription revenue pools for platform-enabled device-as-a-service models.
TGA's evolving guidance on software-enabled respiratory devices is tightening evidentiary requirements for algorithm-driven diagnostic features embedded in home sleep apnea testing units. Manufacturers must now submit local clinical validation studies demonstrating equivalence to polysomnography before ARTG inclusion. Sleep clinic operators in New South Wales are responding by consolidating procurement around vendors with established Australian regulatory dossiers, raising competitive barriers for imported platforms without domestic clinical footprints.
Homecare providers are consolidating purchasing authority through state-level tender frameworks that bundle device procurement with remote monitoring service obligations. Queensland Health's recent respiratory equipment panel contracts require winning bidders to supply cloud connectivity infrastructure and patient adherence analytics as standard inclusions. This unbundling of hardware from data services is visible most acutely in oxygen concentrator segments, where standalone device margins compress against integrated therapy management contracts.
Australia Respiratory Devices Market Segmentation
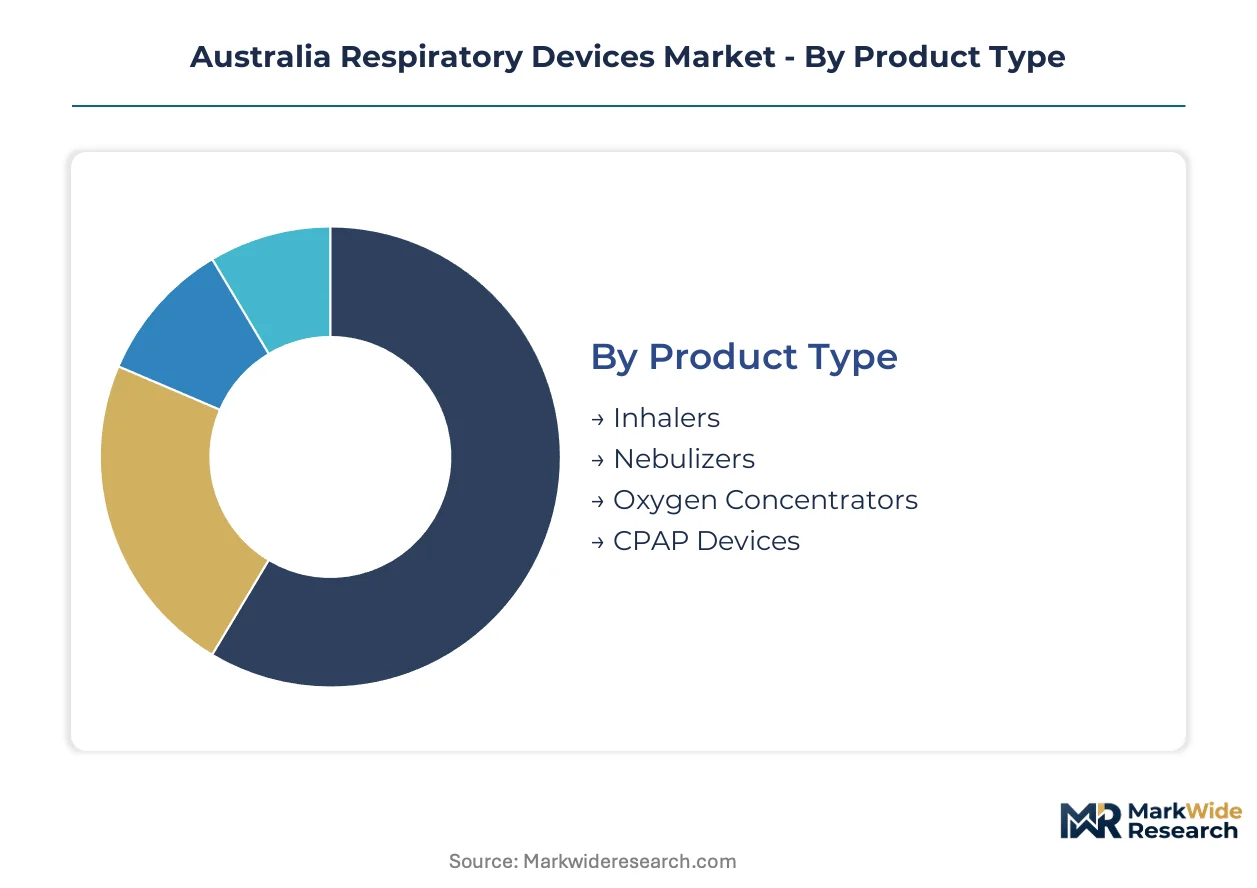
Segmentation reveals how TGA regulatory pressure and hospital-to-home transitions reshape procurement patterns across device categories. Understanding these divides exposes where substitution threats from digital biomarkers and telehealth platforms concentrate most intensely.
Product Type:
Smart inhalers and connected platforms face acute substitution pressure from smartphone-based symptom tracking apps that bypass hardware entirely.
- Inhalers:Metered-dose and dry-powder devices deliver bronchodilators and corticosteroids through standardized aerosol mechanics. Demand concentrates in Victorian pharmacy networks where chronic asthma prevalence drives repeat prescription volumes, though Bluetooth-enabled alternatives erode conventional unit economics.
- CPAP Devices:Continuous positive airway pressure systems modulate upper airway patency through turbine-generated airflow and mask interfaces. New South Wales sleep clinics anchor procurement volumes as diagnostic backlogs convert to therapy initiation, with cloud-connected platforms capturing preference in state tender frameworks.
- Oxygen Concentrators:Molecular sieve units extract medical-grade oxygen from ambient air for hypoxemic patients.
- Nebulizers:Compressor and mesh devices aerosolize liquid medications for deep lung deposition.
CPAP devices anchor the volume base while smart inhalers gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital installations from distributed homecare procurement with diverging margin profiles.
- Homecare:Patient-directed settings encompass domiciliary oxygen therapy, sleep apnea management, and nebulized medication regimens. Queensland Health's bundled tender models now mandate remote monitoring infrastructure as standard, compressing standalone device margins into service-contract economics.
- Hospitals:Acute care facilities deploy high-flow nasal cannula systems, mechanical ventilators, and ICU-grade humidification across emergency and critical care wards. Victorian and New South Wales procurement frameworks prioritize devices with EMR interoperability, excluding vendors lacking standardized data exchange protocols.
- Clinics:Outpatient respiratory services include spirometry, sleep study interpretation, and chronic disease monitoring.
- Long-Term Care Facilities:Aged care residences manage COPD and obstructive sleep apnea in multimorbid populations.
Hospitals dominate capital expenditure while homecare segments expand most quickly through state-mandated discharge protocols.
Technology:
Application focus determines which platforms capture clinical workflow integration versus standalone consumer positioning.
- Smart Inhalers:Bluetooth-enabled dose counters and propellant devices capture timestamped usage data for adherence analytics. TGA's software-as-medical-device guidance imposes local clinical validation requirements that favor ResMed's Sydney-based regulatory dossier over imported alternatives.
- Biomedical Sensors:Wearable and implantable transducers monitor respiratory rate, oxygen saturation, and airflow patterns. Tasmanian rural health networks pilot chest-worn accelerometers for remote COPD exacerbation detection, bypassing conventional spirometry infrastructure.
- Portable Devices:Battery-powered concentrators and travel CPAP units enable patient mobility outside clinical settings.
- High-Frequency Oscillation:Ventilatory support through rapid pressure oscillation targets neonatal and acute respiratory distress populations.
Portable devices anchor installed base volumes while biomedical sensors climb the fastest through Medicare remote monitoring reimbursement expansion.
Distribution Channel:
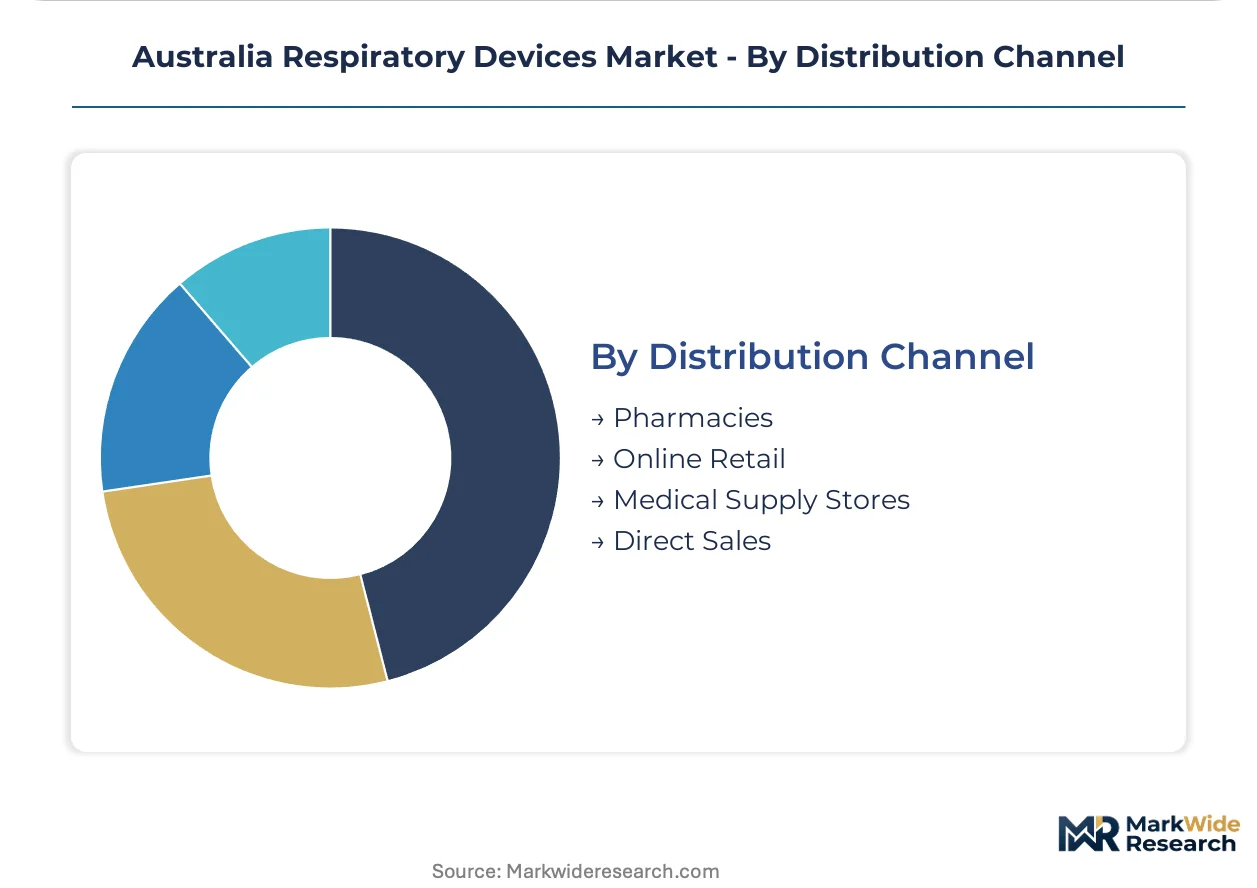
Customer type fragmentation separates institutional procurement through direct sales from fragmented retail pharmacy and emerging digital pathways.
- Direct Sales:Manufacturer-to-provider contracts dominate hospital and state health panel procurement, bundling devices with training, maintenance, and data analytics. Queensland Health's respiratory equipment panels require winning bidders to supply cloud connectivity and adherence reporting as mandatory inclusions.
- Online Retail:E-commerce platforms enable patient-direct acquisition of travel CPAP units, portable concentrators, and replacement consumables. Victorian consumers increasingly bypass pharmacy intermediaries for mask and tubing resupply, compressing traditional retail margins.
- Pharmacies:Community dispensaries retain inhaler and nebulizer medication-device combination dominance.
- Medical Supply Stores:Specialized durable medical equipment retailers serve homecare oxygen and sleep therapy markets.
Direct sales capture institutional value pools while online retail segments expand most quickly through consumer-direct resupply behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TGA's post-market surveillance reforms and state-level hospital-to-home procurement mandates are redistributing respiratory device demand across Australia's eastern seaboard and emerging regional markets.
New South Wales
Sydney's sleep clinic networks and chronic disease management programs anchor the nation's largest respiratory device procurement volumes. State Health mandates portable oxygen concentrators for COPD discharge protocols under the NSW Integrated Care Strategy. The Westmead Health Precinct hosts clinical validation trials for cloud-connected CPAP platforms seeking ARTG inclusion.
Victoria
Melbourne's aging demographic concentration drives nebulizer and humidification system demand through hospital networks and community pharmacy channels. The Victorian Department of Health's Digital Health Strategy prioritizes EMR-interoperable respiratory devices in public tender frameworks. The Parkville biomedical cluster supports local firmware development for Bluetooth-enabled inhaler dose counters.
Queensland
Brisbane's state health procurement panels now bundle remote monitoring infrastructure with oxygen concentrator contracts under revised respiratory equipment frameworks. The Therapeutics Innovation Queensland program accelerates clinical validation timelines for software-enabled diagnostic devices. Gold Coast telehealth hubs pilot rural patient adherence analytics for portable ventilation systems.
Western Australia
Perth's mining workforce health programs generate distinct demand for portable sleep apnea screening and occupational respiratory protection. The WA Country Health Service expands home oxygen therapy access through regional telehealth-integrated distribution networks. The Fiona Stanley Hospital cluster validates remote patient monitoring platforms for isolated community deployment.
Australia Respiratory Devices Market Competitive Environment
Listed leaders compete with private specialists across regulatory dossier depth and cloud platform integration capabilities. The market exhibits tiered concentration where multinational manufacturers with Sydney-based clinical validation capabilities capture state tender volumes, while mid-tier distributors serve fragmented pharmacy and homecare channels. Three archetypes dominate: integrated diagnostic-to-therapy platform vendors, humidification technology specialists, and regional field-service distributors. Competitive dynamics center on M&A activity consolidating remote monitoring service capabilities and strategic partnerships securing lithium-ion battery supply chains for portable concentrator portfolios.
Within the platform-integrated tier, ResMed Inc and Fisher & Paykel Healthcare Ltd exemplify archetypes distinguished by Sydney-based R&D infrastructure and regulatory dossier depth. Koninklijke Philips NV occupies a position spanning diagnostic workflow integration across sleep lab and home monitoring segments. These three manufacturers anchor procurement preference in state health frameworks where TGA software-as-medical-device compliance determines tender eligibility.
| Leading Market Players |
|---|
| ResMed Inc |
| Koninklijke Philips NV |
| Fisher & Paykel Healthcare Ltd |
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Medtronic PLC |
| Invacare Corporation |
| Drive Medical |
| GSK plc |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen month ISO 18562 certification queues at Australian notified bodies concentrate pricing power among manufacturers with pre-established TGA dossiers, forcing mid-tier competitors to absorb extended working capital costs or exit tender participation.
Pricing Analysis
Certification level (ISO/CE/TGA-grade) creates the primary spread between premium cloud-connected platforms and commodity inhaler alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies around software validation depth, with Bluetooth-enabled dose counters commanding subscription-service premiums against per-unit disposable economics. Cost compression in mid-tier portable concentrators is intensifying because Queensland Health's bundled tender models unbundle hardware margins into remote monitoring service contracts. Homecare patients demonstrate highest price sensitivity for replacement mask and tubing consumables, while hospital purchasing committees prioritize total cost-of-ownership metrics that favor integrated platform vendors.
Supply Chain Analysis
Extended lithium-ion cell lead times from East Asian contract manufacturers constrain portable oxygen concentrator assembly schedules and amplify inventory carrying costs for Australian distributors. Component sourcing draws from China, South Korea, and Japan for molecular sieve membranes, pressure transducers, and battery cells. Firmware development capacity scarcity in Sydney and Melbourne labor markets creates single-source vulnerability for software-enabled device programs. Distribution runs through state health procurement panels for institutional volumes, with direct-to-consumer online channels capturing growing replacement consumable demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware developers with ISO 62304 medical device software lifecycle expertise command premium recruitment cycles in Australian metropolitan labor markets, constraining product development velocity for platform-enabled respiratory devices.
For Market Incumbents: Consolidate cloud platform interoperability capabilities through acquisition of telehealth infrastructure specialists, defending against substitution threats from smartphone-based symptom tracking apps that bypass hardware entirely. Deepen Sydney-based clinical validation assets to maintain TGA software-as-medical-device compliance advantages over imported competitors lacking local regulatory footprints. For New Entrants and Emerging Players: TGA's MDSAP audit harmonization pathway offers accelerated ARTG listing for manufacturers holding FDA or Health Canada approvals, enabling faster market entry than de novo certification routes. Target Tasmania and South Australia rural respiratory clinics as first-mover geography, deploying telehealth-integrated field service networks where incumbent coverage remains sparse. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational medical device parents seeking to divest non-core respiratory portfolios, particularly humidification technology units lacking cloud connectivity roadmaps. Long-term viability hinges on software-enabled diagnostic convergence capabilities, with AI-enabled cough pattern analysis integration serving as the critical inflection signal for platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Software-as-Medical-Device Compliance Investment | Local clinical validation studies secure ARTG inclusion ahead of algorithm-driven diagnostic competitors. |
| Remote Monitoring Infrastructure Partnership | Queensland Health's bundled tender models mandate cloud connectivity as standard procurement requirement. |
| Lithium-Ion Battery Supply Agreement | East Asian cell production concentration creates input cost volatility for portable concentrator assemblers. |
| Biomedical Sensor Integration Development | Medicare remote monitoring reimbursement expansion accelerates wearable transducer adoption in Tasmanian rural networks. |
| Hospital EMR Interoperability Certification | Victorian Digital Health Strategy prioritizes standardized data exchange protocols in public tender frameworks. |
Study Parameters
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and homecare respiratory therapists anchored the qualitative base. Primary interview insights combined with secondary validation against TGA ARTG listings, state health procurement panel contracts, Medicare Benefits Schedule reimbursement databases, and ISO 18562 notified body certification records. Bottom-up device shipment estimates triangulated against top-down healthcare expenditure flows across the analysis window.
Sensitivity analysis tested forecast outputs against alternative scenarios for TGA software guidance evolution and lithium-ion supply disruption. Segmentation modeling incorporated product type, end user setting, technology platform, and distribution channel dimensions throughout the forecast period. CAGRs derived from weighted average growth contributions across segment-level demand drivers, with hospital-to-home transition velocity and remote monitoring reimbursement expansion serving as primary respiratory device market inputs.
Underlying assumptions cover TGA regulatory timeline stability and state health procurement framework continuity, with deviation risk concentrated in firmware audit burden escalation and biocompatibility testing backlog extension. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Capnography Market
Medical Devices
Electroencephalography (EEG) Systems Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Helium Free MRI Scanners Market
Medical Devices
Prescription Lens Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
Radial Access Catheter Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
Penile Implants Market
Medical Devices
Urine Flow Meters Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Global Occlusion Devices Market
Medical Devices
Pedicle Screw Systems Market
Medical Devices
Catheter Coatings Market
Medical Devices
Global Body Contouring Devices Market
Medical Devices
Europe Electroencephalography Devices Market