
 Global Portable Ultrasound Equipment Market | 2026-2036
Global Portable Ultrasound Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Ultrasound Equipment Market Intelligence
The integration of AI-driven diagnostic algorithms and wireless connectivity is reconfiguring the fundamental design of portable ultrasound systems, shifting them from simple imaging tools to connected diagnostic platforms. GE HealthCare leverages its extensive hospital network to deploy these advanced systems at scale. Siemens Healthineers competes through its specialized software for cardiology and obstetrics applications. Butterfly Network, Inc. differentiates with its unique semiconductor-based, single-probe technology for ultra-portable handheld devices.
Portable ultrasound equipment comprises compact, non-invasive systems that generate real-time anatomical images using high-frequency sound waves, typically operating between 2 and 18 megahertz. Their primary function is to enable rapid diagnostic imaging directly at the point of care, bypassing traditional radiology departments. Handheld devices represent the fastest-growing product segment, gaining significant traction in emergency medicine and general practice. In contrast, more powerful laptop-integrated units continue to be standard in cardiology and obstetrics applications.
Regulatory frameworks strictly govern market entry for these Class II medical devices. The US FDA's 510(k) clearance pathway, Europe's CE marking under the Medical Device Regulation (MDR), and approvals from China's NMPA are critical hurdles. These regulations enforce rigorous testing for patient safety, diagnostic efficacy, and data interoperability. Navigating the evolving requirements for software as a medical device (SaMD) and ensuring robust cybersecurity for connected systems are becoming central strategic challenges for all manufacturers.
Market Dynamics
The central structural force shaping the market is the convergence of advanced piezoelectric materials and AI-driven software. This combination enables the production of highly portable, yet diagnostically powerful, ultrasound systems for immediate use at the point of care.
Growth Catalysts
- Point-of-Care Expansion:Surging utilization within emergency medicine and critical care units in the United States is creating a baseline of demand for rapid, non-invasive diagnostic tools.
- Technological Miniaturization:Ongoing advancements in piezoelectric transducer technology and semiconductor fabrication allow for smaller, more powerful handheld devices, expanding the addressable market to new clinical settings.
- Favorable Reimbursement:Supportive reimbursement policies for outpatient ultrasound procedures in countries like Germany and France encourage investment in portable systems by specialized ambulatory clinics.
Market Restraints
- Regulatory Scrutiny:Rigorous and evolving regulatory pathways, including the US FDA's 510(k) clearance and Europe's MDR, create significant time-to-market delays and compliance costs.
- Image Quality Trade-offs:Ultra-portable handheld devices can exhibit inferior image resolution for deep anatomical structures compared to larger cart-based systems, limiting their utility in some diagnostic scenarios.
- High Acquisition Cost:The initial capital investment required for premium portable systems, particularly those with advanced AI software licenses, remains a barrier for smaller clinics and healthcare facilities in developing economies.
Strategic Opportunities
- Tele-Ultrasound Services:Integrating portable ultrasound with telehealth platforms offers the ability to conduct expert-guided scans in remote or underserved regions, creating a new service delivery model.
- Veterinary Medicine:The non-invasive nature and portability of handheld scanners present a significant growth opportunity in veterinary practices for both companion animals and livestock diagnostics.
- Emerging Economies:Underpenetrated healthcare markets across Southeast Asia and Latin America represent a major opportunity as primary care and emergency response infrastructure develops.
Industry Challenges
- Training and Skill Gaps:A widespread shortage of clinicians proficient in performing and interpreting point-of-care ultrasound examinations limits the effective deployment and clinical impact of the technology.
- Data Interoperability:Ensuring seamless integration of ultrasound imaging data from multiple vendors' devices into a hospital's central electronic health record (EHR) and picture archiving systems remains a persistent technical challenge.
- Cybersecurity Risks:The increasing connectivity of wireless ultrasound devices exposes them to potential data breaches, demanding robust cybersecurity measures to protect sensitive patient information and comply with HIPAA and GDPR.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Ultrasound Equipment Market |
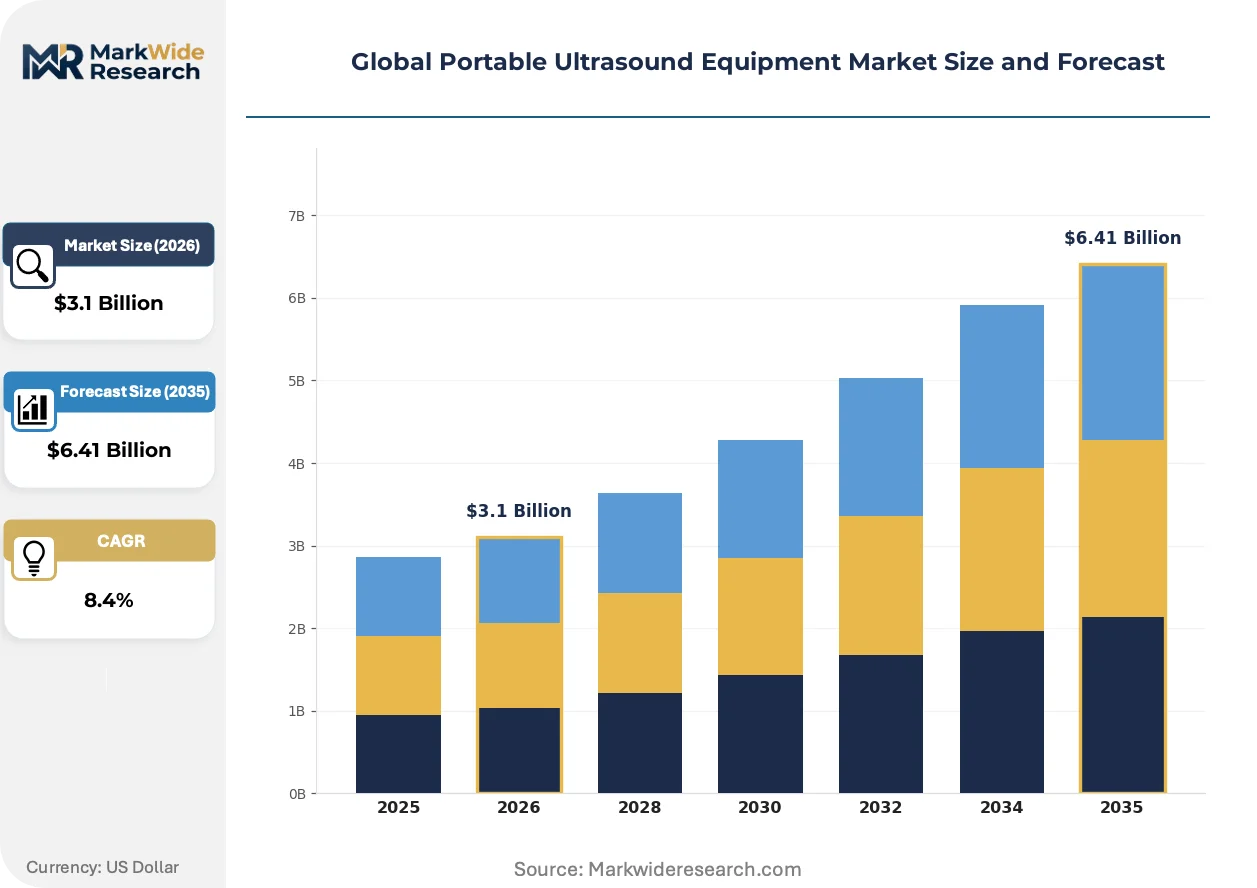
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Laptop-Integrated Units, Tablet Ultrasounds, Compact Carts Technology: Doppler Ultrasound, 3D Imaging, Wireless Connectivity, Real-Time Imaging, Color Flow Application: Point-of-Care, Emergency Medicine, Obstetrics, Cardiology, Veterinary Diagnostics End User: Ambulatory Clinics, Diagnostic Laboratories, Mobile Health Units, Research Institutions |
| Companies Covered | Canon Medical Systems Corporation, Mindray Medical International Limited, GE HealthCare, Butterfly Network, Inc., Samsung Medison, Siemens Healthineers, FUJIFILM Holdings Corporation, Esaote S.p.A., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Ultrasound Equipment Market Strategic Shifts & Innovations
The fundamental character of portable ultrasound is changing, shifting from a standalone imaging device to an interconnected, software-defined diagnostic platform. This evolution is driven by advancements in semiconductor technology, wireless connectivity, and the growing importance of data integration within clinical workflows.
Semiconductor-based transducer technology integrates the entire ultrasound system onto a single silicon chip. Emergency medicine and general practice physicians are adopting these single-probe devices that connect directly to standard smartphones or tablets. This technology is hybridizing the traditional multi-component system into a singular, pocket-sized diagnostic tool, fundamentally altering the product's form factor and cost structure.
Europe's Medical Device Regulation (MDR) establishes a more stringent framework for clinical validation and post-market surveillance compared to the previous directive. This significantly increases the burden of proof for manufacturers, especially for software as a medical device (SaMD). Systems incorporating AI-driven diagnostic algorithms are most affected, as they must now demonstrate ongoing safety and performance through real-world data collection.
A transition from one-time capital equipment sales to recurring subscription models is gaining momentum among healthcare providers. This approach lowers the initial financial barrier to entry and provides continuous access to the latest software features and security updates, displacing traditional procurement cycles. The trend is most prominent within private practice groups and departmental budgets in the United States and key Western European markets.
Global Portable Ultrasound Equipment Market Segmentation
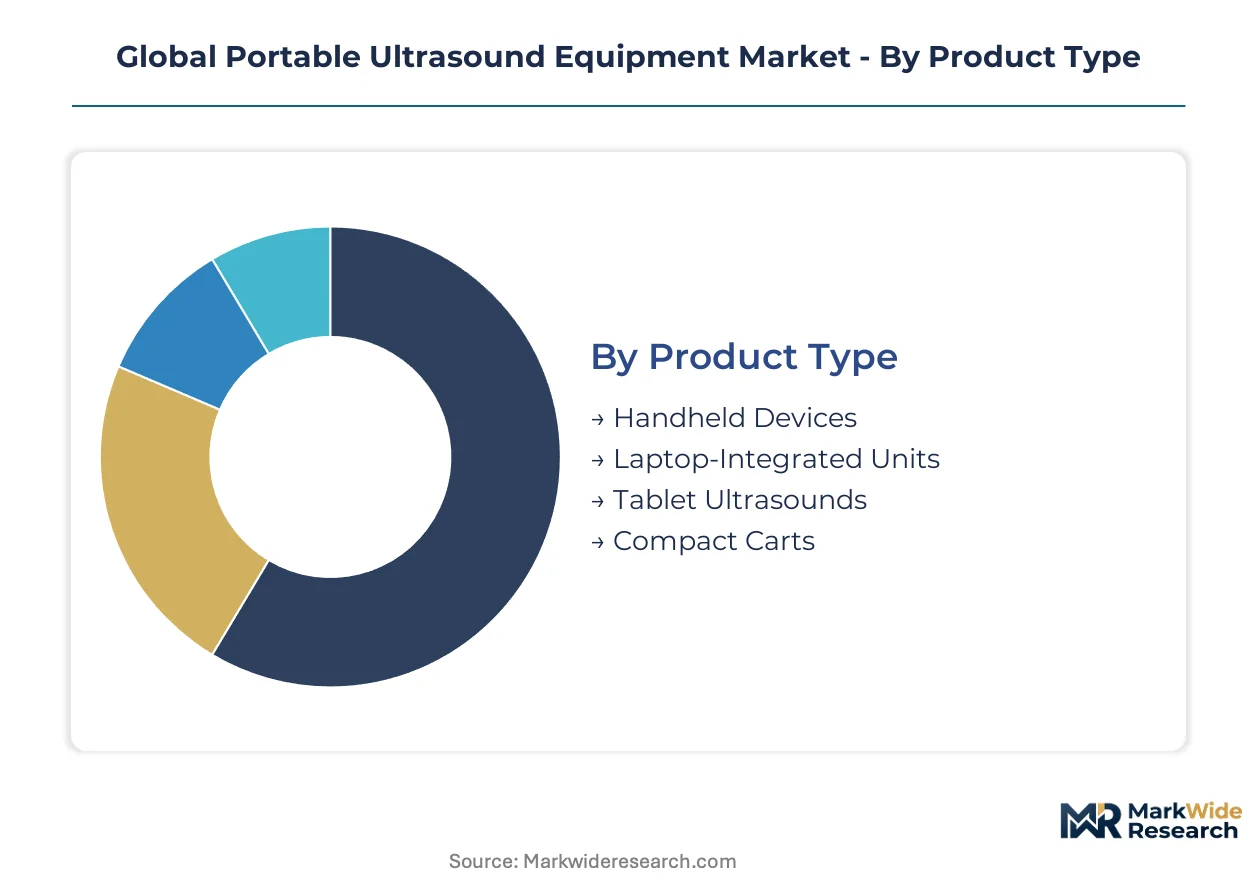
Understanding the market's segmentation reveals the precise areas of innovation and demand within portable ultrasound equipment. This granular view allows manufacturers to tailor product development and market strategies to specific clinical needs and user preferences. The distinct requirements of various end-users and applications shape the competitive landscape.
Product Type:
The after-sales service intensity varies significantly across product types, influencing lifecycle costs and customer loyalty. More complex, integrated systems often require specialized maintenance contracts and software updates, creating recurring revenue streams for manufacturers. Simpler handheld devices, while easier to service, depend on high-volume sales and accessory ecosystems.
- Handheld Devices:These ultra-portable systems integrate a transducer with a small display or connect directly to smartphones/tablets, enabling rapid diagnostic imaging at the point of care. Demand concentrates within emergency medicine departments in the United States, driven by their immediate accessibility for initial assessments.
- Laptop-Integrated Units:These systems pair a dedicated ultrasound transducer with a standard laptop, offering more processing power and advanced imaging capabilities than handheld devices. These units are standard in cardiology and obstetrics applications across Western Europe, where detailed imaging is critical for complex diagnoses.
- Tablet Ultrasounds:These devices combine the portability of tablets with dedicated ultrasound functionalities, providing a balance between compact design and enhanced display for clinical workflows.
- Compact Carts:These mobile units offer comprehensive imaging features with larger screens and multiple probe options, providing flexibility for various diagnostic procedures within hospital settings.
Laptop-Integrated Units holds the largest share; momentum sits with Handheld Devices, which represent the fastest-growing product segment.
Technology:
Different technologies enable distinct applications and diagnostic capabilities within portable ultrasound systems. The choice of technology directly impacts image quality, diagnostic accuracy, and the overall utility of the device in specific clinical scenarios. Advanced features like AI integration transform data acquisition and interpretation.
- Doppler Ultrasound:This technology measures blood flow velocity and direction, crucial for assessing cardiovascular health and detecting vascular abnormalities. Its application is fundamental in cardiology clinics and vascular surgery departments across Germany for non-invasive diagnoses.
- 3D Imaging:This advanced technique generates volumetric anatomical data, providing enhanced visualization of complex structures and improved diagnostic confidence. Obstetrics departments in France utilize 3D imaging for detailed fetal assessments and anomaly detection.
- Wireless Connectivity:This feature allows seamless data transfer and integration with electronic health records, enhancing workflow efficiency and enabling remote consultation.
- Real-Time Imaging:This core capability provides immediate visualization of anatomical structures and physiological processes, essential for dynamic assessments and guided procedures.
- Color Flow:This imaging mode visualizes blood flow in different colors, aiding in the identification of blood vessel patency and the presence of blockages.
Doppler Ultrasound maintains its foundational role, while 3D Imaging shows significant promise due to its enhanced diagnostic capabilities in specialized fields.
Application:
The volume of diagnostic procedures dictates the demand for portable ultrasound equipment across various applications. Each clinical setting requires specific features and levels of portability, influencing product design and market penetration. Specialized applications often drive the adoption of advanced technological features.
- Point-of-Care:This application involves immediate diagnostic imaging directly at the patient's bedside or examination room, significantly reducing diagnostic delays. Utilization within emergency medicine and critical care units in the United States drives the demand for rapid, non-invasive tools.
- Emergency Medicine:Portable ultrasound devices are critical for rapid assessment of trauma, cardiac conditions, and abdominal issues in urgent care settings, enabling quick decision-making. Their deployment in US emergency departments ensures efficient triage and immediate intervention.
- Obstetrics:Routine prenatal check-ups and monitoring of fetal development constitute a significant application, requiring detailed imaging capabilities and patient comfort.
- Cardiology:Assessment of heart function, valve integrity, and blood flow dynamics represents a specialized application demanding high-resolution imaging and Doppler capabilities.
- Veterinary Diagnostics:The non-invasive nature of portable ultrasound supports imaging for companion animals and livestock, enabling diagnoses for various medical conditions.
Demand for Point-of-Care continues to expand, reflecting the need for immediate diagnostic tools, while Emergency Medicine is also climbing due to its critical role in rapid patient assessment.
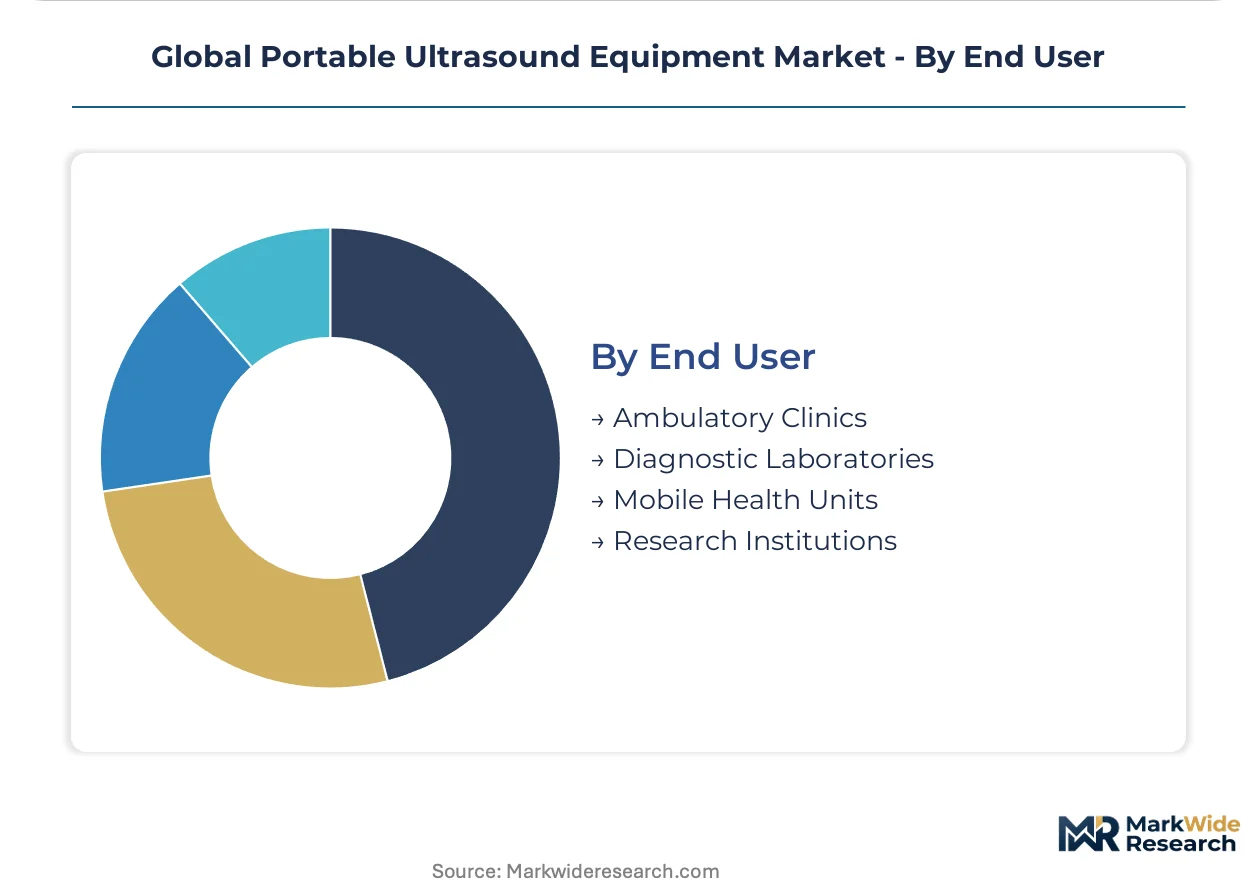
End User:
The type of customer influences procurement patterns, feature requirements, and budget considerations for portable ultrasound systems. Different end-user environments necessitate varying levels of ruggedness, connectivity, and integration with existing healthcare infrastructure. Procurement is shifting towards subscription models for many end-users.
- Ambulatory Clinics:These outpatient facilities require compact, easy-to-use systems for routine diagnostics and specialized procedures, prioritizing efficiency and patient throughput. Specialized ambulatory clinics across Germany and France are investing in these systems due to supportive reimbursement policies.
- Diagnostic Laboratories:These facilities often integrate portable ultrasound with other diagnostic equipment, demanding robust data interoperability and high-quality imaging for accurate results. Laboratories in the United States require seamless integration with central electronic health records.
- Mobile Health Units:These units provide healthcare services in remote or underserved areas, relying on ultra-portable and durable devices for basic diagnostic imaging.
- Research Institutions:These organizations utilize portable ultrasound for clinical trials, physiological studies, and device development, requiring advanced features and data acquisition capabilities.
The market for Ambulatory Clinics is evolving with the shift towards outpatient care, and Diagnostic Laboratories are also seeing shifts in procurement to support integrated digital workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Exports of portable ultrasound equipment from advanced manufacturing hubs like Germany to specialized ambulatory clinics in Western Europe drive significant market activity. This global market sees diverse demand patterns influenced by healthcare infrastructure, regulatory environments, and economic development across key regions. The continuous evolution of diagnostic needs shapes regional investment in these compact imaging systems.
United States
The United States market for portable ultrasound equipment is driven by surging utilization within emergency medicine and critical care units for rapid diagnostic tools. The US FDA's 510(k) clearance pathway governs market entry, ensuring devices meet safety and efficacy standards. Boston's medical technology cluster focuses on advanced diagnostic device development, integrating AI and connectivity features into new systems.
Germany
German demand for portable ultrasound stems from specialized ambulatory clinics and cardiology departments, supported by favorable reimbursement policies for outpatient procedures. Europe's CE marking under the Medical Device Regulation (MDR) requires rigorous testing for patient safety and diagnostic performance. Munich's medtech firms develop specialized software for cardiology and obstetrics applications, enhancing device utility.
China
China's expanding primary care and emergency response infrastructure creates substantial demand for portable ultrasound systems in underserved areas. Approvals from China's NMPA are critical hurdles for manufacturers seeking market access. Shenzhen's manufacturing base produces cost-effective portable ultrasound systems for both domestic consumption and export markets, driving accessibility.
France
French obstetrics departments utilize portable ultrasound for detailed fetal assessments and anomaly detection, alongside general practice applications. The ANSM, France's national agency for the safety of medicines and health products, oversees device regulation in conjunction with CE marking requirements. Lyon's healthcare technology ecosystem supports innovation in 3D imaging for portable ultrasound, improving diagnostic confidence.
India
India represents a significant opportunity due to underpenetrated healthcare markets and a growing need for accessible diagnostic imaging. The CDSCO (Central Drugs Standard Control Organization) regulates medical devices, with evolving guidelines for portable ultrasound equipment. Bengaluru's tech industry fosters integration of AI-driven diagnostic algorithms into portable systems, enhancing diagnostic capabilities in remote settings.
Global Portable Ultrasound Equipment Market Key Industry Players
Channel-controlling players compete with product-specialist players across the global portable ultrasound equipment market. The market exhibits a tiered structure, with large diversified healthcare technology conglomerates alongside agile, innovation-focused startups. Strategic archetypes include integrated solution providers, niche technology developers, and cost-effective mass manufacturers. Portfolio diversification and strategic partnerships are dominant competitive moves among established firms.
Among integrated solution providers, GE HealthCare and Siemens Healthineers represent large-scale players leveraging extensive networks and specialized software capabilities. Butterfly Network, Inc. exemplifies a technology-driven innovator, focusing on semiconductor-based, single-probe devices for ultra-portable handheld applications. These firms occupy distinct positions within the market, from comprehensive hospital system integration to highly specialized point-of-care diagnostics. This differentiation shapes competitive dynamics across product segments.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Mindray Medical International Limited |
| GE HealthCare |
| Butterfly Network, Inc. |
| Samsung Medison |
| Siemens Healthineers |
| FUJIFILM Holdings Corporation |
| Esaote S.p.A. |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
Semiconductor fabrication concentration in East Asia directly influences the cost structure of portable ultrasound systems, impacting where profit margins accumulate across the value chain. This upstream dependency shapes component availability and pricing for global manufacturers.
Pricing Analysis
The pricing gap between advanced laptop-integrated units and basic handheld devices remains significant, reflecting varied diagnostic capabilities and software integration. Hybrid pricing models combine an initial hardware purchase with recurring software subscription fees for AI features and security updates. Regulatory clearance, such as US FDA 510(k) approval, and specialized after-sales service bundles are crucial price differentiation drivers. Pricing pressure stems from the increasing availability of cost-effective handheld devices, particularly for general practice applications. Smaller clinics and healthcare facilities in developing economies exhibit the highest price sensitivity, favoring lower-cost, essential functionality.
Supply Chain Analysis
Logistics chokepoints and geopolitical tensions create structural risks for the supply of critical components like piezoelectric materials and specialized semiconductor chips. Geographic supply concentration for these inputs is high, primarily in China, Japan, and South Korea. Manufacturers depend on a limited number of specialized suppliers for high-frequency sound wave transducers. Downstream distribution runs through a mix of direct sales channels to large hospital networks and third-party medical equipment distributors serving smaller clinics and international markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable ultrasound market faces a critical capability gap, specifically in the widespread proficiency for performing and interpreting point-of-care ultrasound examinations. Addressing this skill shortage is paramount for clinical impact.
For Market Incumbents:
Build an extensive ecosystem moat by integrating advanced AI diagnostic algorithms with existing electronic health record systems. This deep integration mitigates the threat from agile software-focused startups and enhances clinical workflow efficiency. Invest in robust cybersecurity measures and secure cloud infrastructure to protect sensitive patient data. Expand POCUS training programs for clinicians, leveraging established hospital networks to drive adoption and skill development.
For New Entrants and Emerging Players:
Establish a beachhead in underserved markets by offering ultra-portable, smartphone-connected devices with intuitive interfaces. Veterinary medicine and remote healthcare across Southeast Asia present significant white-space targets. Focus on developing specialized AI-driven applications for niche diagnostic areas, offering a distinct value proposition. A subscription-based go-to-market angle can lower initial acquisition barriers for smaller clinics and individual practitioners.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upward across the software development and AI integration segments of portable ultrasound. The long-term viability favors firms that can effectively combine hardware miniaturization with advanced, clinically validated software. Acquisition target archetypes include niche AI diagnostics companies and telehealth platform providers with strong integration capabilities. A signal to watch is the increasing adoption rate of subscription models for medical device software across key markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven diagnostic algorithms | Enhances diagnostic accuracy and reduces reliance on expert interpretation, expanding point-of-care utility. |
| Expand POCUS training and certification programs | Addresses the critical skill gap among clinicians, accelerating wider adoption of portable ultrasound systems. |
| Integrate tele-ultrasound capabilities with telehealth platforms | Extends diagnostic reach to remote and underserved regions, creating new service delivery models. |
| Secure regulatory clearances for Software as a Medical Device (SaMD) | Ensures market access and validates the safety and efficacy of AI-powered diagnostic features. |
| Implement robust cybersecurity protocols for connected devices | Protects sensitive patient data and maintains compliance with regulations like HIPAA and GDPR. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a comprehensive understanding of the portable ultrasound equipment market. Primary interviews included emergency physicians, cardiologists, biomedical engineers, hospital procurement managers, and regulatory affairs specialists. This primary data was then validated against extensive secondary research, including FDA 510(k) databases, CE marking registries, medical device industry reports, and clinical trials databases, triangulating findings through both bottom-up and top-down analyses.
The calibration approach involved developing a robust analytical framework that models market dynamics across the analysis window. Segmentation dimensions included product type, technology, application, end-user, and the critical differentiating factor of wireless connectivity features. Compound annual growth rates were derived through a multi-variable regression analysis, incorporating factors such as healthcare infrastructure development and regulatory approval timelines. Forecast inputs also considered the expansion of POCUS training programs and the adoption rates of telehealth services.
Stress conditions across reimbursement policies and cybersecurity risks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements and market acceptance. Unexpected regulatory shifts or global economic downturns could significantly revise these projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Gastric Electrical Stimulators Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Clear Aligners Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Eye Massage Device Market
Medical Devices
Endoscope Procedure Kits Market
Medical Devices
Digital Medical Thermometers Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Global Anesthesia Gas Blender Market
Medical Devices
Asthma Device Market
Medical Devices
Continuous Bladder Irrigation Devices Market