
 Bariatric Beds Market | 2026-2036
Bariatric Beds Market Size, Share, and Industry Trends Forecast 2026-2036
Bariatric Beds Market Intelligence
ISO 13485 certification is reorganizing competitive access in bariatric bed manufacturing, filtering out suppliers lacking quality management systems for medical devices. Stryker leverages its vertical integration across hospital bed platforms to sustain premium positioning in acute care settings. Hillrom dominates North American distribution through direct sales teams that control institutional purchasing relationships.
Bariatric beds are heavy-duty medical sleep surfaces engineered with reinforced steel frames, expanded width configurations typically spanning 42 to 60 inches, and weight capacities exceeding 600 pounds to safely accommodate obese patients during treatment and recovery. Fully electric beds command the strongest margin pools as healthcare facilities prioritize staff ergonomics and patient positioning automation over manual alternatives. Long-term care homes represent the fastest-growing application segment as aging demographics and obesity prevalence converge to reshape residential care requirements.
FDA 510(k) premarket notification requirements govern powered bed safety standards in the United States, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for CE-marked products sold across Europe. The Joint Commission accreditation standards in the United States further influence hospital procurement by embedding safe patient handling protocols into facility certification criteria. Stakeholders must monitor evolving reimbursement codes for bariatric equipment across Medicare and private insurers, as coverage determinations directly shape end-user affordability and replacement cycles.
Market Dynamics
ISO 13485 certification requirements are filtering supplier bases in bariatric bed manufacturing, forcing quality management system investments that reshape competitive access across acute care and long-term care procurement channels.
Growth Catalysts
- EU Medical Device Regulation:CE marking mandates for clinical evidence and post-market surveillance are elevating compliant manufacturers above uncertified competitors in European hospital procurement.
- Long-term care infrastructure:Germany's residential care expansion is accelerating specialized bed procurement as aging demographics and obesity prevalence converge in institutional settings.
- Fully electric positioning systems:Automation of patient handling is pulling capital allocation away from manual and semi-electric alternatives in staff-constrained facilities.
Market Restraints
- Steel frame input costs:Reinforced chassis manufacturing faces commodity price volatility that compresses margin pools for mid-tier suppliers lacking captive metalworking capacity.
- FDA 510(k) timelines:Premarkot notification requirements for powered beds extend product development cycles and delay revenue recognition for novel feature introductions.
- Specialized maintenance networks:Technical service scarcity outside major metropolitan clusters limits addressable market expansion into rural and secondary hospital systems.
Strategic Opportunities
- Home care transition:Discharge pressure from acute facilities is opening rental and purchase demand for bariatric-capable home medical equipment in the United States.
- The Joint Commission accreditation:Safe patient handling protocol embedding in facility certification criteria creates procurement pull for ergonomic bed platforms in US hospital systems.
- Weight capacity segmentation:600-pound to 1000-pound tier differentiation is enabling premium positioning above standard 450-pound hospital bed alternatives.
Industry Challenges
- Biomedical technician training gaps:Specialized repair competencies for integrated electronics and hydraulic systems lag equipment complexity in distributed service networks.
- Legacy EMR integration:Bed data connectivity requirements strain IT departments attempting to unify disparate patient monitoring architectures across multi-vendor fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bariatric Beds Market |
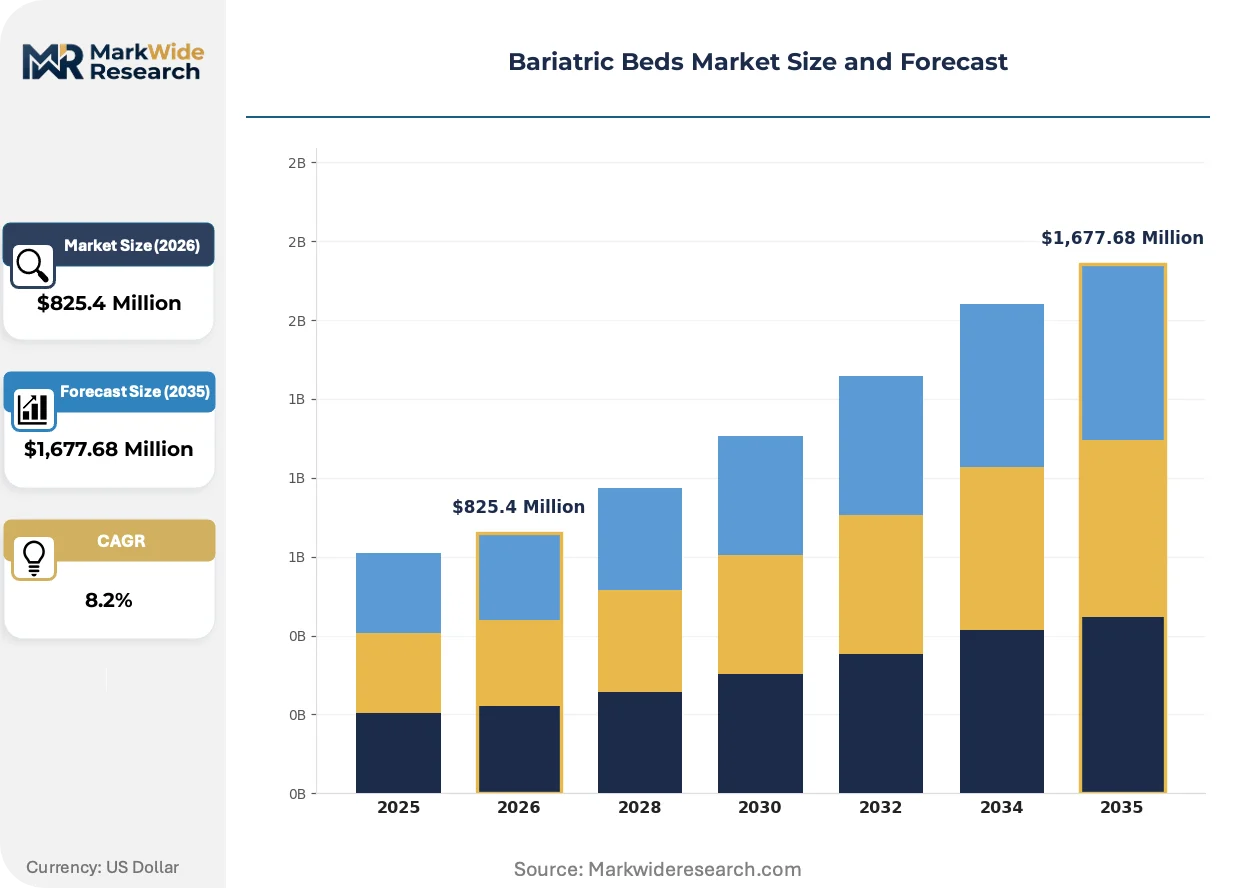
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,677.68 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bariatric Beds, Semi-Electric Beds, Fully Electric Beds, Manual Hydraulic Beds Application: Hospital Wards, Rehabilitation Facilities, Long-Term Care Homes, Home Care Settings End User: Healthcare Centers, Assisted Living Facilities, Nursing Homes, Specialty Clinics Distribution Channel: Direct Sales, Medical Equipment Distributors, Online Retail, Resellers |
| Companies Covered | Medline Industries, Drive DeVilbiss Healthcare, Hillrom, GF Health Products, Joerns Healthcare, Stryker, Arjo, Span America, Invacare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bariatric Beds Market Strategic Shifts & Innovations
Smart surface technologies and predictive maintenance architectures are redefining how bariatric beds interface with broader patient care ecosystems, shifting value capture from hardware sales toward integrated service models.
Sensor-embedded mattresses with pressure mapping and microclimate control are fragmenting the traditional bed-plus-mattress procurement bundle. Acute care hospitals in the United States are piloting these systems to reduce pressure injury incidence and associated litigation exposure. The technology is fragmenting vendor relationships as mattress specialists displace integrated bed manufacturers in purchasing decisions.
The EU Medical Device Regulation's post-market surveillance requirements are extending clinical evidence obligations across the product lifecycle. Manufacturers must now maintain active safety monitoring systems that feed into periodic safety update reports. German and French hospital procurement committees are prioritizing suppliers with established vigilance infrastructure over newer market entrants.
Acute care facilities are consolidating vendor relationships through single-source contracting for bariatric bed fleets. Group purchasing organizations are aggregating demand across hospital networks to extract volume-based pricing and standardize maintenance protocols. This concentration is most visible in the United States, where IDN consolidation has reduced the number of independent purchasing decision points by half over the past decade.
Bariatric Beds Market Segmentation
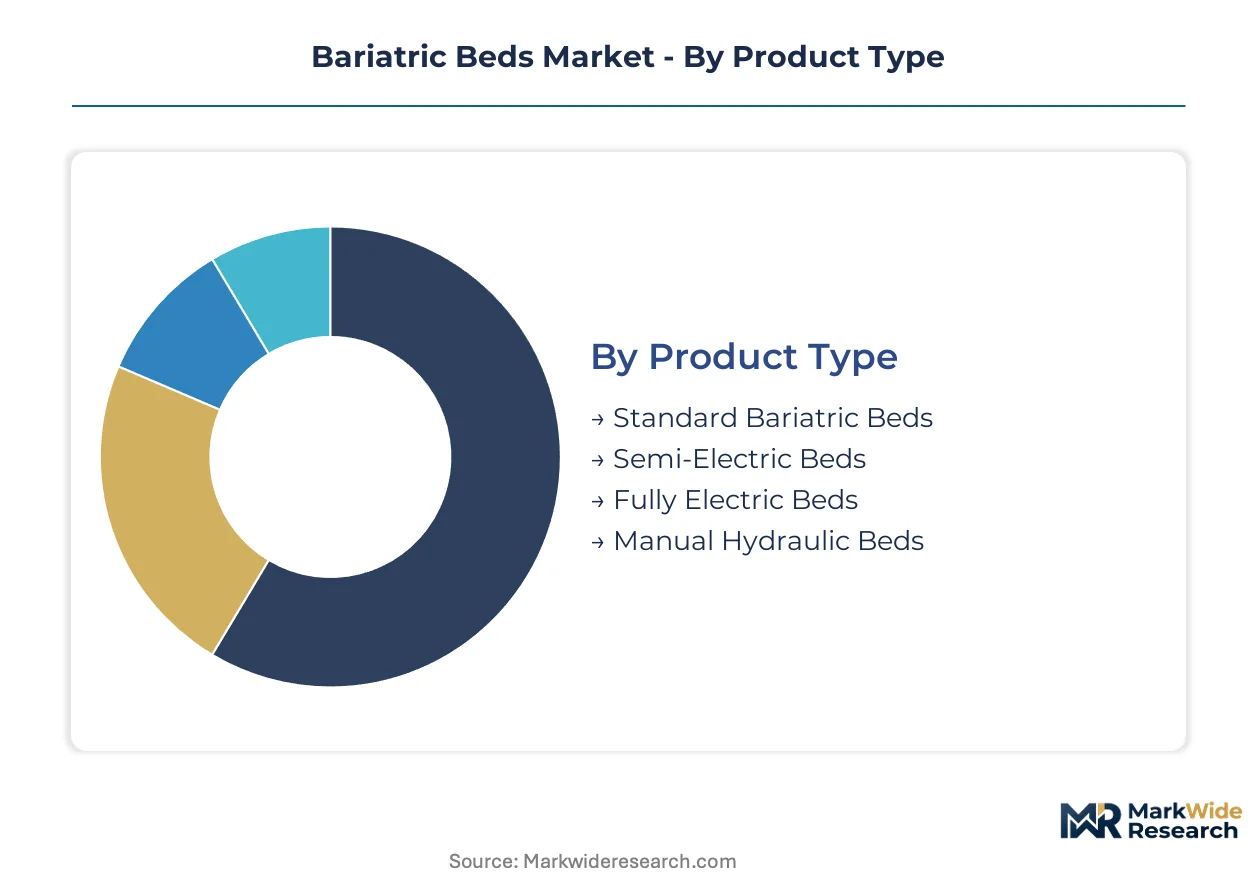
Bariatric bed purchasing decisions fragment across clinical setting, patient acuity, and procurement channel. Each dimension carries distinct technical specifications and margin structures that reshape vendor competitive positioning.
Product Type:
Manual and semi-electric configurations face acute substitution pressure from fully electric platforms as labor costs and injury liability reshape facility capital planning.
- Fully Electric Beds:Motorized positioning systems with programmable height, Trendelenburg, and cardiac chair functions eliminate manual patient handling. Hospital wards in the United States concentrate procurement here as safe patient handling mandates harden. Staff ergonomics and reduced workers compensation claims justify capital premiums over semi-electric alternatives.
- Semi-Electric Beds:Electric height adjustment paired with manual head and foot section positioning occupies a narrowing mid-market niche. Long-term care homes in Germany deploy these where resident mobility permits limited automation and budget constraints bite harder than in acute settings.
- Standard Bariatric Beds:Reinforced frames with expanded width but basic positioning capabilities serve price-sensitive institutional buyers.
- Manual Hydraulic Beds:Hand-crank or foot-pump mechanisms persist in resource-constrained environments and backup fleet roles.
Fully electric beds retain volume leadership in developed markets; semi-electric configurations hold the steepest contraction curve as electrification accelerates.
Application:
Cost tier stratification separates acute reimbursement environments from residential care budgets, with home care emerging as a distinct margin pool.
- Long-Term Care Homes:Residential facilities with 24-hour skilled nursing oversight require beds balancing durability with aesthetic integration. Germany's residential care infrastructure expansion concentrates demand here as aging demographics and obesity prevalence converge. Reimbursement codes for bariatric equipment directly shape replacement cycles and feature prioritization.
- Hospital Wards:Acute care settings demand rapid repositioning, integrated scale systems, and fall prevention alarms. Medical-surgical and bariatric specialty units in the United States drive specification intensity as The Joint Commission accreditation standards embed safe patient handling into facility certification criteria.
- Rehabilitation Facilities:Transitional care environments prioritize early mobilization support and therapy integration.
- Home Care Settings:Discharge pressure from acute facilities opens rental and purchase demand for bariatric-capable medical equipment.
Hospital wards dominate revenue concentration; long-term care homes are expanding most quickly as residential infrastructure scales.
End User:
Customer type determines service intensity expectations, with integrated health systems extracting standardized fleet terms versus fragmented independent facilities.
- Nursing Homes:Skilled nursing facilities with Medicare and Medicaid reimbursement exposure prioritize beds with pressure redistribution surfaces and fall risk mitigation. Group purchasing organization aggregation across multi-facility operators standardizes procurement specifications and maintenance protocols in the United States.
- Healthcare Centers:Hospital-based outpatient and inpatient units require EMR connectivity and centralized fleet management capabilities.
- Assisted Living Facilities:Residential care with limited medical oversight seeks lower-acuity beds with lifestyle-oriented design.
- Specialty Clinics:Bariatric surgery and weight management centers need pre- and post-operative positioning support.
Nursing homes anchor procurement volume; healthcare centers capture the steepest feature escalation curve as digital integration hardens.
Distribution Channel:
Supply concentration in direct sales forces distributor and digital channels into specialized or geographic niche roles.
- Direct Sales:Manufacturer field teams control institutional purchasing relationships through long-term service contracts and fleet standardization. Hillrom and Stryker deploy dedicated account management to IDN consolidated decision points, extracting multi-year agreements with preventive maintenance bundles.
- Medical Equipment Distributors:Regional and national distributors serve independent facilities and secondary markets outside major metropolitan clusters where manufacturer direct coverage thins.
- Online Retail:E-commerce platforms capture home care and small facility demand with transparent pricing and rapid fulfillment.
- Resellers:Refurbished and rental equipment brokers address budget-constrained buyers and temporary capacity needs.
Direct sales commands revenue leadership; online retail is gaining share fastest as home care purchasing decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European medical equipment distribution, while the I-95 corridor and Great Lakes rail networks underpin North American supply chain efficiency for heavy-duty hospital infrastructure.
United States
Hospital ward expansion and long-term care infrastructure drive procurement intensity across acute and residential settings. FDA 510(k) premarket notification requirements govern powered bed safety standards and extend product development timelines. The I-95 corridor from Boston to Washington concentrates IDN headquarters and group purchasing organization decision points.
Germany
Residential care infrastructure expansion and aging demographics converge to accelerate specialized bed procurement in institutional settings. EU Medical Device Regulation mandates clinical evidence and post-market surveillance for CE-marked products. The Rhine-Ruhr metropolitan region hosts dense clusters of medical device distributors serving Central European hospital systems.
United Kingdom
NHS procurement consolidation and obesity-related admission growth reshape capital allocation toward bariatric-capable equipment. MHRA regulations align with EU MDR transition timelines for medical device market access. The Greater Manchester and West Midlands health innovation clusters pilot integrated bed fleet management systems.
Japan
Super-aging demographics and rising obesity prevalence expand demand for reinforced sleep surfaces in geriatric care facilities. PMDA medical device approval processes emphasize clinical evidence requirements for powered positioning systems. The Kanto region surrounding Tokyo concentrates university hospital procurement authority and medical equipment distribution networks.
Australia
Rural health infrastructure gaps and metropolitan hospital consolidation create divergent procurement patterns across states. TGA medical device regulations require conformity assessment for powered beds entering the national market. The Sydney-Melbourne corridor anchors private hospital chain purchasing decisions and specialist equipment import channels.
Bariatric Beds Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and service bundling dimensions, producing a tiered structure where scale advantages concentrate in acute care procurement channels. Three archetypes dominate: integrated hospital bed platforms with captive manufacturing, dedicated medical equipment distributors with regional service networks, and mattress specialists fragmenting the traditional bed-plus-surface bundle. M&A activity targets service network density, while portfolio diversification into predictive maintenance architectures reshapes recurring revenue streams.
Among US-based platform manufacturers, Stryker and Hillrom exemplify the integrated archetype through direct sales force deployment and multi-year fleet standardization contracts. Joerns Healthcare occupies a position within the private specialist tier, representing service-intensive competitive positioning outside major metropolitan clusters. These anchors illustrate how quality management certification and preventive maintenance bundling filter competitive access across institutional procurement channels.
| Leading Market Players |
|---|
| Medline Industries |
| Drive DeVilbiss Healthcare |
| Hillrom |
| GF Health Products |
| Joerns Healthcare |
| Stryker |
| Arjo |
| Span America |
| Invacare |
| Others |
Cost & Logistics Intelligence
Electric actuator substitution for hydraulic positioning systems is redrawing manufacturing geography toward East Asian electronics clusters while compressing margin structures for European metalworking-dependent suppliers. This input shift simultaneously elevates procurement leverage for buyers consolidating fleet orders and squeezes mid-tier competitors lacking captive motor-drive production.
Pricing Analysis
Volume-discount tiering structures dominate institutional procurement, with IDN consolidated purchasing extracting 15-25 point spreads between single-unit and fleet-scale contracts. Pricing stratifies across ISO 13485-certified premium manufacturers, FDA-cleared mid-tier suppliers, and uncertified economy alternatives. Cost compression in the manual and semi-electric tiers is intensifying because acute care automation mandates displace lower-specification beds. Nursing home chains exhibit highest price sensitivity due to Medicaid reimbursement constraints; hospital systems show lowest sensitivity where safe patient handling liability costs dominate capital planning.
Supply Chain Analysis
Just-in-time component sourcing prevails for electronic control systems, while steel frame manufacturers maintain strategic raw material stockpiles against commodity volatility. Supply concentrates in Germany for precision mechanical assemblies, China for electric motor and control module production, and the United States for final assembly serving North American demand. Reinforced steel chassis, linear actuators, and sensor-embedded mattress cores constitute critical input dependencies. Single-source vulnerability in semiconductor-dependent motor controllers represents the dominant structural risk. Distribution runs through manufacturer direct sales teams controlling IDN relationships, with regional distributors serving fragmented independent facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biomedical technician training infrastructure represents the scarcest capability layer, constraining service network expansion and filtering competitive access for aftermarket-dependent revenue models.
For Market Incumbents: Shield premium positioning by deepening preventive maintenance bundling and captive technician certification programs against distributor encroachment. Backward integration into smart surface sensor production secures margin pools as mattress specialists fragment traditional bed-plus-surface procurement bundles. For New Entrants and Emerging Players: Lead with home care rental and purchase channels where discharge pressure from acute facilities creates white-space demand outside established hospital GPO relationships. Target rural and secondary hospital systems where manufacturer direct coverage thins and service scarcity limits incumbent penetration. Deploy online retail transparency and rapid fulfillment as the primary go-to-market angle against field-sales-dependent legacy vendors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors possessing dense service technician networks but lacking ISO 13485 certification for manufacturing expansion. Long-term viability hinges on recurring revenue attachment rates for maintenance and digital fleet management subscriptions. Watch Medicare reimbursement code expansions for bariatric home equipment as the inflection signal for rental model profitability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Premarket notification timelines govern powered bed launch schedules and revenue recognition timing. |
| CE Marking Under EU MDR | Clinical evidence requirements elevate compliant manufacturers above uncertified competitors in European procurement. |
| Hospital System Partnership | IDN consolidated purchasing extracts multi-year fleet standardization agreements with preventive maintenance bundles. |
| Software Companion Development | EMR connectivity and predictive maintenance architectures shift value capture toward integrated service models. |
| Reimbursement Strategy | Medicare and private insurer coverage determinations directly shape end-user affordability and replacement cycles. |
Research Approach
A standing panel of hospital purchasing committee directors, biomedical equipment managers, GPO contracts specialists, and long-term care facility administrators provided ongoing calibration against shifting procurement specifications. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through FDA 510(k) clearance databases, EU MDR vigilance reports, hospital procurement contract filings, and CMS Medicare durable medical equipment reimbursement schedules. Bottom-up unit demand modeling triangulated against top-down healthcare capital expenditure benchmarks.
Consistency checks validated volume and value outputs against independent healthcare infrastructure investment trackers and medical device trade association shipment data across the projection horizon. Segmentation dimensions modeled include product type automation tier, application setting acuity level, end-user institutional scale, and distribution channel concentration. CAGRs derived from weighted average of historical replacement cycle analysis and forward-looking reimbursement policy trajectory. Industry-specific forecast inputs incorporated obesity prevalence demographic projections and skilled nursing facility bed capacity expansion plans.
Forecasts assume regulatory continuity in FDA premarket notification requirements and EU MDR post-market surveillance obligations; material policy shifts would require re-modeling of product development timeline assumptions and competitive access filters. Revision becomes warranted when steel commodity price volatility or semiconductor supply disruptions cross thresholds that alter manufacturer margin structures and procurement prioritization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Contact Thermometer Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
France Drug Delivery Devices Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Male Artificial Urinary Sphincter Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Foot Suction Unit Market
Medical Devices
Global Cast Saw Devices Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Gastroretentive Drug Delivery Systems Market
Medical Devices
Mexico Contraceptive Devices Market
Medical Devices
Defibrillator Pads Market
Medical Devices
Coronary Angiography Devices Market
Medical Devices
Nasal Atomizer Devices Market