
 Supraglottic Airway Devices Market | 2026-2036
Supraglottic Airway Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Supraglottic Airway Devices Market Intelligence
The divergence in R&D investment for integrated video technologies versus mass production scale is redrawing competitive boundaries. Medtronic leverages its vast global distribution network to reach diverse end-user segments from hospitals to ambulance services. In contrast, Ambu A/S specializes in the single-use device category, emphasizing clinical benefits and infection prevention. Teleflex Incorporated sustains its market position through a diversified portfolio covering multiple anesthesia and respiratory care applications.
Supraglottic airway devices are medical instruments designed to secure an open airway for ventilation without passing through the vocal cords. These devices, typically made from medical-grade silicone or PVC, form a low-pressure seal around the laryngeal inlet for use in anesthesia or emergency medicine. Laryngeal Mask Airway (LMA) products continue to represent the largest product category by volume. The market's primary growth comes from the disposable devices segment, driven by hospital protocols aimed at minimizing cross-contamination risks.
Market access hinges on compliance with stringent regulatory frameworks. Manufacturers must secure FDA 510(k) clearance in the United States and CE marking under the EU's Medical Device Regulation (MDR) for European market entry. These regulations dictate material biocompatibility and clinical performance standards. Consequently, providers must continually evaluate the total cost of ownership, balancing the logistical burden of sterilizable devices against the material waste of single-use products.
Market Dynamics
The central structural force shaping the market is the institutional mandate for single-use devices to mitigate healthcare-associated infections. This shift, driven by hospital infection control committees and risk management protocols, fundamentally alters procurement priorities and the total cost of ownership calculation for end-users.
Growth Catalysts
- Prehospital Care Expansion:The integration of advanced airway management into paramedic and emergency medical technician protocols, particularly in the United States and Germany, creates sustained volume demand for easy-to-insert supraglottic devices.
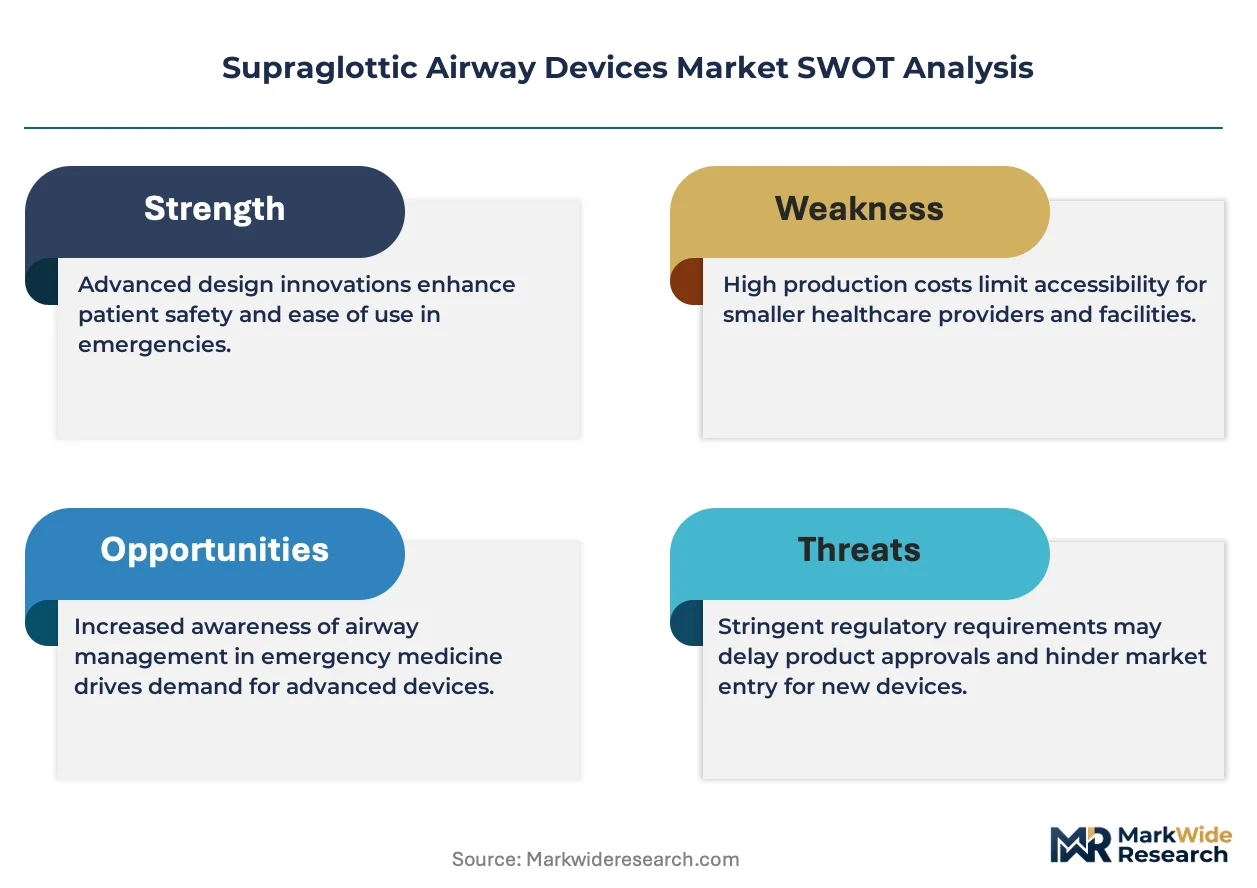
- Stringent Regulatory Standards:The EU's Medical Device Regulation (MDR) elevates clinical evidence requirements, favoring manufacturers with robust quality systems and well-documented device performance, thereby creating a barrier to lower-quality entrants.
- Material Science Advances:Development of softer, more pliable medical-grade silicones and thermoplastic elastomers improves the anatomical fit and seal effectiveness of cuffs, reducing mucosal trauma and enhancing patient safety.
Market Restraints
- Total Cost of Ownership Debate:The higher per-procedure material cost and environmental impact of disposable devices present a significant hurdle for budget-constrained healthcare facilities compared to the capital cost of sterilizable alternatives.
- Regulatory Clearance Delays:The extensive validation and documentation required for FDA 510(k) clearance or CE marking can significantly delay the market entry of innovative device designs, slowing the pace of technological adoption.
- Clinical Substitution Risk:In certain controlled anesthetic settings, the proficiency of anesthesiologists with traditional endotracheal intubation continues to limit the routine use of supraglottic airways, especially in complex surgical cases.
Strategic Opportunities
- Emerging Market Penetration:Expanding emergency medical services infrastructure in countries across Latin America and Southeast Asia represents a significant opportunity for introducing basic and advanced supraglottic airway devices.
- Integrated Digital Technologies:The convergence of supraglottic airway devices with micro-camera and sensor technologies offers a pathway to create smart devices that confirm placement and monitor ventilation in real-time.
- Procedural Sedation Applications:Use in outpatient settings, such as endoscopy suites and dental surgery centers, for conscious sedation procedures provides a new growth vector beyond traditional anesthesia and emergency medicine.
Industry Challenges
- Clinical Training and Competency:Ensuring consistent and correct placement by a wide range of healthcare providers, from anesthesiologists to paramedics, requires standardized training programs to minimize complications like aspiration or ineffective ventilation.
- Medical Waste Management:The industry-wide shift toward single-use products generates substantial plastic waste, creating logistical and environmental challenges for hospitals that must manage its disposal.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supraglottic Airway Devices Market |
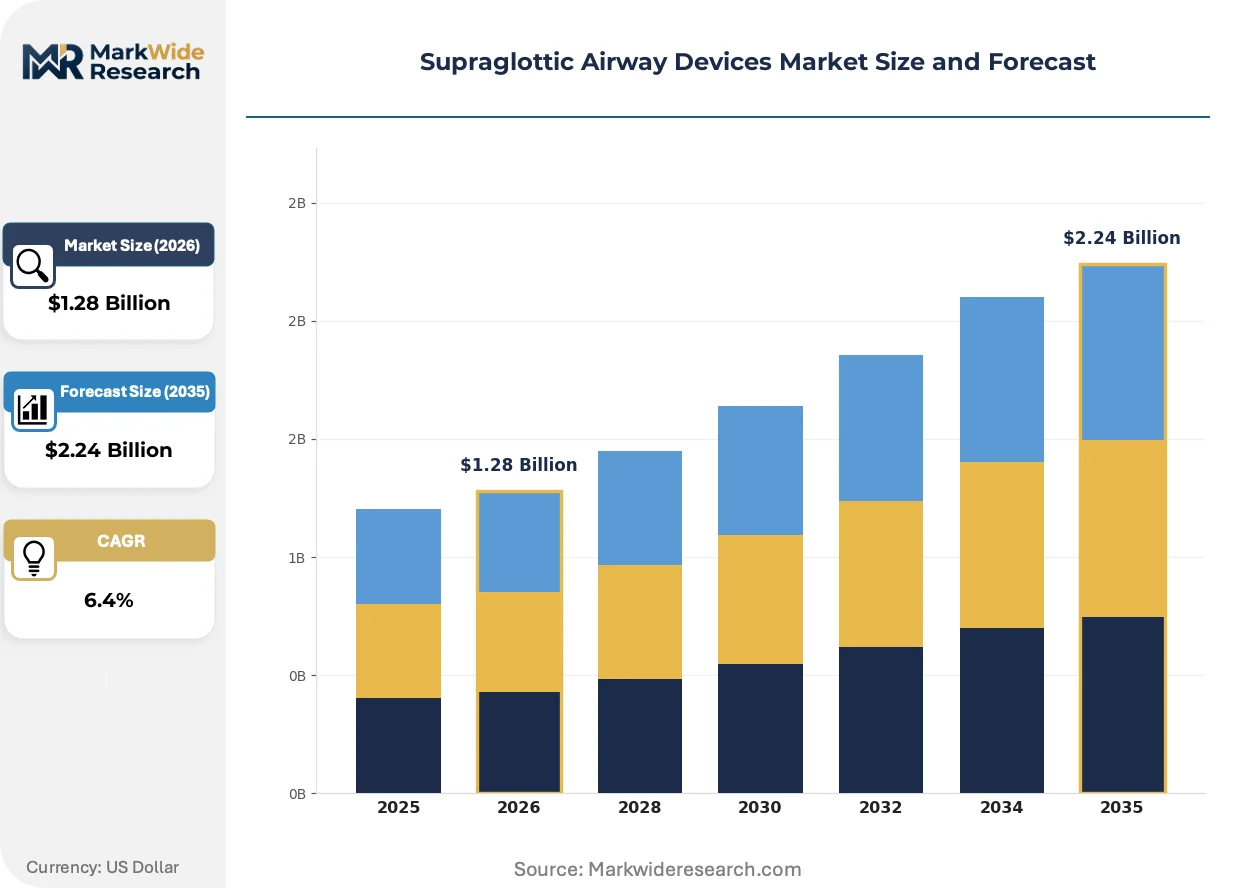
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laryngeal Mask Airway, Oropharyngeal Airway, Laryngeal Tube, Pharyngeal Airway, Esophageal Obturator, Retroglottic Airway Application: Emergency Medicine, Anesthesia Management, Critical Care, Prehospital Care, Dental Procedures, Endoscopy End User: Ambulance Services, Anesthesiology Clinics, Critical Care Units, Dental Offices, Gastroenterology Centers, Surgical Centers Deployment Mode: Reusable Devices, Disposable Devices, Single-Use, Multi-Use, Sterilizable, Portable Units |
| Companies Covered | Smiths Medical, Intersurgical Ltd, Medtronic, Flexicare Medical Limited, Mercury Medical, Teleflex Incorporated, Karl Storz SE & Co. KG, Verathon Inc., Ambu A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supraglottic Airway Devices Market Strategic Shifts & Innovations
Technological evolution is focused on enhancing patient safety features and simplifying insertion, directly responding to demands from emergency and non-specialist clinical settings. This drive for clinical efficacy and ease of use is defining the next generation of supraglottic airway devices.
Second-generation devices incorporate specific design enhancements like a dedicated gastric access channel for suctioning stomach contents. Anesthesiologists and emergency physicians are rapidly adopting these models to reduce the risk of pulmonary aspiration, a critical complication. This evolution is supplanting older, first-generation laryngeal mask designs that lack these integral safety features and offer a lower level of airway protection.
The European Union's Medical Device Regulation (MDR) has intensified scrutiny on clinical performance and post-market surveillance. This regulation forces manufacturers to generate more extensive clinical data to support safety and efficacy claims for all devices sold in the EU. Disposable device manufacturers are particularly impacted, now needing to provide robust evidence for each product variant to maintain CE marking and market access.
A distinct behavioral change is evident in how hospital systems approach device selection, moving from individual clinician preference to system-wide standardization. This consolidation of purchasing decisions disrupts the sales model for specialized vendors and favors suppliers offering a comprehensive portfolio under a master agreement. This trend is highly visible in large integrated delivery networks across the United States and public hospital trusts in the United Kingdom.
Supraglottic Airway Devices Market Segmentation
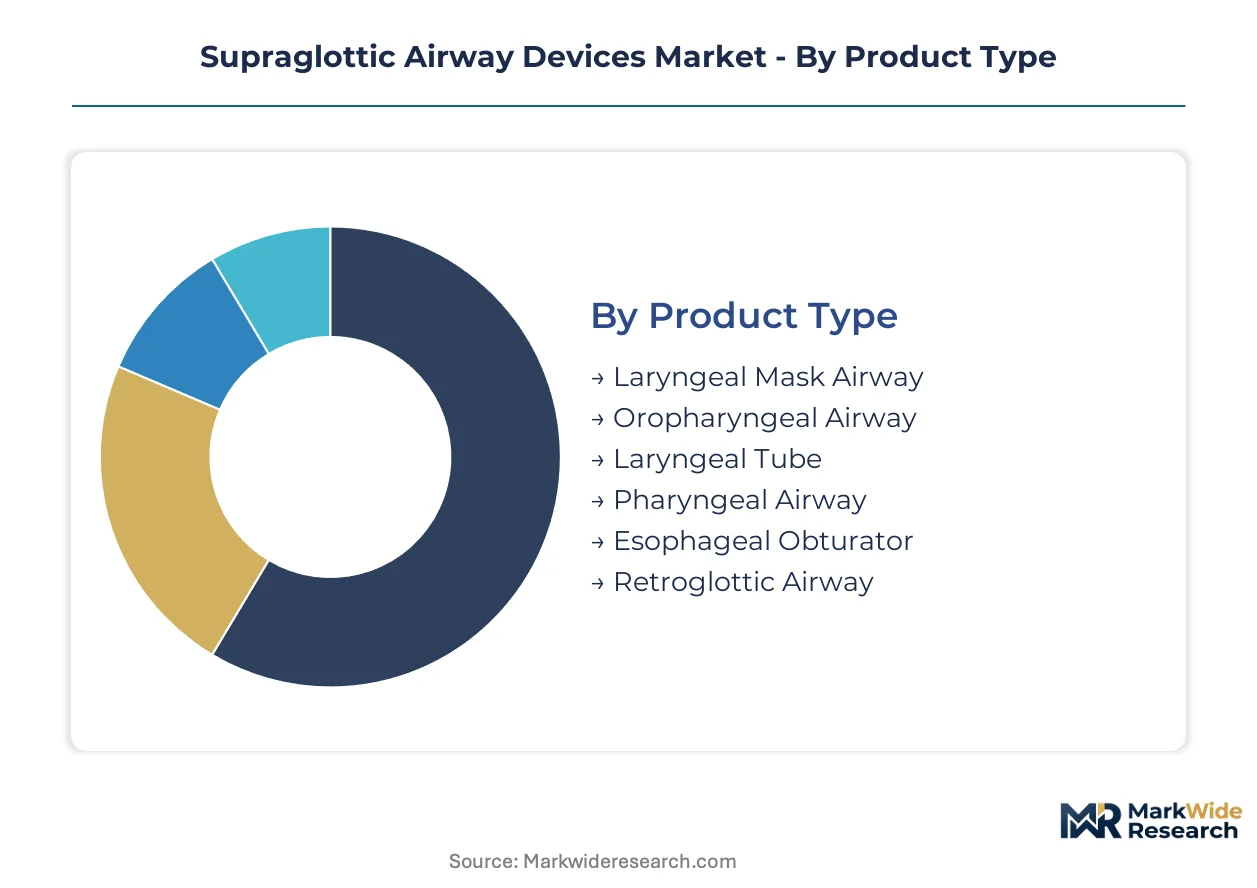
The Supraglottic Airway Devices Market segments across various dimensions, reflecting diverse clinical needs and operational preferences within healthcare. Understanding these segments is crucial for manufacturers to align product development with specific demands and for providers to optimize procurement strategies.
Product Type:
The product type segment demonstrates varied adoption patterns across different healthcare systems, with some designs showing stronger uptake in specific national emergency medical services while others are more prevalent in hospital settings.
- Laryngeal Mask Airway:These devices, typically made from medical-grade silicone, form a low-pressure seal around the laryngeal inlet for ventilation. Demand concentrates in prehospital care settings in countries like the United States, where rapid and less invasive airway management is critical.
- Laryngeal Tube:Featuring two cuffs that inflate simultaneously, these devices seal both the esophagus and pharynx for effective ventilation. Their use is growing in emergency medicine across Europe due to ease of insertion and high success rates.
- Oropharyngeal Airway:Simple plastic devices maintain airway patency by preventing tongue obstruction, widely used in basic life support.
- Pharyngeal Airway:Similar to oropharyngeal airways, these devices keep the upper airway open during patient transport or short procedures.
- Esophageal Obturator:These devices block the esophagus to prevent gastric inflation during ventilation attempts, historically used in prehospital care.
- Retroglottic Airway:Advanced devices secure the airway by positioning a cuff behind the larynx, offering an alternative to traditional laryngeal masks.
Laryngeal Mask Airway holds the largest share; momentum sits with Laryngeal Tube.
Application:
The application segments highlight how varying clinical requirements drive device specifications and procurement decisions, with certain settings prioritizing cost-effectiveness while others demand advanced features for patient safety.
- Emergency Medicine:This application requires devices for rapid, reliable airway management in unpredictable environments, often by non-specialist personnel. Demand is high in ambulance services in the United States, where ease of insertion is paramount.
- Prehospital Care:Devices in this segment must withstand challenging conditions and provide secure ventilation outside of hospital settings. The market for these devices is expanding in Germany, driven by national protocols for advanced life support.
- Anesthesia Management:Anesthesiologists use these devices for maintaining a patent airway during surgical procedures, balancing patient comfort with effective ventilation.
- Critical Care:In intensive care units, supraglottic devices assist in ventilation and oxygenation for patients requiring temporary airway support.
- Dental Procedures:Short-term airway support is provided by these devices during conscious sedation in dental offices, ensuring patient safety.
- Endoscopy:Devices facilitate airway access and protection during endoscopic procedures, particularly those involving the upper gastrointestinal tract.
The Emergency Medicine application consistently generates significant volume, while Prehospital Care demonstrates rapid expansion due to evolving paramedic protocols.
End User:
End-user segments reveal distinct purchasing behaviors and volume requirements, with large institutional buyers seeking comprehensive portfolios and smaller clinics prioritizing specialized, cost-effective solutions.
- Ambulance Services:These services require durable, easy-to-use devices for rapid deployment in prehospital emergency situations. Procurement is shifting towards single-use disposable models to reduce cross-contamination risks.
- Surgical Centers:Devices are used here for anesthesia in elective procedures, emphasizing patient safety and efficient workflow. Demand focuses on second-generation devices with gastric access channels to minimize aspiration risk.
- Anesthesiology Clinics:These clinics utilize supraglottic airways for outpatient procedures, focusing on devices offering quick recovery and minimal post-operative complications.
- Critical Care Units:ICU settings use these devices for temporary airway management in intubated or critically ill patients.
- Dental Offices:For conscious sedation during dental work, these offices select devices that are minimally invasive and ensure patient comfort.
- Gastroenterology Centers:These centers employ supraglottic airways to manage patient airways during endoscopic procedures, ensuring ventilation and aspiration protection.
Ambulance Services are a primary volume driver, with Surgical Centers representing a significant segment for advanced device adoption.
Deployment Mode:
The deployment mode segment reflects a critical industry shift influenced by infection control mandates and environmental considerations, driving innovation in material science and waste management solutions.
- Disposable Devices:These single-use products are designed for one-time patient contact, then discarded, significantly reducing healthcare-associated infection risks. Their adoption is accelerating across hospitals in the United Kingdom, driven by stringent infection control.
- Single-Use:This sub-category of disposable devices emphasizes complete disposability after a single patient encounter, aligning with strict hospital hygiene policies. The market for these products is expanding most quickly in integrated delivery networks across the United States.
- Reusable Devices:Designed for multiple uses after sterilization, these devices offer lower per-procedure costs but require robust reprocessing infrastructure.
- Multi-Use:Similar to reusable, these devices can be employed for several patients after appropriate cleaning and sterilization.
- Sterilizable:This refers to devices that can withstand high-temperature or chemical sterilization processes, allowing for repeated clinical application.
- Portable Units:These are often integrated systems or compact devices designed for use in emergency vehicles or remote clinical environments.
The shift towards Disposable Devices and Single-Use products is fundamentally altering procurement patterns across the market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power for supraglottic airway devices diverges significantly between the United States and European markets. US procurement often prioritizes rapid deployment and single-use convenience, while European countries like Germany weigh total cost of ownership more heavily. Stringent EU MDR compliance also impacts pricing strategies for manufacturers.
United States
United States demand for supraglottic airways stems from expanding prehospital care protocols within ambulance services. FDA 510(k) clearance mandates rigorous safety and efficacy standards for market entry. Integrated delivery networks across major US metros drive system-wide standardization for procurement.
Germany
German emergency medicine consistently generates significant volume for easy-to-insert supraglottic devices. CE marking under the EU's Medical Device Regulation (MDR) requires extensive clinical evidence for market access. Ambulance services throughout Germany are expanding advanced life support protocols.
United Kingdom
United Kingdom hospitals adopt disposable supraglottic devices rapidly, driven by stringent infection control mandates. National hospital protocols aim to minimize cross-contamination risks through single-use products. Public hospital trusts across the UK consolidate purchasing decisions for comprehensive portfolios.
Brazil
Brazil's expanding emergency medical services infrastructure creates significant opportunities for basic and advanced supraglottic airway devices. ANVISA regulations govern device registration and material biocompatibility for market entry. Major cities like São Paulo and Rio de Janeiro are integrating these devices into prehospital care.
Japan
Japanese healthcare emphasizes patient safety and advanced features in supraglottic airway device selection. The PMDA ensures rigorous clinical performance and post-market surveillance for medical devices. Leading medical device manufacturers in Tokyo and Osaka focus on material science advances.
Supraglottic Airway Devices Market Key Industry Players
Concentration sits with established medical device conglomerates offering broad portfolios across multiple care settings. The market exhibits a tiered structure, encompassing global generalists, specialized innovators, and regional players. Archetypes include diversified healthcare giants like Medtronic, single-use device specialists such as Ambu A/S, and niche technology providers. Portfolio diversification, strategic partnerships, and targeted geographic expansion are dominant competitive moves.
Within the diversified healthcare giants tier, Medtronic and Teleflex Incorporated exemplify extensive global distribution networks and broad product portfolios. Medtronic leverages its vast reach across diverse end-user segments, from hospitals to ambulance services. Teleflex Incorporated sustains its market position through a diversified portfolio covering multiple anesthesia and respiratory care applications. Ambu A/S, a specialist in the single-use device category, emphasizes clinical benefits and infection prevention solutions.
| Leading Market Players |
|---|
| Smiths Medical |
| Intersurgical Ltd |
| Medtronic |
| Flexicare Medical Limited |
| Mercury Medical |
| Teleflex Incorporated |
| Karl Storz SE & Co. KG |
| Verathon Inc. |
| Ambu A/S |
| Others |
Cost & Logistics Intelligence
Hospitals typically maintain 30 days of inventory for essential supraglottic devices, a strategic choice influenced by supply chain resilience and pricing stability, particularly for high-volume disposable units. This inventory strategy balances immediate clinical needs with the cost efficiencies of bulk procurement. Pricing power often concentrates with manufacturers capable of navigating stringent regulatory frameworks and offering comprehensive product portfolios.
Pricing Analysis
Configured-to-order pricing for integrated video-enabled devices commands a premium over standard, high-volume disposable units. Price differentiation stems from certification levels, such as FDA 510(k) or CE marking, and the degree of material science innovation. Pricing pressure stems from the institutional mandate for single-use devices, driving volume but demanding cost-effectiveness. Ambulance services exhibit the highest price sensitivity for basic devices, while surgical centers prioritize advanced features over marginal cost savings.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume disposable devices, but specialized components for integrated video systems often require strategic stockpiling. Supply concentrates in manufacturing hubs across China and Malaysia for base components, with final assembly and advanced manufacturing occurring in Germany and the United States. Raw material dependencies include medical-grade silicone, PVC, and increasingly, micro-camera modules. Single-source vulnerability for specialized digital components represents a structural risk. Distribution runs through direct sales channels to large integrated delivery networks and regional distributors for prehospital care providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in an early-cycle expansion phase, driven by the rapid penetration of single-use devices into prehospital care settings.
For Market Incumbents: Shield existing market share by accelerating R&D into integrated video technologies. Consolidate purchasing agreements with large integrated delivery networks to counter clinical substitution risk from traditional intubation. Leverage extensive global distribution networks to maintain competitive advantage against emerging lower-cost entrants. Invest in advanced CE marking and FDA 510(k) certification processes.
For New Entrants and Emerging Players: The service-layer gap in comprehensive training and post-market support presents an entry point for new players. Target emerging markets across Latin America and Southeast Asia with cost-effective, easy-to-insert devices suitable for basic life support. Focus go-to-market strategies on demonstrating superior ease of use and reduced training requirements for non-specialist personnel. Procedural sedation applications in outpatient settings offer a penetrable segment.
For Investors and Strategic Acquirers: Long-term, this sits as a patient safety-driven medical technology play because of persistent clinical needs and evolving regulatory standards. Acquisition targets should include niche innovators with strong intellectual property in material science or digital integration. A signal to watch for inflection is the increased regulatory harmonization across major medical device markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Training Program Expansion | Ensures consistent placement by paramedics, reducing complications in emergency medicine. |
| Integrated Video Technology Development | Enhances patient safety by confirming device placement and monitoring ventilation in real-time. |
| EU MDR Compliance Investment | Secures market access and strengthens competitive position in European healthcare systems. |
| Emerging Market Distribution Partnerships | Expands reach into underserved regions like Latin America, increasing volume demand. |
| Material Science Innovation | Improves anatomical fit and reduces mucosal trauma, directly enhancing patient comfort and safety. |
Research Approach
The analysis maps supraglottic airway device sub-sectors, each validated through extensive interviews with clinicians and hospital procurement teams. Primary interviews with anesthesiologists, emergency physicians, hospital procurement managers, and paramedics informed market dynamics. Secondary validation drew from FDA 510(k) databases, EU MDR reports, clinical trial registries, and medical device manufacturer reports. Bottom-up and top-down triangulation ensured data integrity.
Outputs were validated for consistency against global medical device market benchmarks, ensuring robust projections across the analysis window. The analytical framework segmented the market by product type, application, end user, deployment mode, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and future demand projections. Key forecast inputs included procedure volumes and infection control mandates.
Forecasts assume regulatory continuity in FDA and EU MDR regimes; material policy shifts would require re-modeling. The analysis reflects assumptions regarding technological advancements and healthcare spending trends. Unforeseen technological breakthroughs or major shifts in global healthcare spending represent risk factors. Revision becomes warranted when infection control protocols or reimbursement structures cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Ultrasound Devices Market
Medical Devices
Clinical Rollators Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Asia Pacific Apheresis Market
Medical Devices
Modular Anatomic Reconstruction Market
Medical Devices
Global Pulse Oximetry Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Intrathecal Pumps Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Global Nerve Monitoring System Market
Medical Devices
Neurosurgical Products Market