
 Asia-Pacific Viscosupplementation Market | 2026-2036
Asia-Pacific Viscosupplementation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Viscosupplementation Market Outlook
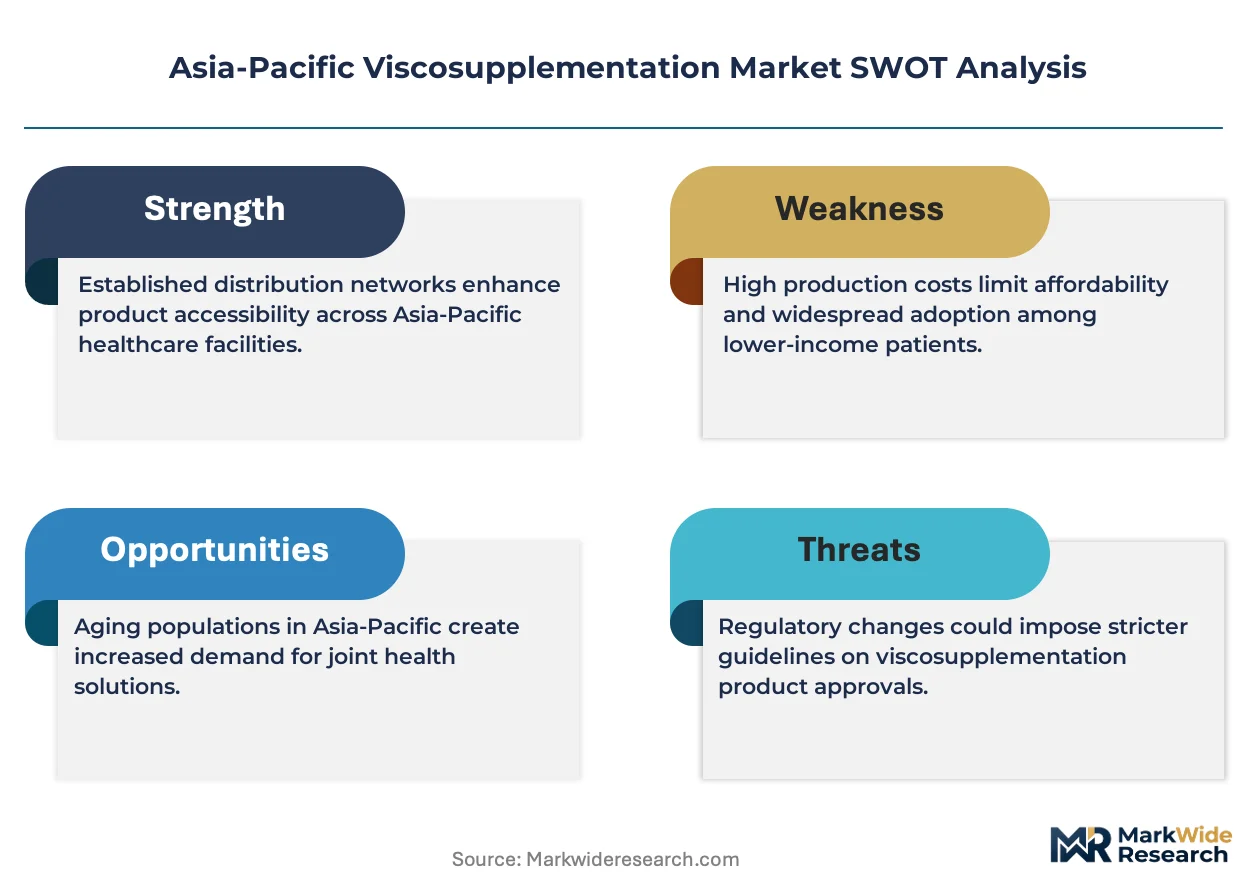
Multi-source procurement of hyaluronic acid raw material is repositioning supply security for injectable manufacturers across the Asia-Pacific region. Seikagaku Corporation leverages captive fermentation capacity in Japan to sustain quality control over sodium hyaluronate precursors. LG Chem Life Sciences anchors regional production scale through its biopolymer platform in South Korea.
Viscosupplementation denotes intra-articular injection of hyaluronic acid or derivatives to restore synovial fluid viscoelasticity in degenerated joints, with formulations typically ranging from 500 kDa to 6,000 kDa molecular weight depending on therapeutic indication. Cross-linked hyaluronate variants command premium positioning due to extended residence time in the joint cavity and reduced injection frequency. Orthopedic clinics represent the fastest-growing end-user channel as ambulatory procedures displace hospital-based administration across Australia and Japan.
Japan's PMDA, Australia's TGA, and South Korea's MFDS each enforce distinct purity and endotoxin thresholds for intra-articular devices, fragmenting registration pathways and elevating compliance costs for multinational suppliers. The divergence in clinical evidence requirements between these regulators shapes trial design priorities and timelines for product sponsors. Stakeholders must monitor reimbursement list revisions and biosimilar entry protocols as the primary determinants of portfolio profitability across the region.
Market Dynamics
Cross-linked hyaluronate formulations are compressing injection frequency requirements and forcing orthopedic clinics across Japan, South Korea, and Australia to recalibrate their procedure economics and inventory planning around extended-residence products.
Growth Catalysts
- PMDA Purity Standards:Japan's tightened endotoxin thresholds for intra-articular devices are filtering out marginal suppliers and concentrating procurement among qualified manufacturers with captive fermentation capacity.
- Ambulatory Procedure Migration:Orthopedic clinics in Australia and Japan are displacing hospital-based administration, expanding addressable patient volumes through same-day injection protocols.
- Hyaluronic Acid Molecular Weight Engineering:Advances in 500-6,000 kDa formulation tuning are matching viscoelastic profiles to specific joint degeneration stages, improving clinical outcomes and repeat procedure rates.
Market Restraints
- Raw Material Concentration:Sodium hyaluronate precursor supply clusters in Japanese and South Korean fermentation facilities, exposing manufacturers to single-source geographic risk.
- Regulatory Fragmentation:Divergent MFDS, PMDA, and TGA clinical evidence requirements force sponsors to run parallel trial programs, extending registration timelines and inflating compliance expenditure.
- Biosimilar Entry Protocols:Australia's TGA reference pricing mechanisms for follow-on hyaluronate products are compressing margin structures for originator formulations ahead of patent cliffs.
Strategic Opportunities
- Southeast Asia Underpenetration:Thailand, Malaysia, and Indonesia present white-space demand as private hospital chains expand joint care centers without established viscosupplementation protocols.
- Single-Injection Cross-Linked Formats:Extended-residence variants reduce patient compliance burdens and clinic chair time, commanding premium positioning against multi-injection standard hyaluronate.
- Reimbursement List Expansion:South Korea's National Health Insurance Service is reviewing inclusion criteria for hip and shoulder indications beyond knee osteoarthritis, opening new anatomical segments.
Industry Challenges
- Fermentation Scale-Up Talent Scarcity:Biopolymer production engineering expertise concentrates in legacy Japanese and South Korean facilities, constraining new entrant manufacturing capabilities.
- Multi-Regulatory Synchronization:Sponsors must align PMDA, TGA, and MFDS submission dossiers with incompatible stability data requirements and inspection protocols.
- Cold Chain Integrity:Temperature-sensitive hyaluronate formulations require validated distribution infrastructure across Australia's remote territories and Japan's island prefectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Viscosupplementation Market |
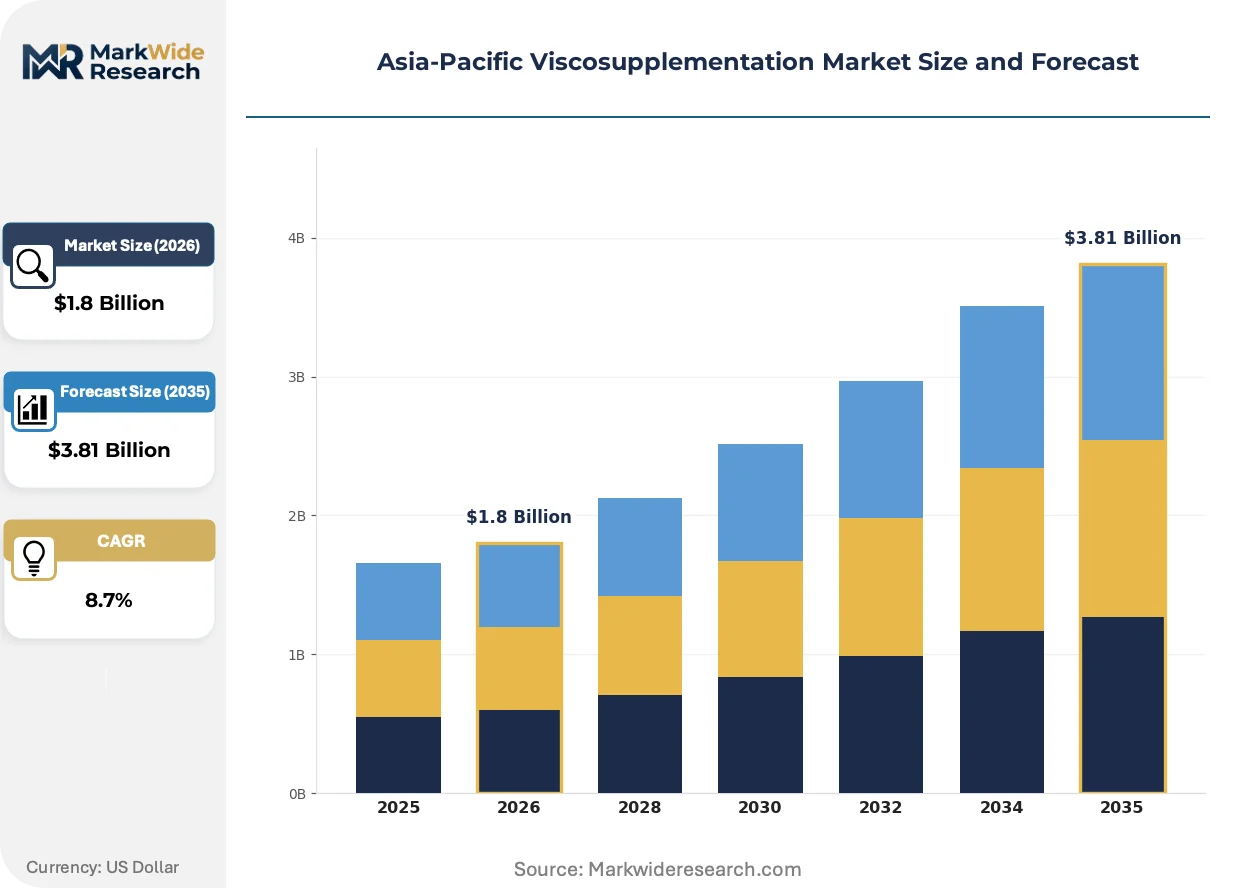
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Hyaluronate, High Molecular Weight Hyaluronate, Cross-Linked Hyaluronate, Others Application: Osteoarthritis, Sports Injuries, Post-Surgical Recovery, Chronic Joint Pain End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Pain Management Centers Distribution Channel: Pharmacies, Online Platforms, Direct Sales, Medical Supply Stores |
| Companies Covered | Zimmer Biomet Holdings, Fidia Farmaceutici S.p.A., Seikagaku Corporation, Ferring Pharmaceuticals, LG Chem Life Sciences, Chugai Pharmaceutical, Bioventus LLC, Anika Therapeutics Inc., Sanofi S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Viscosupplementation Market Strategic Shifts
Formulation science and point-of-care delivery models are restructuring competitive advantage in Asia-Pacific viscosupplementation, with molecular architecture and regulatory navigation displacing pure commercial scale as primary differentiators.
Cross-linked hyaluronate technology is decentralizing treatment logistics by extending intra-articular residence time from days to weeks. Orthopedic clinics in Melbourne, Sydney, and Tokyo are adopting single-injection protocols for moderate osteoarthritis cases, reducing patient visit burdens and clinic scheduling complexity. This formulation shift is decentralizing procedure volume from tertiary hospitals toward ambulatory specialist centers with lower fixed-cost structures.
Australia's TGA has tightened post-market surveillance requirements for intra-articular medical devices, mandating real-world outcome registries for hyaluronate products. Manufacturers now face expanded pharmacovigilance obligations and periodic safety reporting beyond initial registration. The policy is reshaping trial design priorities, with sponsors prioritizing Australian sites to generate locally compliant longitudinal data ahead of reimbursement negotiations.
Patient self-referral patterns are fragmenting traditional orthopedic gatekeeper channels across Japan's urban prefectures. Direct-to-clinic appointment platforms are displacing general practitioner-mediated pathways for knee pain assessment, compressing diagnostic delays but raising concerns about appropriateness of injection candidacy. Tokyo and Osaka metropolitan areas exhibit the most pronounced channel disintermediation, with specialist clinics investing in MRI partnerships to complete workup without hospital referral.
Asia-Pacific Viscosupplementation Market Segmentation
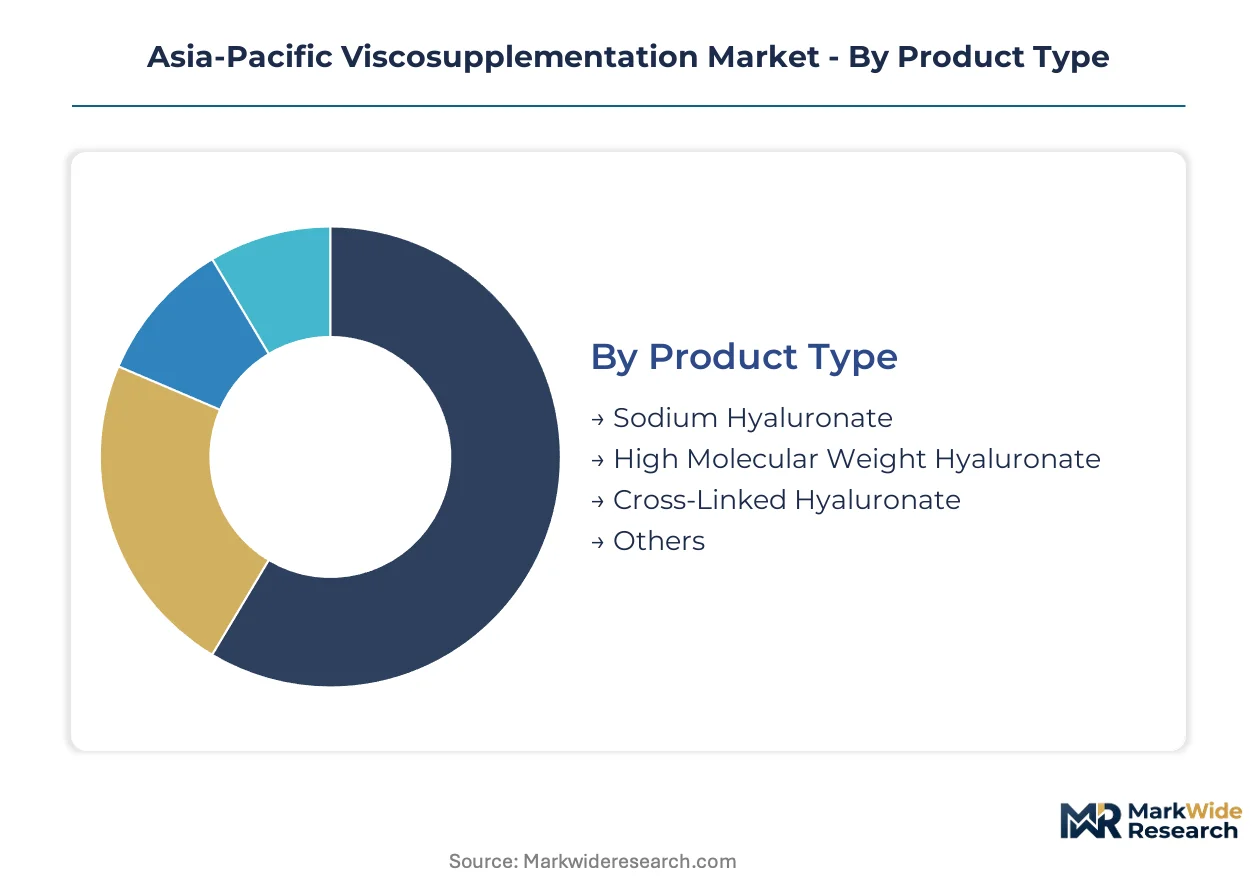
Formulation chemistry and delivery setting determine reimbursement pathways and procurement economics across Asia-Pacific viscosupplementation. Molecular architecture shapes clinical utility while end-user channel selection influences margin capture and patient access protocols.
Product Type:
Upgrade cycles from standard to extended-residence formulations are compressing injection frequency and reshaping clinic inventory economics across Japan, South Korea, and Australia.
- Sodium Hyaluronate:Linear unmodified polymer chains with molecular weights spanning 500-6,000 kDa dominate baseline therapy for early-stage knee osteoarthritis. Procurement concentrates in Japanese orthopedic clinics seeking PMDA-compliant endotoxin profiles for routine intra-articular administration.
- Cross-Linked Hyaluronate:Covalent bonding between hyaluronate chains extends intra-articular residence from days to weeks, enabling single-injection protocols. Demand clusters in Australian ambulatory centers where TGA post-market surveillance requirements favor products with robust longitudinal outcome data.
- High Molecular Weight Hyaluronate:Formulations exceeding 3,000 kDa deliver enhanced viscoelasticity for advanced joint degeneration cases.
- Others:Composite formulations incorporating corticosteroids or analgesic adjuncts serve niche pain management protocols.
Volume placements concentrate in sodium hyaluronate; the faster expansion belongs to cross-linked hyaluronate.
Application:
Cost tier stratification separates acute traumatic indications from chronic degenerative management, with reimbursement intensity varying by clinical pathway complexity.
- Osteoarthritis:Progressive cartilage degradation in weight-bearing joints drives the core therapeutic indication, with hyaluronate restoring synovial fluid lubrication and shock absorption. Japanese and South Korean national health insurance programs cover knee osteoarthritis viscosupplementation, anchoring procedure volume in Tokyo, Seoul, and Osaka metropolitan clusters.
- Sports Injuries:Acute ligament and meniscal trauma in active populations creates episodic demand for joint lubrication during rehabilitation. Australian private sports medicine practices in Sydney and Melbourne represent the fastest-expanding channel for athlete-focused injection protocols.
- Post-Surgical Recovery:Arthroscopy and joint replacement adjunct therapy supports mechanical function restoration.
- Chronic Joint Pain:Long-standing discomfort in non-osteoarthritic conditions drives off-label utilization patterns.
Procedure economics favor osteoarthritis management; sports injury applications are climbing the fastest as ambulatory sports medicine expands across Australia.
End User:
Customer type migration from institutional to specialist outpatient settings is redistributing procurement authority and inventory risk exposure.
- Orthopedic Clinics:Specialist ambulatory facilities with same-day injection capabilities are displacing hospital-based administration across Japan and Australia. Melbourne, Sydney, and Tokyo clinics are investing in MRI partnerships to complete diagnostic workup without referral delays, compressing patient pathways.
- Hospitals:Tertiary institutions retain complex case management and multi-joint injection protocols requiring imaging guidance.
- Rehabilitation Centers:Post-acute facilities integrate viscosupplementation into multimodal recovery programs for joint function restoration.
- Pain Management Centers:Anesthesia-led practices employ hyaluronate as part of interventional pain protocols for refractory joint discomfort.
Patient flows concentrate in orthopedic clinics; pain management centers are expanding most quickly as direct-to-specialist referral platforms fragment traditional gatekeeper channels.
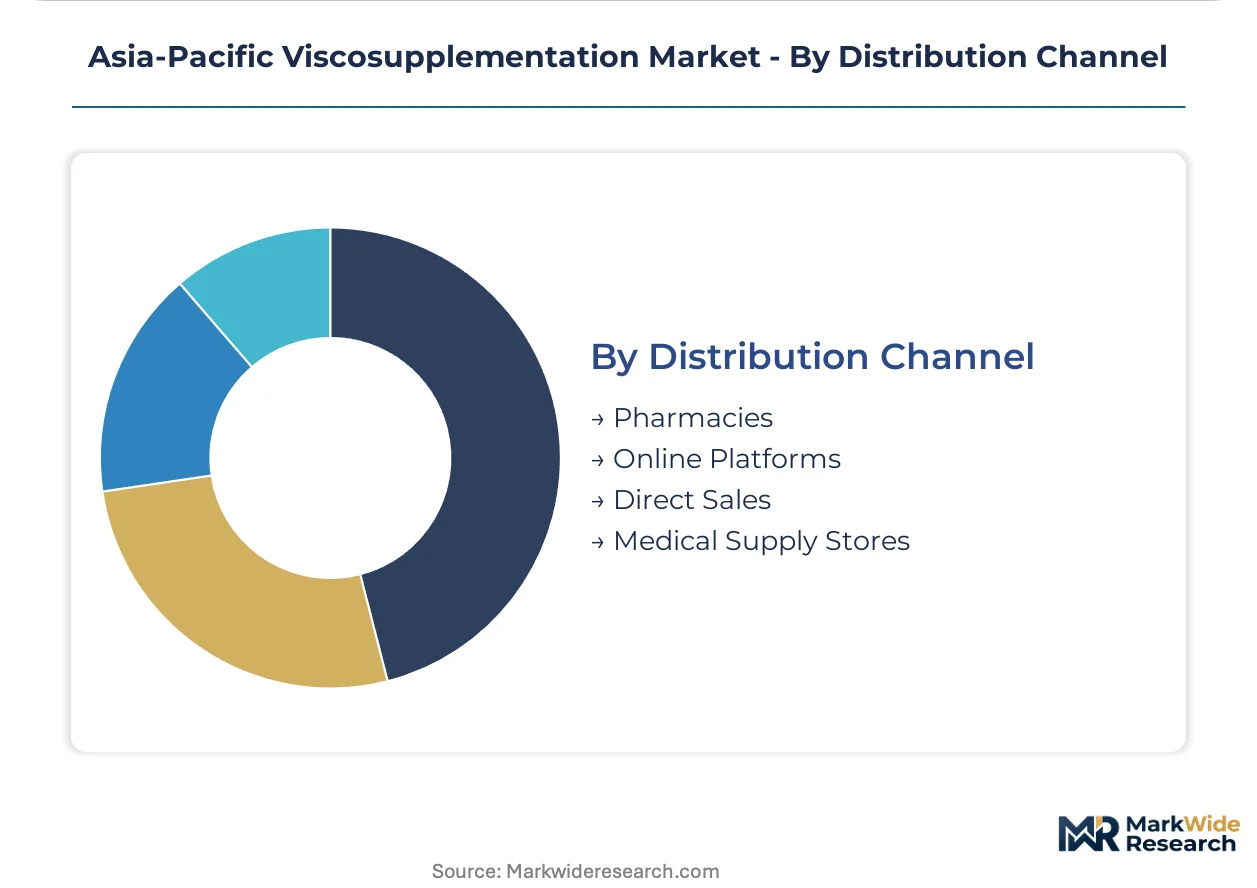
Distribution Channel:
Supply concentration in fermentation-based manufacturing clusters shapes logistics requirements and cold chain infrastructure investment priorities.
- Direct Sales:Manufacturer-to-clinic relationships dominate high-value cross-linked formulations requiring temperature-controlled handling and specialized inventory management. Seikagaku Corporation and LG Chem Life Sciences leverage captive production in Japan and South Korea to secure direct procurement contracts with major orthopedic clinic chains.
- Pharmacies:Retail and hospital pharmacy channels handle standard sodium hyaluronate products with established cold chain protocols.
- Online Platforms:Digital procurement portals are emerging for consumable replenishment in high-volume clinic networks.
- Medical Supply Stores:Regional distributors serve secondary markets with fragmented clinic density across Australia's remote territories and Japan's island prefectures.
Transaction volume concentrates in direct sales; online platforms are gaining share fastest as clinic procurement digitizes across urban Australian and Japanese markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-based sodium hyaluronate production clusters in Japanese and South Korean facilities anchor supply security for injectable manufacturers across Asia-Pacific. PMDA, TGA, and MFDS regulatory divergence shapes registration economics and clinical trial placement across the region.
Japan
Tokyo and Osaka metropolitan areas concentrate knee osteoarthritis procedure volume under National Health Insurance coverage. PMDA tightened endotoxin thresholds for intra-articular devices, filtering procurement toward qualified manufacturers with captive fermentation capacity. Seikagaku Corporation maintains precursor production in domestic facilities to sustain quality control over sodium hyaluronate supply.
South Korea
Seoul Capital Area drives demand through National Health Insurance Service reimbursement for viscosupplementation procedures. MFDS enforces distinct purity and clinical evidence requirements that fragment registration pathways from Japanese and Australian protocols. LG Chem Life Sciences anchors regional production scale through its biopolymer platform serving domestic and export markets.
Australia
Melbourne and Sydney orthopedic clinics displace hospital-based administration through same-day injection protocols. TGA reference pricing mechanisms for follow-on hyaluronate products compress margin structures ahead of patent cliffs. Post-market surveillance requirements mandate real-world outcome registries, reshaping trial design priorities for product sponsors.
China
Aging demographics in Yangtze River Delta and Pearl River Delta urban clusters expand addressable patient volumes for joint degeneration management. NMPA regulatory pathways for intra-articular medical devices require distinct stability data from Japan and South Korean submissions. Private hospital chains in Beijing and Shanghai expand joint care centers without established viscosupplementation protocols.
Thailand
Bangkok private hospital chains expand joint care infrastructure without mature viscosupplementation adoption patterns. The country's national pharmaceutical regulator maintains separate medical device registration requirements from ASEAN harmonization frameworks. Medical tourism flows from neighboring markets create episodic demand for premium orthopedic procedures.
Asia-Pacific Viscosupplementation Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers invest in cross-linked formulation capabilities to capture extended-residence product premiums. The vendor base concentrates around fermentation-based biopolymer specialists with captive precursor supply and multinational pharmaceutical platforms with orthopedic device portfolios. Three archetypes define positioning: Japanese fermentation specialists with backward-integrated raw material control, South Korean chemical conglomerates with biopolymer scale, and European-origin pharmaceutical firms with regulatory navigation expertise. M&A activity and strategic partnerships represent the dominant competitive moves as sponsors seek manufacturing capacity and regional registration infrastructure.
Within the fermentation-specialist tier, Seikagaku Corporation exemplifies captive production architecture, while LG Chem Life Sciences anchors scale-driven positioning through its South Korean biopolymer platform. European-origin players including Fidia Farmaceutici S.p.A. and Ferring Pharmaceuticals occupy positions emphasizing regulatory dossier sophistication across PMDA, TGA, and MFDS pathways. These named entities represent strategic archetypes rather than exhaustive market coverage, with additional participants including Zimmer Biomet Holdings, Chugai Pharmaceutical, Bioventus LLC, Anika Therapeutics Inc., and Sanofi S.A. competing across formulation and distribution vectors.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings |
| Fidia Farmaceutici S.p.A. |
| Seikagaku Corporation |
| Ferring Pharmaceuticals |
| LG Chem Life Sciences |
| Chugai Pharmaceutical |
| Bioventus LLC |
| Anika Therapeutics Inc. |
| Sanofi S.A. |
| Others |
Value Chain & Pricing Dynamics
Family-owned fermentation specialists in Japan and South Korea anchor raw material supply for sodium hyaluronate precursors, translating captive production control into pricing discipline that resists commoditization pressure from Australian biosimilar entry protocols. PMDA and TGA purity standards fragment procurement tiers, concentrating premium positioning among qualified manufacturers while marginal suppliers absorb margin compression in standard hyaluronate segments.
Pricing Analysis
Service bundling separates qualified manufacturers from commodity suppliers, with PMDA-compliant endotoxin documentation and cold chain validation included in cross-linked formulation contracts while standard hyaluronate transactions strip these to bare product pricing. Three-tier pricing structure across premium single-injection cross-linked, standard multi-injection sodium hyaluronate, and economy unbranded alternatives reflects molecular architecture and regulatory certification intensity. Cost compression in standard formulations intensifies as Australia's TGA reference pricing mechanisms for follow-on products compress originator margins ahead of patent cliffs. Orthopedic clinics in Melbourne and Sydney exhibit highest price sensitivity for multi-injection protocols, while Japanese National Health Insurance reimbursement insulates Tokyo and Osaka facilities from direct cost pressure.
Supply Chain Analysis
Fermentation engineering talent scarcity in legacy Japanese and South Korean facilities constrains capacity expansion for sodium hyaluronate precursor production, limiting new entrant manufacturing capabilities regardless of capital availability. Supply concentrates in Japanese captive fermentation facilities and South Korean biopolymer platforms, with raw material dependencies on pharmaceutical-grade glucose feedstocks, endotoxin-controlled water systems, and specialized bioreactor vessels. Single-source geographic risk in East Asian fermentation clusters exposes manufacturers to regional logistics disruption and regulatory inspection backlogs. Distribution runs through direct manufacturer-to-clinic relationships for temperature-sensitive cross-linked formulations, with pharmacy and medical supply store channels handling standard products across Australia's remote territories and Japan's island prefectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation scale-up talent scarcity in Japan and South Korea constrains sodium hyaluronate precursor capacity expansion, propping pricing power for incumbent manufacturers with qualified production infrastructure.
For Market Incumbents: Anticipate biosimilar entry pressure in Australian standard hyaluronate segments by accelerating cross-linked formulation capacity additions in Japanese fermentation facilities, while securing PMDA and TGA inspection priority through enhanced pharmacovigilance infrastructure investment. Channel control through direct procurement contracts with expanding orthopedic clinic chains in Melbourne, Sydney, and Tokyo defends margin position against price erosion from follow-on competitors. For New Entrants and Emerging Players: Capture white-space demand in Thailand, Malaysia, and Indonesia where private hospital chains expand joint care centers without established viscosupplementation protocols, bypassing saturated Japanese and South Korean reimbursement markets. Partner with regional distributors possessing validated cold chain infrastructure across Australia's remote territories as the most penetrable entry pathway without fermentation capacity investment. For Investors and Strategic Acquirers: MFDS reimbursement list expansion for hip and shoulder indications beyond knee osteoarthritis is the leading indicator that anatomical segment diversification will reshape portfolio economics over the medium-term horizon. Acquisition targets should prioritize Japanese fermentation specialists with backward-integrated sodium hyaluronate precursor supply and existing PMDA qualified facility status, with biosimilar market share inflection in Australian tender protocols as the signal to watch for timing entry.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Linked Formulation Capacity Expansion | Captures premium positioning as Australian clinics adopt single-injection protocols for moderate osteoarthritis cases. |
| PMDA Qualified Facility Investment | Filters procurement toward manufacturers meeting tightened endotoxin thresholds for intra-articular devices in Japan. |
| Southeast Asia Distribution Partnership | Establishes early presence in Thailand and Indonesia before private hospital chains finalize procurement protocols. |
| Real-World Outcome Registry Development | Satisfies TGA post-market surveillance requirements ahead of Australian reimbursement negotiations. |
| Fermentation Talent Acquisition Program | Addresses biopolymer production engineering scarcity constraining new entrant manufacturing capabilities. |
Study Parameters
Independent corroboration across orthopedic clinic procurement managers, pharmaceutical regulatory affairs leads, hospital formulary directors, and biopolymer fermentation engineers underwrites the qualitative findings in this study. Primary interviews with these stakeholders combined secondary validation through PMDA medical device registration databases, TGA therapeutic goods listings, MFDS approval records, and National Health Insurance Service reimbursement bulletins. Bottom-up procedure volume estimates from metropolitan clinic clusters triangulate against top-down manufacturer shipment data across the analysis window.
Rate-of-change decomposition separates volume expansion from value capture across formulation chemistry tiers, end-user channel migration, and regional regulatory clusters. Segmentation dimensions include molecular weight architecture, cross-linking technology, injection frequency protocol, and reimbursement pathway intensity. CAGRs derive from fitted growth curves applied to procedure volume trajectories, with hyaluronic acid raw material supply constraints and biosimilar entry timing as primary forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MFDS reimbursement list revisions, TGA reference pricing mechanism adjustments, and PMDA purity standard enforcement intensity. Material deviation in biosimilar market share capture rates or fermentation capacity expansion timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Ablation Technologies Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Vascular Boot Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Absorbable PGLA Surgical Sutures Market
Medical Devices
Global Non Fusion Spinal Devices Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
Global Casting Devices Market
Medical Devices
Spherical IOL Market
Medical Devices
Joint Reconstruction Devices Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Asia-Pacific Biosurgery Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Interphalangeal Fusion Market