
 South Africa Anesthesia Devices Market | 2026-2036
South Africa Anesthesia Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Anesthesia Devices Market Analytics
Aftermarket service revenue is narrowing as original equipment manufacturers tighten control over calibration, spare parts, and software updates. B. Braun Melsungen AG leverages its established service infrastructure across South African provinces to sustain recurring income streams. Medtronic PLC anchors its position through intensive R&D allocation toward integrated monitoring ecosystems. Draegerwerk AG specializes in high-acuity anesthesia workstations for academic hospital complexes.
Anesthesia devices encompass mechanical and electronic systems designed to deliver precise inhalational and intravenous anesthetic agents while monitoring patient vital parameters such as end-tidal carbon dioxide, oxygen saturation, and airway pressures during surgical procedures. These systems integrate vaporizers, breathing circuits, gas delivery modules, and patient monitors to maintain controlled unconsciousness and analgesia across operative settings. The product type dimension shows anesthesia machines capturing the dominant installed base while software-integrated monitoring equipment represents the fastest-expanding margin pool. Electronic technology systems lead current hospital procurement specifications, though hybrid configurations retain substantial share in cost-constrained clinic environments.
South Africa's Health Products Regulatory Authority governs medical device registration, licensing, and post-market surveillance, while the South African Bureau of Standards enforces technical compliance through SANS specifications aligned with IEC 60601 safety standards. The National Health Insurance policy framework is reshaping procurement centralization and supplier qualification requirements. Stakeholders must monitor regulatory harmonization timelines and procurement platform transitions to align product portfolios with evolving reimbursement and tender structures.
Market Dynamics
The National Health Insurance policy framework is consolidating procurement authority within South Africa's public hospital system, compressing vendor relationships and elevating software-integrated anesthesia workstations as the default specification for tertiary tenders.
Growth Catalysts
- National Health Insurance Centralization:The policy framework aggregates purchasing power across provincial health departments, creating volume incentives for suppliers capable of nationwide service coverage.
- Gauteng Tertiary Modernization:Academic hospital complexes in Johannesburg and Pretoria are replacing legacy anesthesia machines with integrated monitoring ecosystems to support complex surgical volumes.
- SANS 60601-1 Alignment:South African Bureau of Standards enforcement of IEC-aligned electrical safety specifications is accelerating replacement cycles in facilities with aging installed bases.
Market Restraints
- Import Dependency for Electronic Modules:Core patient monitoring sensors and vaporizer control systems rely on concentrated Asian manufacturing, exposing margins to currency volatility and shipping disruptions.
- Service Infrastructure Concentration:Original equipment manufacturers have captured calibration and spare parts distribution, narrowing independent service provider viability and elevating total cost of ownership.
- Western Cape Budget Constraints:Provincial health departments face competing capital priorities, delaying anesthesia workstation refresh cycles in secondary hospitals despite clinical need.
Strategic Opportunities
- Eastern Cape Secondary Hospital Penetration:Under-equipped surgical facilities in Port Elizabeth and Mthatha present whitespace for mid-tier anesthesia machine deployment with bundled training services.
- Software-as-a-Service Monitoring:Cloud-connected anesthesia data platforms enable recurring revenue streams through subscription-based analytics and remote technical support.
- Public-Private Partnership Tenders:NHI pilot procurement channels are opening to private sector equipment vendors meeting centralized qualification standards.
Industry Challenges
- Biomedical Engineering Talent Scarcity:South African universities produce insufficient anesthesia device technicians to support expanded installed bases across rural provinces.
- Legacy System Integration Complexity:Hybrid anesthesia configurations in cost-constrained clinics require custom interfacing with non-standard patient monitors, extending deployment timelines.
- SAHPRA Registration Timelines:South Africa's Health Products Regulatory Authority review cycles for software-upgradable devices lag hardware-only approvals, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Anesthesia Devices Market |
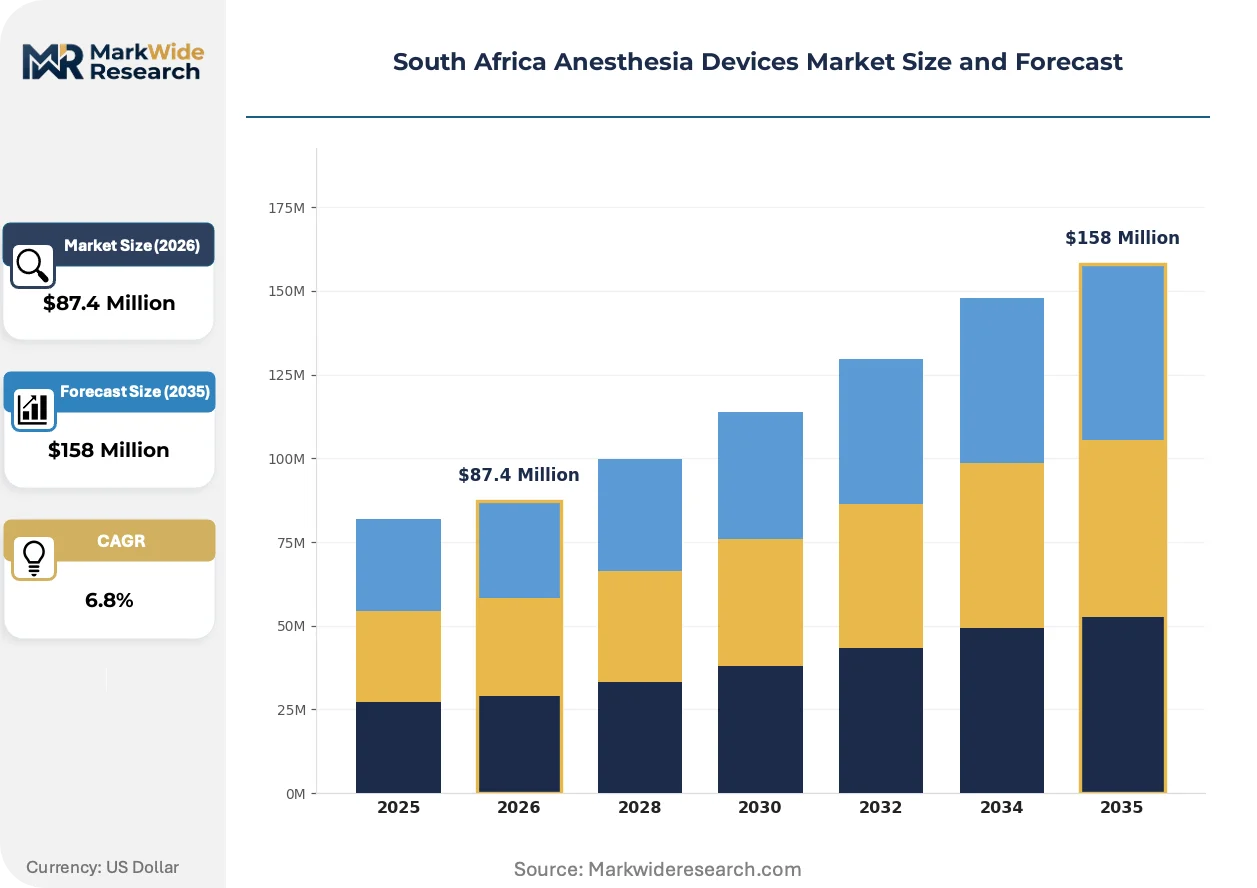
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaporizer, Anesthesia Machine, Breathing Circuit, Monitoring Equipment End User: Hospitals, Clinics, Surgical Centers, Emergency Services Technology: Electronic, Manual, Hybrid, Software-Integrated Service Type: Installation, Maintenance, Training, Consulting |
| Companies Covered | B. Braun Melsungen AG, Medtronic PLC, Draegerwerk AG, GE Healthcare, Koninklijke Philips NV, ICU Medical Inc (Smiths Medical), Teleflex Incorporated, Mindray Medical International Limited, Aspen Pharmacare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Anesthesia Devices Market Evolving Landscape
Anesthesia device architecture is converging around integrated data ecosystems, with hardware specifications increasingly subordinate to software capabilities and connectivity standards in procurement evaluations.
Closed-loop anesthesia delivery systems incorporating real-time pharmacokinetic modeling are digitizing intraoperative workflow in South Africa's academic medical centers. Anesthesiologists at Groote Schuur Hospital and Charlotte Maxeke Johannesburg Academic Hospital have adopted these platforms for cardiac and neurosurgical cases. The technology is digitizing documentation burden while compressing variability in anesthetic depth management.
South Africa's Health Products Regulatory Authority has aligned medical device cybersecurity requirements with international IMDRF guidance, mandating vulnerability disclosure protocols for network-connected anesthesia workstations. Manufacturers must now submit software bill of materials and patch management procedures as registration conditions. High-acuity equipment categories face the steepest compliance burden, with academic hospitals leading implementation.
Centralized tender platforms are displacing hospital-level purchasing autonomy as provincial health departments consolidate anesthesia device procurement under NHI-aligned frameworks. Single-supplier contracts covering multiple facilities are replacing fragmented institutional negotiations. This concentration is most advanced in Gauteng and Western Cape, where tertiary center specifications now cascade to secondary hospitals through master service agreements.
South Africa Anesthesia Devices Market Segmentation
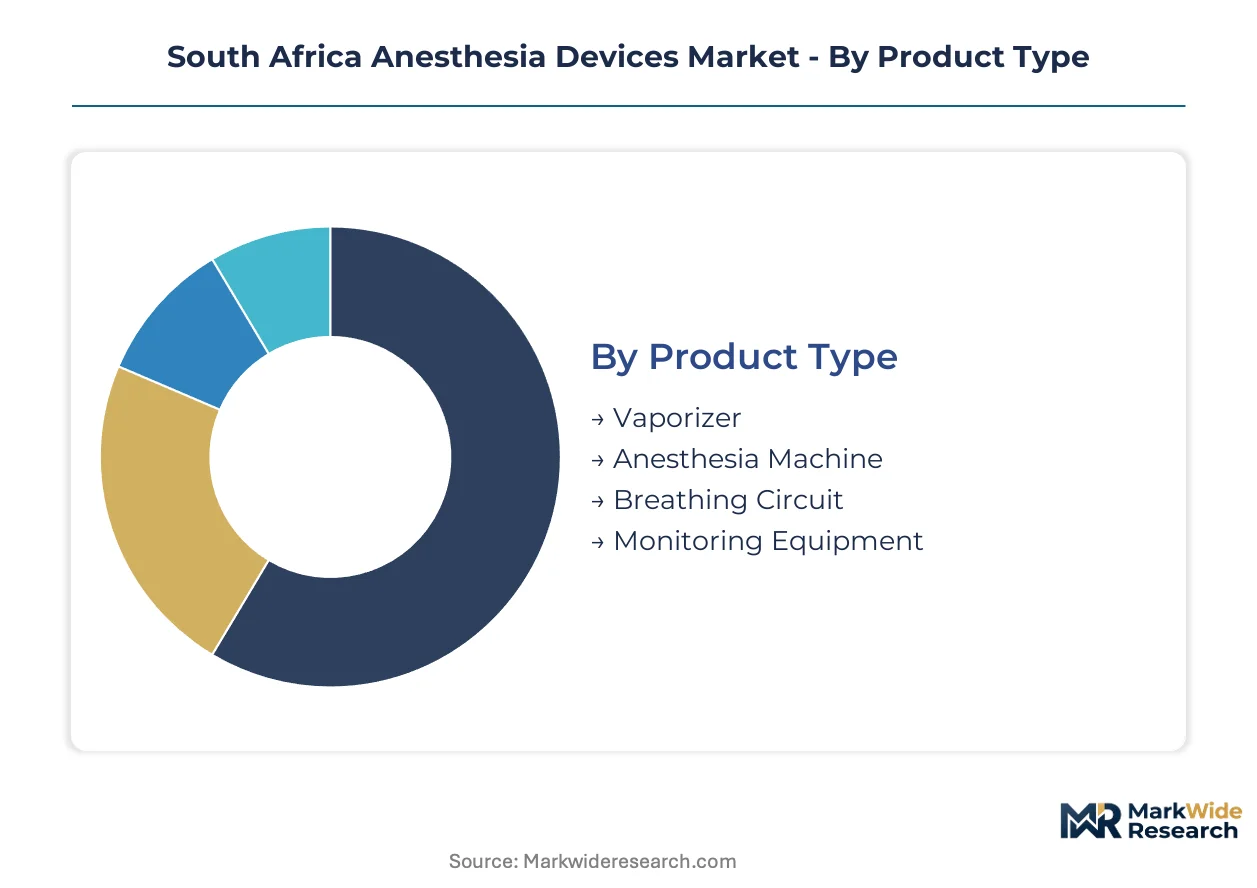
Procurement centralization under the National Health Insurance policy is compressing vendor relationships around standardized specifications. Segmentation reveals where software-integrated systems displace legacy configurations and which service models sustain recurring revenue.
Product Type:
Equipment composition determines capital intensity and replacement cadence across South Africa's hospital tiers.
- Anesthesia Machine:Integrated platforms combine gas delivery, ventilation, and vaporization in single units. Gauteng tertiary centers specify these for cardiac and neurosurgical suites where precise control over anesthetic depth is non-negotiable.
- Monitoring Equipment:End-tidal CO2 sensors, pulse oximetry modules, and airway pressure transducers feed data into centralized displays. Western Cape academic hospitals are bundling these with workstation upgrades to satisfy SANS 60601-1 electrical safety alignment.
- Vaporizer:Precision agent-specific vaporizers mount to anesthesia machines or operate as standalone units for field anesthesia.
- Breathing Circuit:Disposable and reusable circuits connect patients to gas delivery systems, with procurement volumes tied to surgical caseloads.
Anesthesia machines anchor the installed base across public hospital networks. Monitoring equipment is climbing the fastest as software-integrated ecosystems displace standalone devices.
End User:
Customer type shapes specification complexity and service contract duration.
- Hospitals:Public tertiary facilities in Johannesburg and Pretoria drive demand for high-acuity workstations with integrated data capture. NHI centralization is consolidating purchasing authority within provincial health departments, favoring vendors with nationwide service coverage.
- Surgical Centers:Day-procedure facilities in Durban and Cape Town prioritize compact anesthesia machines with rapid turnover capabilities. These sites generate concentrated maintenance contract revenue despite lower capital outlays per unit.
- Clinics:Secondary facilities in Eastern Cape provinces operate hybrid configurations blending manual and electronic components.
- Emergency Services:Pre-hospital and military medical units require portable anesthesia systems for field deployment.
Hospitals absorb the dominant share of capital expenditure. Surgical centers are expanding most quickly as outpatient procedure volumes rise.
Technology:
Control architecture determines regulatory pathway and procurement evaluation weighting.
- Software-Integrated:Closed-loop delivery systems incorporate real-time pharmacokinetic modeling and automated documentation. Groote Schuur Hospital and Charlotte Maxeke Johannesburg Academic Hospital have adopted these platforms for complex cases, digitizing intraoperative workflow.
- Electronic:Microprocessor-controlled vaporizers and ventilators dominate current hospital procurement specifications, satisfying SAHPRA cybersecurity requirements for network-connected devices.
- Hybrid:Cost-constrained clinics in rural provinces combine electronic monitoring with manual gas delivery to manage capital outlays.
- Manual:Basic vaporizers and breathing systems persist in resource-limited settings and emergency stockpiles.
Electronic systems command the current procurement cycle. Software-integrated platforms are gaining share fastest as academic hospitals modernize.
Service Type:
Revenue model differentiation separates equipment vendors from pure-service competitors.
- Maintenance:Calibration, preventive servicing, and spare parts replacement generate recurring income. Original equipment manufacturers have tightened control over these activities, narrowing independent provider viability.
- Training:Anesthesiologist and technician education on new platforms extends deployment timelines but reduces adverse event risk. Biomedical engineering talent scarcity across South African universities elevates vendor-delivered training value.
- Installation:Site preparation, commissioning, and acceptance testing for new anesthesia workstations.
- Consulting:Workflow optimization and integration planning for centralized procurement frameworks.
Maintenance contracts anchor service revenue. Training is expanding most quickly as software complexity outpaces local technical education output.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public hospital procurement in Gauteng and Western Cape provinces operates with limited price elasticity, while Eastern Cape and rural facilities face severe budget constraints that compress equipment specifications toward hybrid configurations.
Gauteng
Academic hospital complexes in Johannesburg and Pretoria drive demand for software-integrated anesthesia workstations with closed-loop delivery capabilities. The National Health Insurance centralization framework aggregates purchasing authority within the provincial health department. Charlotte Maxeke Johannesburg Academic Hospital and Steve Biko Academic Hospital are replacing legacy machines with integrated monitoring ecosystems.
Western Cape
Tertiary centers in Cape Town specify high-acuity anesthesia systems for cardiac and neurosurgical suites where precise anesthetic depth control is mandatory. SAHPRA cybersecurity requirements for network-connected devices shape procurement evaluations. Groote Schuur Hospital anchors adoption of real-time pharmacokinetic modeling platforms for complex surgical cases.
KwaZulu-Natal
Durban's surgical centers and day-procedure facilities prioritize compact anesthesia machines with rapid turnover capabilities for rising outpatient volumes. The provincial health department faces competing capital priorities that delay workstation refresh cycles. Metropolitan clusters concentrate maintenance contract revenue despite lower per-unit capital outlays.
Eastern Cape
Under-equipped surgical facilities in Port Elizabeth and Mthatha present deployment whitespace for mid-tier anesthesia machines with bundled training services. Budget constraints force hybrid configurations blending electronic monitoring with manual gas delivery. Biomedical engineering talent scarcity extends deployment timelines across rural provinces.
Free State
Secondary hospitals in Bloemfontein operate aging installed bases accelerated toward replacement by SANS 60601-1 electrical safety alignment enforcement. The provincial health department participates in NHI pilot procurement channels opening to qualified private sector vendors. Master service agreements cascade tertiary center specifications to secondary facilities.
South Africa Anesthesia Devices Market Competitive Landscape
Full-system integrators and component specialists split the market between bundled workstation contracts and modular upgrade pathways. The vendor base concentrates around established service infrastructure capable of nationwide coverage under centralized tender frameworks. Three archetypes dominate: European-origin full-line manufacturers, Asian-scale producers, and regional service-anchored distributors. Competitive moves center on tightening control over aftermarket calibration and spare parts distribution, plus securing provincial master service agreements before NHI procurement consolidation finalizes.
Among European-origin full-line manufacturers, B. Braun Melsungen AG and Draegerwerk AG occupy positions defined by service infrastructure depth across South African provinces. Medtronic PLC represents the integrated monitoring ecosystem archetype, anchoring R&D-intensive positioning within academic hospital procurement channels. These three exemplify how aftermarket control and centralized qualification standards are reshaping vendor viability under the National Health Insurance framework.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Medtronic PLC |
| Draegerwerk AG |
| GE Healthcare |
| Koninklijke Philips NV |
| ICU Medical Inc (Smiths Medical) |
| Teleflex Incorporated |
| Mindray Medical International Limited |
| Aspen Pharmacare |
| Others |
Value Network & Pricing Analysis
Single-source dependency for patient monitoring sensors and vaporizer control modules manufactured in concentrated Asian supply bases determines both the spread between premium software-integrated workstations and economy-tier hybrid configurations and the elongated procurement timelines that compress vendor margins. Currency volatility against the Rand amplifies landed cost uncertainty, forcing distributors to buffer pricing through service contract bundling rather than hardware markup alone.
Pricing Analysis
After-sales service revenue from calibration, preventive maintenance, and software update subscriptions drives lifetime value capture for anesthesia workstation vendors. Three-tier pricing structure across premium, standard, and economy levels separates academic hospital integrated ecosystems from mid-tier secondary hospital configurations and rural clinic hybrid systems. Cost compression in the economy tier is intensifying because provincial health departments face competing capital priorities under National Health Insurance centralization. Public tertiary centers in Gauteng and Western Cape exhibit the lowest price sensitivity, while Eastern Cape secondary hospitals and rural clinics demonstrate acute budget constraint responsiveness.
Supply Chain Analysis
Upstream feedstock for electronic patient monitoring modules draws from concentrated manufacturing in China, South Korea, and Taiwan, with precision vaporizer components sourced from German and Japanese specialty producers. Core inputs include semiconductor chips for control systems, sensor arrays for end-tidal CO2 and pulse oximetry, and medical-grade polymers for breathing circuits. Single-source vulnerability for advanced sensor modules exposes South African distributors to shipping disruption and tariff exposure. Distribution runs through Johannesburg-based medical equipment importers holding SAHPRA import licenses, with secondary logistics nodes in Cape Town and Durban serving provincial health department consolidation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against refurbished equipment channels and low-cost Asian manufacturers penetrating through direct provincial tender participation, threatening incumbent service-anchored positioning.
For Market Incumbents: Insulate installed base relationships by tightening captive control over calibration equipment and spare parts distribution, narrowing independent service provider viability. Deepen backward integration into software update infrastructure to capture recurring revenue streams as SAHPRA cybersecurity mandates expand. Defend against refurbished workstation substitution by embedding proprietary data architecture that complicates third-party reconditioning. For New Entrants and Emerging Players: Build out service infrastructure in Eastern Cape and Free State provinces where biomedical engineering talent scarcity extends deployment timelines and creates whitespace for bundled training offerings. Target under-equipped secondary hospitals in Port Elizabeth and Mthatha with mid-tier anesthesia machines featuring simplified electronic interfaces. Pursue public-private partnership qualification under NHI pilot channels as the fastest regulatory pathway to provincial master service agreements. For Investors and Strategic Acquirers: The market sits at a procurement consolidation phase that favors vendors with established nationwide service coverage and SAHPRA registration track records. Long-term viability over the next decade hinges on software-as-a-service monitoring capabilities and closed-loop anesthesia delivery platform development. Acquisition target archetypes include regional distributors with dense biomedical technician networks and software specialists with SAHPRA-cleared cybersecurity protocols. Watch for National Health Insurance tender platform finalization as the critical inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Acceleration | Software-upgradable device approvals lag hardware-only timelines, compressing product launch windows. |
| Provincial Master Service Agreement | NHI centralization favors single-supplier contracts covering multiple facilities under consolidated purchasing authority. |
| Biomedical Training Academy Partnership | University collaboration addresses technician scarcity while embedding vendor platforms into clinical education pathways. |
| Cloud-Connected Monitoring Platform | Subscription-based analytics enable recurring revenue streams beyond capital equipment sales cycles. |
| Backward Integration into Spare Parts | Captive distribution of calibration components narrows independent service provider competitive threat. |
Research Methodology
Cross-validation between procurement database analysis and clinical stakeholder interviews anchors the qualitative findings in observable tender behavior and frontline workflow requirements. Primary fieldwork engaged hospital purchasing committee members, biomedical engineering directors, anesthesiology department heads, and provincial health department contract managers across Gauteng, Western Cape, KwaZulu-Natal, and Eastern Cape. Secondary sources incorporated SAHPRA medical device registration records, National Treasury procurement disclosure reports, South African Bureau of Standards technical specifications, and academic hospital capital expenditure budgets. Bottom-up installed base enumeration triangulated against top-down provincial health department spending projections.
Calibration against historical replacement cycle data and documented SANS 60601-1 enforcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, end-user tier, technology architecture, and service contract structure, with provincial regulatory cluster differentiation capturing NHI implementation variance. CAGRs derived from surgical volume growth trajectories, equipment age distribution analysis, and centralized procurement volume incentives. Industry-specific forecast inputs include academic hospital modernization pipelines and Eastern Cape secondary hospital backlog assessments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by low-cost Asian manufacturers or refurbished equipment channels would shift outcomes beyond modeled ranges. Cross-checking against National Health Insurance tender award disclosures and provincial health department budget allocation announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Medication Management System Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Gracey Curette Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Support Surfaces Market
Medical Devices
Eye Massage Device Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Pulse Lavage Market