
 Aircraft Ignition System Market | 2026-2036
Aircraft Ignition System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Ignition System Market Analysis
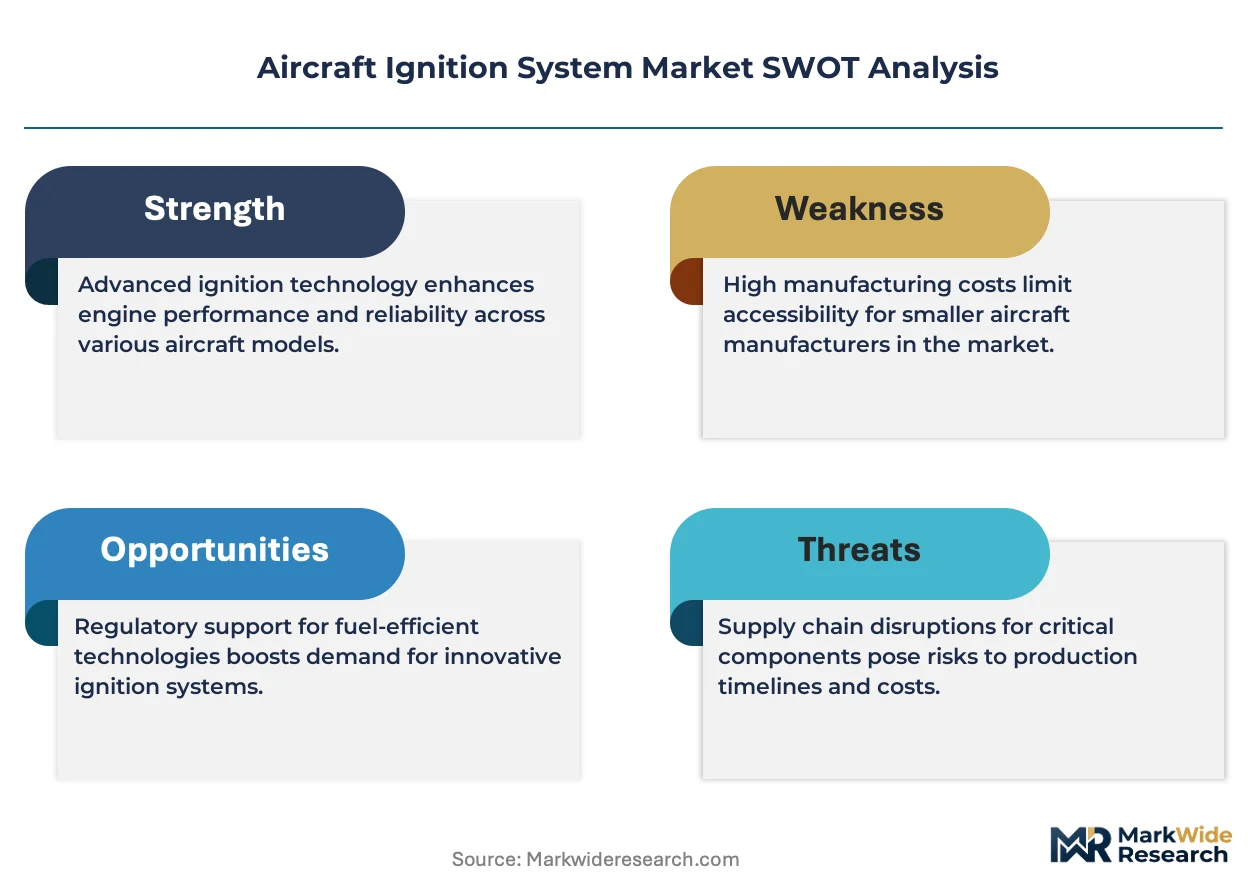
Ceramic insulators are pivoting toward silicon nitride compositions that withstand higher thermal loads and extend spark plug service intervals. Champion Aerospace leverages in-house ceramic processing to control material costs across its aviation spark plug portfolio. Unison Industries sustains dual-source strategies for exciter units that protect against supply disruption in military programs. Hartzell Engine Technologies anchors its aftermarket position through FAA-certified magneto overhaul capabilities that general aviation operators depend on for compliance.
An aircraft ignition system generates timed high-voltage electrical discharge across spark plug electrodes to initiate combustion in piston aircraft engines, typically operating at 14,000 to 20,000 volts with redundancy mandated for flight-critical applications. Electronic ignition systems are displacing magneto architectures in turboprop retrofits where digital timing control improves fuel efficiency and reduces maintenance cycles. Magneto ignition still dominates the training aircraft segment where mechanical simplicity and independence from electrical systems preserve market share. Aftermarket installation channels capture margin pools from aging general aviation fleets that require recurring magneto replacement and ignition harness upgrades.
FAA airworthiness directives and EASA certification standards govern ignition system design, testing, and field modification across all installed platforms. EPA leaded aviation gasoline regulations are forcing ignition system adaptations that support alternative fuel combustion profiles without engine knock or pre-ignition damage. Stakeholders must monitor emerging solid-state ignition architectures and their interaction with unleaded fuel formulations to anticipate certification pathways and fleet conversion economics.
Market Dynamics
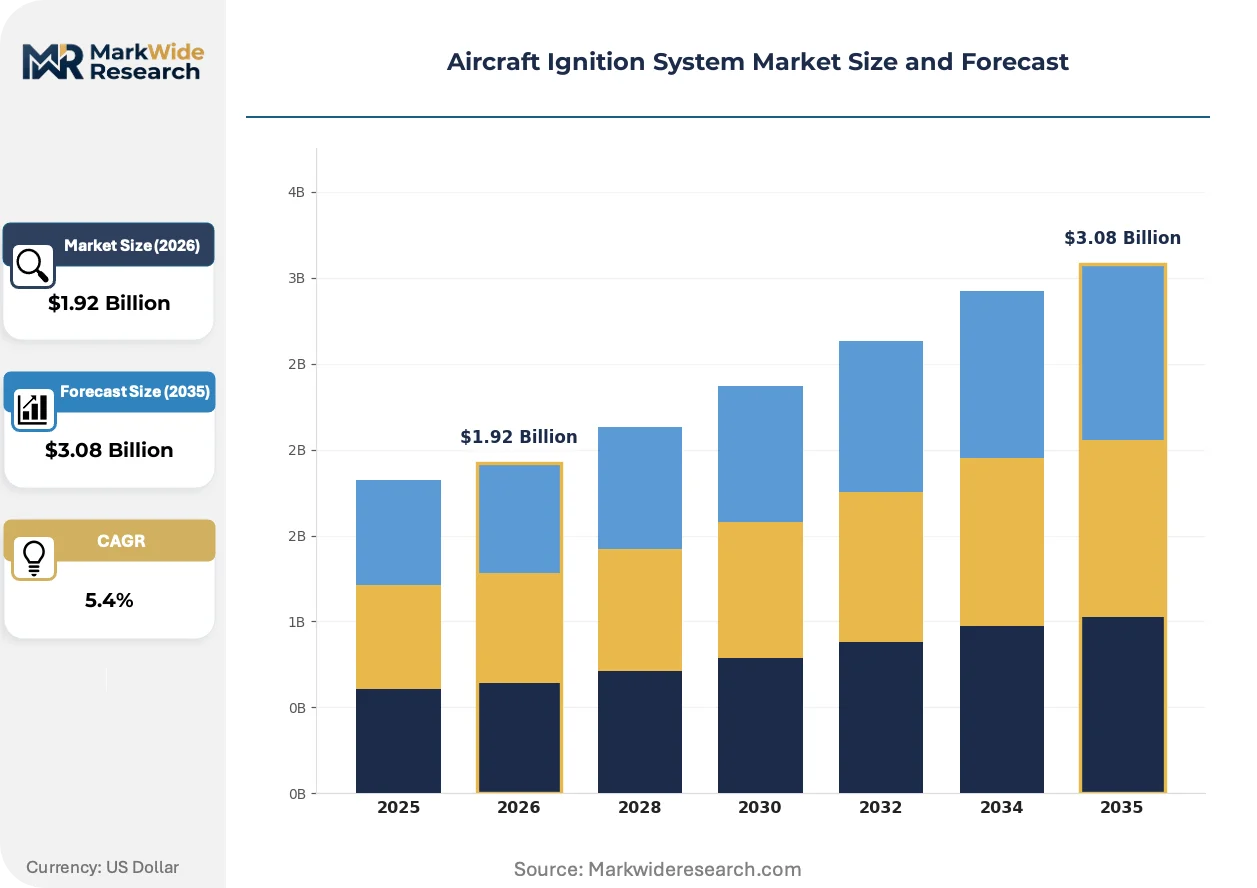
Electronic ignition architectures are displacing magneto systems across turboprop and light jet platforms, driven by FAA and EASA mandates for reduced emissions and digital engine control integration. This technology transition reconfigures supplier relationships, certification timelines, and aftermarket revenue pools for established ignition component manufacturers.
Growth Catalysts
- FAA Airworthiness Directives:Mandated magneto replacement intervals for aging general aviation fleets sustain recurring aftermarket demand for ignition harnesses and exciter units.
- Silicon nitride ceramic insulators:Advanced ceramic compositions withstand thermal loads above 1,200°C, extending spark plug service intervals and reducing total cost of ownership for commercial operators.
- Military platform modernization:Defense procurement programs across NATO member states fund electronic ignition retrofits for tactical turboprop aircraft to improve fuel efficiency and reduce logistics footprints.
Market Restraints
- Specialized cobalt and nickel alloy supply:Spark plug electrode materials face price volatility and geographic concentration in African and Russian mining jurisdictions, squeezing raw material cost structures.
- Dual-source exciter manufacturing constraints:Military programs require redundant supplier qualification, limiting vendor pool flexibility and extending procurement cycles for critical ignition components.
- Magneto mechanical durability:Simpler magneto architectures retain dominance in flight training aircraft where electrical system independence and field repairability outweigh electronic ignition efficiency gains.
Strategic Opportunities
- Unleaded aviation gasoline transition:EPA regulations phasing out 100LL avgas create demand for ignition system adaptations that optimize combustion timing for alternative fuel formulations without pre-ignition damage.
- Solid-state ignition convergence:Integration of digital engine control units with variable ignition timing enables real-time altitude and load compensation, opening retrofit markets for piston engine operators.
- Urban air mobility platforms:Electric-hybrid propulsion architectures for advanced air mobility vehicles require specialized ignition systems for range-extender turbine engines, creating new OEM qualification pathways.
Industry Challenges
- FAA Parts Manufacturer Approval timelines:Electronic ignition system certification requires extensive electromagnetic interference testing and flight-hour accumulation, compressing product launch windows against competitor first-mover advantages.
- Legacy magneto technical workforce:Mechanical ignition expertise concentrates among aging technician populations, creating knowledge transfer gaps as electronic architectures dominate new platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Ignition System Market |
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.08 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Ignition, Magneto Ignition, Plasma Ignition, Solid-State Ignition Technology: Turbocharge Ignition, Dual Ignition System, Automated Ignition, Continuous Wave Ignition End User: Commercial Aviation, Military Aviation, General Aviation, Helicopters Installation Type: Line Fit, Retrofit, OEM Installation, Aftermarket Installation |
| Companies Covered | Hartzell Engine Technologies, Electroair, Champion Aerospace, Air Power Inc., SureFly, TransDigm Group, Unison Industries, Sky Dynamics, Tempest Aero Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Ignition System Market Emerging Trajectories
Digital control architectures are penetrating piston and turboprop propulsion systems, compressing maintenance intervals and enabling predictive ignition health monitoring. This shift demands new competencies in embedded software, electromagnetic compatibility, and integrated engine management.
Capacitor discharge ignition technology is automating spark energy modulation across varying manifold pressure conditions, eliminating mechanical advance mechanisms. Regional airlines operating Beechcraft King Air and Cessna Caravan fleets are adopting these systems to reduce magneto overhaul frequency. The technology is automating timing precision previously requiring mechanical linkages, compressing the value proposition for traditional magneto suppliers.
EPA leaded aviation gasoline regulations are forcing ignition system recalibration to accommodate lower-octane unleaded formulations without detonation damage. Engine manufacturers are advancing modified compression ratios and spark timing maps to preserve power output. The piston training aircraft segment across the United States faces the steepest adaptation requirements as 100LL phase-out accelerates.
Aftermarket channel consolidation is compressing distributor margins as OEM-authorized service centers capture direct relationships with fleet operators. Independent maintenance facilities are responding with specialized magneto overhaul capabilities and expedited ignition harness fabrication. This pattern concentrates most visibly in the United States general aviation sector, where Part 145 repair stations compete for aging Cessna and Piper fleet maintenance contracts.
Aircraft Ignition System Market Segmentation
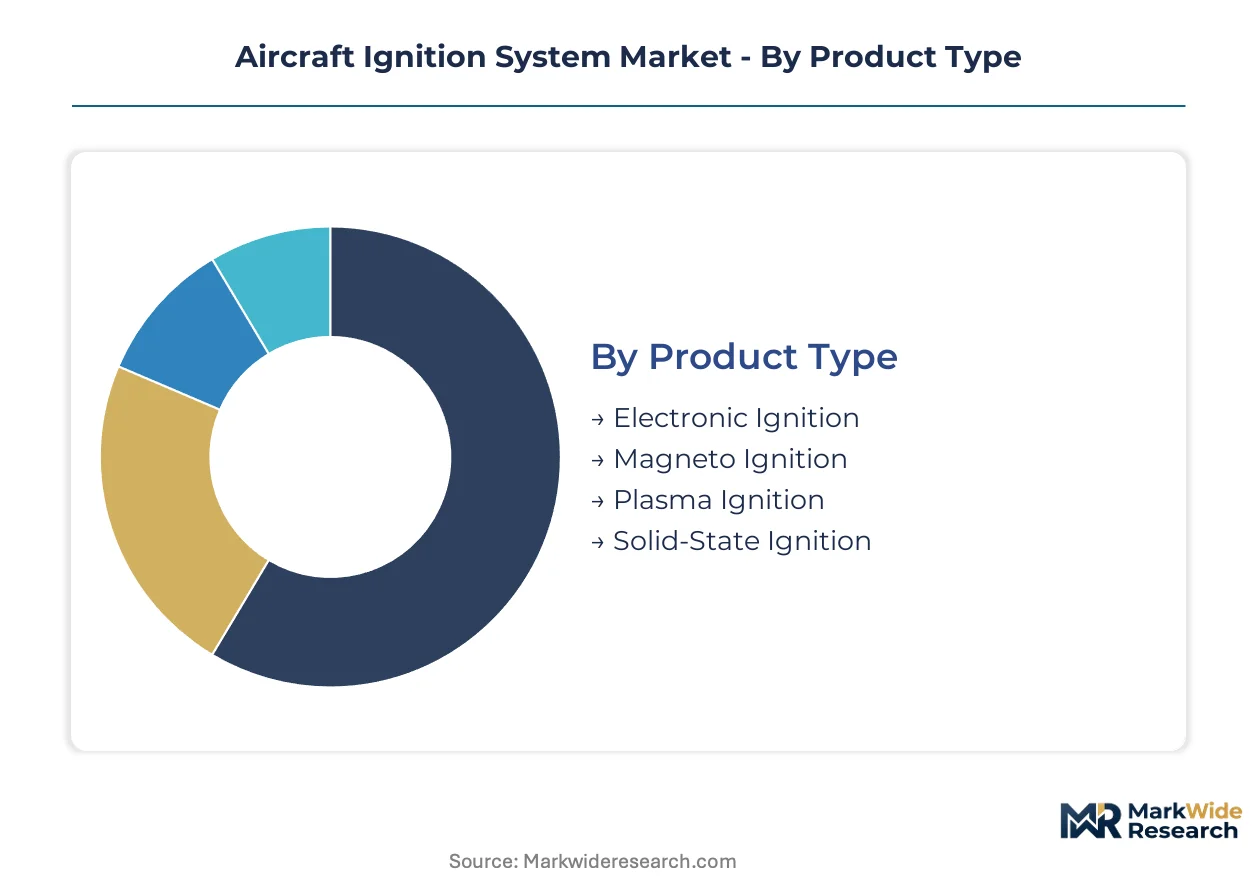
Ignition system architectures diverge sharply across aircraft propulsion categories, with certification requirements and maintenance economics dictating technology selection. Product type and installation channel configurations determine supplier margin structures and aftermarket revenue durability.
Product Type:
Standardization dominates high-volume commercial turboprop retrofits, while custom ignition timing maps preserve differentiation in piston engine platforms.
- Electronic Ignition:Digital timing control modules replace mechanical advance mechanisms with microprocessor-managed spark delivery across manifold pressure ranges. FAA-certified electronic systems are concentrating in Beechcraft King Air and Cessna Caravan regional airline fleets where fuel efficiency mandates drive retrofit procurement.
- Magneto Ignition:Self-contained electromagnetic generators produce high-voltage discharge without aircraft electrical system dependence. Training aircraft operators across the United States sustain demand for Champion and Slick magneto architectures where field repairability outweighs electronic efficiency advantages.
- Plasma Ignition:Corona discharge ignition enables leaner fuel mixtures through distributed plasma kernel formation. Experimental applications in high-altitude unmanned platforms test thermal tolerance limits.
- Solid-State Ignition:Semiconductor switching eliminates mechanical contact wear in exciter units. Military turboprop modernization programs specify solid-state architectures for reduced logistics footprints.
Most installed capacity flows through Magneto Ignition. Expansion is steepest in Electronic Ignition.
Technology:
Cost tier stratification separates premium automated systems from baseline continuous wave architectures in price-sensitive training aircraft.
- Turbocharge Ignition:Pressure-compensated spark energy modulation prevents detonation in boosted piston engines. Aftermarket demand concentrates in Cirrus and Cessna high-performance single-engine retrofits.
- Dual Ignition System:Redundant ignition channels satisfy FAR Part 23 and Part 25 airworthiness requirements for flight-critical redundancy. All certificated transport-category aircraft mandate dual-channel configurations.
- Automated Ignition:Full-authority digital engine control integrates ignition timing with fuel injection and propeller governing. Light jet OEMs specify automated architectures for reduced pilot workload.
- Continuous Wave Ignition:Sustained plasma discharge extends lean misfire limits in experimental alternative-fuel testing. Research applications at NASA Glenn and FAA William J. Hughes Technical Center validate combustion stability.
Volume concentrates in Dual Ignition System. Automated Ignition is gaining share fastest in new platform development.
End User:
Application severity drives specification divergence, with military programs demanding extended temperature ranges and commercial operators prioritizing time-between-overhaul metrics.
- Commercial Aviation:Regional turboprop fleets specify electronic ignition for digital engine monitoring integration. EASA emissions standards accelerate technology transitions in ATR and De Havilland Canada platforms.
- Military Aviation:Tactical aircraft require electromagnetic hardening and nuclear event tolerance in ignition exciters. NATO procurement programs fund dual-source qualification for supply security.
- General Aviation:Piston engine operators balance magneto reliability against electronic ignition fuel savings. United States Part 91 and Part 135 fleets drive aftermarket harness and spark plug replacement cycles.
- Helicopters:Turbine ignition systems face unique vibration and altitude exposure profiles. Bell and Airbus Helicopters specify specialized exciter mounting and lead routing.
Procurement volume flows through Commercial Aviation. Military Aviation shows the steepest technology refresh trajectory.
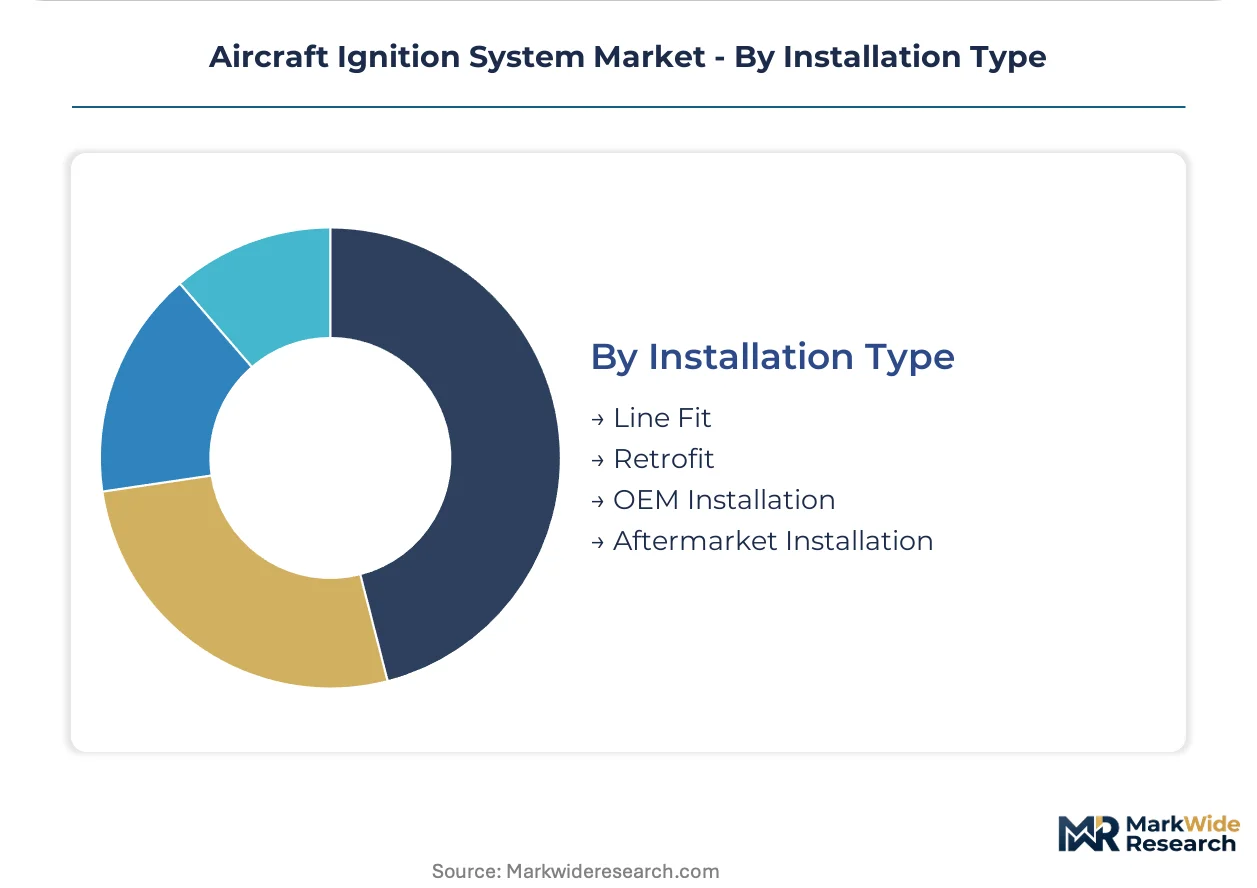
Installation Type:
Customer type segmentation separates OEM production line economics from aftermarket service center margin capture.
- Line Fit:Factory-installed ignition systems integrate with engine manufacturer's production schedules and warranty terms. Pratt & Whitney Canada and Honeywell turbine programs specify line-fit exciters.
- Retrofit:Supplemental type certificate modifications enable electronic ignition upgrades to in-service aircraft. United States STC holders like Electroair and SureFly target Cessna 172 and Piper Archer training fleets.
- OEM Installation:Engine manufacturer-directed procurement channels concentrate volume for new production platforms. Lycoming and Continental Motors specify ignition system suppliers in engine type certificates.
- Aftermarket Installation:Part 145 repair stations and independent maintenance facilities capture recurring magneto overhaul and harness replacement demand. Aging United States general aviation fleets sustain channel volume.
Revenue concentration sits with Aftermarket Installation. Retrofit channels are climbing the fastest as 100LL phase-out accelerates fleet modifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita, Kansas anchors the global aircraft ignition system supply base through dense concentrations of general aviation manufacturers and FAA-certified component suppliers. Regional procurement patterns diverge sharply between mature North American aftermarket channels and emerging Asian production hubs.
United States
General aviation retrofit activity and military platform upgrades sustain the largest national procurement volume for magneto and electronic ignition systems. FAA airworthiness directives mandate recurring magneto replacement intervals for aging Cessna and Piper fleets. Wichita, Kansas and Phoenix, Arizona host dense clusters of Part 145 repair stations capturing aftermarket harness and spark plug replacement cycles.
Germany
Regional turboprop operators under EASA jurisdiction accelerate electronic ignition retrofits to meet tightening emissions standards for ATR and De Havilland Canada platforms. The country's national aviation regulator enforces certification requirements that align with EU Green Deal decarbonization timelines. Bavaria's aerospace engineering corridor around Munich concentrates system integration expertise for European retrofit programs.
France
Helicopter ignition system demand from Airbus Helicopters and Safran propulsion programs drives specialized exciter procurement for turbine applications. EASA certification standards govern electromagnetic compatibility testing for solid-state ignition architectures. The Provence-Alpes-Côte d'Azur region around Marseille hosts maintenance facilities serving Mediterranean offshore and emergency medical rotorcraft fleets.
United Kingdom
Military platform modernization across RAF tactical turboprop fleets funds electronic ignition retrofits for improved fuel efficiency and reduced logistics footprints. The country's national aviation regulator maintains alignment with NATO dual-source qualification requirements for critical ignition components. The Midlands aerospace cluster around Birmingham sustains magneto overhaul capabilities for legacy training aircraft.
Japan
Domestic general aviation operators and regional turboprop fleets drive steady demand for ignition system replacements and upgrades. METI industrial policy supports technology transitions toward solid-state architectures in collaboration with propulsion system manufacturers. The Nagoya aerospace manufacturing corridor concentrates supplier relationships with Pratt & Whitney Canada and Honeywell turbine programs.
Aircraft Ignition System Market Vendor Landscape
Global majors compete with regional champions across certification capabilities and aftermarket service networks, producing a tiered structure where FAA Parts Manufacturer Approval holders command premium positioning. The vendor base separates into three strategic archetypes: vertically integrated aerospace conglomerates with captive ignition divisions, specialized ignition system houses with deep FAA certification expertise, and aftermarket-focused overhaul specialists with distributed repair station networks. Competitive moves concentrate on strategic partnerships for dual-source military qualification and geographic expansion through Part 145 repair station acquisitions.
Within the specialized ignition tier, Champion Aerospace, Unison Industries, and Hartzell Engine Technologies exemplify contrasting strategic positions. Champion Aerospace occupies a position anchored by in-house ceramic processing capabilities that control material costs across aviation spark plug portfolios. Unison Industries sits within the military-qualified supplier segment, representing dual-source exciter strategies that protect against supply disruption in defense procurement programs. Hartzell Engine Technologies exemplifies the aftermarket-focused archetype, anchoring market presence through FAA-certified magneto overhaul capabilities that general aviation operators depend upon for regulatory compliance.
| Leading Market Players |
|---|
| Hartzell Engine Technologies |
| Electroair |
| Champion Aerospace |
| Air Power Inc. |
| SureFly |
| TransDigm Group |
| Unison Industries |
| Sky Dynamics |
| Tempest Aero Group |
| Others |
Supply Flow & Price Mechanics
EPA 100LL aviation gasoline phase-out mandates gate both qualified supply and premium-tier pricing access, as ignition system manufacturers must recalibrate spark timing maps and electrode materials for unleaded formulations before capturing OEM line-fit contracts or aftermarket retrofit premiums.
Pricing Analysis
Input-cost pass-through from specialized cobalt and nickel alloys runs through spark plug electrode pricing, with African and Russian mining concentration squeezing raw material cost structures. Three-tier pricing structure across FAA-certified premium, standard commercial, and economy training-aircraft tiers separates certification grade from volume scale. Cost compression in the magneto overhaul segment is intensifying because independent Part 145 repair stations compete for aging Cessna and Piper fleet contracts. Training aircraft operators exhibit highest price sensitivity, while military dual-source programs demonstrate lowest sensitivity due to supply security mandates.
Supply Chain Analysis
Ceramic insulator supply rests on Japanese and German specialty materials producers controlling silicon nitride processing capabilities. Spark plug electrodes draw from Congolese cobalt, Russian nickel, and Chinese rare earth processing. Single-source vulnerability concentrates in FAA Parts Manufacturer Approval holders for electronic ignition exciters. Distribution runs through Wichita, Kansas and Phoenix, Arizona repair station clusters for general aviation aftermarket, with OEM line-fit channels anchored by Pratt & Whitney Canada and Honeywell turbine programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft ignition system procurement functions as a geographic-arbitrage play, with FAA certification timelines compressing product launch windows in the United States while EASA emissions standards accelerate technology transitions in Germany and France at differential compliance costs.
For Market Incumbents: Extend aftermarket service center networks through Part 145 repair station acquisitions in the United States general aviation corridor, defending against independent magneto overhaul specialists. Deepen backward integration into silicon nitride ceramic processing to control material costs as Champion Aerospace has demonstrated. Prioritize dual-source exciter qualification for NATO military programs to lock in defense procurement volumes.
For New Entrants and Emerging Players: Capture supplemental type certificate pathways for electronic ignition retrofits in Cessna 172 and Piper Archer training fleets, the most penetrable segment as 100LL phase-out accelerates. Target urban air mobility range-extender turbine applications through specialized ignition timing for hybrid-electric architectures. Lead with STC-holder partnerships to bypass OEM line-fit barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among aftermarket-focused magneto overhaul specialists with distributed Part 145 networks. Long-term viability hinges on electronic ignition transition economics across the analysis window. Watch EPA unleaded avgas implementation pace as the inflection indicator for retrofit market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Military Qualification | Protects NATO supply security while capturing defense procurement volumes. |
| Silicon Nitride Ceramic Integration | Extends spark plug service intervals above 1,200°C thermal loads. |
| STC Pathway Development | Enables electronic ignition retrofits for Cessna and Piper training fleets. |
| Part 145 Network Expansion | Captures recurring magneto overhaul demand in Wichita and Phoenix clusters. |
| Unleaded Fuel Timing Recalibration | Preserves power output as EPA 100LL phase-out accelerates. |
Methodological Framework
Multiple input streams — FAA certification database analysis, EASA emissions compliance filings, and NATO procurement records — were reconciled with primary interviews across ignition system engineering directors, Part 145 repair station operators, military procurement officers, and turbine OEM platform managers. Secondary validation drew from FAA airworthiness directive archives, EPA regulatory dockets, customs trade data for cobalt and nickel alloys, and SEC filings from TransDigm Group and Hartzell Engine Technologies. Bottom-up unit economics for spark plug replacement cycles and top-down fleet size projections were triangulated across the analysis window.
Data-stream reconciliation anchored volume and value outputs across product type, installation channel, end user, and technology segmentation dimensions. CAGRs were derived from installed base attrition rates, retrofit penetration curves, and OEM production schedules. Industry-specific forecast inputs included general aviation fleet age distributions, military platform modernization timelines, and unleaded aviation gasoline transition pace assumptions.
Regulatory implementation delays, raw material supply disruptions, and electronic ignition certification timeline extensions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about EPA 100LL phase-out adherence and EASA emissions standard enforcement. A small set of named triggers — FAA Parts Manufacturer Approval backlog, cobalt price volatility, and urban air mobility platform adoption — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Aviation Gas Turbine Market
Aircraft Engine Systems and Services
Aircraft Engine Nacelle Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
America Aircraft Engines Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Angle of Attack Sensor Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market