
 Aircraft Electronic Ignition System Market | 2026-2036
Aircraft Electronic Ignition System Market Size, Share, and Industry Trends Forecast 2026-2036
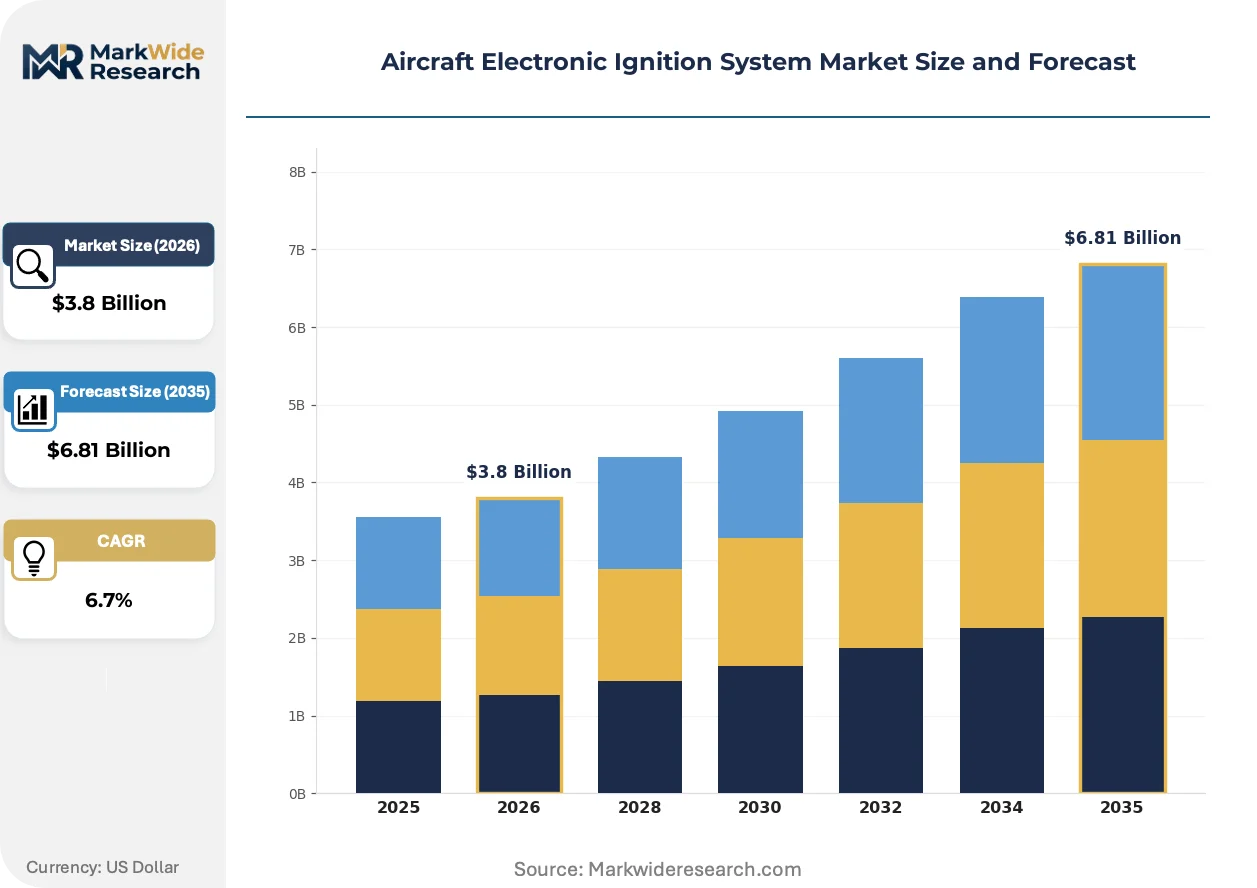
Aircraft Electronic Ignition System Market Outlook
Consolidation among general aviation fleet operators is repositioning procurement leverage toward larger maintenance networks and flight schools. Hartzell Engine Technologies leverages its vertically integrated magneto-to-ignition product pipeline to capture retrofit contracts. TransDigm Group anchors aftermarket pricing power through proprietary ignition lead and exciter portfolios. Woodward competes on digital exciter technology leadership for turbine ignition applications.
An aircraft electronic ignition system replaces mechanical magneto assemblies with solid-state or capacitive-discharge circuits that deliver precisely timed, high-energy sparks to aviation piston and turbine engines. These systems typically operate at excitation voltages between 12 and 24 volts DC, with solid-state designs eliminating mechanical breaker points to reduce maintenance intervals and improve combustion consistency. Dual spark configurations dominate commercial aviation installations where redundancy mandates twin independent ignition channels per cylinder bank. Digital technology is displacing analog architectures across OEM and retrofit channels as engine control units integrate ignition timing with full-authority digital engine control logic. Solid-state product lines are capturing margin pools in the UAV segment where weight reduction and electromagnetic interference resilience outweigh legacy certification burdens.
FAA airworthiness directives and EASA CS-E engine certification standards are mandating higher spark energy thresholds and electromagnetic compatibility testing for electronic ignition replacements. EPA regulations on leaded aviation gasoline are indirectly accelerating electronic ignition adoption by forcing combustion efficiency improvements that reduce tetraethyl lead dependence. Stakeholders must monitor pending FAA policy on unleaded avgas transition timelines and position supply chains for concurrent ignition system upgrade cycles.
Market Dynamics
General aviation fleet operators are consolidating maintenance networks, concentrating procurement leverage toward larger service providers capable of managing fleet-wide ignition retrofit programs at scale.
Growth Catalysts
- FAA Airworthiness Directives:Mandates for higher spark energy thresholds in electronic ignition replacements are forcing magneto-to-solid-state upgrades across Part 23 certified aircraft.
- EPA Leaded Avgas Regulations:Combustion efficiency requirements are indirectly accelerating electronic ignition adoption as operators seek reduced tetraethyl lead dependence.
- United States Fleet Density:Piston-engine concentration and active Part 23 retrofit activity create concentrated demand pull for aftermarket electronic ignition systems.
Market Restraints
- Specialized Component Supply Concentration:High-voltage capacitors and solid-state switching devices rely on limited semiconductor fabrication capacity concentrated in East Asian supply chains.
- EASA CS-E Certification Friction:Electromagnetic compatibility testing requirements for engine certification create extended validation timelines for new electronic ignition entrants.
- Magneto System Substitution Inertia:Legacy magneto assemblies remain technically viable for non-commercial operations, creating price-based competition for basic ignition functions.
Strategic Opportunities
- UAV Segment Electrification:Weight reduction and electromagnetic interference resilience priorities in unmanned aerial vehicle platforms favor solid-state ignition architectures over legacy certification-burdened alternatives.
- Digital-Analog Convergence:Integration of ignition timing with full-authority digital engine control logic creates upgrade pathways for analog-equipped turbine installations.
- Flight School Fleet Modernization:High-utilization training aircraft operators represent concentrated retrofit demand for fuel efficiency gains from electronic ignition conversion.
Industry Challenges
- Avionics-Electrical Integration Complexity:Solid-state ignition systems require specialized troubleshooting expertise that legacy A&P mechanics trained on mechanical magneto systems often lack.
- Dual-Channel Redundancy Validation:Commercial aviation twin independent ignition channel mandates per cylinder bank extend certification testing protocols and engineering resource requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Electronic Ignition System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Spark, Dual Spark, Transistor Ignition, Solid State Technology: Capacitive, Inductive, Analog, Digital End User: OEMs, Aftermarket Providers, Maintenance Facilities, Aviation Schools Application: Commercial Aviation, General Aviation, Military Aviation, UAVs |
| Companies Covered | Champion Aerospace, Hartzell Engine Technologies, TransDigm Group, Electroair, G3i, SureFly, Unison Industries, Woodward, Meggitt PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Electronic Ignition System Market Strategic Shifts
Solid-state architectures are compressing maintenance intervals while digital exciter technology redefines timing precision standards across piston and turbine engine categories.
Capacitive-discharge ignition circuits are electrifying spark delivery in high-performance piston engines by replacing mechanical breaker points with precisely timed electronic switching. Experimental and homebuilt aircraft builders are adopting these systems at accelerating rates. The technology is electrifying competitive positioning among aftermarket suppliers by establishing performance differentiation beyond legacy magneto reliability benchmarks.
EU REACH chemical substance restrictions are tightening material composition requirements for ignition system components containing heavy metals or persistent organic pollutants. Manufacturers must reformulate encapsulants and conductor coatings to maintain CE marking eligibility. Turbine ignition exciter suppliers serving European-registered aircraft face the most immediate material qualification burdens.
Maintenance network consolidation is compressing supplier negotiation cycles as larger fleet operators demand volume pricing and standardized ignition system configurations across mixed aircraft types. Independent maintenance shops are losing access to major retrofit contracts. The United States exhibits the most visible channel restructuring as regional flight school chains and fractional ownership programs centralize procurement decisions.
Aircraft Electronic Ignition System Market Segmentation
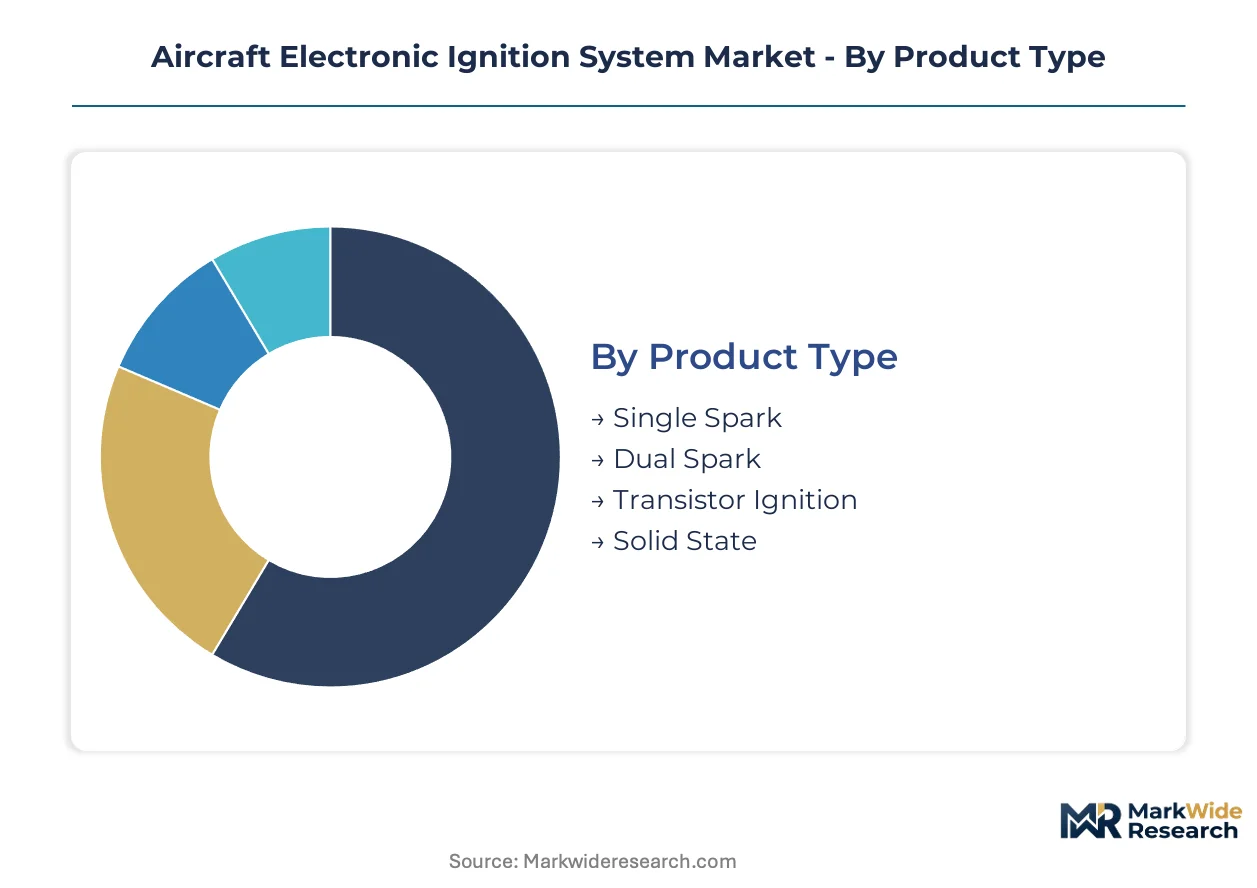
Electronic ignition procurement patterns diverge sharply between turbine OEMs seeking integrated digital architectures and general aviation operators prioritizing retrofit economics. Understanding these segment boundaries clarifies where technology premiums command pricing power versus where cost competition dominates.
Product Type:
Buyers differentiate primarily by redundancy requirements and maintenance interval expectations rather than initial hardware cost.
- Dual Spark:Twin independent ignition channels per cylinder bank deliver the redundancy mandated by FAA Part 23 and EASA CS-E for commercial piston operations. Demand concentrates among United States-based charter operators and flight school fleets where dispatch reliability directly affects revenue. FAA airworthiness directives on spark energy thresholds are accelerating magneto-to-dual-spark conversions in high-utilization aircraft.
- Solid State:Semiconductor-based switching eliminates mechanical breaker points entirely, compressing maintenance intervals from hundreds to thousands of flight hours. UAV manufacturers in the United States and experimental aircraft builders represent the fastest-expanding demand pool, as electromagnetic interference resilience and weight reduction outweigh legacy certification burdens.
- Single Spark:Basic configurations serve non-commercial experimental and light-sport aircraft where regulatory redundancy mandates do not apply.
- Transistor Ignition:Intermediate architectures bridge analog magneto systems and fully solid-state designs, finding niche adoption in vintage aircraft restoration projects.
Dual spark leads volumes today; solid state is gaining share fastest.
Technology:
Technology selection tracks engine control integration depth, with digital architectures commanding premiums where full-authority digital engine control logic is standard.
- Digital:Microprocessor-controlled timing integrates ignition sequencing with fuel injection and propeller governing through unified engine control units. Turbine OEMs in the United States and European commercial aviation sectors specify digital exciters exclusively for new production. EASA electromagnetic compatibility testing requirements extend validation timelines but lock in incumbent supplier relationships.
- Capacitive:High-voltage discharge circuits store energy in capacitors rather than induction coils, enabling precise spark timing at high compression ratios. High-performance piston engine builders and racing aviation applications in the United States drive concentrated demand for this technology's combustion efficiency advantages.
- Analog:Legacy transistor-transistor logic and discrete component designs persist in magneto retrofit applications where certification grandfathering reduces requalification costs.
- Inductive:Traditional coil-based energy storage dominates lowest-cost aftermarket replacements for mechanically timed ignition systems.
Digital platforms anchor OEM procurement; capacitive designs are climbing the fastest in aftermarket premium tiers.
End User:
End-user category determines procurement scale, with consolidated maintenance networks extracting volume pricing unavailable to fragmented independent operators.
- Maintenance Facilities:FAA-certified repair stations and EASA Part-145 organizations manage fleet-wide retrofit programs for regional operators and flight school chains. United States-based networks with ten-plus locations centralize procurement decisions and demand standardized ignition configurations across mixed aircraft types.
- OEMs:Airframe and engine manufacturers specify ignition systems during type certification, locking in supplier relationships through production runs lasting decades. Pratt & Whitney, Textron Aviation, and Cirrus Aircraft procurement teams in the United States negotiate multi-year supply agreements with exciter and lead manufacturers.
- Aftermarket Providers:Independent distributors and parts brokers serve owner-operated aircraft where single-unit purchases predominate.
- Aviation Schools:High-utilization training fleets prioritize fuel efficiency gains from electronic ignition conversion to offset operating hour economics.
Maintenance facilities lead current volume; aviation schools are expanding procurement most quickly as fleet modernization accelerates.
Application:
Application scope dictates certification burden and technology performance thresholds, with commercial aviation demanding redundant channel validation absent in experimental categories.
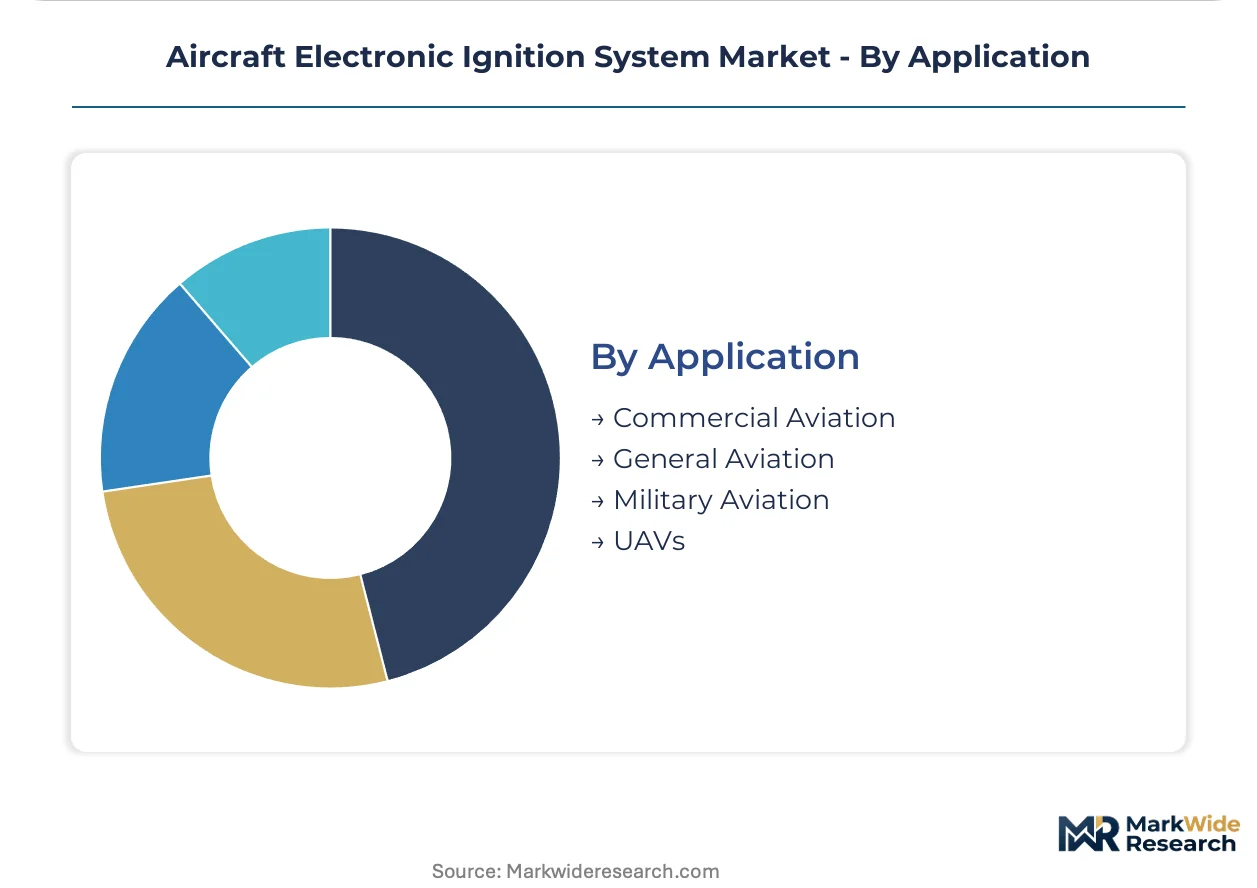
- General Aviation:Piston-engine aircraft operating under Part 23 certification constitute the largest installed base for electronic ignition retrofit. United States fleet density and active magneto replacement cycles concentrate demand in this segment. EPA regulations on leaded avgas are indirectly forcing combustion efficiency investments that favor electronic ignition adoption.
- UAVs:Unmanned platforms prioritize weight reduction and electromagnetic resilience over legacy certification compliance, enabling solid-state architectures to capture design wins without FAA Part 33 engine certification burdens. United States defense contractors and commercial drone operators are electrifying procurement for military and agricultural applications.
- Commercial Aviation:Turbine-powered regional jets and business aircraft require digital exciter technology integrated with full-authority digital engine control systems.
- Military Aviation:Department of Defense specifications for electromagnetic pulse hardening and extreme environment operation create specialized procurement channels.
General aviation dominates installed base; UAV applications are expanding most steeply as platform electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains substantially higher piston-engine fleet density than Germany, yet both markets exhibit divergent regulatory pressures reshaping electronic ignition procurement patterns across their respective aviation sectors.
United States
Part 23 retrofit activity and flight school fleet modernization concentrate demand in Florida, Texas, and Arizona training corridors. FAA airworthiness directives on spark energy thresholds mandate magneto-to-solid-state conversions for high-utilization aircraft. Oklahoma and Kansas maintenance networks centralize procurement decisions for regional operator chains seeking standardized ignition configurations.
Germany
General aviation operators prioritize EASA CS-E electromagnetic compatibility compliance for turbine ignition upgrades. EU REACH chemical restrictions force reformulation of encapsulants and conductor coatings in Baden-Württemberg manufacturing clusters. Bavaria's engine component suppliers face extended validation timelines that lock in incumbent exciter manufacturer relationships.
United Kingdom
London-area charter operators and Oxford-Cambridge flight training networks drive dual-spark redundancy demand for commercial piston operations. EASA certification alignment post-Brexit creates parallel compliance pathways for ignition system suppliers. Midlands aerospace clusters specialize in legacy magneto refurbishment alongside electronic ignition distribution.
France
Toulouse and Bordeaux regional aviation hubs exhibit concentrated turbine OEM procurement for digital exciter technology. ANSM oversight of aviation equipment imports adds regulatory friction for non-European ignition suppliers. Île-de-France maintenance facilities consolidate fleet-wide retrofit programs for corporate aircraft operators.
Canada
Prairie province flight schools and British Columbia charter operators pursue electronic ignition conversions to offset leaded avgas cost pressures. Transport Canada certification reciprocity with FAA standards accelerates US-supplied system adoption. Ontario maintenance networks serve cross-border general aviation fleets operating under dual regulatory frameworks.
Aircraft Electronic Ignition System Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the electronic ignition value chain, creating a tiered structure where scale advantages clash with retrofit agility. The market consolidates around exciter manufacturing and ignition lead production as distinct capability nodes. Three archetypes dominate: vertically integrated engine component suppliers, specialized ignition technology developers, and diversified aerospace electronics conglomerates. Competitive dynamics center on backward integration into semiconductor switching devices and strategic partnerships with UAV platform developers.
Among US-based suppliers, Champion Aerospace, Hartzell Engine Technologies, and TransDigm Group occupy positions across different value chain segments. Champion Aerospace exemplifies the dedicated ignition component archetype with concentrated product portfolios. Hartzell Engine Technologies represents backward-integrated specialists controlling magneto-to-electronic conversion pathways. TransDigm Group anchors the diversified aerospace electronics tier with proprietary aftermarket pricing structures. These three entities collectively illustrate how geographic clustering in Ohio, Illinois, and Connecticut correlates with distinct competitive positioning strategies.
| Leading Market Players |
|---|
| Champion Aerospace |
| Hartzell Engine Technologies |
| TransDigm Group |
| Electroair |
| G3i |
| SureFly |
| Unison Industries |
| Woodward |
| Meggitt PLC |
| Others |
Value Chain & Pricing Dynamics
Captive semiconductor fabrication capacity in East Asian supply chains anchors both input security and pricing power for high-voltage capacitor and solid-state switching device suppliers serving electronic ignition manufacturers. FAA and EASA certification burdens create natural price stratification between qualified incumbent exciter producers and unqualified entrants, while maintenance network consolidation in the United States extracts volume discounts that compress margins for aftermarket distributors.
Pricing Analysis
Capacity additions in South Korean and Taiwanese semiconductor foundries are reshaping price floors for solid-state ignition components by expanding high-voltage switching device availability. Three-tier pricing structure across OEM-certified, aftermarket-approved, and experimental-tier products reflects FAA Part 33 certification investment differentials. Cost compression in the experimental aircraft segment runs through direct-to-builder sales channels that bypass traditional distribution markups. Flight school chains with fleet-wide retrofit programs exhibit lowest price sensitivity due to fuel efficiency payback calculations, while individual owner-operators drive hardest bargain on single-unit magneto replacements.
Supply Chain Analysis
Regional distribution centers in Ohio, Illinois, and Connecticut maintain hub-and-spoke patterns for ignition lead and exciter fulfillment to FAA-certified repair stations across the United States. Manufacturing concentration in the United States, Germany, and China feeds from specialized high-voltage capacitor production in Japan and South Korea. Single-source vulnerability around silicon carbide switching devices creates procurement risk for solid-state ignition producers seeking dual qualification. Distribution runs through OEM direct contracts for turbine installations and independent aftermarket channels for general aviation retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic ignition procurement arbitrage opportunities emerge between United States flight school consolidation and European EASA CS-E certification backlogs, where regulatory friction differential creates margin capture potential for suppliers with dual qualification.
For Market Incumbents: Hedge against solid-state substitution acceleration by deepening backward integration into semiconductor switching devices while maintaining magneto refurbishment capabilities for legacy fleet lock-in. FAA airworthiness directive timelines on spark energy thresholds represent the priority lever for forcing fleet-wide upgrade commitments before competitive entrants achieve certification. Channel control through exclusive repair station partnerships defends pricing power against independent distributor erosion. For New Entrants and Emerging Players: Capture UAV platform design wins where electromagnetic resilience requirements favor solid-state architectures absent legacy FAA Part 33 burdens. Experimental aircraft builders in the United States represent the most penetrable segment due to minimal certification overhead and direct-to-builder sales channel viability. Technical partnership with agricultural drone OEMs offers fastest go-to-market pathway outside established aviation supplier networks. For Investors and Strategic Acquirers: Roll-up economics work for specialized ignition component suppliers because maintenance network consolidation creates procurement leverage that favors scaled providers with standardized product portfolios. Five-to-ten year viability hinges on unleaded avgas transition timeline execution and concurrent ignition system upgrade cycle synchronization. Monitor FAA policy announcements on leaded fuel phase-out as primary inflection signal for retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Backward Integration | Captive high-voltage switching device production secures supply against East Asian fabrication constraints. |
| EASA CS-E Dual Certification Investment | Electromagnetic compatibility qualification unlocks European turbine OEM procurement channels. |
| UAV Platform Partnership Program | Defense contractor design wins bypass legacy aviation certification barriers for solid-state adoption. |
| Flight School Fleet Retrofit Contracting | Volume agreements with consolidated training networks capture fuel efficiency upgrade cycles. |
| Digital Exciter Technology Licensing | Full-authority digital engine control integration partnerships with turbine OEMs lock in long-term supply. |
Study Parameters
Bottom-up general aviation fleet modeling reconciled against top-down exciter production tracking forms the analytical core of this study. Primary interviews with FAA-certified repair station managers, OEM procurement directors, UAV platform engineers, and aftermarket distribution executives combined with secondary validation from FAA airworthiness directive filings, EASA CS-E certification databases, and EPA regulatory dockets. Customs records for high-voltage capacitor imports and semiconductor trade data complete the supply-side triangulation against maintenance network demand surveys.
Historical trendline analysis of magneto replacement cycles and electronic ignition adoption rates across piston-engine fleet segments establishes baseline growth patterns over the projection horizon. Segmentation modeling incorporates product type redundancy requirements, technology architecture migration paths, end-user procurement consolidation patterns, and application-specific certification burdens. CAGRs derive from fitted growth curves adjusted for regulatory mandate acceleration effects and fleet age distribution dynamics. Unleaded avgas transition policy uncertainty and UAV electrification penetration curves represent key forecast sensitivity inputs.
FAA regulatory delay, EASA certification timeline extension, and semiconductor supply disruption are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding fleet replacement rates and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Global Aircraft Micro Turbine Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Aerospace Electrical Inserts Market
Aircraft Power Systems
Aerospace and Military Auxiliary Power Unit (APU) Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Aircraft Battery Market
Aircraft Power Systems
UAV Propulsion System Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Military Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Aircraft Thrust Reverser Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market