
 Aircraft Landing Gear Repair and Overhaul Market | 2026-2036
Aircraft Landing Gear Repair and Overhaul Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Landing Gear Repair and Overhaul Market Analysis
A shift from captive in-house maintenance toward outsourced multi-source contracts is pivoting procurement strategy across airline fleets. Lufthansa Technik AG leverages its European base and OEM partnerships to anchor high-value overhaul work. AAR Corporation competes through distributed service networks across North American military and commercial segments. ST Engineering Aerospace specializes in Asia-Pacific turnaround capabilities with Singapore-based heavy maintenance infrastructure.
Aircraft landing gear repair and overhaul encompasses the inspection, refurbishment, and restoration of undercarriage assemblies including shock struts, actuators, wheels, and brakes to restore airworthiness after operational fatigue cycles. The process involves non-destructive testing, chrome plating, seal replacement, and dynamic retraction testing to ensure structural integrity and performance within OEM tolerance specifications. Overhaul services command the largest revenue pool due to mandatory interval-driven demand and labor-intensive teardown protocols. Repair work on wheels and brakes shows faster volume expansion as high-cycle regional jet operations accelerate component wear. Military operator end users sustain premium pricing through specialized certification requirements and security-cleared labor pools.
FAA airworthiness directives and EASA continuing airworthiness program regulations tighten inspection mandates and documentation standards for landing gear overhaul providers. ISO quality management certifications and OEM approvals function as gatekeeping mechanisms that restrict market access to qualified facilities. Stakeholders must monitor evolving regulatory harmonization between FAA and EASA standards while assessing capital deployment toward additive manufacturing qualifications for non-critical component repair.
Market Dynamics
Fleet renewal cycles at low-cost carriers and military operators are compressing turnaround time requirements for landing gear overhaul providers, forcing infrastructure investments in automated inspection lines and distributed service networks.
Growth Catalysts
- FAA Airworthiness Directives:Mandated inspection interval reductions for high-cycle landing gear assemblies create recurring revenue pools for approved overhaul facilities.
- Additive Manufacturing Qualification:Powder-bed fusion processes for non-critical bracket and housing repairs reduce lead times and material waste in component restoration workflows.
- Southeast Asia Narrow-Body Expansion:Low-cost carrier fleet growth in Indonesia, Vietnam, and the Philippines drives outsourcing volumes to Singapore-based heavy maintenance clusters.
Market Restraints
- Specialized Labor Scarcity:Security-cleared technicians with NDT Level III certifications command wage premiums that compress margin structures at independent overhaul shops.
- OEM Parts Monopoly:Proprietary seal kits and chrome-plating specifications lock repair providers into single-source supply agreements with landing gear manufacturers.
- Capital Equipment Intensity:Dynamic retraction test rigs and automated shot-peening systems require seven-figure investments that deter market entry.
Strategic Opportunities
- India Defense Modernization:Indigenous fighter and transport aircraft programs create demand for domestic landing gear overhaul capability with offset localization requirements.
- Line-Replaceable Unit Exchange Pools:Pre-positioned component inventories at hub airports enable same-day turnaround for AOG scenarios, capturing premium pricing from cargo operators.
- EASA-CSRD Alignment:Sustainability reporting mandates for aviation MROs favor providers with carbon-accounted repair processes and circular material flows.
Industry Challenges
- Qualification Timeline Compression:OEM approval cycles for new repair processes extend 18-24 months, delaying revenue recognition on technical investments.
- Legacy Fleet Documentation Gaps:Incomplete maintenance histories for aging regional turboprops complicate damage tolerance assessments and airworthiness determinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Landing Gear Repair and Overhaul Market |
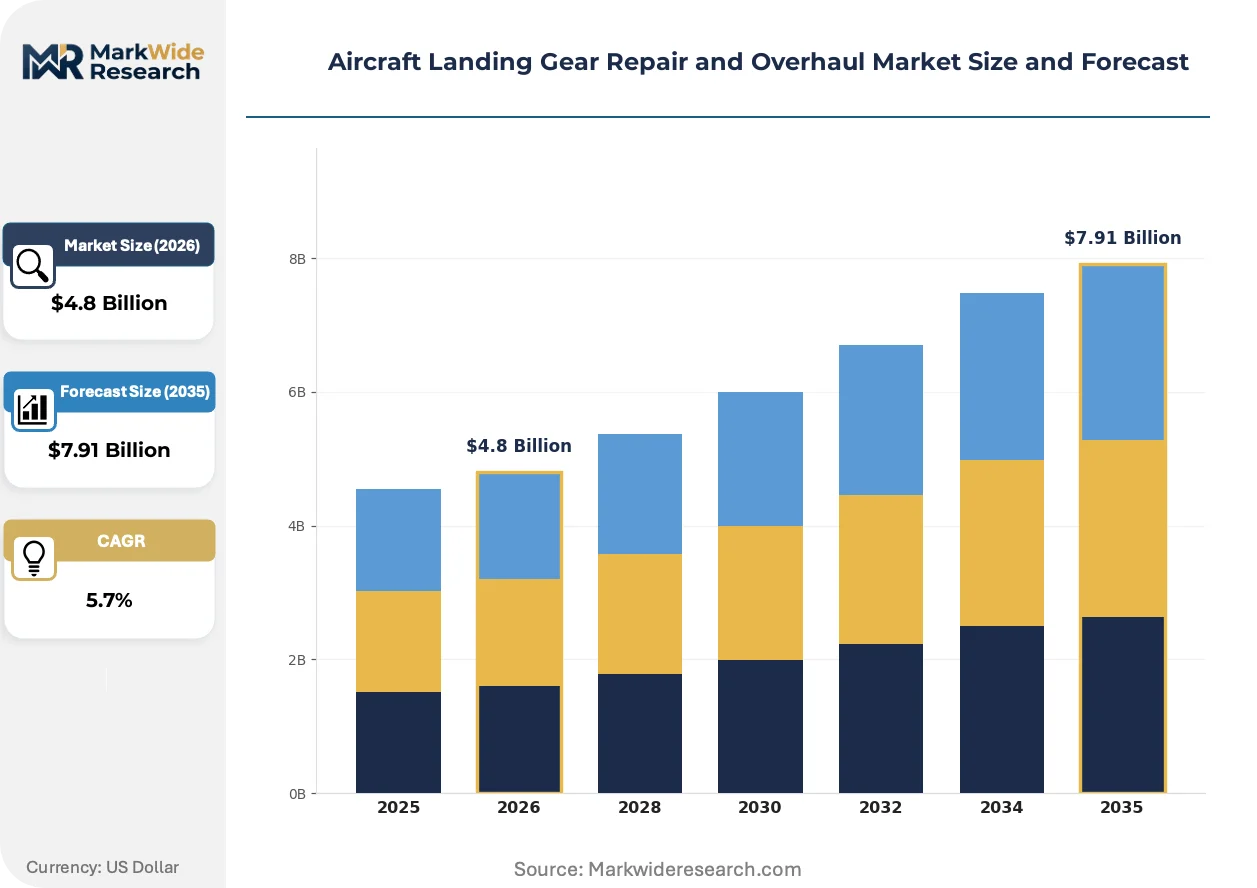
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Repair, Overhaul, Modification, Retrofitting End User: Commercial Airlines, Military Operators, Maintenance Repair Organizations, Private Jet Owners Component: Wheels, Brakes, Actuators, Shock Struts Certification: FAA, EASA, ISO, OEM |
| Companies Covered | REVIMA Group, Delta TechOps, Lufthansa Technik AG, ST Engineering Aerospace, HAECO Group, AAR Corporation, GA Telesis, Air France Industries KLM Engineering & Maintenance, Safran Landing Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Landing Gear Repair and Overhaul Market Emerging Trajectories
Digital thread technologies and predictive maintenance algorithms are rewriting how landing gear condition data flows between operators, MROs, and regulators, collapsing information asymmetries that once defined procurement negotiations.
Cold spray deposition is integrating solid-state coating restoration for magnesium alloy components without thermal distortion risks. Military overhaul facilities in the United States and Germany are qualifying these processes for flight-critical applications. The technology is integrating chromic-acid-free repair workflows that eliminate hexavalent chromium exposure liabilities while meeting OEM structural tolerance requirements.
EASA continuing airworthiness program amendments now require digital records interoperability between national aviation authorities and approved maintenance organizations. Repair stations must deploy blockchain-anchored documentation systems to satisfy audit trail mandates. European narrow-body operators face the steepest compliance costs, with German and French carriers consolidating supplier panels to reduce certification overhead.
Airlines are unbundling landing gear overhaul from full-service MRO contracts, awarding component-specific work to niche specialists with OEM approvals. Cargo operators at Memphis and Louisville hubs pioneered this model, selecting dedicated brake and wheel shops for high-frequency turnaround needs. The practice now spreads to passenger fleets in the United States seeking to compress induction-to-return intervals during peak summer scheduling windows.
Aircraft Landing Gear Repair and Overhaul Market Segmentation
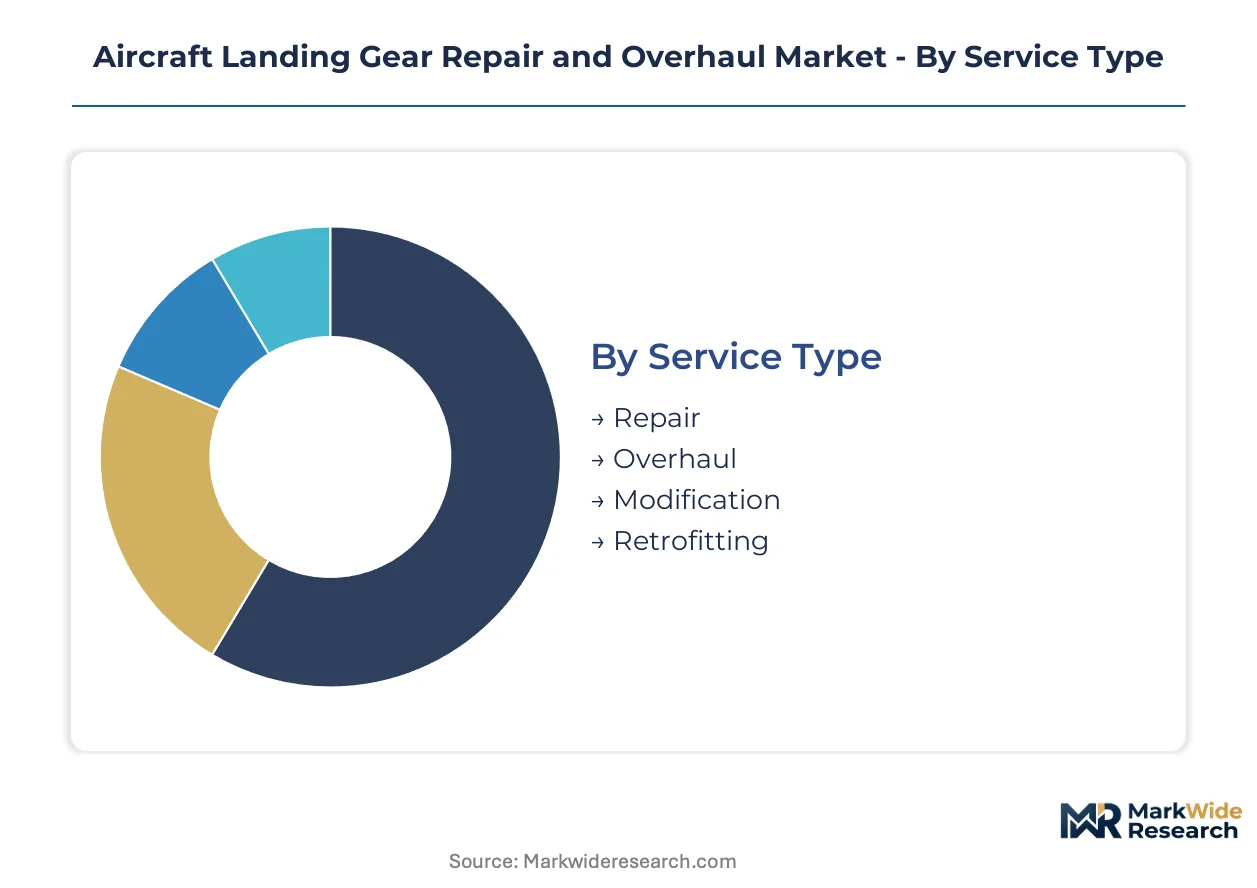
Segmentation in landing gear MRO reveals how procurement contracts bifurcate between mandatory overhaul intervals and discretionary repair events. Understanding these divisions exposes where pricing power concentrates and which technical qualifications gate market access.
Service Type:
Upgrade and replacement cycles vary dramatically across service tiers, with interval-driven mandates competing against condition-based interventions for capital allocation.
- Repair:Component-level restoration addresses localized fatigue, corrosion, or seal degradation without full assembly teardown. Wheels and brake units in high-cycle regional jet fleets drive volume concentration at Singapore and Frankfurt hub facilities.
- Overhaul:Complete disassembly, inspection, and recertification of landing gear assemblies to restore zero-time status. Mandatory intervals under FAA airworthiness directives sustain recurring revenue pools at approved stations in the United States and Germany.
- Modification:Structural or software alterations to accommodate operational changes or regulatory mandates.
- Retrofitting:Integration of upgraded components into legacy assemblies to extend service life or improve performance.
Volume placements concentrate in Overhaul; the faster expansion belongs to Repair.
End User:
Customer procurement sophistication spans captive in-house capabilities to fully outsourced multi-source contracts, with security clearance requirements fragmenting the competitive landscape.
- Commercial Airlines:Narrow-body low-cost carriers in Southeast Asia compress turnaround windows and unbundle component work from full-service MRO agreements. Fleet renewal cycles at Indonesia and Vietnam operators accelerate outsourcing volumes to Singapore-based heavy maintenance clusters.
- Military Operators:Specialized certification requirements and security-cleared labor pools sustain premium pricing structures. United States and German defense overhaul facilities command margins unavailable to commercial-focused competitors.
- Maintenance Repair Organizations:Third-party specialists with OEM approvals capture component-specific contracts unbundled from airline captive shops.
- Private Jet Owners:Dispersed demand with high service expectations and limited bargaining leverage against approved repair stations.
Procurement scale favors Commercial Airlines; Military Operators retain the steepest pricing premiums.
Component:
Component complexity and wear rates determine whether restoration occurs at line stations or requires heavy maintenance infrastructure with dynamic test capabilities.
- Wheels:High-frequency replacement items with standardized inspection protocols enabling distributed repair networks.
- Brakes:Heat-intensive wear components requiring specialized reline and torque testing equipment. Cargo operators at Memphis and Louisville hubs drive dedicated brake shop demand for same-day turnaround.
- Actuators:Precision hydraulic assemblies demanding clean-room teardown conditions and OEM-approved seal kits.
- Shock Struts:Chrome-plated structural elements with proprietary plating specifications locking providers into single-source supply agreements with landing gear manufacturers.
Turnaround velocity concentrates in Brakes; technical complexity peaks with Shock Struts.
Certification:
Regulatory and quality credentials function as gatekeeping mechanisms that restrict facility access and determine contract eligibility tiers.
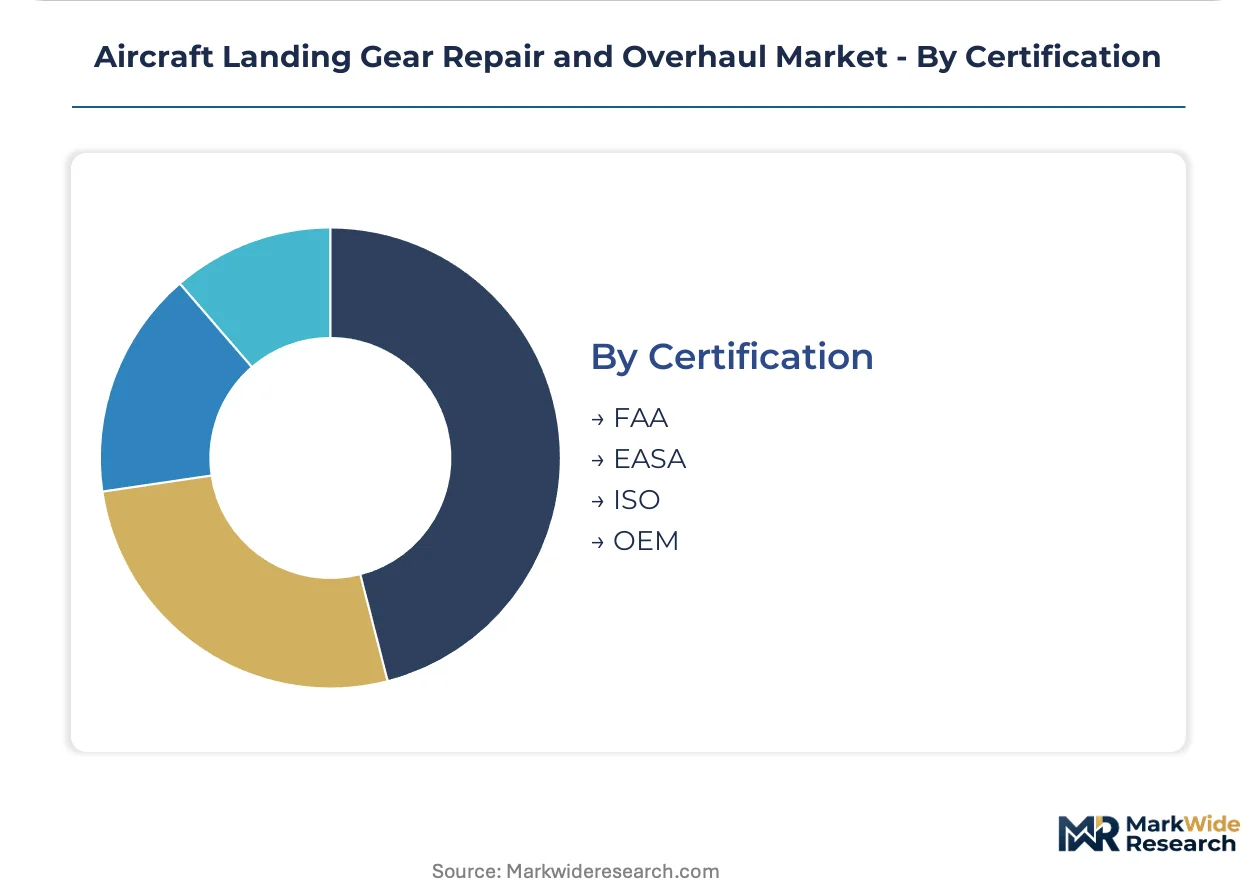
- FAA:United States federal airworthiness standards with airworthiness directive enforcement creating mandatory inspection demand.
- EASA:European continuing airworthiness program with digital records interoperability mandates under recent amendments. German and French carriers consolidate supplier panels to reduce certification overhead.
- ISO:Quality management certifications required as baseline qualification for OEM approval processes.
- OEM:Manufacturer-specific approvals for proprietary repair processes and component specifications. Approval cycles extend 18-24 months, delaying revenue recognition on technical investments.
Contract eligibility hinges on OEM approval; compliance cost burdens concentrate under EASA mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for landing gear overhaul services concentrates in three national clusters where military procurement, commercial fleet density, and regulatory stringency intersect. Singapore, Germany, and the United States host the dominant third-party heavy maintenance infrastructure.
United States
Military operator procurement sustains premium pricing at security-cleared facilities. FAA airworthiness directives mandate reduced inspection intervals for high-cycle assemblies. Memphis and Louisville cargo hubs drive dedicated brake shop demand for same-day turnaround services.
Germany
EASA continuing airworthiness program amendments tighten digital records interoperability requirements. German defense overhaul facilities command margins unavailable to commercial-focused competitors. Hamburg and Frankfurt anchor European heavy maintenance clusters with OEM-approved capabilities.
Singapore
Narrow-body fleet expansion among Indonesian and Vietnamese low-cost carriers accelerates outsourcing volumes. The country's national aviation regulator enforces alignment with EASA standards for approved maintenance organizations. Seletar Aerospace Park hosts ST Engineering Aerospace infrastructure for Asia-Pacific turnaround capabilities.
France
Air France Industries KLM Engineering & Maintenance leverages European base and OEM partnerships for high-value overhaul work. ANSM and CNIL oversight extends to aviation maintenance data governance under GDPR-aligned frameworks. Toulouse and Paris-Charles de Gaulle concentrate specialized landing gear capabilities near Airbus manufacturing.
United Kingdom
RAF procurement sustains domestic military overhaul demand with security-cleared labor requirements. The UK Civil Aviation Authority maintains bilateral recognition agreements with FAA and EASA for repair station approvals. London Stansted and Manchester host component-specific specialists unbundled from full-service MRO contracts.
Aircraft Landing Gear Repair and Overhaul Market Vendor Landscape
Strategic partnerships dominate the current landscape as providers seek OEM approvals and geographic reach without capital-heavy facility duplication. The vendor base organizes into three tiers: integrated airline-affiliated shops, independent third-party specialists, and OEM-captive service arms. Two archetypes define competitive positioning—European-based heavy maintenance anchors and Asia-Pacific turnaround specialists. M&A activity and distributed service network expansion represent the dominant competitive moves as firms compress induction-to-return intervals.
Within the integrated airline-affiliated tier, Lufthansa Technik AG and Air France Industries KLM Engineering & Maintenance exemplify European heavy maintenance anchors with OEM partnership structures. ST Engineering Aerospace occupies a position representing Asia-Pacific turnaround specialization. Among independent third-party specialists, AAR Corporation and REVIMA Group sit within the component-specific service archetype. Safran Landing Systems anchors the OEM-captive tier with proprietary repair process control.
| Leading Market Players |
|---|
| REVIMA Group |
| Delta TechOps |
| Lufthansa Technik AG |
| ST Engineering Aerospace |
| HAECO Group |
| AAR Corporation |
| GA Telesis |
| Air France Industries KLM Engineering & Maintenance |
| Safran Landing Systems |
| Others |
Supply Flow & Price Mechanics
Captive in-house maintenance operations at legacy carriers anchor supply positions for high-value overhaul work while simultaneously constraining pricing power for independent shops. OEM-captive service arms exploit proprietary seal kits and chrome-plating specifications to extract premium margins from third-party providers.
Pricing Analysis
Warranty and zero-time status guarantees bundle into overhaul contracts at premium tiers, while unbundled component repairs trade at compressed margins. Three-tier pricing structure across OEM-approved, EASA-certified, and baseline ISO-qualified facilities segments buyers by risk tolerance. Pricing pressure stems from low-cost carrier procurement teams consolidating supplier panels for narrow-body fleets. Cargo operators at Memphis and Louisville hubs exhibit lowest price sensitivity due to AOG urgency premiums.
Supply Chain Analysis
Certification gating through FAA and EASA approvals restricts qualified supplier pools to Singapore, Germany, and the United States. Chrome-plated shock struts, proprietary seal kits, and aerospace-grade magnesium alloys draw from single-source OEM agreements. Single-source vulnerability concentrates in proprietary plating specifications controlled by landing gear manufacturers. Distribution runs through hub-and-spoke networks anchored at Seletar Aerospace Park, Hamburg, and Oklahoma City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Additive manufacturing qualification is displacing legacy chromic-acid repair workflows, compressing lead times and eliminating hexavalent chromium exposure liabilities for early adopters.
For Market Incumbents: Hedge against cold spray deposition disruption by qualifying solid-state coating restoration processes before military facilities lock in preferred supplier status. Backward integration into powder-bed fusion capabilities secures margin defense against OEM parts monopolies on non-critical bracket repairs. EASA-CSRD alignment investments in carbon-accounted repair processes create differentiation as sustainability mandates tighten. For New Entrants and Emerging Players: The gap between premium military overhaul pricing and economy-tier commercial repair rates creates entry space for security-cleared facilities serving dual-use applications. India defense modernization programs with offset localization requirements offer the most penetrable geography for greenfield capability. Target component-specific brake and wheel contracts unbundled from full-service MRO agreements at cargo hub airports. For Investors and Strategic Acquirers: Exit pathways concentrate in OEM-captive acquisitions of independent specialists with FAA/EASA dual approvals. Long-term viability favors facilities with additive manufacturing qualifications and digital thread documentation capabilities. Watch for EASA-FAA regulatory harmonization announcements as inflection indicators for cross-border consolidation activity.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Qualification | Powder-bed fusion approval reduces OEM dependency for non-critical component repairs. |
| Cold Spray Deposition Certification | Solid-state coating restoration eliminates hexavalent chromium exposure at military facilities. |
| Digital Thread Documentation | Blockchain-anchored records satisfy EASA interoperability mandates for audit trail integrity. |
| Line-Replaceable Unit Exchange Pools | Pre-positioned inventories at Memphis and Louisville capture AOG premium pricing from cargo operators. |
| EASA-CSRD Carbon Accounting | Circular material flow reporting differentiates providers as sustainability mandates tighten for European carriers. |
Methodological Framework
Document review covered FAA airworthiness directive filings, EASA continuing airworthiness program amendments, and OEM repair process specifications, complemented by interviews with MRO operations directors, airline procurement executives, and defense overhaul program managers. Secondary validation drew from customs trade data, national aviation authority approval registries, and military procurement disclosures. Bottom-up facility capacity estimates triangulated against top-down fleet projection models.
Segment-level revenue outputs across service type, end user, component, and certification dimensions were generated through the analytical framework. CAGRs derived from regression analysis against fleet renewal cycles, regulatory interval compression rates, and outsourcing penetration trends. Forecast inputs incorporated narrow-body delivery schedules at Indonesian and Vietnamese low-cost carriers, plus military modernization timelines for indigenous fighter programs.
Inputs from EASA and FAA regulatory filings were available through the study window; gaps in proprietary OEM repair process documentation introduce uncertainty bands around qualification timeline assumptions. Forecasts reflect documented inspection interval mandates and documented fleet expansion plans. A model refresh is warranted upon material change in FAA-EASA regulatory harmonization progress or additive manufacturing approval acceleration at major OEMs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Training Market
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Middle-East Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
GCC Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market