
 Air Crane Helicopter Market | 2026-2036
Air Crane Helicopter Market Size, Share, and Industry Trends Forecast 2026-2036
Air Crane Helicopter Market Intelligence
Aftermarket fleet management subscriptions is restructuring how operators monetize air crane platforms beyond the initial airframe sale. Erickson Incorporated leverages its S-64 Aircrane proprietary data analytics to secure recurring revenue from firefighting agencies. Columbia Helicopters anchors the logging sector with its Vertol 107-II fleet, sustaining long-term contracts in the Pacific Northwest. Airbus Helicopters competes through H215 Super Puma variants optimized for construction support in alpine terrain.
An air crane helicopter is a rotary-wing aircraft engineered for external load operations, typically featuring twin-turboshaft engines generating 4,000–10,000 shaft horsepower and single-point cargo hook systems rated for 10,000–25,000 pounds. These platforms serve primary industrial functions including aerial firefighting, precision timber harvesting, and heavy equipment placement in remote construction sites. Heavy lift configurations command the largest revenue share due to irreplaceable payload requirements in infrastructure maintenance, while electric lift assistance technologies represent the fastest-evolving segment as hybrid propulsion trials reduce fuel burn during hover-intensive missions. Composite materials adoption is maturing across main rotor blades, shifting margin pools toward certified repair stations rather than original equipment manufacturers.
The FAA enforces Part 133 and Part 135 operational standards governing external load certification and crew rest limitations, directly shaping fleet availability and insurance premiums for contractors. EASA's CS-29 certification requirements for large rotorcraft impose design standards that filter market entry for European operators and OEMs serving energy companies in the North Sea. Stakeholders must monitor emerging urban air mobility regulations that could divert turboshaft engineering talent and composite manufacturing capacity toward competing aerial platforms.
Market Dynamics
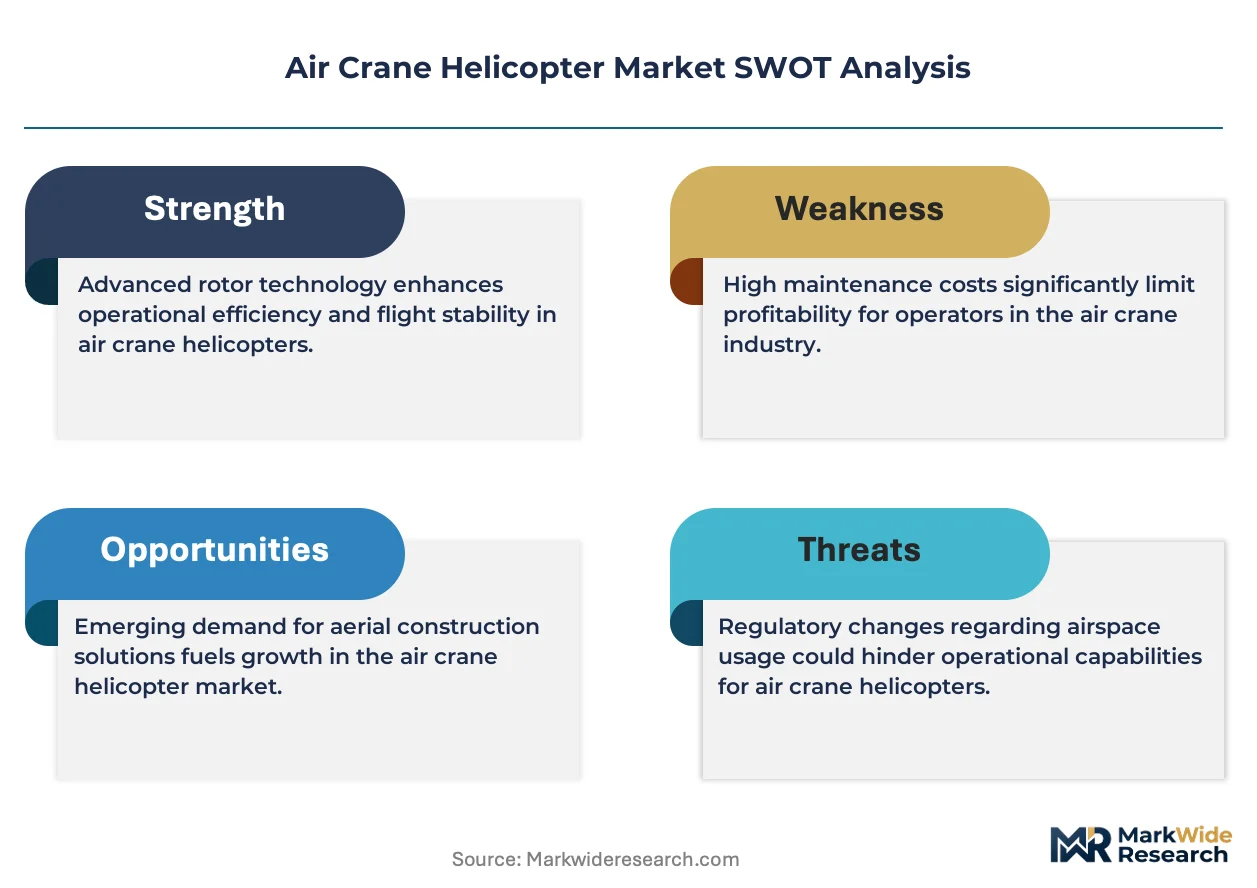
Composite rotor blade manufacturing is consolidating supply chains toward certified repair stations, diverting margin pools from original equipment manufacturers and forcing fleet operators to renegotiate long-term maintenance contracts.
Growth Catalysts
- FAA Part 133 Certification:Tightening external load operational standards in the United States is filtering out marginal operators and concentrating contract awards among certified heavy-lift specialists.
- Bushfire Suppression Contracts:Seasonal fleet utilization spikes in Australia are creating predictable revenue streams that justify capital deployment for specialized aerial firefighting configurations.
- Hybrid Propulsion Trials:Electric lift assistance technologies are reducing fuel burn during hover-intensive missions, extending operational endurance for timber extraction cycles in remote terrain.
Market Restraints
- Turboshaft Engine Supply Concentration:Limited qualified suppliers for 4,000–10,000 shaft horsepower powerplants creates procurement bottlenecks and extended lead times for fleet expansion.
- CS-29 Certification Barriers:EASA's large rotorcraft design standards impose capital-intensive compliance costs that restrict European market entry for specialized air crane operators.
- Fixed-Wing Aerial Tankers:Conventional firefighting aircraft offer lower per-gallon suppression costs for wide-area coverage, constraining air crane pricing power in bulk water delivery contracts.
Strategic Opportunities
- Alpine Construction Support:Heavy equipment placement in mountainous terrain across Switzerland and Austria remains underpenetrated due to limited certified high-altitude operators.
- Data Analytics Subscriptions:Fleet management software monetization is creating recurring revenue streams beyond initial airframe sales through predictive maintenance and mission optimization tools.
- Urban Air Mobility Talent Diversion:Turboshaft engineering expertise and composite manufacturing capacity are becoming available as eVTOL programs absorb adjacent aerospace skill pools.
Industry Challenges
- Part 135 Crew Rest Limitations:FAA-mandated duty time restrictions compress fleet availability during peak fire season, requiring redundant crew rotations that inflate labor costs.
- Single-Point Hook System Integration:Legacy timber harvesting infrastructure lacks standardized attachment interfaces, forcing custom engineering for each extraction site and extending mission preparation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Crane Helicopter Market |
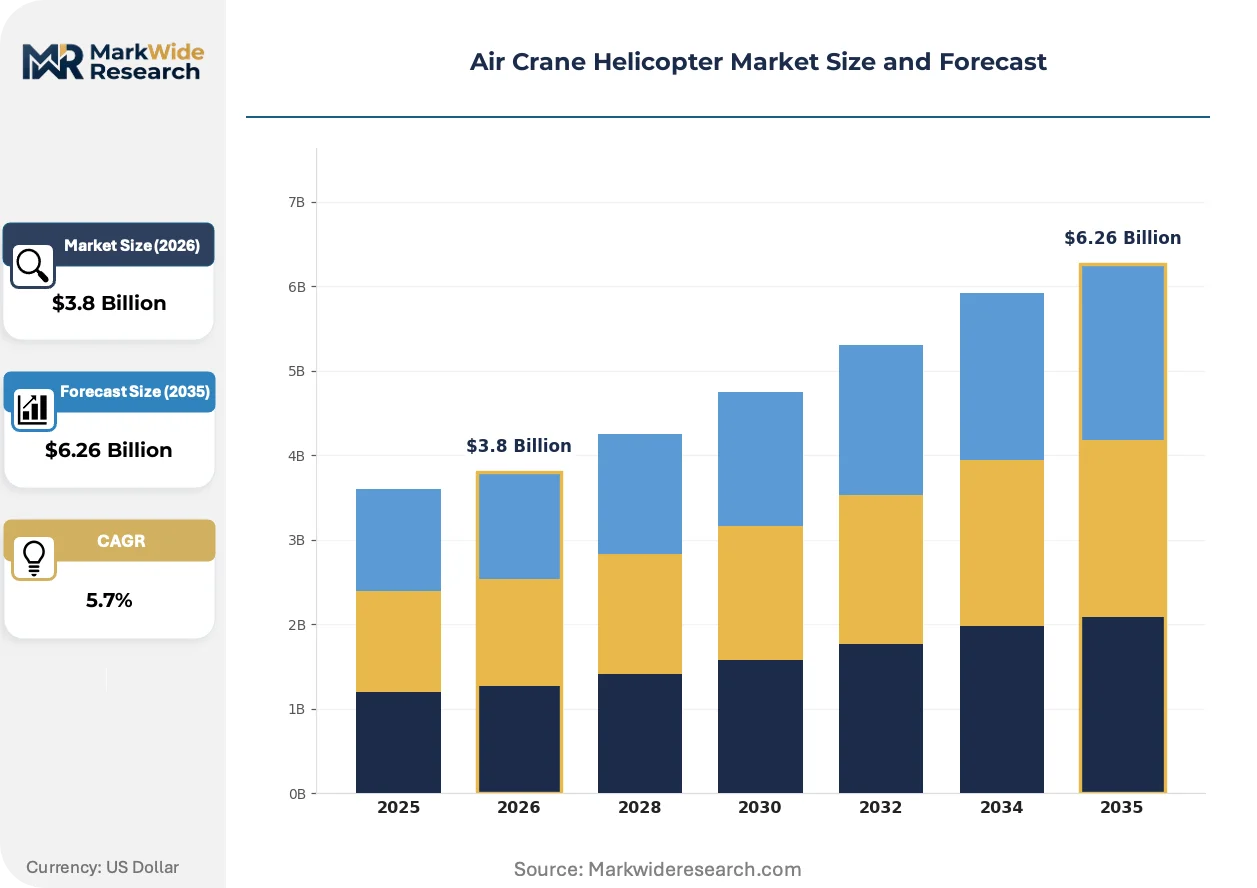
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy Lift, Medium Lift, Light Lift, Utility, Rescue Technology: Turboshaft Engine, Electric Lift Assistance, Composite Materials, Avionics Systems, Fly-by-Wire Application: Logging Operations, Firefighting, Construction Support, Disaster Relief, Infrastructure Maintenance End User: Contractors, Emergency Response Teams, Energy Companies, Forestry Services, Government Agencies |
| Companies Covered | Erickson Incorporated, Aircrane, Inc., Columbia Helicopters, Airbus Helicopters, Lockheed Martin Corporation, The Boeing Company, High Performance Helicopters Corp, Kaman Corporation, Textron Aviation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Crane Helicopter Market Strategic Shifts & Innovations
Digital fleet analytics and predictive maintenance platforms are restructuring operator economics, shifting value capture from hardware sales toward software-enabled service relationships.
Composite main rotor blades are overtaking traditional metal constructions in heavy-lift configurations. Timber harvesting operators in the Pacific Northwest are adopting carbon-fiber reinforced designs at accelerating rates. This material transition is overtaking established repair networks and compressing turnaround times for blade overhaul services.
REACH chemical safety standards are reshaping manufacturing processes for European-sourced composite materials. Industrial consequences include mandatory substance registration and restricted use of certain resin hardeners in blade production. Alpine construction contractors sourcing H215 Super Puma variants face extended certification timelines as suppliers adapt formulations.
Agency procurement officers are unbundling after-sales service contracts from airframe acquisitions. Firefighting agencies in Australia now separately negotiate fleet management subscriptions and predictive analytics access. This purchasing pattern shift is most visible in seasonal contract structures where utilization data drives renewal terms rather than hourly flight rates.
Air Crane Helicopter Market Segmentation
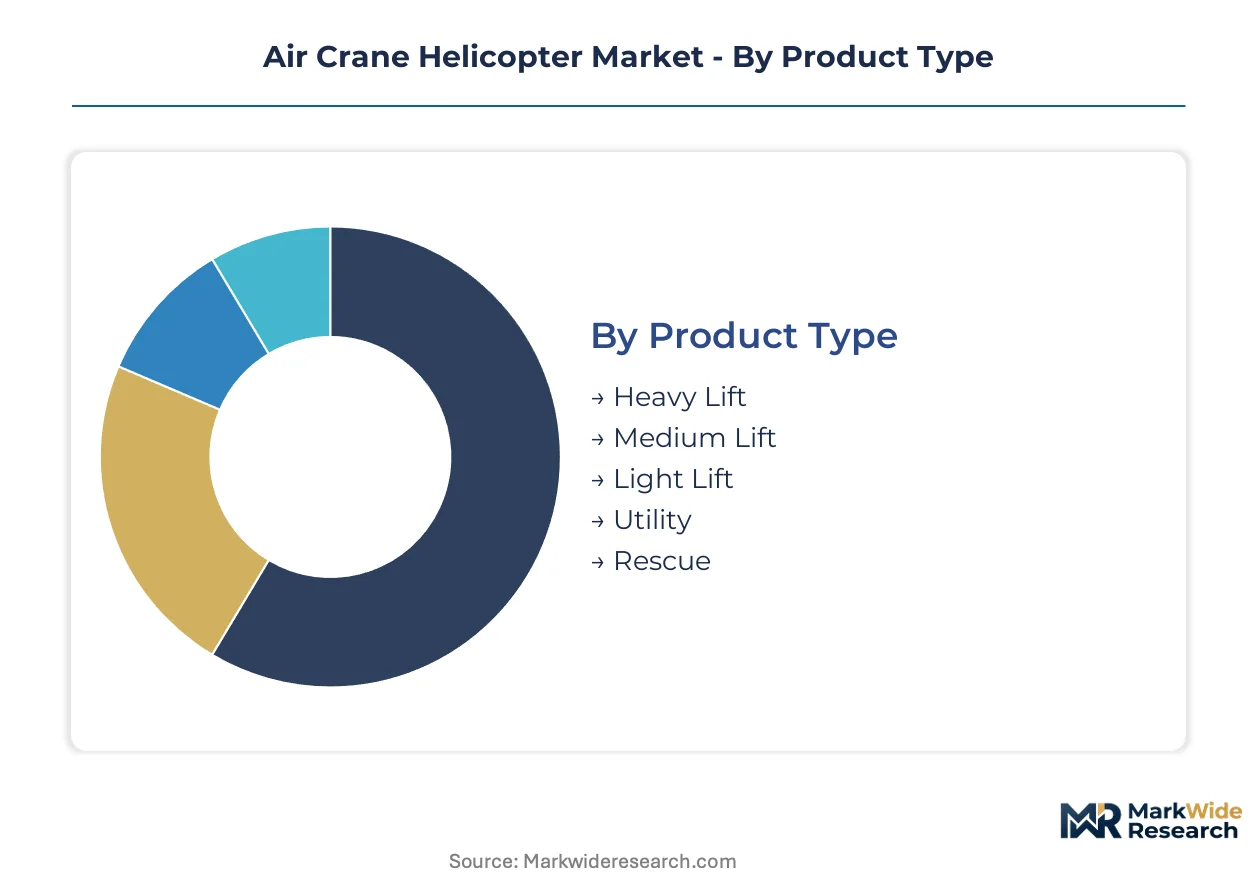
Segmentation in air crane helicopter procurement reveals how payload capacity, propulsion architecture, and mission profile dictate contract economics. Operators align fleet composition with seasonal demand spikes and regulatory certification tiers.
Product Type:
Supply concentration in heavy-lift manufacturing has consolidated around twin-turboshaft platforms exceeding 4,000 shaft horsepower.
- Heavy Lift:Twin-turboshaft configurations rated for 10,000–25,000 pounds external load dominate timber extraction in the Pacific Northwest and alpine construction in Switzerland. Irreplaceable payload requirements sustain premium pricing despite high hourly operating costs.
- Medium Lift:Single or dual-engine platforms in the 5,000–10,000-pound range serve firefighting agencies in Australia with seasonal deployment flexibility. Bushfire suppression contracts drive predictable utilization patterns that justify capital deployment.
- Light Lift:Compact rotorcraft under 5,000-pound capacity address utility missions in remote infrastructure inspection.
- Utility:Multi-role configurations balance external load capability with passenger transport for energy sector logistics.
- Rescue:Specialized hoisting and medical evacuation equipment prioritize crew safety systems over pure lift performance.
Today's leader: Heavy Lift. Tomorrow's challenger: Medium Lift.
Technology:
Cost tier differentiation separates legacy turboshaft platforms from emerging electric-hybrid architectures with divergent maintenance footprints.
- Turboshaft Engine:Conventional gas turbine propulsion delivers 4,000–10,000 shaft horsepower through proven mechanical transmission systems. FAA Part 133 certification pathways favor these established powerplants for external load operations.
- Electric Lift Assistance:Hybrid propulsion trials reduce fuel burn during hover-intensive missions, extending operational endurance for precision timber harvesting cycles. EASA CS-29 compliance timelines for hybrid configurations remain unresolved.
- Composite Materials:Carbon-fiber reinforced main rotor blades displace metal constructions, shifting margin pools toward certified repair stations.
- Avionics Systems:Digital flight management and load monitoring platforms enable predictive maintenance subscriptions.
- Fly-by-Wire:Electronic flight control architectures reduce pilot workload during precision external load placement.
Established dominance: Turboshaft Engine. Steepest expansion trajectory: Electric Lift Assistance.
Application:
Volume concentration in firefighting and logging concentrates fleet utilization in geographically dispersed, seasonally predictable contract structures.
- Logging Operations:Precision timber harvesting in remote terrain demands single-point cargo hook systems rated for 10,000–25,000 pounds. Pacific Northwest forestry services anchor demand with long-term fleet contracts.
- Firefighting:Aerial water tanker and bucket operations generate seasonal revenue spikes across Australia and the western United States. Fixed-wing tanker competition constrains pricing power for bulk water delivery.
- Construction Support:Heavy equipment placement in mountainous terrain across Austria and Switzerland remains underpenetrated due to limited certified high-altitude operators.
- Disaster Relief:Rapid deployment requirements prioritize fleet availability over payload optimization.
- Infrastructure Maintenance:Power line stringing and tower erection demand precision hover capability in confined airspace.
Current revenue anchor: Logging Operations. Fastest-climbing application: Construction Support.
End User:
Customer type segmentation distinguishes capital-owning agencies from contract-dependent service providers with divergent procurement cycles.
- Contractors:Private operators bid on seasonal firefighting and timber extraction contracts, bearing fleet utilization risk. FAA Part 135 crew rest limitations compress availability during peak demand windows.
- Forestry Services:Government and private timber management entities in the Pacific Northwest sustain multi-year heavy-lift agreements with dedicated fleet assignments.
- Emergency Response Teams:Rapid deployment requirements favor medium-lift configurations with cross-mission flexibility.
- Energy Companies:North Sea and alpine operators source H215 Super Puma variants for construction logistics.
- Government Agencies:Procurement officers unbundle after-sales service contracts from airframe acquisitions, negotiating separate fleet management subscriptions.
Dominant buyer today: Contractors. Emerging procurement force: Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia deploys the densest seasonal firefighting fleets, while Switzerland concentrates specialized alpine construction operators at higher altitudes than any other European jurisdiction.
United States
Pacific Northwest forestry services anchor heavy-lift demand through precision timber extraction contracts. FAA Part 133 certification requirements filter operational permits toward established external load specialists. Oregon and Washington state operators sustain multi-year fleet agreements with integrated logging infrastructure.
Australia
Seasonal bushfire suppression contracts generate predictable utilization spikes across New South Wales and Victoria. The Civil Aviation Safety Authority enforces stringent crew duty limitations during peak fire seasons. Queensland operators deploy medium-lift configurations for rapid response rotations in remote terrain.
Switzerland
Alpine construction support remains underpenetrated due to limited certified high-altitude operators for heavy equipment placement. Federal Office of Civil Aviation mandates specialized mountain flying certifications for external load missions. The Bernese Oberland and Valais cantons concentrate demand for infrastructure maintenance in glaciated terrain.
Canada
Remote resource extraction and power line stringing drive fleet deployment across British Columbia and Alberta. Transport Canada external load regulations align with FAA Part 133 operational standards. Vancouver Island operators specialize in coastal logging with extended range fuel configurations.
Austria
Mountainous construction logistics and ski resort infrastructure maintenance sustain niche demand for precision heavy-lift capability. Austro Control enforces EASA CS-29 derived certification for large rotorcraft operations. Tyrol and Vorarlberg provinces host concentrated alpine contractor activity.
Air Crane Helicopter Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with proprietary airframe developers commanding premium positioning in heavy-lift configurations while component suppliers capture recurring aftermarket revenue. The vendor base concentrates around three strategic archetypes: integrated platform OEMs with certified repair networks, specialized operators leasing standardized fleets to government agencies, and avionics providers monetizing predictive analytics subscriptions. Competitive moves center on backward integration into composite blade manufacturing and exclusive long-term service contracts that lock in agency procurement cycles.
Within the integrated platform tier, Erickson Incorporated and Columbia Helicopters exemplify divergent specialization strategies—one leveraging proprietary data analytics for firefighting agency relationships, the other anchoring Pacific Northwest logging through Vertol fleet standardization. Airbus Helicopters occupies a position bridging European regulatory compliance with alpine construction applications. These three entities represent distinct competitive vectors: analytics-enabled service bundling, geographic-mission vertical integration, and certification-optimized regional adaptation.
| Leading Market Players |
|---|
| Erickson Incorporated |
| Aircrane, Inc. |
| Columbia Helicopters |
| Airbus Helicopters |
| Lockheed Martin Corporation |
| The Boeing Company |
| High Performance Helicopters Corp |
| Kaman Corporation |
| Textron Aviation Inc. |
| Others |
Cost & Logistics Intelligence
Titanium and nickel alloy price indices cascade through turboshaft engine manufacturing into three distinct pricing tiers for air crane operators. Pacific Northwest forestry services absorb premium rates for heavy-lift configurations with integrated logging infrastructure, while Australian firefighting agencies negotiate seasonal contracts with utilization-linked pricing structures.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for FAA Part 133 certified heavy-lift services. Pricing stratifies across premium, standard, and economy tiers based on certification level and after-sales service bundling. Cost compression in medium-lift segments is intensifying because fixed-wing aerial tankers constrain pricing power for bulk water delivery. Contractors bidding on seasonal bushfire suppression contracts exhibit highest price sensitivity, whereas alpine construction operators in Switzerland demonstrate lowest sensitivity due to irreplaceable payload requirements.
Supply Chain Analysis
Single-source vulnerability sits with Pratt & Whitney Canada and Safran Helicopter Engines for 4,000–10,000 shaft horsepower turboshaft powerplants. Manufacturing draws from the United States, France, and Canada for critical engine components, with carbon-fiber prepregs sourced from Japan and Germany for composite rotor blade fabrication. Tariff exposure on aerospace-grade titanium creates procurement bottlenecks extending fleet expansion timelines. Distribution runs through OEM-certified repair stations and specialized operators leasing standardized fleets to government agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air crane helicopter market represents a late-cycle quality story as firefighting agencies unbundle after-sales service contracts and demand predictive analytics integration. Premium specifications now dominate procurement evaluation criteria over hourly flight rates.
For Market Incumbents: Cement exclusive long-term service agreements that lock in agency procurement cycles across multiple fire seasons. Deepen backward integration into composite blade manufacturing to capture margin pools shifting from OEMs toward certified repair stations. Electric lift assistance technologies threaten established turboshaft maintenance revenue streams. For New Entrants and Emerging Players: Begin with alpine construction support in Switzerland and Austria, where limited certified high-altitude operators create penetrable white space. Target medium-lift configurations for Australian bushfire suppression contracts with seasonal utilization flexibility. Go-to-market leverage rests on EASA CS-29 compliance expertise enabling European regulatory pathway navigation. For Investors and Strategic Acquirers: Asymmetric upside sits with avionics providers monetizing predictive maintenance subscriptions and fleet management software platforms. Five-to-ten year viability favors data analytics-enabled service bundling over pure airframe manufacturing. Watch for FAA Part 135 crew rest limitation amendments as inflection indicator for labor cost compression and fleet availability expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Blade Manufacturing | Captures margin pools shifting from OEMs toward certified repair stations in Pacific Northwest timber extraction markets. |
| Fleet Management Subscription Launch | Creates recurring revenue streams beyond initial airframe sales through predictive maintenance tools for Australian firefighting agencies. |
| Alpine Construction Operator Certification | Unlocks underpenetrated heavy equipment placement demand in Switzerland's Bernese Oberland and Valais cantons. |
| Hybrid Propulsion Platform Development | Addresses fuel burn reduction during hover-intensive timber harvesting cycles through electric lift assistance trials. |
| Exclusive Long-Term Service Contract Negotiation | Locks in government agency procurement cycles across multiple seasonal firefighting contract renewals. |
Research Approach
Coverage spans the United States, Australia, Switzerland, Canada, and Austria, with primary inputs from each jurisdiction combined with secondary validation. Fleet operations directors, FAA certification specialists, forestry procurement officers, and turboshaft engine program managers contributed interview data. Secondary sources include FAA Part 133 certification databases, EASA CS-29 type certificate records, Australian Civil Aviation Safety Authority incident reports, and customs data on aerospace titanium imports. Bottom-up fleet deployment modeling triangulates against top-down contract value aggregation.
Rate-of-change decomposition separates volume growth from price realization across payload capacity tiers, propulsion architecture categories, and mission profile segments. The analytical framework projects external load operation hours, fleet utilization rates, and aftermarket service attachment over the projection horizon. CAGRs derive from segmented growth rate blending weighted by revenue contribution. Industry-specific inputs include seasonal firefighting contract award patterns and timber extraction cycle frequency in Pacific Northwest logging operations.
Caveats apply where FAA Part 135 crew rest limitation amendments, turboshaft engine supply disruptions, or EASA hybrid propulsion certification delays could materially shift the outlook. Forecasts reflect documented assumptions about contract renewal rates and fleet replacement cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
Flying Taxi Market
Air Mobility
Offshore Helicopter Services Market
Air Mobility
Global Aerodynamics Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Hang Glider Market
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
Air Transport Modifications Market
Air Mobility
Advanced Aerial Mobility Market
Air Mobility
Middle-East and Africa Military Aviation Market
Air Mobility
Global Flying Cars Market
Air Mobility
Helicopter-Based Transportation Market
Air Mobility
Air Transport USM Market
Air Mobility
Asia-Pacific Charter Jet Service Market
Air Mobility
Flying Jetpacks Market
Air Mobility
China Chartered Air Transport Market