
 Global Aircraft Filter Market | 2026-2036
Global Aircraft Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Filter Market Intelligence
The integration of smart sensors for real-time performance monitoring and predictive maintenance alerts is reshaping aircraft filter design. This shift enables operators to optimize replacement schedules and prevent unscheduled downtime. Parker Hannifin Corporation leverages its broad aerospace systems portfolio to integrate these smart technologies. Donaldson Company Inc. competes on its advanced filtration media science, while Pall Corporation specializes in complex fluid management and purification systems for demanding applications.
Aircraft filters are specialized components designed to remove contaminants from air and fluid systems, such as fuel, oil, and hydraulic fluid. These filters must meet stringent specifications for particle capture efficiency, often exceeding 99.97% for HEPA cabin air filters. Their primary purpose is to protect critical engine components, ensure passenger well-being, and maintain system reliability. Hydraulic and fuel filter segments command significant value, while cabin air filters represent a high-volume replacement market, particularly for commercial jets.
The market operates under strict regulatory oversight from bodies like the US Federal Aviation Administration (FAA) and through European Union airworthiness standards. These regulations dictate material specifications, performance testing, and mandatory replacement intervals for certified parts. Military specifications (MIL-SPEC) impose even more rigorous demands for defense applications. Future investment decisions will hinge on developing filters that meet stricter environmental regulations and offer lower total cost of ownership.
Market Dynamics
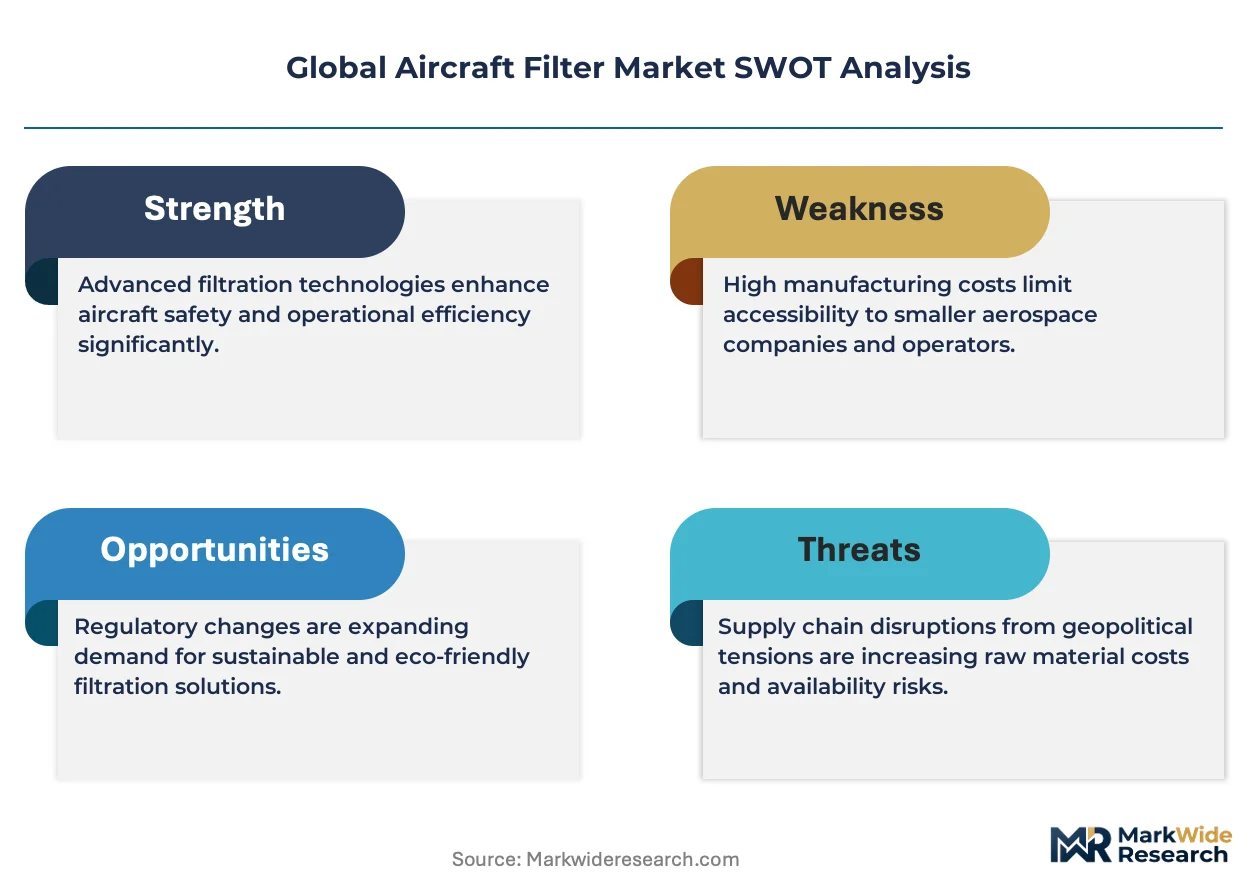
The aircraft filter market's evolution is driven by the fundamental tension between increasingly stringent airworthiness regulations and the operational demand for lower total cost of ownership. This dynamic forces manufacturers to innovate beyond simple particle capture toward integrated systems that enhance overall aircraft performance and reliability.
Growth Catalysts
- Advanced Filter Media:The adoption of nanofiber and other synthetic media improves filtration efficiency and extends service intervals, supporting fleet modernization programs for commercial and business jets.
- UAV Fleet Expansion:Rapid proliferation of Unmanned Aerial Vehicles in logistics, agriculture, and defense creates a high-volume demand stream for specialized, lightweight air, fuel, and hydraulic filters.
- Cabin Air Quality Mandates:Stricter international health and safety standards, influenced by bodies like the European Union Aviation Safety Agency (EASA), are compelling airlines to upgrade to HEPA filters, boosting the replacement market.
Market Restraints
- Material Price Volatility:Fluctuations in the cost of specialized raw materials, including aerospace-grade aluminum and advanced polymer fibers, create margin pressure and complicate long-term pricing strategies for manufacturers.
- Lengthy Certification Cycles:New filter designs are subject to extensive and costly qualification testing to meet US Federal Aviation Administration (FAA) and other regulatory standards, significantly delaying market entry for innovations.
- High Initial Investment:Developing and qualifying filters for demanding military applications, which require adherence to rigorous MIL-SPEC standards, necessitates substantial capital expenditure that acts as a barrier to new entrants.
Strategic Opportunities
- Predictive Maintenance Integration:Embedding smart sensors into filter modules to monitor differential pressure and particle accumulation enables a shift to condition-based maintenance, creating opportunities for data-driven service contracts.
- Urban Air Mobility (UAM):The emerging eVTOL aircraft market presents a new frontier for developing novel, compact, and lightweight filtration systems optimized for electric powertrain thermal management and cabin air systems.
- Sustainable Aviation Fuel (SAF) Compatibility:Developing filters specifically designed to handle the unique properties and potential contaminants of Sustainable Aviation Fuels offers a path to capture value from the industry's green transition.
Industry Challenges
- Regulatory Harmonization:Manufacturers face significant design and testing costs to ensure a single product can meet the often-divergent certification requirements of the FAA, EASA, and the Civil Aviation Administration of China (CAAC).
- Legacy System Integration:Integrating new sensor-equipped smart filters with older aircraft avionics and ground-based maintenance software presents technical challenges, potentially limiting adoption in aging fleet segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Filter Market |
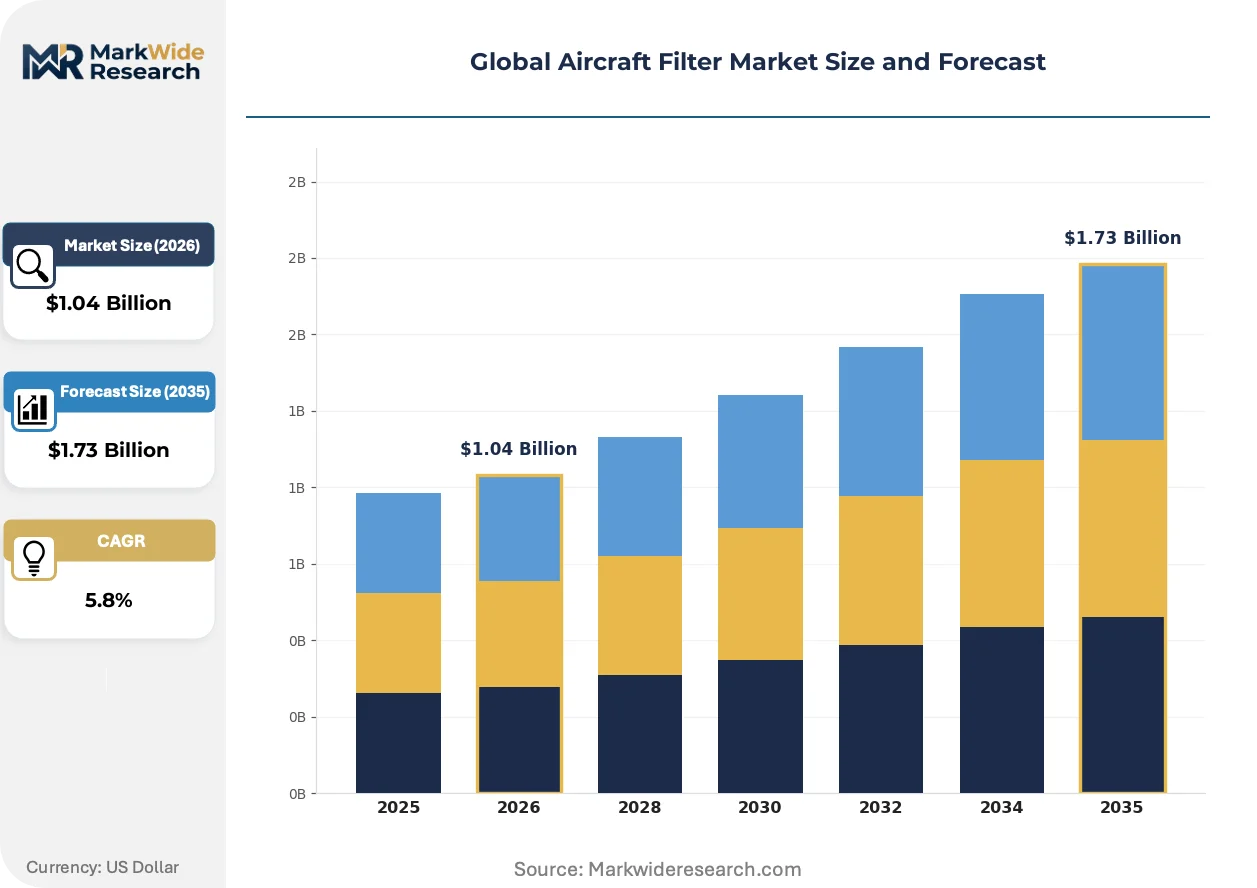
| Market Size in 2026 | $1.04 Billion |
| Market Size in 2035 | $1.73 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: Air Intake, Oil, Fuel, Hydraulic, Cabin Air Technology: HEPA, ULPA, Activated Carbon, Electrostatic, Nanofiber Application: Commercial Jets, Military Aircraft, Helicopters, Business Jets, Unmanned Aerial Vehicles End User: Airlines, Defense Forces, Private Operators, Maintenance Repair Organizations, Leasing Companies |
| Companies Covered | Parker Hannifin Corporation, Donaldson Company Inc., Safran Filtration Systems, Freudenberg Group, Pall Corporation, Eaton Corporation, Porvair Plc, Honeywell International Inc., Hollingsworth & Vose, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Filter Market Strategic Shifts & Innovations
The core transformation in the aircraft filter market is the evolution of filters from passive, disposable components into active, intelligent nodes within the aircraft's health monitoring network. This shift provides operators with actionable data to optimize maintenance logistics and enhance operational availability.
Nanofiber filter media provides superior particle capture with a lower pressure drop compared to traditional microglass materials. Commercial airlines and business jet operators are adopting this technology for engine intake and cabin air systems to improve performance and extend service intervals. This technological advancement is collapsing the historical trade-off between filtration efficiency and system energy consumption, enabling more fuel-efficient aircraft operations.
European Union regulations, enforced through EASA airworthiness directives, are mandating the use of higher-efficiency cabin air recirculation filters. This action compels airlines operating within or flying to Europe to upgrade from standard filters to HEPA-grade systems, primarily to mitigate the risk of airborne pathogen transmission. The commercial wide-body and narrow-body aircraft segments are most impacted, which accelerates replacement cycles and retrofit programs.
Airlines are transitioning from fixed-interval replacement schedules toward condition-based maintenance for high-value hydraulic and fuel filters. This change is enabled by data from integrated sensors that provide real-time alerts on filter performance and remaining useful life. The trend is most prominent within North American and European carrier fleets, where operators use the data to optimize spare parts inventory and prevent unscheduled downtime.
Global Aircraft Filter Market Segmentation
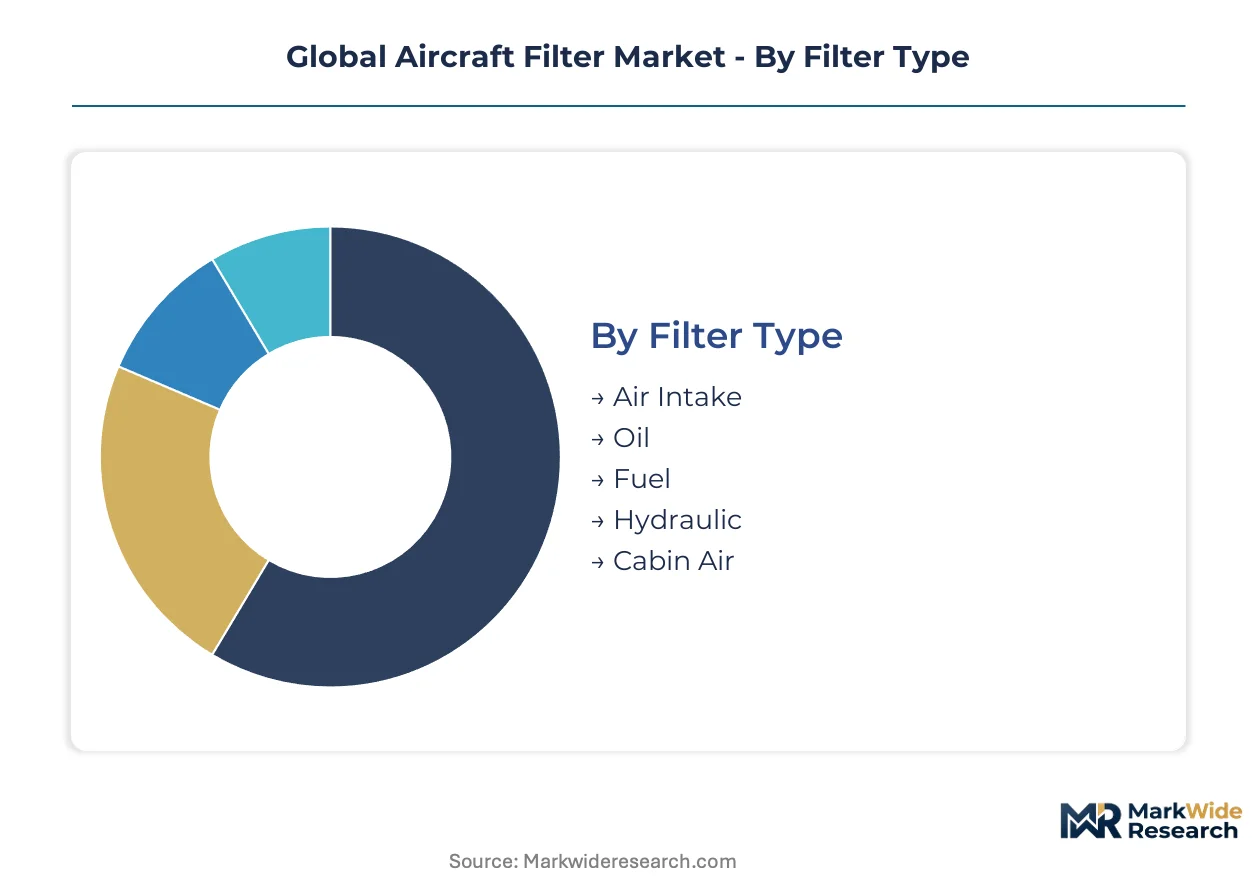
Understanding the Global Aircraft Filter Market through segmentation provides clarity on the diverse technological requirements and operational demands across aviation sectors. This granular view allows stakeholders to identify specific growth pockets and tailor product development to address distinct end-user needs and regulatory mandates.
Filter Type:
The functional role of filters across various aircraft systems defines this segmentation category, reflecting critical performance requirements.
- Air Intake:These filters protect aircraft engines from foreign object debris, dust, and other atmospheric contaminants, ensuring optimal airflow and preventing compressor damage.
- Oil:Components designed to remove metallic particles, carbon deposits, and other impurities from engine lubrication systems, extending engine life and reducing maintenance costs.
- Fuel:Filters engineered to capture particulate matter and separate water from aviation fuel, safeguarding engine components from corrosion and ensuring efficient combustion. Demand concentrates in commercial and military fleets, driven by stringent engine performance requirements and operational reliability.
- Hydraulic:Filters that remove contaminants from hydraulic fluids, maintaining system cleanliness to ensure precise control, prevent component wear, and avoid critical system failures.
- Cabin Air:Specialized filters, including HEPA systems, designed to purify recirculated air within the aircraft cabin, capturing allergens, pathogens, and odors for passenger well-being. This segment experiences high-volume replacement demand, particularly for commercial jets responding to stricter health and safety standards.
Fuel filters command the established base. The steepest expansion runs through Cabin Air filters.
Technology:
The material science and engineering principles applied to filter media differentiate this category, impacting efficiency and service life.
- HEPA:High-Efficiency Particulate Air filters capture 99.97% of particles 0.3 micrometers in diameter, essential for cabin air purification and sterile environments within aircraft. Demand is accelerating in commercial aviation due to stringent EASA airworthiness directives for pathogen mitigation.
- ULPA:Ultra-Low Particulate Air filters offer even higher efficiency than HEPA, used in highly sensitive aerospace manufacturing processes and specialized aircraft applications.
- Activated Carbon:Filters designed to adsorb gaseous contaminants, volatile organic compounds, and odors from the air stream, improving air quality in specific aircraft compartments.
- Electrostatic:Employs an electrostatic charge to attract and capture airborne particles, often used in conjunction with other media types for enhanced filtration performance and reduced pressure drop.
- Nanofiber:Utilizes extremely fine synthetic fibers to achieve superior filtration efficiency with lower pressure drop, extending service intervals for engine intake and cabin air systems. This technology sees increasing adoption in new commercial and business jet designs for improved fuel efficiency.
Advanced HEPA technology underpins critical safety standards, while nanofiber media drives efficiency gains across new platforms.
Application:
The operational environment and aircraft type dictate the specific filter requirements within this segment, influencing design and durability.
- Commercial Jets:Filters designed for large passenger aircraft, including narrow-body and wide-body models, protecting engines, hydraulic systems, and cabin air quality. This segment represents a significant replacement market, driven by fleet size and mandatory maintenance schedules.
- Military Aircraft:Filtration systems engineered to withstand extreme conditions, including high vibration, temperature fluctuations, and chemical exposure, meeting rigorous MIL-SPEC standards for combat and transport aircraft.
- Helicopters:Filters optimized for rotary-wing aircraft, protecting engines and systems from unique environmental challenges like dust and debris encountered in diverse operating conditions.
- Business Jets:Advanced filtration solutions providing enhanced cabin comfort, superior engine protection, and extended service intervals for private and corporate aircraft operators.
- Unmanned Aerial Vehicles:Specialized, lightweight filters for drones used in logistics, agriculture, and defense, addressing unique requirements for compact size and thermal management. The rapid proliferation of UAV fleets creates a high-volume demand stream for these specialized components.
Commercial Jets form the largest installed base, while Unmanned Aerial Vehicles represent a rapidly expanding frontier for specialized filter development.
End User:
The primary customer base and their operational models define the purchasing patterns in this category, influencing procurement strategies.
- Airlines:Commercial carriers operating large fleets of passenger and cargo aircraft, requiring high volumes of replacement filters for routine maintenance and regulatory compliance. Their purchasing decisions are heavily influenced by total cost of ownership and operational uptime.
- Defense Forces:Military organizations procuring filters for combat, transport, and surveillance aircraft, prioritizing performance, reliability, and adherence to stringent MIL-SPEC standards. Procurement cycles are often long-term and tied to national defense budgets.
- Private Operators:Owners of business jets and private aircraft, seeking premium filtration solutions for enhanced cabin comfort and optimal engine performance.
- Maintenance Repair Organizations:Companies providing aircraft maintenance services to various operators, purchasing filters for a wide range of aircraft types during scheduled and unscheduled repairs.
- Leasing Companies:Entities that own and lease aircraft to operators, influencing filter specifications and maintenance requirements as part of their comprehensive asset management strategies.
Airlines drive substantial volume demand, while Defense Forces dictate the most rigorous performance specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global aircraft filter market sees significant demand concentration from established aviation ecosystems. Airlines and defense forces represent the largest procurement entities, driving both volume and stringent performance requirements. Private operators and maintenance, repair, and overhaul (MRO) organizations also contribute substantially to replacement cycles.
United States
Demand in the United States stems from its extensive commercial airline fleet and robust military aviation programs. The US Federal Aviation Administration (FAA) sets rigorous airworthiness standards for filters, especially for cabin air quality and engine protection. Major aerospace hubs like Seattle, Wichita, and Fort Worth concentrate manufacturing and MRO activities for aircraft filters.
China
China's expanding commercial aviation sector and growing domestic aircraft manufacturing capabilities drive filter demand. The Civil Aviation Administration of China (CAAC) implements its own certification processes, often aligning with international standards. Shanghai and Xi'an are emerging as critical centers for aerospace component production and aircraft assembly.
France
France benefits from its strong position in European aerospace manufacturing, particularly with Airbus and Dassault Aviation. The European Union Aviation Safety Agency (EASA) mandates high-efficiency filter standards for all aircraft operating within its jurisdiction. Toulouse serves as a major aerospace cluster, integrating filter innovation into new aircraft designs.
Germany
German aerospace companies and a strong MRO segment generate consistent demand for aircraft filters. German airworthiness regulations, often aligned with EASA, emphasize safety and environmental performance. Hamburg and Munich host significant aerospace engineering and maintenance facilities, requiring advanced filtration solutions.
United Kingdom
The United Kingdom's aerospace industry, including engine manufacturers and MRO providers, creates substantial filter requirements. The UK Civil Aviation Authority (CAA) enforces airworthiness directives, influencing filter specifications and replacement schedules. Bristol and Derby are key centers for aerospace component design and engine manufacturing.
Global Aircraft Filter Market Key Industry Players
Channel-controlling players compete with product-specialist players across the aircraft filter market. The market exhibits a tiered structure, with large diversified aerospace suppliers alongside niche filtration technology providers. Strategic archetypes include integrated system providers leveraging broad portfolios, material science innovators focused on media efficiency, and MRO-focused specialists. Portfolio diversification and strategic partnerships represent dominant competitive moves to secure long-term contracts.
Integrated system providers like Parker Hannifin Corporation represent a segment offering broad aerospace solutions, often incorporating smart technologies into their filter modules for enhanced performance monitoring. Donaldson Company Inc. exemplifies an archetype focused on advanced filtration media science, developing high-performance filter media for diverse aircraft applications. Pall Corporation occupies a position as a specialist in complex fluid management and purification systems, serving highly demanding aerospace applications with specialized products and engineering expertise. These companies collectively anchor different strategic vectors within the industry, from broad system integration to specialized material innovation.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Donaldson Company Inc. |
| Safran Filtration Systems |
| Freudenberg Group |
| Pall Corporation |
| Eaton Corporation |
| Porvair Plc |
| Honeywell International Inc. |
| Hollingsworth & Vose |
| Others |
Cost & Logistics Intelligence
Global air freight corridors, while efficient for high-value components, introduce cost dynamics that influence both supply concentration and downstream price differentiation across the aircraft filter market. This tension drives strategic sourcing decisions for aerospace manufacturers.
Pricing Analysis
Long-term cost-plus contracts often incorporate raw material indexation, forming a dominant pricing model for aircraft filters. Price differentiation stems from the stringent certification level required by bodies like the FAA or EASA, and specialized after-sales service packages. Pricing softness stems from airline cost optimization initiatives for high-volume replacement parts. Defense Forces exhibit the least price sensitivity, prioritizing performance and reliability over cost, while commercial airlines are the most price-sensitive buyers.
Supply Chain Analysis
Specialized aerospace component manufacturers in key hubs like the United States and Germany hold significant capacity for aircraft filter production. Raw material dependencies include advanced nanofiber media and aerospace-grade aluminum. Single-source vulnerability for highly specialized filtration media presents a structural supply chain risk. Distribution runs through direct sales channels to Original Equipment Manufacturers (OEMs) and established Maintenance, Repair, and Overhaul (MRO) networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft filter market represents a high-growth disruption, driven by the rapid expansion of UAV fleets and evolving air quality mandates. Stakeholders must strategically adapt to these shifts.
For Market Incumbents: Build intellectual property moats through continuous investment in advanced materials R&D, particularly in nanofiber and smart sensor integration. Acquire specialized media manufacturers to counter emerging niche players with novel filtration technologies. Leverage existing certification investment with FAA and EASA to maintain market access and regulatory compliance.
For New Entrants and Emerging Players: Establish a beachhead in the Urban Air Mobility (UAM) filtration segment, which requires novel, compact, and lightweight systems. Target the rapidly proliferating UAV market for specialized, lightweight air and fluid filters as a penetrable segment. Partner with eVTOL OEMs for co-development of thermal management and cabin air systems to gain early market access.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized filtration solution providers with proprietary media or integrated smart sensor capabilities. The long-term viability of this market is critical for airworthiness and operational efficiency over the next decade. Look for increased M&A activity for companies developing advanced filtration media or predictive maintenance platforms as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Nanofiber Media Expansion | Enhances filtration efficiency and extends service intervals for commercial and business jets. |
| OEM Co-development Partnerships | Secures future platform integration for advanced filtration systems in new aircraft designs. |
| Smart Sensor Integration Acquisition | Adds predictive maintenance capabilities, optimizing replacement schedules and reducing downtime. |
| Asia-Pacific MRO Network Expansion | Captures growing aftermarket demand from expanding commercial fleets in the region. |
| EASA HEPA Compliance Investment | Ensures access to the European market for cabin air filters under strict health regulations. |
Research Approach
Findings reconcile primary fieldwork against secondary review of aviation authority filings, aerospace OEM reports, and MRO association publications. Primary interviews involved aerospace engineers, procurement managers at OEMs, MRO directors, and airline operations leads. This primary data was triangulated with secondary sources such as FAA and EASA regulations, company financial statements, and specialized industry journals, employing both bottom-up market sizing and top-down validation.
Forecast inputs being considered include global aircraft fleet projections, regulatory mandate timelines for cabin air quality, and raw material cost trends. The analytical framework models market segmentation across filter type, technology, application, end-user, and regional air traffic growth over the projection horizon. Compound annual growth rates are derived from historical data and projected market drivers, including UAV adoption rates and Sustainable Aviation Fuel compatibility development.
Sensitivities concentrate around geopolitical events, new airworthiness directives, or significant shifts in raw material supply that could impact market forecasts. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Quarterly review of commercial aircraft deliveries and regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Narrow-Body Turbofan Engine Shop Visit Services Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Aircraft Engine Nacelle Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market