
 Asia-Pacific Aircraft Engine Market | 2026-2036
Asia-Pacific Aircraft Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aircraft Engine Market Outlook
Modular engine leasing and power-by-the-hour contracts is decoupling ownership from operational risk across Asia-Pacific airline procurement. GE Aerospace leverages its joint venture footprint through CFM International to sustain aftermarket revenue streams throughout the region. Pratt & Whitney anchors narrowbody engine placements with multiple ASEAN flag carriers. Rolls-Royce Holdings competes on widebody platforms serving long-haul routes between East Asia and Europe.
An aircraft engine converts chemical energy from fuel into mechanical thrust through controlled combustion and turbine expansion, typically operating at core temperatures exceeding 1,400°C and pressure ratios above 40:1 to achieve optimal thermodynamic efficiency for propulsion. Turbofan configurations dominate commercial installations due to bypass ratio advantages that reduce noise and fuel consumption on medium-haul routes. Military aviation applications favor turbojet and low-bypass turbofan architectures where thrust-to-weight ratios outweigh efficiency priorities. Auxiliary Power Units represent a concentrated margin pool as regional airports upgrade ground support infrastructure across Indonesia and Vietnam.
Japan's METI coordinates national propulsion research through IHI Corporation and Mitsubishi Heavy Industries partnerships that align with JIS certification requirements for domestic aerospace suppliers. China's NMPA and MIIT jointly enforce airworthiness standards that progressively favor Aero Engine Corporation of China content in state-owned airline fleets. India's DGCA implements ICAO-aligned type certification procedures that govern import approvals for foreign-manufactured powerplants. Stakeholders must weigh technology transfer obligations against intellectual property exposure when structuring joint ventures with Chinese engine developers.
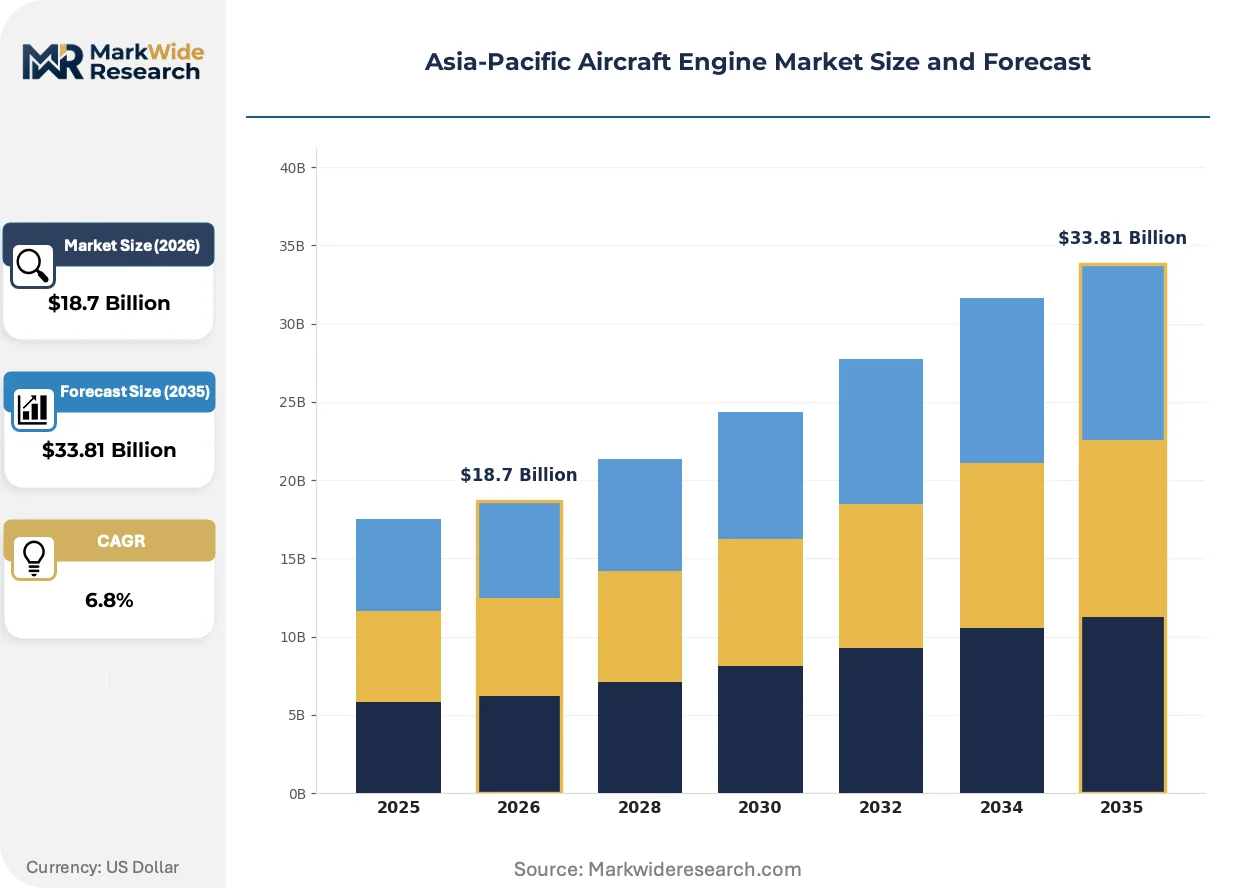
Market Dynamics
China's MIIT domestic content mandates are forcing multinational OEMs to restructure joint venture terms and localize core component production across their Asia-Pacific supply footprints.
Growth Catalysts
- Low-cost carrier fleet expansion:Southeast Asian budget airlines are placing record narrowbody orders, driving turbofan demand through 2035.
- MIIT localization requirements:China's ministry mandates progressively higher domestic engine content in state-owned airline fleets, accelerating indigenous development programs.
- MRO corridor concentration:India's maintenance infrastructure around Bengaluru and Hyderabad is attracting foreign direct investment in specialized overhaul capabilities.
Market Restraints
- Superalloy supply concentration:Precision-cast turbine blade supply chains concentrate among a handful of certified Japanese and European foundries, creating single-source vulnerability.
- Technology transfer friction:China's joint venture rules require foreign OEMs to share core intellectual property, deterring participation from proprietary technology holders.
- Dual-use export controls:US and EU military technology restrictions limit certain turbofan architectures from entering Chinese maintenance networks.
Strategic Opportunities
- Indonesia airport infrastructure:Ground support modernization across Jakarta and Surabaya creates concentrated demand for auxiliary power unit upgrades and leasing models.
- Hybrid-electric propulsion convergence:Distributed electric architectures paired with gas turbine cores are opening development partnerships between Japanese industrial conglomerates and regional airlines.
- PLI scheme alignment:India's production-linked incentive framework for aerospace components offers cost offsets for engine part manufacturing investments in Gujarat and Tamil Nadu.
Industry Challenges
- Specialized technician scarcity:Advanced composite repair and hot-section refurbishment skills lag fleet growth across Vietnam and Philippines MRO facilities.
- Type certification timelines:DGCA and NMPA parallel approval processes for imported powerplants extend entry-to-service intervals by 18-24 months.
- Legacy fleet interoperability:Mixed-engine maintenance protocols complicate ground operations for airlines operating both CFM56 and V2500 families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aircraft Engine Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbofan, Turboprop, Turbojet, Auxiliary Power Unit Installation Type: Linefit, Retrofit, Engine Change, Overhaul End User: Commercial Aviation, Military Aviation, Cargo Aviation, Business Aviation Fuel Type: Jet A, Jet A-1, Biofuels, Synthetic Fuels |
| Companies Covered | Rolls-Royce Holdings, GE Aerospace, Pratt & Whitney, Safran Aircraft Engines, MTU Aero Engines, CFM International, Aero Engine Corporation of China, IHI Corporation, Mitsubishi Heavy Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aircraft Engine Market Strategic Shifts
Digital thread integration across design, manufacturing, and aftermarket service is compressing development cycles and enabling predictive maintenance business models throughout the Asia-Pacific engine value chain.
Additive manufacturing is integrating nickel-based superalloy lattice structures into low-pressure turbine frames, reducing part count and weight. Japanese suppliers through METI-coordinated research programs are qualifying these processes for JIS-certified production lines. The technology is integrating repair-on-demand capabilities that collapse traditional spare parts inventory requirements.
China's NMPA and MIIT jointly enforce airworthiness standards that progressively favor Aero Engine Corporation of China content in state-owned airline procurement decisions. Foreign OEMs must establish domestic maintenance joint ventures to retain aftermarket access. Widebody engine segments serving international routes face the steepest compliance adjustments.
Power-by-the-hour contracts are displacing traditional engine ownership across ASEAN flag carriers and low-cost operators alike. Lessors and OEMs capture recurring revenue while airlines transfer residual value risk. This procurement evolution concentrates in Indonesia and Vietnam where capital constraints favor operational expenditure structures.
Asia-Pacific Aircraft Engine Market Segmentation
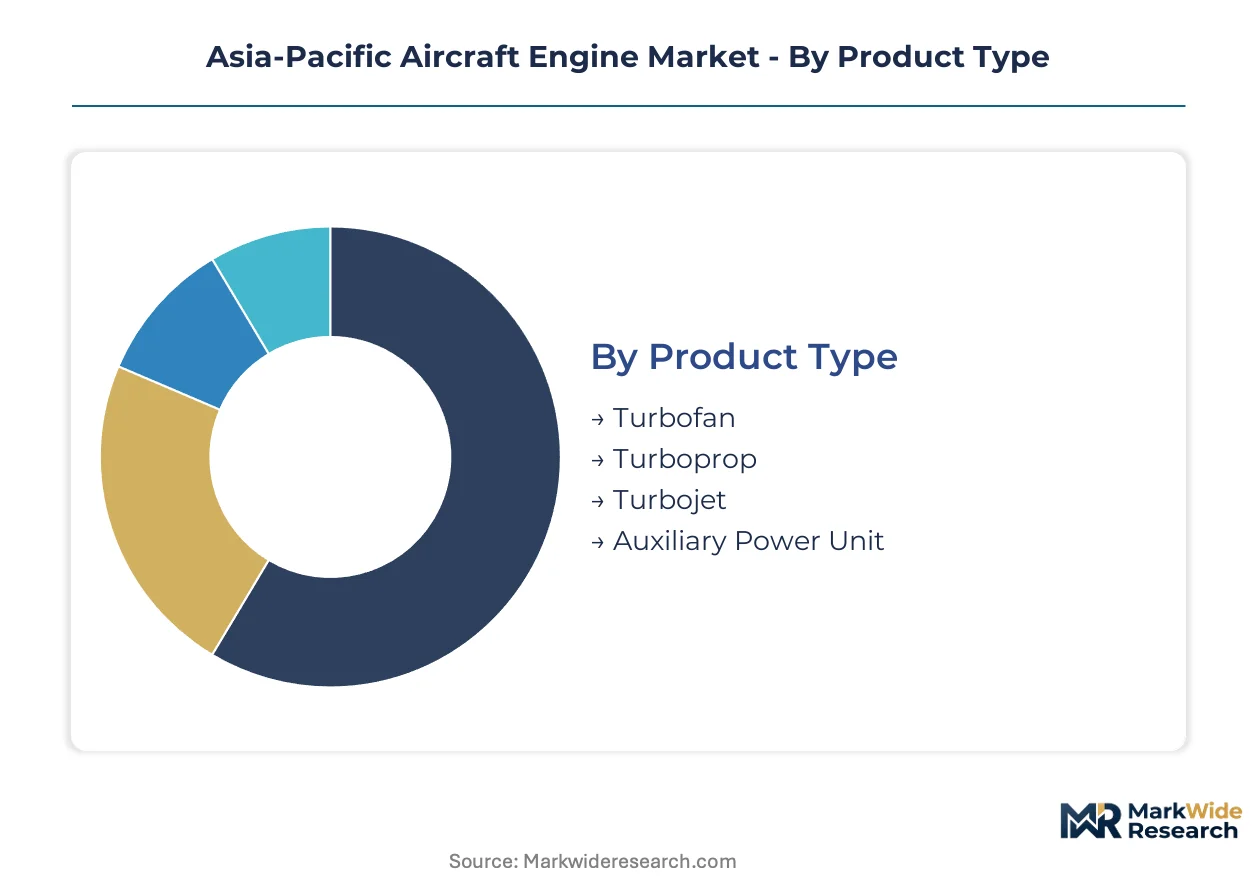
Engine architecture choices determine maintenance protocols, fuel infrastructure requirements, and regulatory compliance pathways across Asia-Pacific operator fleets. Segmentation reveals where procurement budgets concentrate and which technologies face substitution pressure from hybrid-electric alternatives.
Product Type:
Turbofan configurations command premium unit economics through higher thrust ratings and bypass ratio advantages, while turboprop and auxiliary power units serve volume-driven replacement cycles.
- Turbofan:High-bypass architectures dominate narrowbody and widebody commercial installations across Southeast Asian low-cost carrier fleets. China's MIIT domestic content mandates are accelerating joint venture localization for core turbofan modules serving state-owned airlines.
- Turboprop:Regional connectivity networks across Indonesia's archipelago and India's UDAN scheme routes favor turboprop fuel efficiency on sub-500 nautical mile sectors. Demand concentrates in turboprop conversions for aging ATR and Q400 fleets requiring engine life extensions.
- Turbojet:Military trainer and light combat aircraft programs in South Korea and Australia sustain turbojet procurement despite commercial obsolescence.
- Auxiliary Power Unit:Ground support modernization at Jakarta and Surabaya airports drives concentrated APU upgrade demand for parked aircraft power and air conditioning.
Mature deployment sits with turbofan configurations on trunk routes. Newer deployment is concentrated in auxiliary power unit leasing models at expanding Indonesian airport infrastructure.
Installation Type:
Procurement patterns split between factory-integrated linefit volumes and aftermarket-driven retrofit and overhaul revenue streams.
- Linefit:OEM-integrated engine deliveries accompany record narrowbody order backlogs from Vietnam and Philippines low-cost carriers. CFM International and Pratt & Whitney secure multi-year linefit commitments through airframe manufacturer partnerships.
- Engine Change:Lease-end transitions and redelivery requirements drive engine swap volumes at Singapore and Hong Kong maintenance hubs. Lessors mandate engine change compliance to preserve residual asset values.
- Retrofit:Re-engining programs for legacy freighter fleets face certification delays from DGCA and NMPA parallel approval processes.
- Overhaul:Hot-section refurbishment demand outstrips certified technician supply across Bengaluru and Hyderabad MRO corridors.
Volume economics favor linefit installations for new aircraft deliveries. Margin concentration is shifting toward engine change and overhaul services as Asia-Pacific fleet age profiles mature.
End User:
Commercial aviation procurement dwarfs military and business segments, though cargo operators are expanding dedicated freighter engine orders.
- Commercial Aviation:Narrowbody engine demand from AirAsia, IndiGo, and VietJet dominates order books. Power-by-the-hour contracts decouple ownership risk for capital-constrained operators.
- Cargo Aviation:E-commerce logistics expansion across China-ASEAN trade lanes drives dedicated freighter conversions requiring high-cycle engine configurations.
- Military Aviation:Indigenous fighter programs in South Korea and Japan sustain specialized low-bypass turbofan development through METI and DAPA procurement.
- Business Aviation:Fractional ownership growth in Australia and Singapore supports premium engine maintenance contracts.
Commercial aviation retains the steepest expansion trajectory through 2035. Military aviation procurement is concentrating in sovereign development programs with technology transfer requirements.
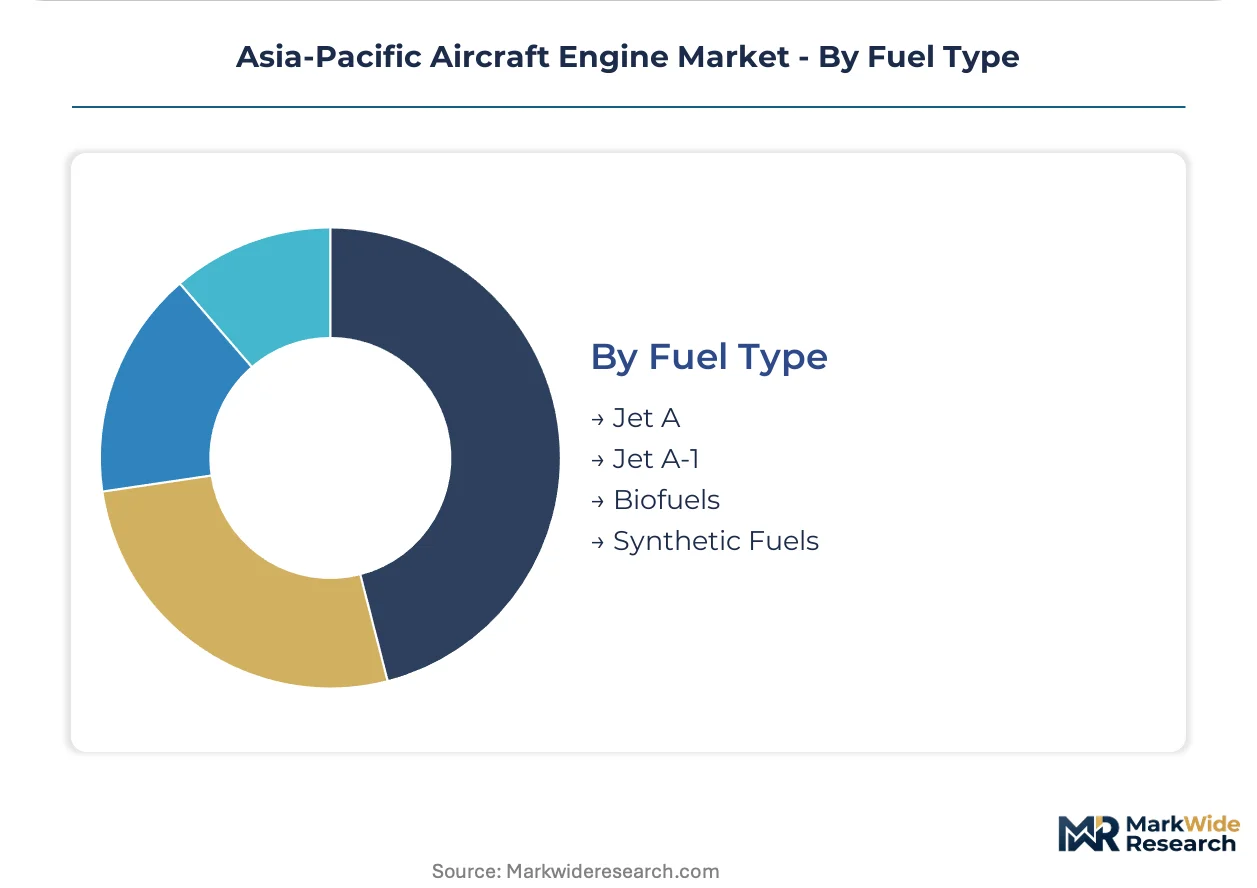
Fuel Type:
Jet A-1 specification dominance faces gradual displacement from sustainability mandates and synthetic fuel certification pathways.
- Jet A-1:Standard kerosene specification underpins current fleet operations across all Asia-Pacific regulatory jurisdictions. Supply infrastructure concentrates in Singapore and South Korea refining hubs.
- Biofuels:ICAO CORSIA alignment drives Singapore Airlines and Cathay Pacific sustainable aviation fuel offtake agreements. Blending limits and certification bottlenecks constrain near-term volume.
- Jet A:Legacy specification persists in domestic Chinese and Indian operations with lower freeze point requirements.
- Synthetic Fuels:Power-to-liquid demonstration projects in Japan and Australia await cost parity breakthroughs for commercial scaling.
Jet A-1 infrastructure represents sunk investment with decades of depreciation remaining. Biofuel blending is gaining share fastest where CORSIA compliance obligations and Singapore green finance incentives align.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the majority of Asia-Pacific engine deliveries while Japan and South Korea concentrate precision manufacturing capabilities. India is emerging as a maintenance hub rather than a production center. Southeast Asian markets function primarily as demand generators through low-cost carrier fleet expansion.
China
State-owned airlines under MIIT mandates are accelerating turbofan procurement from Aero Engine Corporation of China joint ventures. NMPA airworthiness standards progressively favor domestic content in type certification pathways. Shanghai and Xi'an host concentrated engine assembly and hot-section component production facilities serving both commercial and military programs.
Japan
Industrial conglomerates supply precision-cast turbine blades and compressor modules to global OEMs through METI-coordinated research frameworks. JIS certification requirements govern domestic aerospace supplier qualification. Nagoya and Tokyo-Yokohama corridors concentrate IHI Corporation and Mitsubishi Heavy Industries propulsion manufacturing alongside specialized foundry operations.
India
Low-cost carriers IndiGo and AirAsia India are driving narrowbody engine demand through record fleet orders. DGCA type certification alignment with ICAO standards governs import approvals for foreign-manufactured powerplants. Bengaluru and Hyderabad maintenance corridors are attracting foreign direct investment in hot-section overhaul capabilities and specialized technician training.
South Korea
DAPA procurement sustains indigenous fighter engine development programs alongside commercial aerospace component supply. KF-21 Boramae program requirements are accelerating low-bypass turbofan research through domestic industrial partnerships. Busan-Ulsan manufacturing clusters concentrate precision machining for turbine disk and combustor liner production.
Indonesia
Lion Air and Garuda Indonesia fleet modernization is driving turbofan demand across narrowbody and widebody categories. Ground support infrastructure upgrades at Jakarta and Surabaya airports are creating concentrated auxiliary power unit leasing opportunities. Batam and Bintan special economic zones are positioning for MRO investment through regulatory incentives and proximity to Singapore hub capabilities.
Asia-Pacific Aircraft Engine Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific engine value chain. The market structure consolidates around three global OEMs controlling proprietary core architectures, while tier-2 component suppliers fragment across national industrial bases. Strategic archetypes include integrated propulsion system developers, precision superalloy component specialists, and state-backed indigenous programs. Competitive moves concentrate on joint venture restructuring for Chinese market access and power-by-the-hour contract expansion across ASEAN operators.
Within the integrated propulsion tier, GE Aerospace and Pratt & Whitney exemplify global OEM archetypes with established Asia-Pacific aftermarket networks. Rolls-Royce Holdings occupies a position serving widebody long-haul segments between East Asia and Europe. Aero Engine Corporation of China represents the state-backed indigenous developer archetype accelerating domestic content substitution under MIIT mandates.
| Leading Market Players |
|---|
| Rolls-Royce Holdings |
| GE Aerospace |
| Pratt & Whitney |
| Safran Aircraft Engines |
| MTU Aero Engines |
| CFM International |
| Aero Engine Corporation of China |
| IHI Corporation |
| Mitsubishi Heavy Industries |
| Others |
Value Chain & Pricing Dynamics
ICAO CORSIA carbon offset mandates gate qualified supply access and premium-tier pricing for Asia-Pacific engine OEMs, as compliance-certified operators command service contract premiums while non-aligned suppliers face procurement exclusion from Singapore Airlines and Cathay Pacific fleets.
Pricing Analysis
Margin tightening in aftermarket services reflects power-by-the-hour contract saturation across ASEAN low-cost carriers. Three-tier pricing structure across premium OEM-direct, standard joint-venture, and economy third-party overhaul separates certified hot-section refurbishment from uncertified component repair. Pricing pressure intensifies in turboprop segments as India's UDAN scheme operators prioritize capital expenditure minimization. Cargo aviation buyers exhibit lowest price sensitivity due to e-commerce logistics margin structures, while budget narrowbody fleets drive hardest cost-down negotiations.
Supply Chain Analysis
Specialized welder and composite technician scarcity in Vietnam and Philippines MRO facilities constrains throughput expansion. Precision-cast turbine blade supply concentrates in Japan's Nagoya corridor and certified European foundries, with nickel-based superalloy feedstock drawing from Australian and Indonesian mining operations. Single-source vulnerability in high-pressure compressor forging creates structural risk for CFM56 and V2500 mixed-fleet operators. Distribution runs through Singapore and Hong Kong hub warehouses serving Bengaluru and Hyderabad maintenance corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT domestic content mandates construct a cost-of-compliance moat where joint-venture restructuring investments deter marginal competitors, privileging established OEMs with capital depth to absorb technology transfer obligations.
For Market Incumbents: Acquire certified hot-section overhaul capabilities in India's Bengaluru-Hyderabad corridor to anchor aftermarket revenue against Aero Engine Corporation of China's indigenous substitution threat. Deepen backward integration into precision-cast turbine blade supply through METI-coordinated Japanese foundry partnerships, insulating against superalloy supply concentration risk. For New Entrants and Emerging Players: Capture auxiliary power unit leasing white space at Jakarta and Surabaya airport modernization projects, where capital-constrained Indonesian operators favor operational expenditure structures over asset ownership. Target turboprop engine life extension programs for India's UDAN regional connectivity network, positioning through DGCA-aligned certification pathways as the most penetrable entry vector. For Investors and Strategic Acquirers: NMPA type certification acceleration for Aero Engine Corporation of China turbofan modules is the leading indicator that joint-venture restructuring timelines will compress, favoring early positioning in maintenance joint-venture stakes. Long-term viability hinges on exposure to power-by-the-hour contract recurring revenue streams rather than transactional engine sales, with specialized MRO technician training assets representing priority acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Restructuring | MIIT compliance requirements force CFM International and Pratt & Whitney to localize core module production in Shanghai and Xi'an facilities. |
| Power-by-the-Hour Expansion | Recurring revenue capture from VietJet and AirAsia fleets transfers residual value risk from capital-constrained operators to lessors. |
| Hot-Section Overhaul Investment | Foreign direct investment in Bengaluru and Hyderabad addresses certified technician scarcity constraining fleet growth. |
| Hybrid-Electric Propulsion Partnership | METI-coordinated research programs link IHI Corporation with regional airlines for distributed electric architecture development. |
| APU Leasing Model Deployment | Ground support modernization at Jakarta and Surabaya creates concentrated demand for operational expenditure-based procurement. |
Study Parameters
Independent corroboration across engine program directors at ASEAN flag carriers, MRO operations managers in Bengaluru and Hyderabad, and procurement leads at Indonesian low-cost carriers underwrites the qualitative findings. Secondary validation drew from DGCA type certification filings, NMPA airworthiness directives, MIIT domestic content mandates, and ICAO CORSIA implementation guidelines. Bottom-up fleet order aggregation and top-down OEM revenue triangulation anchored market sizing.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by engine architecture, installation type, end-user category, and fuel certification tier. CAGRs derived from fleet expansion backlogs, retirement replacement cycles, and MRO labor capacity constraints. Forecast inputs incorporated MIIT localization phase-in schedules and UDAN scheme route proliferation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA certification timeline shifts and superalloy supply disruption. Forecasts reflect documented assumptions on joint-venture restructuring compliance, technician training pipeline expansion, and CORSIA mandate enforcement. Material deviation in MIIT domestic content thresholds or ICAO carbon offset pricing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Global Aircraft Engine Fuel Systems Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Angle of Attack Sensor Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
General Aviation Engines Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Narrow-Body Turbofan Engine Shop Visit Services Market