
 Global Aircraft Engine Testbed Market | 2026-2036
Global Aircraft Engine Testbed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Engine Testbed Market Foresight
North American aerospace manufacturing clusters is expanding test cell capacity to accommodate next-generation propulsion programs. General Electric leverages its Cincinnati-area test complex to anchor development work for high-bypass turbofan architectures. Rolls-Royce sustains dual-site operations across Indiana and Mississippi, competing for military and commercial validation contracts. Safran specializes in compact testbed configurations for narrow-body engine programs, occupying a distinct niche between full-scale and modular systems.
An aircraft engine testbed comprises instrumented ground facilities designed to measure thrust output, fuel consumption, exhaust emissions, and mechanical durability across controlled operating envelopes; these installations integrate dynamometer load banks, high-speed data acquisition hardware, and environmental conditioning systems to replicate altitude and thermal conditions encountered during flight. Turbofan testbeds dominate capital deployment given the segment's alignment with commercial aviation's dominant propulsion architecture, while hardware-in-the-loop simulation represents the fastest-expanding technology category as digital twin methodologies reduce physical test iterations. Maintenance repair organizations constitute an underdeveloped end-user channel where third-party test capacity could displace captive OEM facilities.
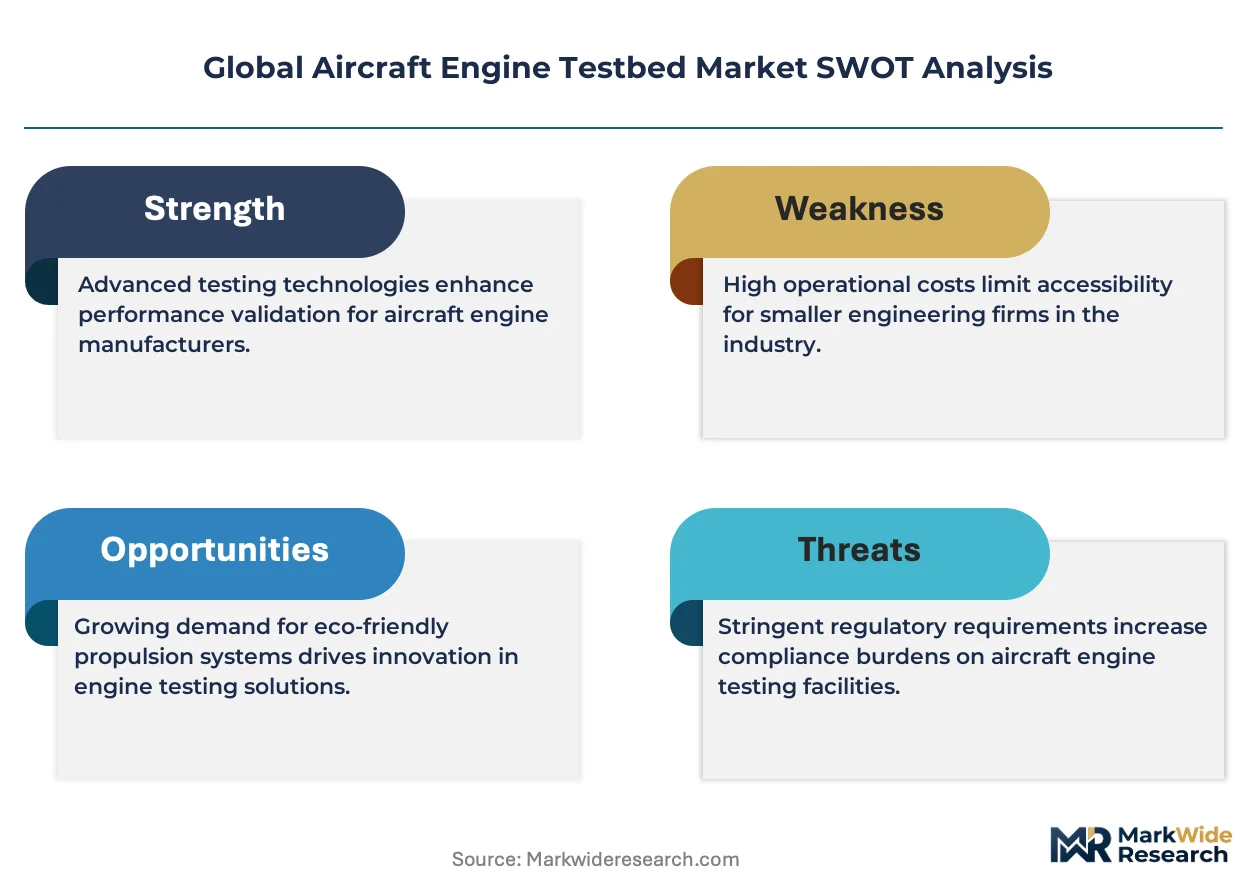
FAA Part 33 airworthiness standards and EASA CS-E certification requirements dictate minimum ground-test durations and failure-mode documentation that directly shape testbed utilization rates and facility investment cycles. The EU Green Deal's Fit for 55 framework and ICAO's Carbon Offsetting and Reduction Scheme for International Aviation are forcing engine manufacturers to expand test regimes for sustainable aviation fuel compatibility and hybrid-electric architectures. Stakeholders must monitor how regulatory divergence between FAA and EASA hydrogen propulsion standards reshapes testbed specification requirements and certification timeline assumptions.
Market Dynamics
Digital twin integration is compressing physical test cycles and forcing testbed operators to retool facilities for hybrid validation workflows that blend hardware-in-the-loop simulation with traditional dynamometer testing.
Growth Catalysts
- FAA Part 33 Certification Expansion:Extended ground-test mandates for new engine architectures are extending facility utilization rates across United States MRO networks.
- Sustainable Aviation Fuel Mandates:EU Green Deal Fit for 55 requirements are compelling manufacturers to validate SAF compatibility through expanded test regimes.
- Hybrid-Electric Propulsion Development:Powertrain electrification programs in Germany and France are generating demand for modified test cell configurations.
Market Restraints
- Specialized Alloy Supply Concentration:High-temperature turbine blade materials sourced from limited Japanese and German suppliers create input cost volatility.
- Site Certification Backlogs:EASA CS-E environmental qualification delays in France and Germany extend facility commissioning timelines.
- Test Cell Construction Cost Escalation:Acoustic hush-house and thrust measurement system integration requires capital intensity that limits new entrant participation.
Strategic Opportunities
- Third-Party MRO Test Capacity:Independent maintenance networks in Poland and Turkey represent underpenetrated channels that could displace captive OEM facilities.
- Hydrogen Propulsion Test Regimes:Cryogenic fuel system validation requirements are creating white space for specialized testbed configurations.
- India Defense Procurement:Indigenous fighter engine programs under DRDO oversight are stimulating greenfield test infrastructure investment.
Industry Challenges
- Simulation Engineer Talent Scarcity:Hardware-in-the-loop platform expertise gaps in United Kingdom and Italy constrain digital twin deployment velocity.
- Legacy Control System Integration:1990s-era data acquisition architectures in established United States facilities resist seamless digital twin interfacing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Engine Testbed Market |
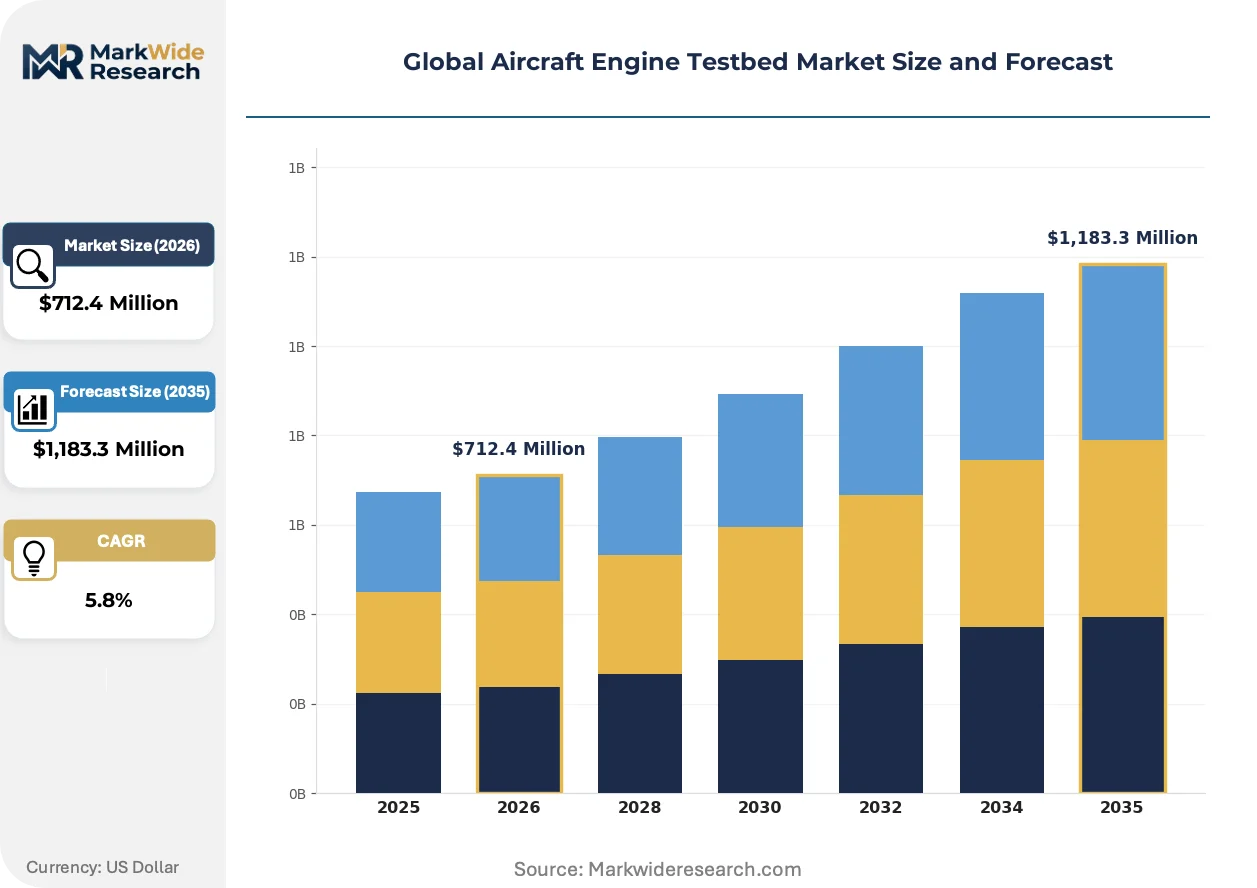
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,183.3 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbofan Testbeds, Turbojet Testbeds, Turboprop Testbeds, Ramjet Testbeds, Rocket Engine Testbeds Technology: Hardware-in-the-Loop Simulation, Real-Time Data Acquisition, Vibration Monitoring, Thermal Control Systems, Acoustic Analysis Application: Commercial Aviation, Military Aviation, Unmanned Aerial Vehicles, Spacecraft Propulsion, Research & Development Facilities End User: Original Equipment Manufacturers, Maintenance Repair Organizations, Aerospace Research Institutes, Flight Training Centers |
| Companies Covered | Honeywell International, Raytheon Technologies Corporation, General Electric, Rolls-Royce, Safran, CFM International, Pratt & Whitney, Nidec Industrial Solutions, Atec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Engine Testbed Market Shifts & Advancements
Test methodology convergence is blurring boundaries between physical validation and virtual simulation, compressing development timelines while raising precision requirements for ground-based measurement systems.
Hardware-in-the-loop simulation platforms are unifying real-time engine controller testing with virtual atmospheric condition modeling. Tier-1 suppliers in Germany and Japan are adopting these systems at accelerating pace to reduce full-scale test cell occupancy. The technology is unifying development workflows across turbofan and hybrid-electric programs, collapsing traditional stage-gate intervals.
EASA CS-E certification amendments for hydrogen combustion systems are mandating novel exhaust emission measurement protocols. Test facilities must install modified gas analysis instrumentation to capture cryogenic fuel combustion byproducts. European engine development centers in France and Germany are retrofitting existing cells ahead of anticipated 2028-2030 certification deadlines.
Power-by-the-hour service contracts are restructuring how airlines access validation data. Carriers now demand real-time test telemetry rather than summary certification reports, forcing testbed operators to deploy cloud-connected data pipelines. This pattern is most visible in United States and United Kingdom carrier procurement, where maintenance cost predictability drives information requirements.
Global Aircraft Engine Testbed Market Segmentation
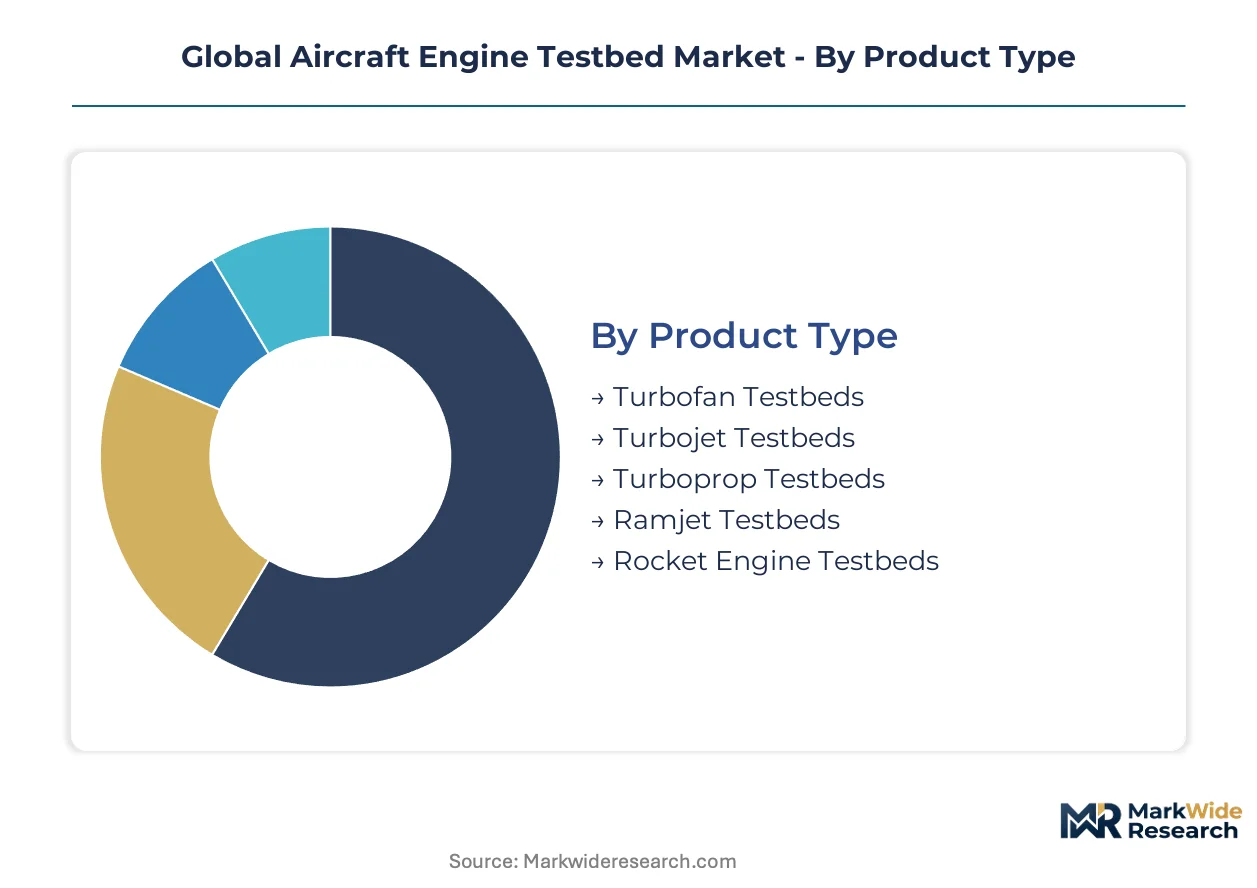
Testbed specification varies sharply across propulsion architectures and validation methodologies. Segmentation reveals how capital allocation concentrates in turbofan infrastructure while emerging technologies reshape facility design requirements.
Product Type:
Technical specifications diverge based on thrust class, thermal envelope, and exhaust management requirements.
- Turbofan Testbeds:These installations incorporate high-bypass ducting and bypass ratio measurement systems for engines exceeding 50,000 pounds thrust. Demand concentrates in the United States and France where Boeing and Airbus supplier networks sustain continuous validation cycles for next-generation narrow-body programs.
- Turbojet Testbeds:Compact axial-flow configurations dominate military fighter engine validation with simplified inlet conditioning and afterburner flameholder instrumentation. Procurement clusters in India and Turkey where indigenous combat aircraft programs are stimulating greenfield test infrastructure investment.
- Turboprop Testbeds:Shaft power measurement and propeller dynamometer integration characterize these lower-thrust facilities.
- Ramjet Testbeds:Supersonic combustion direct-connect rigs require specialized arc-heater or vitiated air heater subsystems.
- Rocket Engine Testbeds:Cryogenic propellant handling and regenerative cooling measurement dominate liquid-fueled variants.
Mature deployment sits with turbofan configurations. Newer deployment is concentrated in turboprop and rocket engine variants serving regional aviation and space launch segments.
Technology:
Capital intensity escalates with simulation fidelity and measurement bandwidth requirements.
- Hardware-in-the-Loop Simulation:Real-time processor-in-the-loop architectures integrate physical engine controllers with virtual atmospheric models, compressing development timelines. German and Japanese Tier-1 suppliers are expanding these platforms fastest to reduce full-scale test cell occupancy.
- Real-Time Data Acquisition:High-channel-count PXI-based systems capture transient combustion events at microsecond resolution. United States facilities lead adoption where FAA Part 33 documentation requirements mandate comprehensive failure-mode telemetry.
- Vibration Monitoring:Blade tip timing and casing-mounted accelerometer networks track rotor-dynamic stability.
- Thermal Control Systems:Altitude simulation chambers replicate stratospheric temperature profiles.
- Acoustic Analysis:Far-field microphone arrays and near-field pressure transducers quantify noise certification metrics.
Established infrastructure prioritizes thermal control and acoustic measurement. Hardware-in-the-loop platforms are climbing the fastest as digital twin methodologies displace physical test iterations.
Application:
End-use specifications determine test cell scale, instrumentation density, and regulatory oversight intensity.
- Commercial Aviation:Extended endurance testing and emissions certification dominate utilization schedules. United States and European MRO networks are expanding capacity to accommodate sustainable aviation fuel compatibility validation under EU Green Deal mandates.
- Military Aviation:Classified test regimes and accelerated mission profile simulation drive facility security requirements. India's DRDO-sponsored fighter engine programs are stimulating dedicated test infrastructure outside traditional Western supply chains.
- Unmanned Aerial Vehicles:Compact thrust classes and rapid test turnaround characterize small-turbine validation.
- Spacecraft Propulsion:Vacuum condition simulation and extended burn duration testing define facility specifications.
- Research & Development Facilities:Flexible configurations accommodate experimental propulsion architectures including hydrogen combustion and hybrid-electric systems.
Commercial aviation anchors installed base economics. Research and development facilities are gaining share fastest as powertrain electrification programs proliferate.
End User:
Procurement authority and facility access models segment sharply across the value chain.
- Original Equipment Manufacturers:Captive test complexes in the United States, United Kingdom, and France sustain proprietary validation workflows. General Electric, Rolls-Royce, and Safran maintain dedicated capacity that limits third-party penetration.
- Maintenance Repair Organizations:Independent networks in Poland and Turkey represent underdeveloped channels where outsourced test capacity could displace OEM-controlled facilities.
- Aerospace Research Institutes:NASA Glenn Research Center and German DLR facilities anchor public-sector validation infrastructure.
- Flight Training Centers:Engine familiarization rigs with reduced thrust measurement precision serve operational training requirements.
Original equipment manufacturers retain mature deployment concentration. Maintenance repair organizations are emerging as the fastest-expanding channel as power-by-the-hour contracts restructure validation data access models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-temperature alloy supply chains from Japanese and German specialty metal producers anchor testbed construction economics across major aerospace manufacturing clusters. Facility investment concentrates where OEM final assembly lines and military procurement programs create sustained validation demand.
United States
Boeing's supplier network and NASA Glenn Research Center sustain concentrated test infrastructure investment across the Midwest and Pacific Northwest. FAA Part 33 certification mandates drive extended ground-test cycles for next-generation turbofan architectures. Cincinnati-area complexes anchor General Electric's high-bypass development work alongside Indiana and Mississippi dual-site operations competing for military validation contracts.
France
Airbus supplier ecosystems and Safran's compact testbed specialization sustain validation capacity concentrated around Toulouse and Paris-Saclay corridors. EASA CS-E environmental qualification protocols shape facility commissioning timelines for narrow-body engine programs. EASA amendments for hydrogen combustion systems are mandating retrofits to existing cells ahead of anticipated certification deadlines.
Germany
Powertrain electrification programs in Bavaria and Baden-Württemberg generate demand for modified test cell configurations serving hybrid-electric propulsion development. DLR facilities anchor public-sector validation infrastructure alongside Tier-1 supplier adoption of hardware-in-the-loop platforms. EU Green Deal Fit for 55 requirements compel SAF compatibility validation through expanded test regimes.
United Kingdom
Rolls-Royce maintains dedicated captive capacity limiting third-party penetration across Derby and Bristol engineering centers. Hardware-in-the-loop platform expertise gaps constrain digital twin deployment velocity relative to German and Japanese adoption rates. Power-by-the-hour contracts from carriers are forcing cloud-connected data pipeline deployment for real-time test telemetry access.
India
DRDO-sponsored fighter engine programs stimulate greenfield test infrastructure investment outside traditional Western supply chains. Indigenous combat aircraft development concentrates procurement in Bengaluru and Hyderabad defense manufacturing corridors. Site certification backlogs for environmental qualification extend facility commissioning timelines relative to established aerospace markets.
Global Aircraft Engine Testbed Market Competitive Landscape
Global majors compete with regional champions across testbed specification and certification service provision. The vendor base organizes around three strategic tiers: integrated aerospace conglomerates operating captive facilities, specialized test equipment fabricators supplying instrumentation subsystems, and emerging third-party validation providers targeting MRO channel displacement. Dominant competitive moves include strategic partnerships between OEMs and national research institutes, plus geographic expansion into underpenetrated maintenance networks.
Among integrated aerospace conglomerates, General Electric, Rolls-Royce, and Safran exemplify the captive-facility archetype where proprietary validation workflows limit external testbed procurement. These entities occupy positions between full-scale turbofan installations and compact narrow-body configurations, representing distinct specialization vectors within the broader market structure.
| Leading Market Players |
|---|
| Honeywell International |
| Raytheon Technologies Corporation |
| General Electric |
| Rolls-Royce |
| Safran |
| CFM International |
| Pratt & Whitney |
| Nidec Industrial Solutions |
| Atec |
| Others |
Supply & Pricing Matrix
Sovereign-backed aerospace research institutes anchor testbed construction economics, linking facility ownership patterns to both specialized alloy procurement discipline and long-term pricing stability for validation services.
Pricing Analysis
Warranty and service bundling separates captive OEM test capacity from third-party MRO offerings, with power-by-the-hour contracts commanding premium pricing for real-time telemetry access. Three-tier pricing structure across certification-grade, standard validation, and economy test-cell rental levels reflects thrust-class segmentation and instrumentation density. Pricing pressure stems from EASA CS-E environmental qualification delays extending facility commissioning timelines and inflating capital recovery schedules. Independent MRO networks in Poland and Turkey exhibit highest price sensitivity, while Airbus and Boeing supplier ecosystems prioritize certification speed over unit cost.
Supply Chain Analysis
Regional distribution centers for high-temperature turbine blade alloys concentrate in Japan and Germany, feeding manufacturing clusters across the United States, France, and the United Kingdom. Testbed construction draws from nickel-based superalloys, precision dynamometer load banks, and cryogenic fuel handling systems as critical inputs. Single-source vulnerability in Japanese specialty metal suppliers creates exposure to input cost volatility and extended lead times. Distribution runs through OEM-proprietary channels for captive facilities, while modular test equipment flows via Tier-1 supplier networks to independent MRO operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where FAA Part 33 and EASA CS-E certification mandates erect substantial barrier-to-entry moats favoring incumbents with established regulatory relationships and amortized facility investments.
For Market Incumbents: Lock in long-term validation contracts with next-generation propulsion programs before hydrogen combustion certification protocols finalize. Expand hardware-in-the-loop simulation capacity in Germany and Japan to preempt digital twin disruption of traditional test cell utilization. Secure backward integration into high-temperature alloy supply through offtake agreements with Japanese specialty metal producers to neutralize input cost volatility threatening margin structures.
For New Entrants and Emerging Players: EASA CS-E amendments for hydrogen combustion systems in France and Germany open a window for specialized cryogenic test cell configurations ahead of 2028-2030 certification deadlines. Target third-party MRO channels in Poland and Turkey where outsourced validation demand exceeds indigenous test capacity. Pursue joint development agreements with DRDO-sponsored programs in India to establish reference installations outside Western OEM supply chains.
For Investors and Strategic Acquirers: Distressed-cycle entries favor modular test equipment fabricators with hardware-in-the-loop platform expertise in the United Kingdom and Italy, where simulation engineer talent scarcity constrains digital twin deployment velocity. Prioritize assets with established EASA environmental qualification credentials over greenfield development exposure to site certification backlogs. Monitor FAA-EASA regulatory divergence on hydrogen propulsion standards as the critical inflection signal for testbed specification requirements and certification timeline assumptions.
| Strategic Initiative | Industry Significance |
|---|---|
| Hardware-in-the-Loop Platform Integration | Reduces physical test iterations for GE and Rolls-Royce development programs. |
| Hydrogen Combustion Test Cell Retrofit | Positions Safran and DLR facilities ahead of EASA 2028-2030 certification deadlines. |
| Third-Party MRO Channel Expansion | Enables Polish and Turkish networks to displace captive OEM validation capacity. |
| High-Temperature Alloy Supply Agreement | Secures Japanese and German specialty metal flows for US and European testbed construction. |
| Real-Time Telemetry Cloud Pipeline | Supports power-by-the-hour contracts from United States and United Kingdom carriers. |
Research Methodology
Document review covered FAA Part 33 certification filings, EASA CS-E amendment drafts, and NASA Glenn Research Center procurement records, complemented by interviews with testbed operations directors at General Electric and Rolls-Royce, MRO procurement leads in Poland and Turkey, and simulation platform engineers at German Tier-1 suppliers. Secondary validation drew from SEC 10-K disclosures of listed aerospace conglomerates, EU Green Deal implementation progress reports, and DRDO defense procurement notifications. Bottom-up facility investment tracking and top-down market sizing triangulated volume estimates across the analysis window.
Cross-referencing historical test cell commissioning timelines against expert panel input on hydrogen propulsion certification requirements shaped the projection framework. Segmentation modeling captured propulsion architecture, technology category, application vertical, and end-user channel dimensions throughout the forecast period. CAGRs derived from facility utilization rate trajectories, regulatory mandate expansion schedules, and sustainable aviation fuel compatibility validation demand curves.
The model assumes a particular technology adoption path for hardware-in-the-loop simulation; alternative pathways for full-scale physical testing persistence would alter the outlook for test cell occupancy rates and capital deployment patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Gas Turbine Service Market
Aircraft Engine Systems and Services
Aero Engine Coatings Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
America Aircraft Engines Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Aircraft Engine Nacelle Market
Aircraft Engine Systems and Services
Narrow-Body Turbofan Engine Shop Visit Services Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market