
 America Aircraft Engines Market | 2026-2036
America Aircraft Engines Market Size, Share, and Industry Trends Forecast 2026-2036
America Aircraft Engines Market Outlook
Aftermarket service channels for engine overhaul and component repair is tilting toward OEM-controlled networks and authorized service centers. General Electric Company leverages its vertical integration into materials science and additive manufacturing to capture high-margin maintenance contracts. Pratt & Whitney sustains competitive pressure through its geared turbofan technology leadership and entrenched position in narrowbody platforms. CFM International anchors the single-aisle segment with its dominant LEAP engine family, controlling access to the highest-volume production lines at Boeing and Airbus.
Aircraft engines are gas turbine powerplants that convert thermal energy from fuel combustion into mechanical thrust through compressed air expansion, typically operating at pressure ratios exceeding 40:1 in modern turbofan architectures and sustaining core temperatures above 1,400°C using single-crystal superalloy blades. Their primary purpose is propelling fixed-wing and rotary-wing aircraft across commercial, military, and general aviation missions while meeting stringent fuel efficiency and emissions benchmarks. Turbofan technology dominates installed base value across the Americas, with widebody and narrowbody platforms generating the deepest aftermarket revenue pools. Biofuel compatibility is emerging as a critical differentiator among fuel type segments, as operators face mounting pressure to certify engines for sustainable aviation fuel blends. Commercial aviation end users command the largest share of new engine deliveries, though military aviation exhibits faster procurement velocity driven by fighter and transport modernization programs.
FAA certification requirements under Part 33 govern airworthiness standards for all engines operating in United States airspace, while EPA regulations on aircraft emissions constrain allowable nitrogen oxide and particulate thresholds for new type designs. The IRA provides production tax credits for sustainable aviation fuel that indirectly shape engine manufacturer R&D priorities toward higher blend tolerance. Stakeholders must monitor how quickly FAA biofuel certification pathways mature, as this timing will determine which engine platforms secure retrofit advantages versus obsolescence risk.
Market Dynamics
FAA Part 33 certification pathways for sustainable aviation fuel blends are compressing engine design cycles and forcing manufacturers to prioritize thermal tolerance over incremental efficiency gains.
Growth Catalysts
- Defense Procurement Acceleration:Military aviation modernization programs across the Americas are replacing legacy fighter and transport platforms. The Pentagon's multi-year procurement commitments stabilize production planning for engine OEMs.
- SAF Blend Mandates:The IRA production tax credits for sustainable aviation fuel are redirecting R&D investment toward higher thermal tolerance architectures. Engine manufacturers must certify existing platforms for 100% SAF compatibility.
- Fleet Replacement Cycles:Narrowbody fleet age profiles in the United States are triggering wave replacements. Domestic carriers face mounting pressure to retire pre-2000 engine architectures for noise and emissions compliance.
Market Restraints
- Single-Crystal Superalloy Concentration:Supply of nickel-based turbine blade materials concentrates among a handful of specialty foundries. Disruptions to cobalt or rhenium supply chains cascade through production schedules.
- Certification Timeline Friction:FAA Part 33 amendment cycles for new propulsion architectures extend 18-36 months beyond initial projections. This regulatory lag penalizes novel engine configurations against derivative designs.
- Additive Manufacturing Scale Limits:Laser powder bed fusion for complex turbine components remains throughput-constrained. Build chamber sizes and post-processing bottlenecks prevent full-scale production of large structural castings.
Strategic Opportunities
- Canadian Arctic Operations:Cold-weather performance specifications for northern routes remain underdeveloped. Engine manufacturers can capture niche positioning through enhanced cold-start architectures and ice ingestion tolerance.
- Urban Air Mobility Convergence:Hybrid-electric distributed propulsion is hybridizing turbine core designs with electric motor augmentation. This technology pairing opens entirely new airframe integration partnerships beyond traditional OEM relationships.
- MRO Network Consolidation:Authorized service center networks are capturing overhaul volume previously fragmented across independent shops. OEM-controlled maintenance channels secure captive aftermarket revenue streams.
Industry Challenges
- Turbine Aerodynamicist Shortage:Specialized computational fluid dynamics expertise for high-pressure compressor design remains scarce. Universities produce fewer graduates with gas turbine-specific training than replacement demand requires.
- Legacy Fleet Interoperability:New engine architectures must maintain backward compatibility with existing maintenance infrastructure. Ground support equipment and tooling investments create switching costs that slow technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | America Aircraft Engines Market |
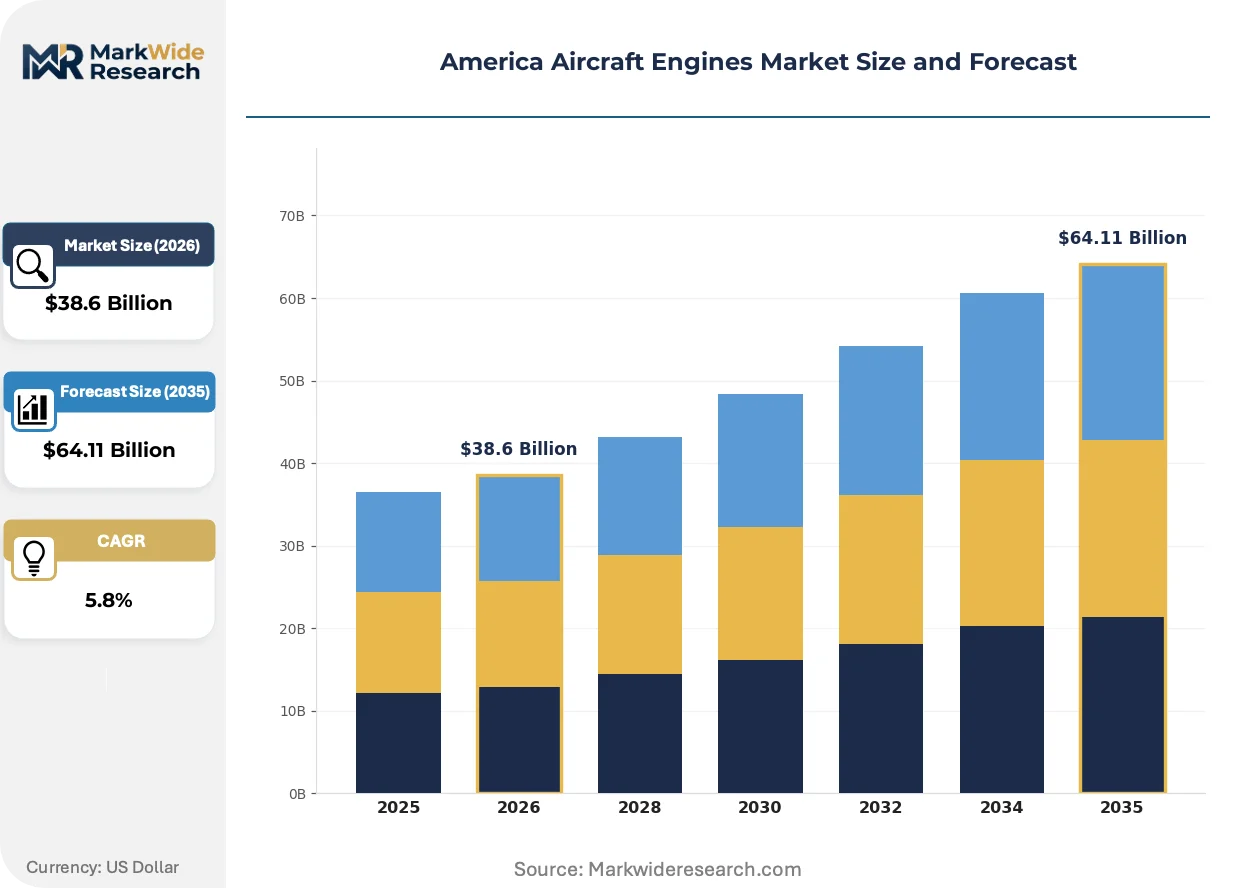
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Turbojet, Turbofan, Turboprop, Turboshaft End User: Commercial Aviation, Military Aviation, Business Aviation, General Aviation Fuel Type: Jet A, Jet A-1, Avgas, Biofuel Maintenance Type: Line Maintenance, Base Maintenance, Overhaul, Modifications |
| Companies Covered | General Electric Company, Pratt & Whitney, CFM International, Rolls-Royce plc, Safran, Honeywell International Inc, MTU Aero Engines, Continental Aerospace Technologies, Inc., BRP-Rotax GmbH & Co KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
America Aircraft Engines Market Strategic Shifts
Propulsion architecture is converging around thermal management breakthroughs and digital thread integration, compressing development cycles while raising certification complexity.
Additive manufacturing of nickel superalloy turbine components is hybridizing traditional casting methods with topology-optimized geometries. Military engine programs are adopting these processes fastest for low-volume, high-complexity parts. This manufacturing shift is compressing lead times for prototype iterations while demanding new non-destructive testing protocols.
FAA Part 33 emissions amendments are tightening nitrogen oxide thresholds for new type certificates. Engine manufacturers must redesign combustor architectures to meet these limits without sacrificing thermal efficiency. The narrowbody segment faces the steepest compliance cost burden given production volume exposure.
Airline procurement departments are unbundling engine overhaul contracts from initial power-by-the-hour agreements. Large North American carriers now negotiate line-item maintenance pricing separately from flight-hour coverage. This buying-pattern shift is most visible among ultra-low-cost operators seeking balance-sheet flexibility over operational simplicity.
America Aircraft Engines Market Segmentation
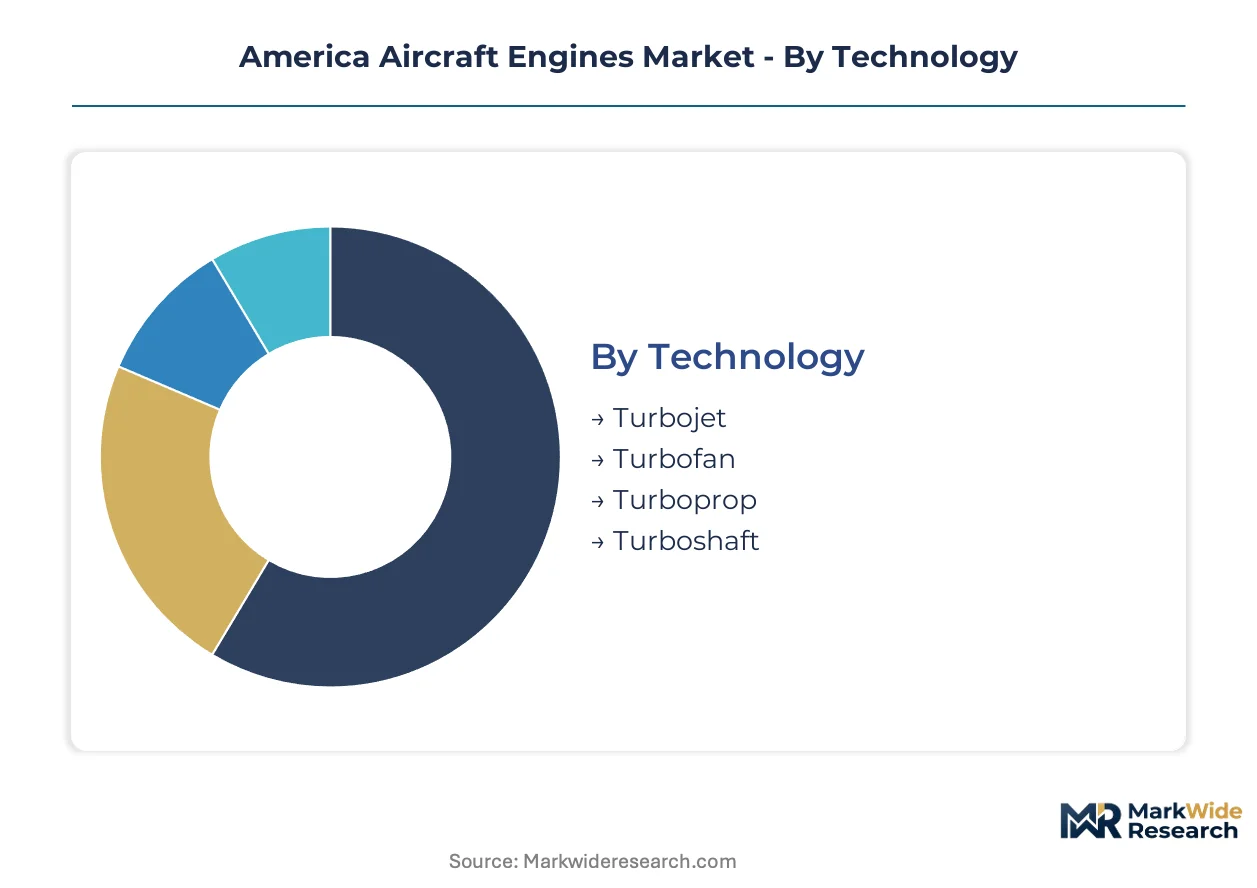
Aircraft engine segmentation reveals distinct technology-performance tradeoffs and regulatory compliance requirements across the Americas. Each dimension—propulsion architecture, operator mission profile, fuel chemistry, and maintenance intensity—commands specialized supply chain configurations and certification pathways.
Technology:
Use-case spectrum spans from high-thrust commercial transport to low-speed utility aviation, with thermal efficiency and bypass ratio defining competitive positioning.
- Turbofan:High-bypass architectures dominate commercial aviation with pressure ratios exceeding 40:1 and core temperatures above 1,400°C. Demand concentrates in United States narrowbody fleet replacements driven by FAA noise and emissions compliance deadlines.
- Turbojet:Pure jet designs retain military fighter applications where supersonic performance outweighs fuel efficiency penalties. Procurement velocity accelerates across Pentagon modernization programs for next-generation combat aircraft.
- Turboprop:Gas turbine core driving propeller systems serves regional connectivity and cargo operations across Canadian Arctic routes and Latin American remote airfields.
- Turboshaft:Power extraction designs for rotary-wing platforms support helicopter emergency medical services and offshore oil transport in Gulf Coast operations.
The dominant share belongs to Turbofan, while Turboshaft is closing the gap fastest through urban air mobility hybrid applications.
End User:
Cost tier stratification separates capital-intensive scheduled carriers from mission-critical defense procurement and discretionary private aviation.
- Commercial Aviation:Scheduled airlines and cargo operators generate the deepest aftermarket revenue pools through power-by-the-hour contracts. United States domestic carriers drive replacement cycles as pre-2000 engine architectures face retirement.
- Military Aviation:Fighter, transport, and tanker platforms exhibit faster procurement velocity than commercial segments. Multi-year Pentagon commitments stabilize production planning for engine OEMs despite budget cycle volatility.
- Business Aviation:Corporate and fractional ownership fleets prioritize dispatch reliability over unit economics. Demand clusters in Texas and Florida hubs serving executive travel corridors.
- General Aviation:Private pilot and flight training operations represent price-sensitive volume with limited aftermarket capture. Training fleet renewals in Arizona and California flight schools sustain piston-to-turbine upgrade demand.
Commercial Aviation holds the dominant share, though Military Aviation is expanding most quickly through accelerated modernization timelines.
Fuel Type:
Application maturity and certification burden create margin differentiation across conventional and emerging fuel chemistries.
- Jet A:Kerosene-based standard for United States commercial aviation with established supply infrastructure and cold-weather performance specifications. Refining capacity concentrates along Gulf Coast petrochemical corridors.
- Jet A-1:Lower freeze-point variant required for Canadian Arctic operations and high-altitude routes. Transborder carriers operating Toronto-Chicago corridors maintain dual-fuel logistics.
- Avgas:High-octane aviation gasoline serves piston-engine general aviation with leaded formulations facing EPA phaseout pressure. California and Washington state regulators are advancing earliest transition mandates.
- Biofuel:Sustainable aviation fuel blends are redirecting R&D investment toward higher thermal tolerance architectures. IRA production tax credits are accelerating blend certification through FAA Part 33 pathways.
Jet A retains the dominant share, while Biofuel is gaining share fastest through regulatory mandate momentum.
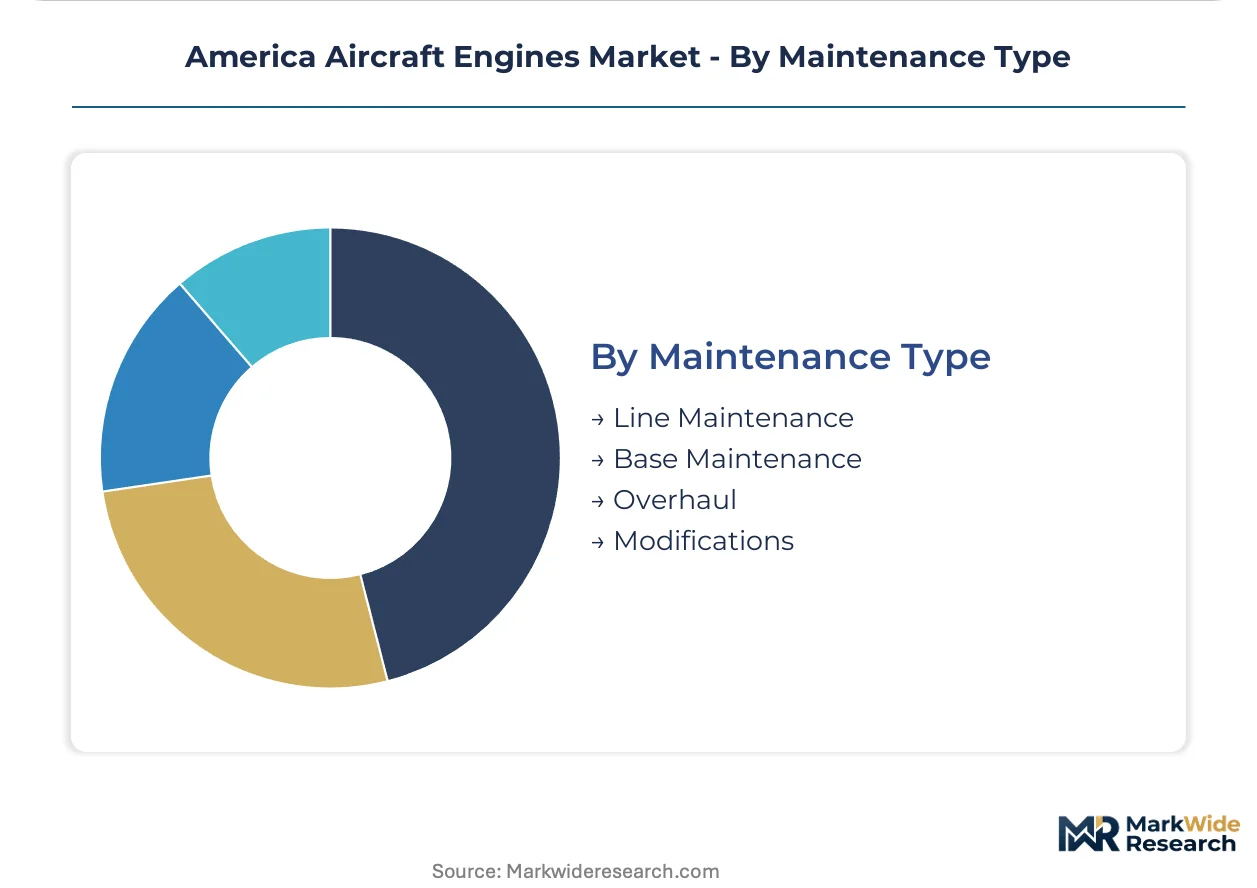
Maintenance Type:
Customer type and fleet scale determine whether operators prioritize operational continuity or balance-sheet flexibility.
- Overhaul:Complete engine disassembly and component restoration captures the highest revenue per event. OEM-controlled networks are consolidating previously fragmented independent shop volume.
- Base Maintenance:Heavy checks and structural inspections occur at fixed intervals independent of flight hours. United States MRO hubs in Oklahoma and Texas compete on turnaround speed.
- Line Maintenance:Pre-flight and transit checks ensure airworthiness between revenue flights. Ultra-low-cost carriers unbundle these services from power-by-the-hour agreements.
- Modifications:Retrofit installations of noise-reduction kits and emissions compliance hardware extend fleet economic life. Aging narrowbody platforms in Latin American operator fleets sustain this segment.
Overhaul commands the dominant share, with Modifications climbing the fastest as legacy fleet extension economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Panama Canal's lock system underwrites Latin American aviation logistics, while the Trans-Alaska Pipeline System anchors Arctic route development. These infrastructure assets shape engine demand patterns across the Americas.
United States
The Pentagon's multi-year procurement commitments drive fighter and transport engine replacements. FAA Part 33 certification pathways compress design cycles for sustainable aviation fuel compatibility. Oklahoma and Texas MRO hubs compete on overhaul turnaround speed for domestic narrowbody fleets.
Canada
Arctic route expansion demands cold-weather performance specifications for turboprop platforms. Transport Canada mandates enhanced ice ingestion tolerance for northern operations. Montreal's aerospace cluster concentrates engine R&D investment toward hybrid-electric distributed propulsion systems.
Brazil
Embraer's regional jet production sustains turbofan demand for Latin American connectivity. ANVISA-aligned environmental regulations pressure fleet modernization timelines. São Paulo state's manufacturing corridor anchors component supply relationships with North American OEMs.
Mexico
Nearshoring trends accelerate maintenance facility investments for US carrier fleets. The Secretariat of Infrastructure, Communications and Transportation oversees bilateral aviation agreements affecting engine certification reciprocity. Querétaro's aerospace park hosts specialized turbine component machining operations.
America Aircraft Engines Market Competitive Environment
On the supply side, the industry is consolidated around a tight oligopoly of full-system integrators with deep aftermarket capture. Three strategic archetypes dominate: vertically integrated conglomerates controlling materials science through maintenance networks, technology specialists leveraging proprietary architectures, and joint ventures pooling development costs across airframe partnerships. Competitive moves center on M&A for additive manufacturing capabilities and strategic partnerships for urban air mobility propulsion systems.
Within the integrated systems tier, General Electric Company and Pratt & Whitney exemplify full-stack manufacturers with captive maintenance channels. CFM International occupies a distinctive position as a transatlantic joint venture anchoring narrowbody platform access. These three entities collectively represent the concentration of turbofan technology leadership and aftermarket revenue capture across the Americas.
| Leading Market Players |
|---|
| General Electric Company |
| Pratt & Whitney |
| CFM International |
| Rolls-Royce plc |
| Safran |
| Honeywell International Inc |
| MTU Aero Engines |
| Continental Aerospace Technologies, Inc. |
| BRP-Rotax GmbH & Co KG |
| Others |
Value Chain & Pricing Dynamics
Single-crystal superalloy supply concentration among specialty foundries in the United States and Europe compresses pricing tier spreads between OEM-controlled maintenance networks and independent overhaul shops while simultaneously forcing engine manufacturers toward backward integration into additive manufacturing capabilities.
Pricing Analysis
Volume-discount tiering structures separate Pentagon multi-year procurement commitments from spot-market commercial airline orders. Price differentiation centers on thermal tolerance certification grades for sustainable aviation fuel compatibility and aftermarket service bundling through power-by-the-hour contracts. Cost compression in narrowbody engine segments is intensifying as ultra-low-cost carriers unbundle maintenance pricing from flight-hour coverage. Military aviation procurement departments exhibit the lowest price sensitivity given mission-critical requirements, while general aviation operators demonstrate acute sensitivity to unit economics.
Supply Chain Analysis
Export-control regime restrictions under ITAR and EAR limit flows of single-crystal casting technology and powder metallurgy processes to foreign maintenance facilities. Geographic supply concentration centers on United States specialty foundries, German precision machining clusters, and Japanese superalloy suppliers. Raw material dependencies draw from cobalt and rhenium mining operations, nickel-based superalloy feedstock, and ceramic thermal barrier coatings. Single-source vulnerability pervades turbine blade casting capacity. Distribution runs through OEM-authorized service center networks consolidating previously fragmented independent MRO channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The America Aircraft Engines Market sits at a cyclical recovery phase driven by narrowbody fleet replacement cycles triggered by FAA emissions compliance deadlines.
For Market Incumbents: Insulate aftermarket revenue streams by deepening captive maintenance network control against independent shop competition. Accelerate certification investment for 100% sustainable aviation fuel compatibility to preempt regulatory obsolescence of legacy architectures. Backward integration into additive manufacturing of nickel superalloy components reduces dependency on specialty foundry capacity.
For New Entrants and Emerging Players: Pursue urban air mobility hybrid-electric propulsion partnerships where traditional OEM relationships remain unformed. Canadian Arctic cold-weather performance specifications represent the most penetrable niche given underdeveloped turboprop architectures. Target direct airframe integration contracts bypassing established engine-airframe bundling structures.
For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors additive manufacturing capability acquisition over pure-play engine development. Long-term viability over the coming decade rests on thermal tolerance technology leadership and SAF certification positioning. Acquisition target archetypes include laser powder bed fusion specialists and ceramic matrix composite developers. The signal to watch is FAA Part 33 amendment timing for 100% biofuel pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF Certification Investment | FAA Part 33 pathway completion secures retrofit advantages against obsolescence risk for existing engine platforms. |
| Additive Manufacturing Scale-Up | Laser powder bed fusion capacity expansion reduces lead times for nickel superalloy turbine component production. |
| Urban Air Mobility Partnership | Hybrid-electric distributed propulsion alliances open airframe integration channels beyond traditional Boeing and Airbus relationships. |
| MRO Network Consolidation | Authorized service center acquisition captures overhaul volume from fragmented independent maintenance shops. |
| Arctic Operations Specification | Enhanced cold-start architecture development addresses Transport Canada mandates for northern route ice ingestion tolerance. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FAA certification databases, Pentagon procurement disclosures, and engine OEM technical filings. Primary interviews engaged fleet planning executives at scheduled carriers, aftermarket service directors at MRO facilities, and procurement officers within defense acquisition programs. Secondary validation drew from EPA emissions compliance records, Department of Energy sustainable aviation fuel production data, and SEC filings from publicly traded engine manufacturers. Bottom-up triangulation across individual platform demand curves and top-down reconciliation against fleet replacement schedules anchored value estimates.
Forecast inputs incorporate narrowbody and widebody delivery schedules, military modernization program commitments, and sustainable aviation fuel blend mandate trajectories. Segmentation dimensions modeled include propulsion architecture, end-user mission profile, fuel chemistry compatibility, and maintenance intensity across the projection horizon. CAGRs derive from regression analysis against historical fleet age distributions and regulatory compliance deadline clustering. Industry-specific inputs include turbine aerodynamicist labor supply constraints and single-crystal superalloy foundry capacity utilization.
Sensitivities concentrate around FAA Part 33 amendment timing, cobalt and rhenium supply disruptions, and Pentagon budget cycle volatility. Forecasts reflect documented assumptions regarding sustainable aviation fuel production scale-up and additive manufacturing throughput expansion. Material shifts in biofuel certification pathways or export-control regime tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Aero Engine Coatings Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Global Aircraft Engine Fuel Systems Market
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Aircraft Engine Nacelle Market