
 Aerospace Engine Mounts Market | 2026-2036
Aerospace Engine Mounts Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Engine Mounts Market Insights
Active vibration control integration with sensor-fed adaptive damping is reshaping how engine mount systems are architected for next-generation turbofans. LORD Corporation leverages its polymer science heritage to sustain leadership in elastomeric isolator formulations for high-bypass engines. Trelleborg AB anchors European supply through specialized rubber-to-metal bonding expertise certified to EASA standards. Parker Hannifin competes across hydraulic and pneumatic mount architectures, extending its motion control portfolio into propulsion isolation.
Aerospace engine mounts are structural load-bearing assemblies that secure turbine engines to wing pylons or fuselage frames, incorporating elastomeric layers, fluid chambers, or piezoelectric actuators to attenuate vibratory loads and accommodate thermal expansion across operational envelopes. Aluminum alloy and titanium alloy material segments dominate current production due to their strength-to-weight ratios and established forge-and-machine supply chains, though composite materials represent the fastest-growing category as automated fiber placement reduces recurring cost for complex load paths. Commercial aircraft application segment absorbs the largest volume share, while unmanned aerial vehicles emerge as a concentrated margin pool where low-volume, high-customization contracts resist commoditization.
FAA Part 25 airworthiness requirements and EASA CS-25 certification standards govern structural integrity and fatigue life demonstration for engine mount installations, with both agencies intensifying scrutiny of elastomer aging in extended operations. The EPA and REACH frameworks indirectly shape material selection through restrictions on certain curing agents and flame-retardant additives used in polymer compounds. Stakeholders must monitor evolving FAA special conditions for active control systems and position qualification investments ahead of anticipated rulemaking on adaptive damping architectures.
Market Dynamics
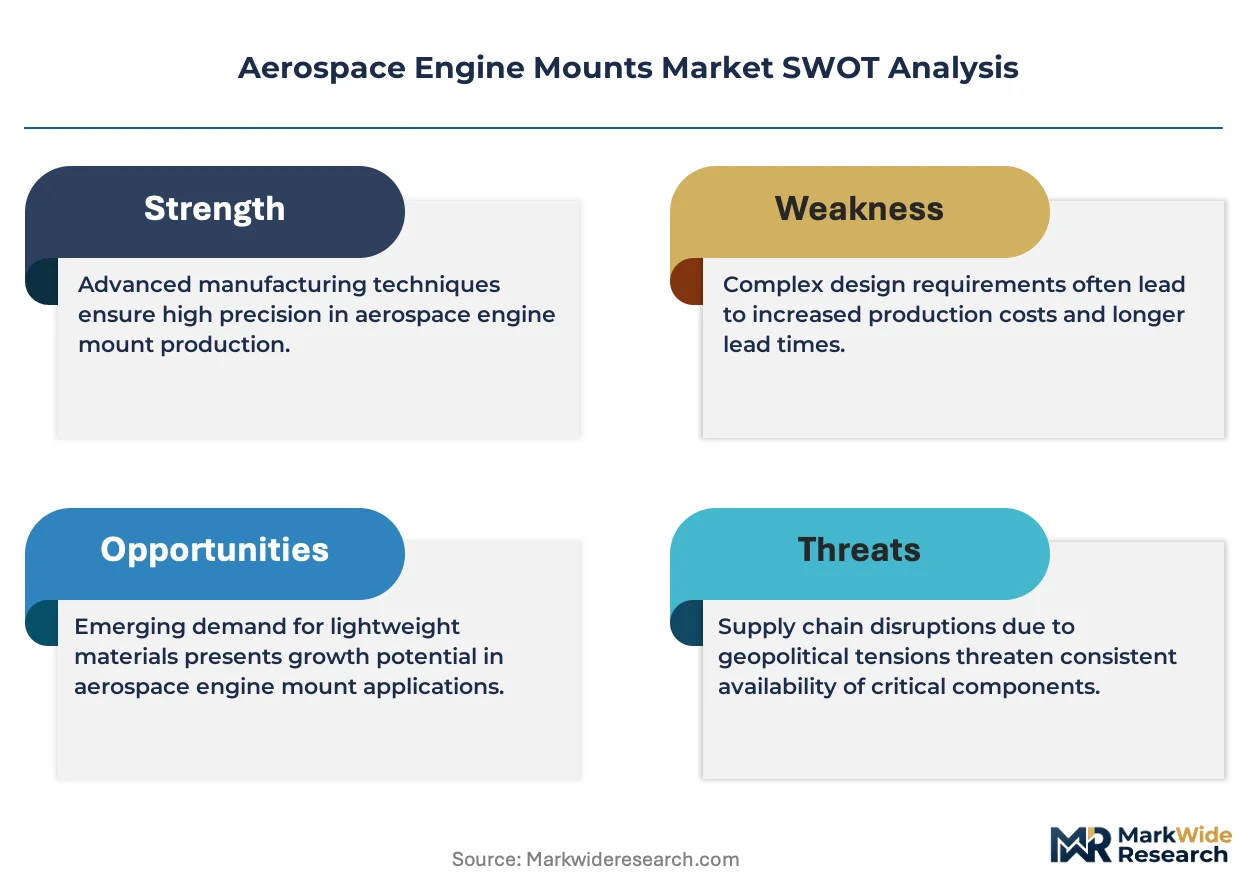
FAA and EASA fatigue-life mandates for elastomeric components are forcing OEMs to redesign qualification protocols, compressing supplier development cycles while widening the performance gap between certified and uncertified mount architectures.
Growth Catalysts
- Next-Generation Narrow-Body Programs:Boeing's 737 MAX and Airbus A320neo family ramp rates are pulling demand for high-bypass engine isolation systems. Final assembly lines in Washington, South Carolina, and Hamburg anchor procurement volumes.
- FAA Part 25 Structural Integrity Standards:Tightened airworthiness directives for extended operations are mandating predictive maintenance integration into mount designs. Commercial airlines now specify sensor-ready architectures in new-build contracts.
- Automated Fiber Placement:Composite load path manufacturing is reducing recurring costs for complex engine mount geometries. Tier-1 suppliers are qualifying carbon fiber-reinforced polymer brackets for secondary structural applications.
Market Restraints
- Titanium Alloy Input Volatility:Sponge and mill product pricing fluctuates with aerospace build rate cycles. Mount manufacturers face margin compression when long-term contracts fix output prices while input costs spike.
- Elastomer Compound Supply Concentration:Specialized fluoroelastomer formulations for high-temperature zones depend on a narrow supplier base in the United States and Germany. Qualifying alternative sources requires 18-24 month re-certification cycles.
- Active Control System Substitution:Piezoelectric and magnetorheological damping architectures threaten traditional passive elastomeric mounts in next-generation turbofan applications. Passive mount specialists must defend position through hybrid system partnerships.
Strategic Opportunities
- Unmanned Aerial Vehicle Segment:Low-volume, high-customization contracts for military and commercial drone platforms resist commoditization. Specialized mount suppliers capture premium pricing for rapid-turnaround development programs.
- REACH-Compliant Curing Agents:European polymer compounders investing in non-phthalate plasticizer formulations gain first-mover advantage as EPA and ECHA restrictions tighten. EASA-certified rubber-to-metal bonding expertise becomes a scarce, defensible capability.
- Sensor-Fed Adaptive Damping Convergence:Integration of IoT-enabled condition monitoring with hydraulic mount architectures opens aftermarket revenue streams. Airlines are piloting predictive replacement scheduling based on real-time vibration signature analysis.
Industry Challenges
- Elastomer Aging Characterization:Accelerated life testing protocols for extended operations lack standardized correlation to field degradation. FAA special conditions for active control systems require case-by-case qualification, stretching engineering resources.
- Legacy Platform Retrofit Integration:New-generation isolation systems must interface with existing wing pylon structures designed decades prior. Physical envelope constraints and load path compatibility limit upgrade options for in-service fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Engine Mounts Market |
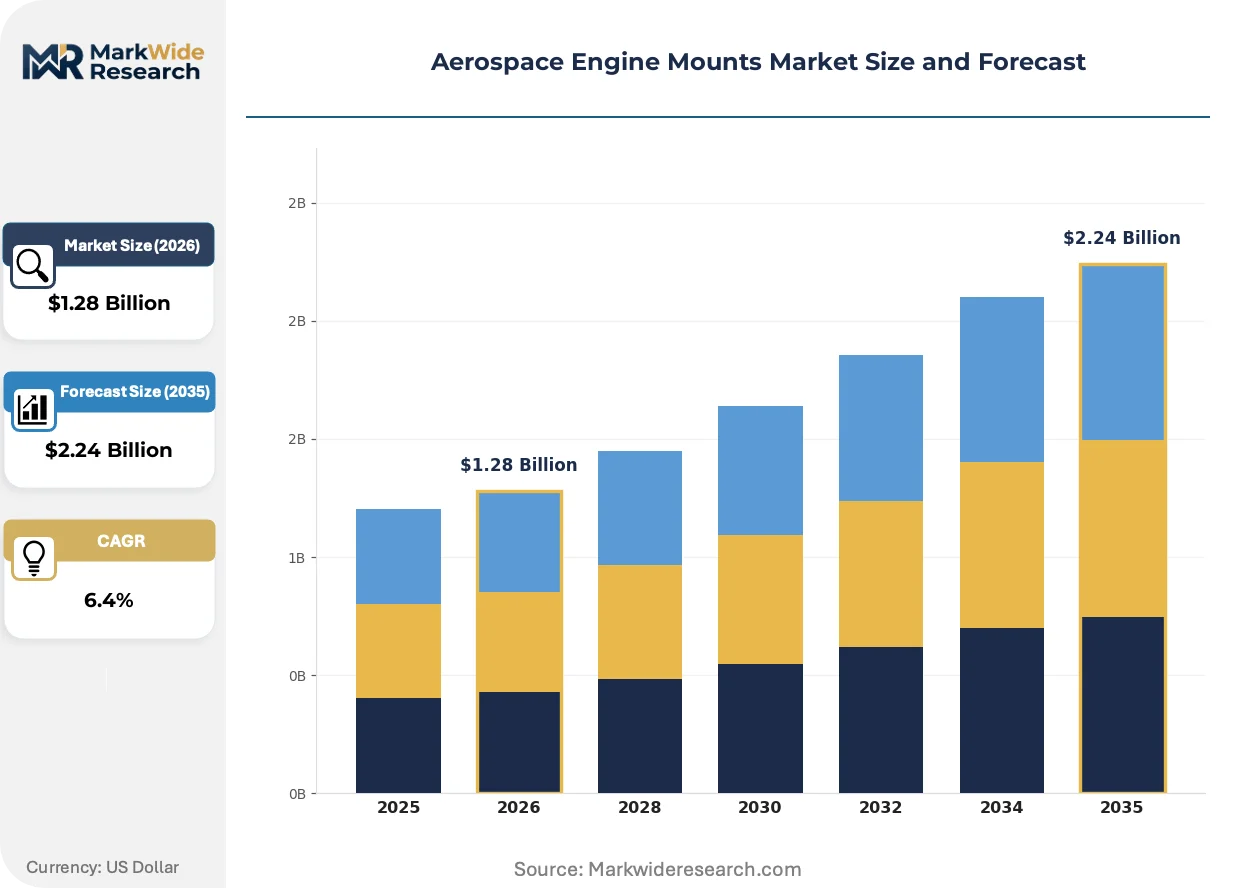
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Mount, Elastomeric Mount, Hydraulic Mount, Pneumatic Mount, Active Vibration Control Material: Aluminum Alloy, Titanium Alloy, Composite Materials, Steel Alloy, High-Temperature Polymers Application: Commercial Aircraft, Military Aircraft, Helicopters, Unmanned Aerial Vehicles, Spacecraft End User: Aircraft Manufacturers, Defense Contractors, Maintenance & Repair Organizations, Research Institutions |
| Companies Covered | LORD Corporation, Trelleborg AB, GMT Rubber-Metal-Technic Ltd., Cadence Aerospace, Mayday Manufacturing, Shock Tech, Inc., AirLoc Ltd., Parker Hannifin, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Engine Mounts Market Trends and Innovations
Digital thread integration across design, manufacturing, and in-service monitoring is compressing development cycles while enabling predictive maintenance business models that reshape supplier-airline relationships.
Embedded fiber optic strain sensing is digitizing structural health monitoring for engine mounts. Commercial airlines operating high-utilization narrow-body fleets are specifying sensor-integrated architectures in new procurement contracts. This capability is digitizing maintenance planning, shifting replacement decisions from calendar-based to condition-based intervals.
EASA CS-25 certification standards for adaptive damping architectures are tightening documentation requirements for software-controlled isolation systems. Manufacturers must demonstrate fail-safe reversion modes and electromagnetic compatibility across operational envelopes. European suppliers with existing EASA design organization approvals are capturing early qualification contracts for hybrid passive-active mount programs.
Airline engineering departments are consolidating vendor bases around full-system suppliers capable of integrating mounts with adjacent pylon components. Procurement teams favor single-source accountability over discrete component sourcing. This concentration is most visible in United States-based network carriers, where maintenance cost reduction mandates are driving supplier rationalization across the propulsion system supply chain.
Aerospace Engine Mounts Market Segmentation
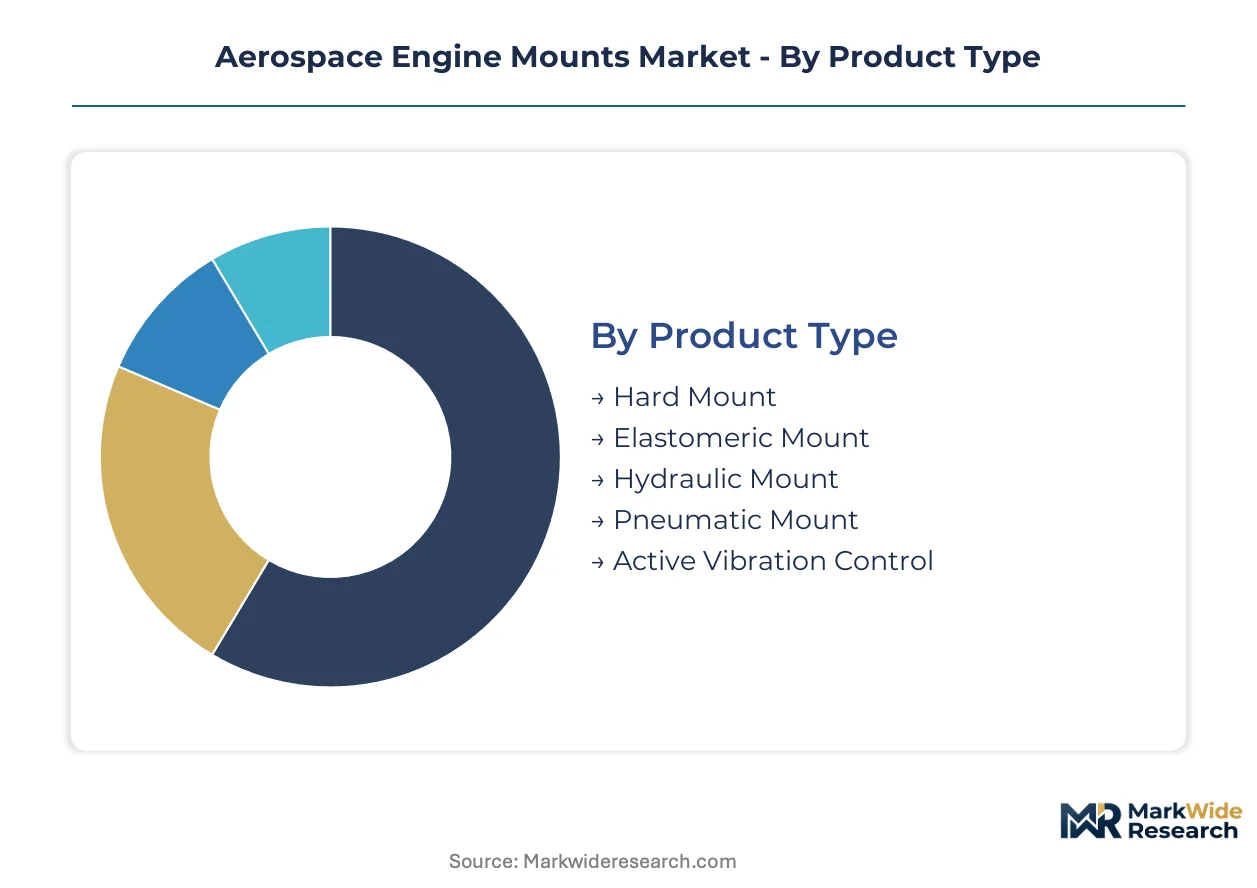
Segmentation in aerospace engine mounts reflects divergent engineering requirements across propulsion architectures. Product type and material selection directly determine vibration attenuation performance, weight trade-offs, and qualification timelines for airworthiness certification.
Product Type:
Use-case spectrum spans passive isolation through adaptive damping architectures, with selection driven by engine bypass ratio and airframe noise certification targets.
- Hard Mount:Rigid metallic brackets transfer loads without isolation, reserved for auxiliary power units and small turboprops where vibration magnitude remains below structural fatigue thresholds. Demand concentrates in general aviation retrofit programs across the United States.
- Elastomeric Mount:Rubber-to-metal bonded laminates attenuate broadband vibration through hysteretic damping, dominating narrow-body commercial applications. Boeing 737 MAX and Airbus A320neo production lines in Washington, South Carolina, and Hamburg anchor procurement volumes for high-bypass turbofan installations.
- Hydraulic Mount:Fluid-filled chambers provide tunable damping across frequency ranges, selected for wide-body engines with variable thrust profiles.
- Pneumatic Mount:Pressurized air chambers enable stiffness adjustment, finding niche application in rotorcraft where ground resonance suppression is critical.
- Active Vibration Control:Sensor-fed piezoelectric or magnetorheological actuators cancel harmonic loads in real time, emerging in next-generation turbofan demonstrators.
The dominant share belongs to Elastomeric Mount, while Active Vibration Control is closing the gap fastest.
Material:
Cost tier stratification separates qualified aerospace alloys from emerging composites, with titanium commanding premium positioning for strength-critical primary structures.
- Aluminum Alloy:7000-series forgings balance machinability and specific strength for secondary brackets and attach fittings. Established supply chains in the United States and Germany support high-volume commercial production with predictable lead times.
- Titanium Alloy:Ti-6Al-4V mill products deliver superior fatigue resistance and thermal stability for pylon-to-engine primary load paths. Sponge pricing volatility from Russian and Ukrainian supply disruptions has compressed margins for long-term fixed-price contracts.
- Composite Materials:Carbon fiber-reinforced polymer brackets reduce mass 25-40% versus metallic equivalents, gaining share in unmanned platforms where recurring cost sensitivity is lower.
- Steel Alloy:High-strength steels retain application in legacy military platforms with established forge qualifications.
- High-Temperature Polymers:PEEK and polyimide formulations insulate mount hardware from engine compartment thermal soak, specified for mounts adjacent to exhaust nozzles.
Titanium Alloy retains the largest installed base, though Composite Materials are expanding most quickly in new program specifications.
Application:
Volume concentration tracks commercial aircraft build rates, while margin pools concentrate where customization resists standardization.
- Commercial Aircraft:Narrow-body and wide-body platforms generate the highest absolute demand, with single-aisle programs driving procurement scale. Final assembly rates at Boeing Everett, Boeing North Charleston, and Airbus Hamburg determine annual volume fluctuations.
- Military Aircraft:Fighter and transport programs prioritize survivability and rapid field replacement over unit cost, sustaining premium pricing for hardened mount architectures. United States Department of Defense procurement cycles create lumpy demand patterns.
- Helicopters:Main rotor and tail rotor gearbox isolation requires specialized frequency-tuned solutions for ground resonance avoidance.
- Unmanned Aerial Vehicles:Low-volume, high-mix production favors suppliers with rapid prototyping capabilities and EAR/ITAR compliance infrastructure.
- Spacecraft:Launch vehicle stage separation and satellite deployment mechanisms demand ultra-lightweight mounts with pyrotechnic release functions.
Commercial Aircraft absorbs the dominant share, while Unmanned Aerial Vehicles are climbing the fastest as defense and logistics applications multiply.
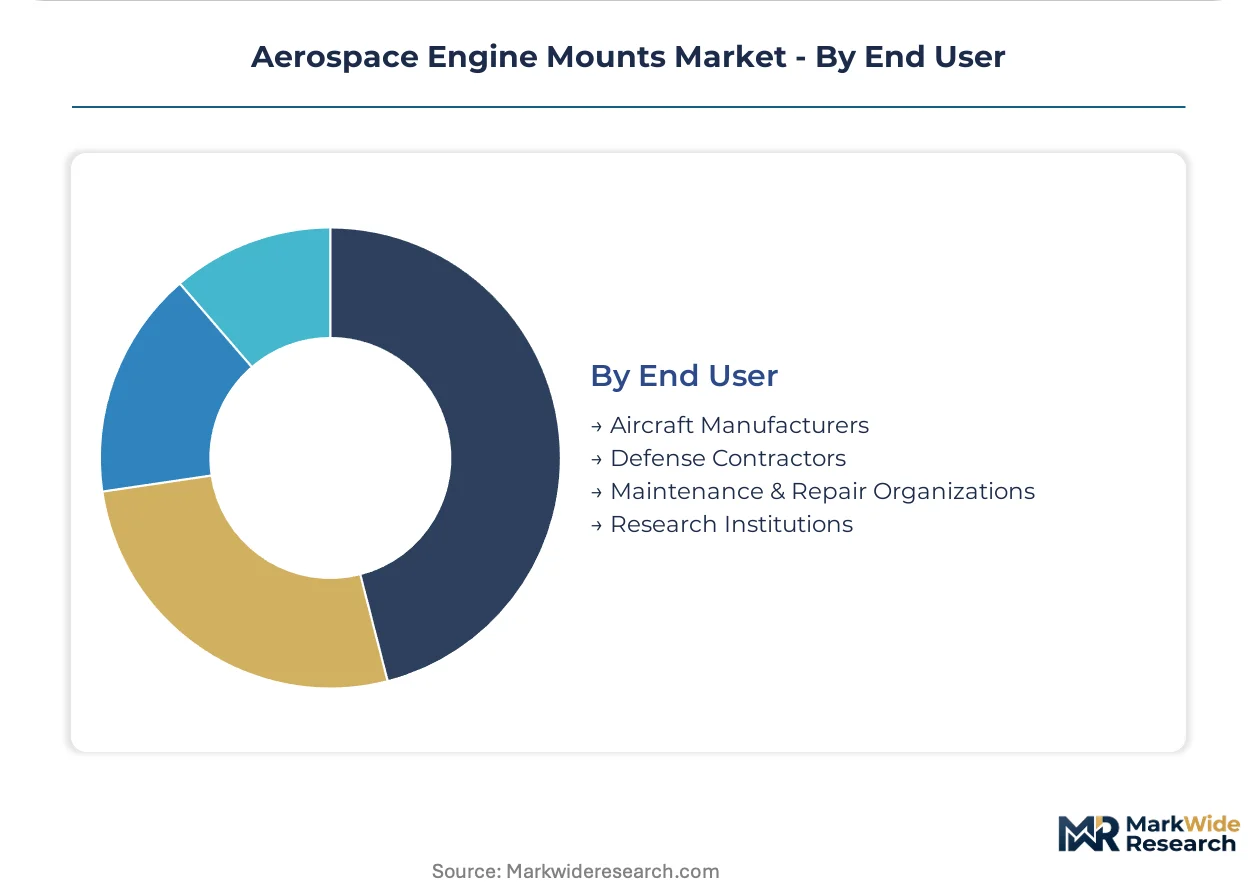
End User:
Customer type determines contract structure, with OEMs demanding system integration accountability and MROs prioritizing interchangeability.
- Aircraft Manufacturers:Boeing, Airbus, and Embraer specify mounts as part of propulsion system integration contracts, favoring suppliers with EASA and FAA design organization approvals. Long-term agreements lock in volume commitments across program lifecycles.
- Defense Contractors:Lockheed Martin, Northrop Grumman, and Raytheon procure mounts for platform-specific military applications with classified performance requirements. Security clearance barriers limit supplier participation.
- Maintenance & Repair Organizations:Airlines and third-party MROs source replacement mounts for in-service fleets, driving aftermarket revenue for OEM-authorized distributors.
- Research Institutions:NASA, DARPA, and university laboratories commission experimental mounts for technology demonstration programs with minimal recurring production.
Aircraft Manufacturers command the dominant share, though Maintenance & Repair Organizations are gaining share fastest as global fleet age extends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace engine mount procurement concentrates around final assembly sites where OEMs demand just-in-time delivery and design organization proximity. Buyers cluster near Boeing and Airbus production lines, with regulatory certification requirements further anchoring supplier investment to specific national aviation authorities.
United States
Boeing's 737 MAX and 777X programs in Everett, Washington and North Charleston, South Carolina generate the largest national demand pool for elastomeric and hydraulic mount architectures. FAA Part 25 airworthiness directives for extended operations mandate predictive maintenance integration, pushing suppliers toward sensor-ready designs. LORD Corporation and Parker Hannifin anchor domestic supply through polymer science and motion control expertise certified to federal standards.
Germany
Airbus final assembly in Hamburg and premium automotive-to-aerospace supplier crossover sustain demand for precision rubber-to-metal bonding. EASA CS-25 certification protocols for adaptive damping architectures tighten documentation requirements, favoring design organizations with existing agency approvals. Trelleborg AB leverages specialized bonding expertise to serve European turbofan programs.
France
Airbus headquarters in Toulouse and Safran propulsion integration create concentrated demand for engine pylon system suppliers. ANSM and DGAC coordination with EASA on elastomer aging characterization shapes qualification timelines for extended operations. The Toulouse-Blagnac aerospace cluster hosts tier-1 mount suppliers co-located with airframe engineering centers.
United Kingdom
Rolls-Royce turbofan development in Derby and Bristol anchors demand for high-temperature isolation systems on next-generation wide-body engines. The Civil Aviation Authority's alignment with EASA certification standards enables cross-border qualification efficiency. GMT Rubber-Metal-Technic Ltd. represents British specialized fabrication capability in bonded laminate architectures.
Japan
Mitsubishi Heavy Industries and Kawasaki Heavy Industries sustain domestic demand for regional jet and defense platform mounts. METI industrial policy supports composite material qualification for weight-critical applications. The Nagoya aerospace cluster concentrates precision machining and polymer compounding expertise for export-qualified production.
Aerospace Engine Mounts Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where EASA and FAA design organization approvals create qualification barriers. The market separates into full-system integrators, component specialists, and materials-science originators. Consolidation pressure intensifies as airlines consolidate vendor bases around single-source accountability. Dominant competitive moves include strategic partnerships for hybrid passive-active architectures and backward integration into polymer compounding.
Within the materials-science originator tier, LORD Corporation exemplifies polymer heritage leveraged into aerospace qualification. Trelleborg AB occupies a position as a European bonding specialist with EASA-certified design organization status. Parker Hannifin represents the diversified motion control conglomerate extending hydraulic and pneumatic expertise into propulsion isolation. These three anchors illustrate how competitive positioning depends on regulatory certification depth and adjacent technology portfolio breadth.
| Leading Market Players |
|---|
| LORD Corporation |
| Trelleborg AB |
| GMT Rubber-Metal-Technic Ltd. |
| Cadence Aerospace |
| Mayday Manufacturing |
| Shock Tech, Inc. |
| AirLoc Ltd. |
| Parker Hannifin |
| Eaton |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in titanium sponge conversion across the United States and Japan is tightening supply discipline and amplifying pricing leverage for qualified mill product suppliers serving FAA-certified mount manufacturers.
Pricing Analysis
Long-term cost-plus contracts with titanium sponge indexation dominate procurement between mount manufacturers and airframe OEMs. Price differentiation rests on EASA design organization certification tier and volume scale commitments across program lifecycles. Cost compression in passive elastomeric architectures is intensifying because active vibration control substitutes threaten incumbent technologies. Military and UAV segments exhibit lowest price sensitivity due to customization requirements and security clearance barriers.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for rare-earth magnet inputs to active damping actuators. Manufacturing concentrates in the United States, Germany, and Japan for qualified rubber-to-metal bonding and precision forging. Raw material dependencies center on titanium mill products, specialized fluoroelastomer compounds, and carbon fiber prepreg. Single-source vulnerability persists in high-temperature polymer compounding. Distribution runs through OEM-authorized tier-1 suppliers with co-located final assembly logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical trough conditions as Boeing and Airbus narrow-body production rates inflect upward, pulling demand for qualified mount architectures through the supply chain.
For Market Incumbents: Entrench certification moats by deepening backward integration into captive fluoroelastomer compounding capacity. Acquire EASA design organization approvals ahead of adaptive damping rulemaking. Active vibration control substitution and titanium input volatility represent the core threats demanding defensive positioning.
For New Entrants and Emerging Players: Japan's unmanned aerial vehicle subsystem tier offers geographic underpenetration for rapid-prototyping specialists with METI export qualification. Target military drone platform engineering houses with ITAR-compliant bonding capabilities. Pursue joint development contracts with Mitsubishi Heavy Industries as the go-to-market anchor.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across composite bracket manufacturing as automated fiber placement achieves scale economics. Five-to-ten year viability favors acquiring specialized rubber-to-metal bonding shops with existing FAA PMA approvals. Watch Boeing 737 MAX production rate announcements as the demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EASA Design Organization Approval | Unlocks European adaptive damping qualification contracts ahead of CS-25 rulemaking. |
| Backward Integration into Polymer Compounding | Captures margin from fluoroelastomer formulations while securing REACH-compliant supply. |
| Sensor-Ready Architecture Development | Aligns with FAA Part 25 predictive maintenance mandates for extended operations. |
| UAV Platform Partnership | Accesses premium pricing pools where low-volume customization resists commoditization. |
| Composite Load Path Qualification | Addresses weight reduction priorities in next-generation turbofan pylon designs. |
Research Methodology
Desk research of FAA airworthiness directives, EASA certification databases, and OEM procurement disclosures preceded structured interviews with propulsion system engineers, tier-1 supplier program managers, airline fleet planning directors, and MRO procurement leads. Primary fieldwork combined with secondary validation across SEC filings, trade customs data, and production rate announcements. Bottom-up build-ups triangulated against top-down market sizing.
Assumptions held fixed include Boeing and Airbus narrow-body delivery schedules, titanium sponge pricing bands, and EASA regulatory timelines. Variable assumptions encompassed active damping adoption rates and UAV platform proliferation curves. Segmentation modeling spanned product type, material grade, application platform, and end-user archetype across the projection horizon. CAGRs derived from production rate-linked volume elasticity and material mix shift assumptions.
Macroeconomic conditions sit as an overlay; deviation in aerospace build rates, titanium commodity cycles, or trade policy would shift the trajectory. Forecasts reflect documented assumptions on elastomer aging test protocols and adaptive damping certification pathways. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
Aircraft Engine Nacelle Market
Aircraft Engine Systems and Services
General Aviation Engines Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Angle of Attack Sensor Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Narrow-Body Turbofan Engine Shop Visit Services Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
America Aircraft Engines Market
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market