
 Aircraft Engine Nacelle Market | 2026-2036
Aircraft Engine Nacelle Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Engine Nacelle Market Analysis
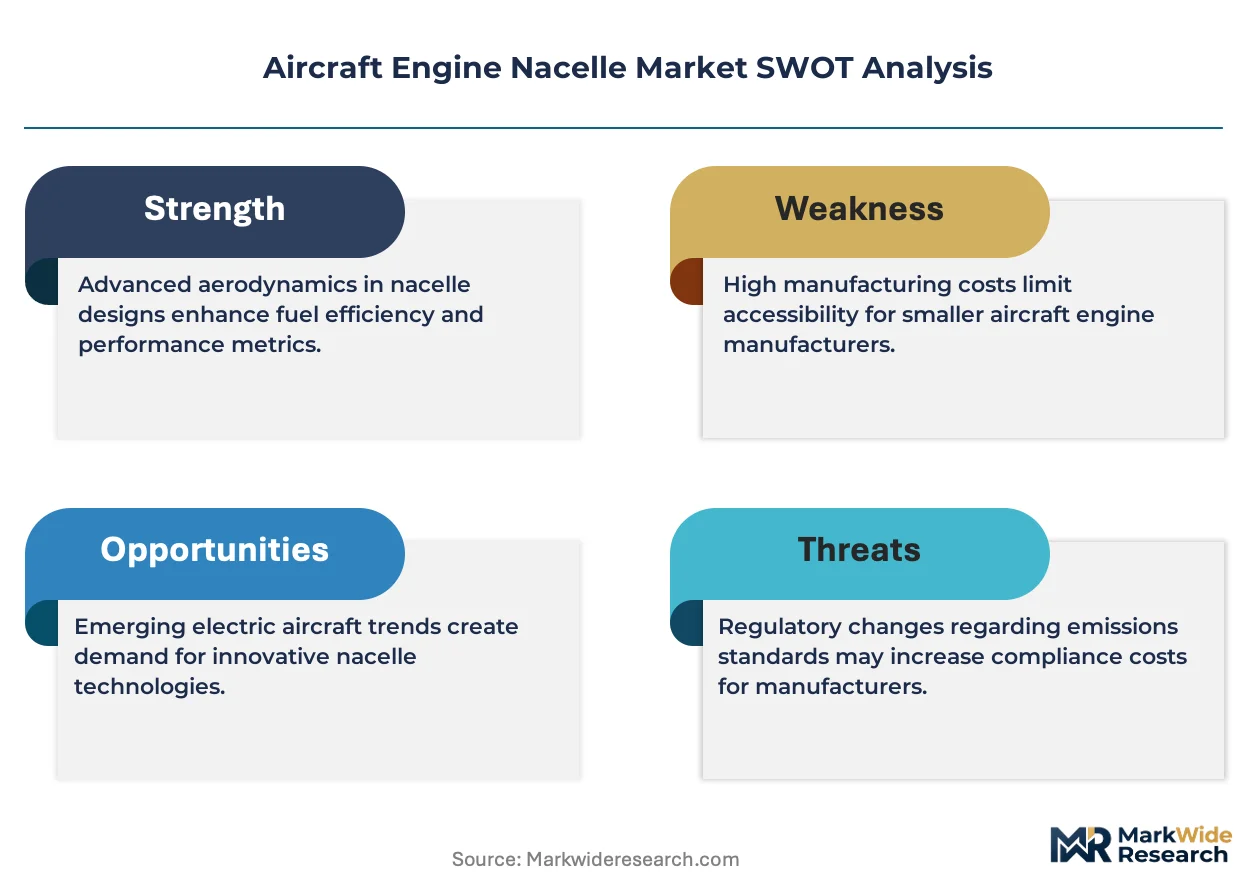
Polymer matrix composites is recalibrating nacelle economics by slashing weight versus traditional aluminum alloy architectures. RTX Corporation leverages its vertically integrated aerostructures division to control critical thermal protection system supply chains. GKN Aerospace sustains long-term positions through specialization in complex composite fan cowls and thrust reverser assemblies. Safran anchors European production gravity through its leadership in integrated propulsion system packages.
An aircraft engine nacelle constitutes the aerodynamic housing enclosing the engine, typically fabricated from carbon fiber reinforced polymer skins over honeycomb cores with titanium alloy leading edges, serving to reduce drag, manage thrust reverser actuation, and attenuate fan noise. Turbofan configurations dominate volume owing to their ubiquity across commercial single-aisle and twin-aisle platforms, while composite material adoption accelerates fastest as OEMs pursue specific fuel consumption reductions. Podded configurations retain structural primacy for under-wing installations on narrow-body workhorses, though integrated designs gain traction where drag reduction justifies development cost premiums.
FAA Part 33 engine certification and EASA CS-E standards govern nacelle fire containment, debris containment, and ice shedding requirements that directly dictate laminate specifications and fastener metallurgy. EPA aircraft emission regulations and ICAO Carbon Offsetting and Reduction Scheme for International Aviation compel manufacturers to optimize nacelle inlet aerodynamics for propulsive efficiency gains. Stakeholders must monitor evolving noise stringency at Heathrow, Frankfurt, and Dubai slot-coordinated airports where operational restrictions increasingly tie landing rights to cumulative noise footprints.
Market Dynamics
Composite material substitution is restructuring nacelle supply economics as polymer matrix architectures displace incumbent aluminum alloy platforms across next-generation turbofan programs.
Growth Catalysts
- ICAO CORSIA compliance deadlines:Airlines in slot-coordinated airports face mounting pressure to reduce cumulative noise footprints, accelerating nacelle replacement cycles on aging narrow-body fleets.
- Thrust reverser actuation electrification:Hydraulic-to-electric conversion programs are opening retrofit demand channels for integrated propulsion system packages on existing in-service aircraft.
- China's narrow-body final assembly concentration:COMAC C919 production ramp-up is generating localized demand spikes for fan cowl and inlet lip skin fabricators with CAAC certification pathways.
Market Restraints
- Titanium alloy leading edge supply concentration:Sponge processing capacity clusters in Russia and Kazakhstan expose nacelle manufacturers to raw material availability shocks and alloy price volatility.
- FAA Part 33 fire containment certification timelines:Extended laminate qualification protocols for honeycomb core assemblies stretch development cycles and freeze capital in pre-revenue programs.
- Aluminum-lithium substitution threat:Advanced wrought alloys for inlet structures retain cost advantages at lower production volumes, limiting composite penetration in regional jet nacelles.
Strategic Opportunities
- India's MRO infrastructure buildout:PLI scheme incentives for aerospace component manufacturing are attracting nacelle repair and overhaul investment near Bengaluru and Hyderabad aviation clusters.
- Hybrid-electric propulsion integration:Boundary layer ingestion nacelle architectures for distributed thrust configurations represent uncontracted design space for next-decade urban air mobility platforms.
- EASA CS-E debris containment rulemakings:Anticipated amendments to fan blade-out requirements will force laminate specification upgrades, creating captive demand for certified material suppliers.
Industry Challenges
- Autoclave capacity scarcity:Out-of-autoclave curing process validation remains incomplete for complex thrust reverser cascade segments, constraining throughput at tier-one aerostructures facilities.
- Adhesive bonding technician certification gaps:FAA-approved repair station networks face qualified personnel shortages for composite scarf repairs on in-service fan cowls, extending turnaround times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Engine Nacelle Market |
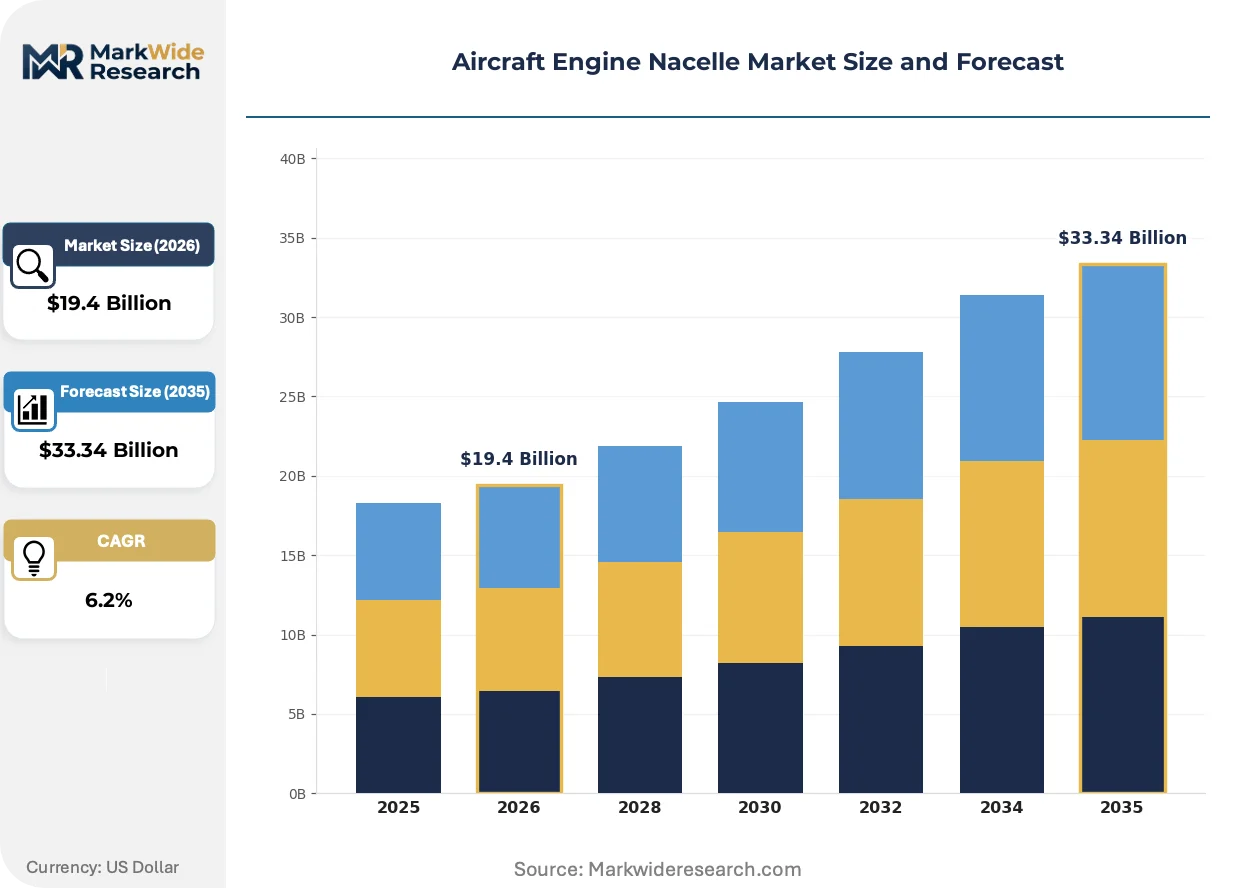
| Market Size in 2026 | $19.4 Billion |
| Market Size in 2035 | $33.34 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbojet, Turbofan, Turboshaft, Auxiliary Power Unit Material: Composite, Aluminum, Titanium, Steel End User: Commercial Aviation, Military Aviation, Cargo, General Aviation Configuration: Podded, Integrated, Rear-Mounted, Top-Mounted |
| Companies Covered | RTX Corporation, GKN Aerospace, Safran, Triumph Group, Leonardo S.p.A., Spirit AeroSystems, GE Aviation, FACC, Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Engine Nacelle Market Emerging Trajectories
Additive manufacturing of titanium alloy brackets and hinge fittings is penetrating nacelle structural assemblies, compressing lead times for low-volume thrust reverser components.
Resin transfer molding of thermoplastic composites is decentralizing production geography for inlet lip skins by enabling cold storage of preforms and reduced energy curing cycles compared to thermoset autoclave processing. Tier-two suppliers in Poland and Mexico are adopting this technology to serve regional Boeing and Airbus subassembly contracts without capital-intensive oven infrastructure.
EPA aircraft emission regulations are tightening inlet aerodynamic efficiency thresholds, forcing nacelle designers to optimize lip surface finishes and anti-ice bleed air integration. Wide-body programs face the steepest compliance gradients, with OEMs incorporating variable geometry inlet cowls to maintain propulsive efficiency across climb and cruise flight regimes.
Airline procurement departments are consolidating nacelle life-cycle cost contracts into power-by-the-hour agreements with engine OEMs, transferring inventory risk and unscheduled repair liability upstream. This reconfiguration concentrates aftermarket revenue at integrated propulsion system providers while fragmenting independent MRO access to technical data and replacement part authorizations, with the shift most visible among European network carriers restructuring fleet maintenance strategies.
Aircraft Engine Nacelle Market Segmentation
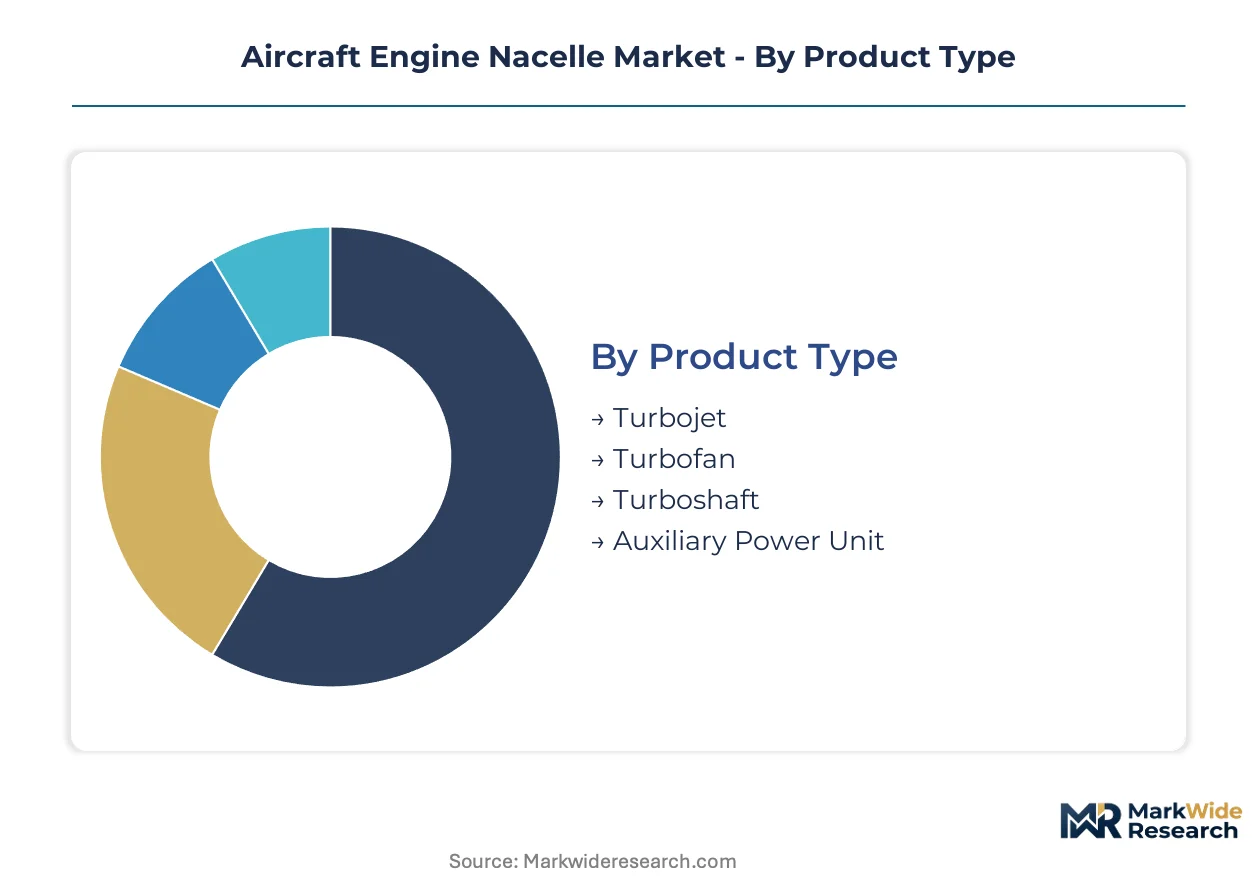
Nacelle procurement decisions split across propulsion architecture, material qualification, and airframe integration geometry. Each segmentation axis carries distinct capital requirements, certification timelines, and aftermarket revenue profiles that reshape supplier economics.
Product Type:
Capital intensity peaks where thrust ratings and thermal management complexity escalate—turbofan programs demand autoclave-scale composite infrastructure that turbojet and turboshaft suppliers rarely replicate.
- Turbofan:Carbon fiber reinforced polymer skins over honeycomb cores dominate these housings, with variable geometry inlets now standard on wide-body platforms. Demand clusters at Airbus and Boeing final assembly lines in Toulouse, France and Charleston, United States, where next-generation narrow-body ramp-ups are compressing supplier lead times. FAA Part 33 fire containment protocols for these high-bypass designs stretch laminate qualification cycles.
- Turbojet:These housings employ simpler fixed-geometry inlets with titanium alloy leading edges for military fighter applications. Procurement concentrates at defense primes in the United States and France, where low-volume, high-performance specifications tolerate unit costs that commercial programs reject. EASA CS-E debris containment rules apply less stringently here than for civil turbofan equivalents.
- Turboshaft:Compact housings for helicopter main and tail rotor drives feature aluminum-lithium alloy architectures to manage weight in vertical lift configurations. Rotorcraft OEMs in the United States and Italy specify these for medevac and offshore oil platform transport fleets.
- Auxiliary Power Unit:Small turbine housings for onboard electrical generation rely on stainless steel sheet metal with thermal insulation blankets. Business jet completion centers in Wichita, United States and São Paulo, Brazil drive replacement cycles for these units.
Most installed capacity flows through Turbofan. Expansion is steepest in Auxiliary Power Unit as business jet deliveries recover.
Material:
Raw material selection dictates tooling amortization schedules—thermoset composite programs require 7-10 year payback horizons that metal alternatives compress to 3-5 years.
- Composite:Polymer matrix architectures—specifically carbon fiber reinforced epoxy—now constitute the majority of new program awards. Boeing 787 and Airbus A350 nacelles exemplify this shift, with RTM processing gaining share for inlet lip skins. CAAC certification pathways for COMAC C919 suppliers in China are accelerating localized preform fabrication.
- Aluminum:Legacy narrow-body retrofit programs and regional jet platforms retain aluminum-lithium alloy specifications where production volumes fail to justify composite tooling investment. Embraer E-Jet nacelles in Brazil still specify these alloys for cost containment.
- Titanium:Leading edges, thrust reverser cascades, and firewalls demand titanium alloy grades for oxidation resistance and debris containment. Sponge processing concentration in Russia and Kazakhstan exposes this segment to supply shocks.
- Steel:APU housings and select firewall structures employ precipitation-hardened stainless grades for thermal durability. These applications resist composite substitution due to fire resistance requirements.
Composite commands the highest capital commitment per square meter of finished surface. Aluminum retains volume leadership in regional jet retrofits.
End User:
Customer type determines warranty exposure and technical data access—military programs restrict aftermarket participation while commercial aviation opens MRO competition.
- Commercial Aviation:Single-aisle and twin-aisle fleet operators dominate procurement, with power-by-the-hour agreements transferring inventory risk to engine OEMs. Slot-coordinated airports at Heathrow and Frankfurt impose noise footprint restrictions that accelerate nacelle replacement on aging A320ceo and 737NG fleets.
- Military Aviation:Fighter and transport programs in the United States, France, and China specify hardened housings with radar signature management. ITAR and comparable export control regimes fragment supplier access to technical data.
- Cargo:Dedicated freighter conversions of passenger wide-bodies require thrust reverser modifications for short-field performance. Amazon Air and DHL Express fleet expansion in the United States and Germany drives this subsegment.
- General Aviation:Business jet and turboprop platforms in the United States and Brazil specify compact nacelles with integrated de-ice systems. Low production volumes favor aluminum-lithium over composite for most programs.
Commercial Aviation absorbs the majority of production capacity. Military Aviation offers the steepest margin premiums despite restricted volumes.
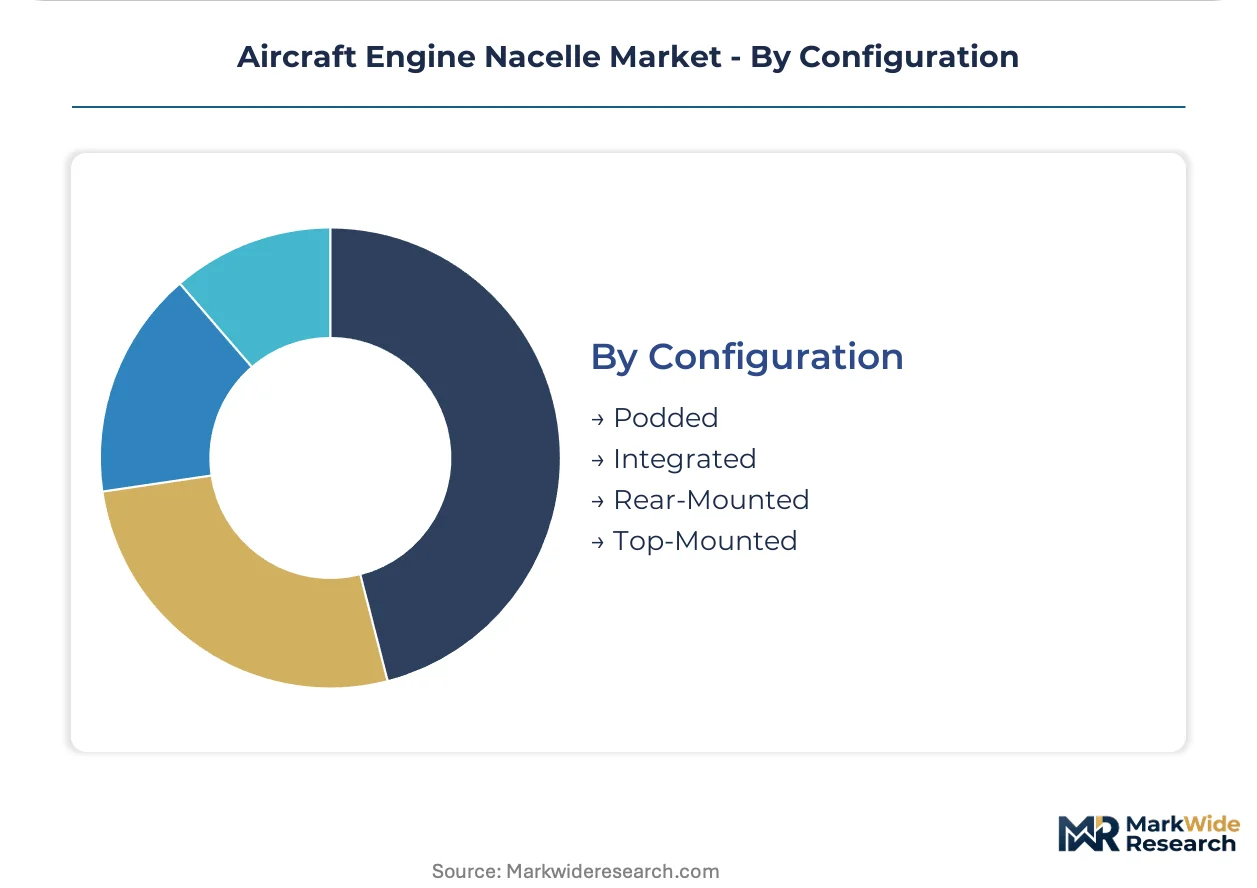
Configuration:
Airframe integration geometry determines aerodynamic trade-offs and maintenance accessibility—podded designs optimize field replaceability while integrated configurations minimize wetted area.
- Podded:Under-wing pylons on narrow-body workhorses enable rapid engine changes and simplify thrust reverser maintenance. This configuration retains structural primacy across Boeing 737 and Airbus A320 programs.
- Integrated:Blended wing-body and rear-fuselage mountings reduce drag penalties for supersonic and hybrid-electric concepts. NASA and industry consortia in the United States are flight-testing boundary layer ingestion variants.
- Rear-Mounted:Trijets and select business jet platforms position housings at the empennage for cabin noise reduction. Gulfstream and Dassault programs in the United States and France specify these for long-range missions.
- Top-Mounted:High-wing regional turboprops and military transport aircraft employ this arrangement for unimproved runway clearance. ATR 42/72 programs in France and Italy continue this specification.
Podded configurations retain installed base dominance. Integrated designs are gaining development funding fastest for next-decade platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toulouse anchors the global nacelle manufacturing footprint through Airbus final assembly concentration and Safran's integrated propulsion packaging. FAA Part 33 and EASA CS-E certification requirements fragment production geography across three dominant clusters. Supply chain proximity to engine OEMs dictates sub-tier fabricator location decisions.
United States
Boeing 737 MAX and 787 production lines in Charleston and Everett drive composite nacelle demand from tier-one aerostructures suppliers. FAA Part 33 fire containment protocols govern laminate qualification for thrust reverser assemblies. RTX Corporation and Spirit AeroSystems maintain vertically integrated production corridors across Connecticut and Kansas.
France
Airbus A320 and A350 programs in Toulouse sustain European nacelle volume leadership through Safran's dominance in integrated propulsion system packages. EASA CS-E debris containment standards dictate fan cowl specification upgrades across the supply base. GKN Aerospace operates specialized composite fabrication facilities in western France for thrust reverser cascade production.
China
COMAC C919 production ramp-up in Shanghai Pudong generates localized demand spikes for fan cowl fabricators with CAAC certification pathways. MIIT industrial policy directs nacelle component localization through domestic supplier qualification programs. Xian and Chengdu aviation clusters attract tier-two composite preform manufacturers serving narrow-body subassembly contracts.
Germany
Airbus Hamburg final assembly lines for A320 family aircraft sustain nacelle inlet lip skin demand from specialized thermoplastic composite processors. KBA-equivalent aerospace standards align with EASA certification reciprocity for cross-border supply integration. Bavaria hosts precision machining clusters for titanium alloy thrust reverser hinge fittings.
India
PLI scheme incentives for aerospace component manufacturing attract nacelle repair and overhaul investment near Bengaluru and Hyderabad aviation clusters. DGFT import substitution policies accelerate domestic fabrication capability for A320neo fan cowl retrofits. Chennai and Pune emerging as MRO hubs for Middle Eastern carrier fleet support contracts.
Aircraft Engine Nacelle Market Vendor Landscape
Global majors compete with regional champions across integrated propulsion system packaging and composite aerostructures fabrication. The market structures around three tiers: engine OEM-captive nacelle divisions, independent tier-one aerostructures suppliers, and specialized composite component fabricators. Dominant competitive moves include backward integration into thermal protection systems and strategic partnerships for out-of-autoclave process validation.
Among vertically integrated propulsion providers, RTX Corporation exemplifies the engine OEM-captive archetype through its Collins Aerospace and Pratt & Whitney divisions. GKN Aerospace and Safran occupy positions as independent tier-one specialists with concentrated composite fan cowl and thrust reverser expertise. These three anchors illustrate how certification-holding capability and final assembly line proximity determine competitive positioning in nacelle procurement.
| Leading Market Players |
|---|
| RTX Corporation |
| GKN Aerospace |
| Safran |
| Triumph Group |
| Leonardo S.p.A. |
| Spirit AeroSystems |
| GE Aviation |
| FACC |
| Collins Aerospace |
| Others |
Supply Flow & Price Mechanics
Airline power-by-the-hour procurement consolidation is forcing nacelle suppliers to absorb inventory risk and unscheduled repair liability, compressing margins and driving selective backward integration into thermal protection system supply chains to retain pricing power.
Pricing Analysis
Titanium alloy sponge cost pass-through dominates nacelle pricing dynamics, with Russian and Kazakh supply concentration exposing manufacturers to volatile raw material swings. Three-tier pricing structure across premium certified, standard qualified, and economy retrofit tiers separates FAA Part 33 fire containment holders from uncertified fabricators. Pricing pressure stems from aluminum-lithium substitution threats in regional jet programs. Regional operators exhibit highest price sensitivity; integrated propulsion system providers face lowest.
Supply Chain Analysis
CAAC, FAA, and EASA qualification protocols gate nacelle supply participation, freezing out uncertified fabricators regardless of cost position. Production clusters concentrate in the United States, France, and China, with tier-two preform manufacturers emerging in Poland and Mexico. Raw material dependencies center on carbon fiber epoxy prepregs, titanium alloy sponge, and honeycomb core. Single-source vulnerability runs through Russian titanium sponge processing. Distribution runs through engine OEM captive channels and independent tier-one aerostructures suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aircraft Engine Nacelle Market compounds steadily as next-generation turbofan fleet renewal cycles sustain replacement demand across narrow-body and wide-body platforms.
For Market Incumbents: Extend certification-holding advantage by deepening FAA Part 33 and EASA CS-E laminate qualification portfolios before anticipated debris containment rulemakings tighten standards. Lock in long-term titanium alloy supply agreements to hedge against Russian sponge export restrictions. Out-of-autoclave process validation offers cost structure defense against emerging thermoplastic composite entrants. For New Entrants and Emerging Players: PLI scheme incentives in India open a window for nacelle repair and overhaul specialization near Bengaluru and Hyderabad aviation clusters, bypassing capital-intensive autoclave infrastructure requirements. Target auxiliary power unit segments where business jet recovery outstrips incumbent capacity. Pursue CAAC certification pathways for COMAC C919 subassembly contracts as the fastest qualification route. For Investors and Strategic Acquirers: Asymmetric upside sits with tier-two composite preform fabricators holding dual FAA-EASA qualifications and established engine OEM supply relationships. Five-to-ten year viability hinges on positioning for hybrid-electric boundary layer ingestion architectures. Watch for EASA CS-E fan blade-out rulemaking amendments as inflection signal for laminate specification upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Out-of-Autoclave Process Validation | Resin transfer molding adoption in Poland and Mexico bypasses capital-intensive oven infrastructure for inlet lip skin production. |
| Dual Certification Investment | Simultaneous FAA Part 33 and EASA CS-E qualification opens access to Boeing and Airbus final assembly line contracts. |
| Titanium Supply Diversification | Non-Russian sponge sourcing hedges against Kazakhstan export disruption and alloy price volatility exposure. |
| Power-by-the-Hour Partnership | Life-cycle cost contracting with engine OEMs transfers inventory risk while capturing aftermarket revenue streams. |
| Hybrid-Electric Architecture R&D | Boundary layer ingestion nacelle development positions suppliers for NASA and industry consortium flight-test programs. |
Methodological Framework
Multiple input streams — supply chain mapping, regulatory filing analysis, and production database reconciliation — were reconciled across primary interviews with nacelle program managers, aerostructures procurement leads, composite fabrication engineers, and MRO operations directors, validated against FAA type certificate data, EASA certification records, COMAC supplier disclosures, and customs trade flows, with bottom-up installation base modeling cross-checked against top-down OEM delivery projections.
Historical production volumes were cross-referenced against expert panel inputs on ramp-rate assumptions across the projection horizon. Segmentation dimensions modeled include propulsion architecture, material qualification tier, end-user category, and airframe integration geometry. CAGRs were derived from installation base turnover analysis and fleet renewal cycle timing, incorporating turbofan thrust rating trajectories and composite adoption elasticity by aircraft class.
Forecast precision tightens around the base case; tail outcomes carry wider variance under titanium supply disruption or accelerated ICAO CORSIA compliance deadlines. Forecasts reflect documented assumptions on certification timeline probabilities and OEM production rate plans. A model refresh is warranted upon material change in EASA debris containment rulemaking schedules or COMAC C919 production ramp trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market
Aircraft Engine Systems and Services
America Aircraft Engines Market
Aircraft Engine Systems and Services
Gas Turbine Service Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market
Aircraft Engine Systems and Services
Aero Engine Coatings Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
General Aviation Engines Market