
 Rocket Propulsion Market | 2026-2036
Rocket Propulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Rocket Propulsion Market Insights
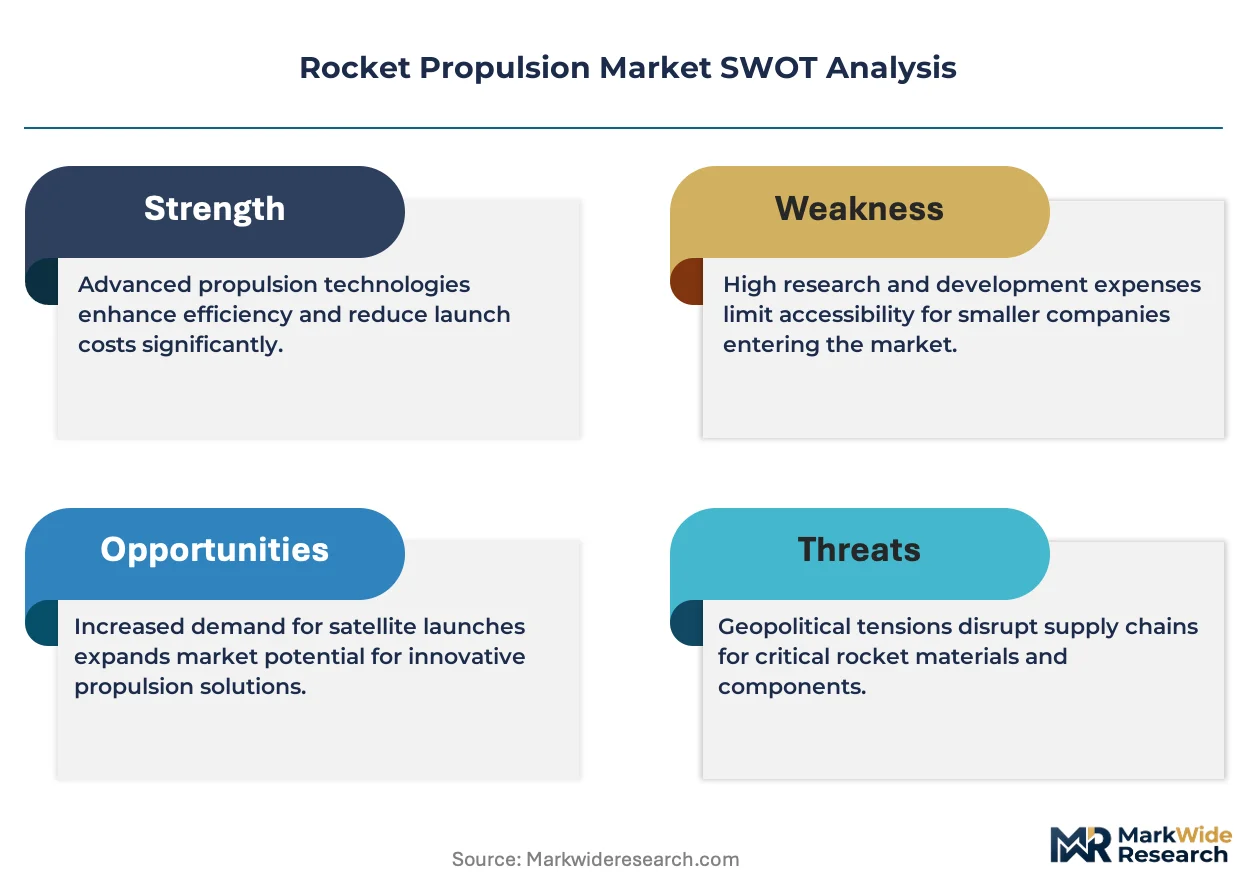
The capability gap between fully reusable and expendable launch architectures is reorganizing competitive hierarchies across the rocket propulsion sector. SpaceX leverages vertical integration across engine design, manufacturing, and launch operations to compress cycle times and capture recurring flight revenue. Blue Origin sustains heavy investment in liquid hydrogen-oxygen propulsion systems for orbital-class vehicles, positioning for long-duration deep-space contracts. Northrop Grumman dominates solid rocket motor production for defense and space applications, anchoring a stable revenue base through classified government programs.
Rocket propulsion encompasses the generation of thrust through controlled expulsion of propellant mass, with liquid bi-propellant systems typically operating at chamber pressures exceeding 100 bar and specific impulses ranging from 300–450 seconds depending on propellant combination. Chemical rocket engines retain the largest installed base due to their thrust-to-weight superiority for launch vehicle ascent phases, while electric propulsion systems—specifically Hall effect thrusters—are displacing conventional chemical alternatives for station-keeping and orbital transfer missions where fuel efficiency outweighs thrust requirements. Satellite launch applications command the dominant share of propulsion unit volume, though space exploration missions concentrate margin pools through low-volume, high-reliability engine contracts with extended qualification timelines.
NASA, the FAA, and the U.S. Department of Defense shape demand through mission assurance requirements, launch licensing protocols, and national security space procurement rules that mandate domestic sourcing for critical propulsion components. The European Space Agency and EASA enforce parallel technical standards through the Ariane program and commercial launch certification pathways, creating dual compliance obligations for multinational suppliers. Stakeholders must monitor how evolving orbital debris mitigation rules and propellant toxicity restrictions reshape engine design trade-offs and factory certification investments.
Market Dynamics
Reusable launch architectures are compressing engine production cycles and forcing incumbents to retool manufacturing lines for rapid refurbishment rather than single-use disposal. This shift from expendable to flight-proven hardware restructures capital allocation across the propulsion supply base.
Growth Catalysts
- FAA Reusable Launch Licensing:Streamlined certification pathways for flight-proven vehicles accelerate operational tempo for commercial launch providers. Domestic operators capture recurring revenue from satellite constellation deployment contracts.
- Small Satellite Constellation Scaling:Low Earth orbit broadband networks drive unit demand for compact liquid and electric propulsion systems. Satellite manufacturers require standardized engine interfaces for rapid vehicle integration.
- In-Space Manufacturing:Orbital production facilities for fiber optics and pharmaceuticals create demand for high-efficiency orbital transfer engines. Chemical propulsion retains dominance for heavy payload insertion missions.
Market Restraints
- Domestic Sourcing Mandates:U.S. Department of Defense procurement rules restrict foreign content in critical propulsion components. European and Asian suppliers face exclusion from classified national security space programs.
- Specialized Alloy Supply Concentration:Nickel-based superalloys for high-temperature turbopump components concentrate among a limited supplier base. Aerospace-grade material lead times extend qualification schedules for new engine programs.
- Hall Effect Thruster Performance Ceiling:Electric propulsion thrust density limits restrict applications to station-keeping and slow orbital transfers. Chemical systems retain monopoly on rapid ascent and de-orbit maneuvers.
Strategic Opportunities
- India Spaceport Expansion:Satish Dhawan Space Centre capacity growth opens procurement channels for foreign propulsion technology partnerships. ISRO's commercial arm seeks co-development agreements for heavy-lift engine qualification.
- Green Propellant Transition:ESA and NASA mandates for reduced-toxicity propulsion create first-mover advantages for ADN and ionic liquid formulations. Ground handling cost reductions improve operational economics for frequent launch cadences.
- On-Orbit Servicing Integration:Rendezvous and proximity operations require precision cold-gas and electric propulsion suites. Satellite life extension contracts bundle propulsion hardware with docking mechanism sales.
Industry Challenges
- Additive Manufacturing Certification:3D-printed combustion chambers and injectors face extended qualification timelines for human-rating standards. NASA and FAA require flight heritage data that delays production scale-up.
- Propulsion-Avionics Integration Complexity:Engine health management systems must interface with vehicle flight computers across multiple launch vehicle platforms. Software verification costs escalate with mission assurance requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rocket Propulsion Market |
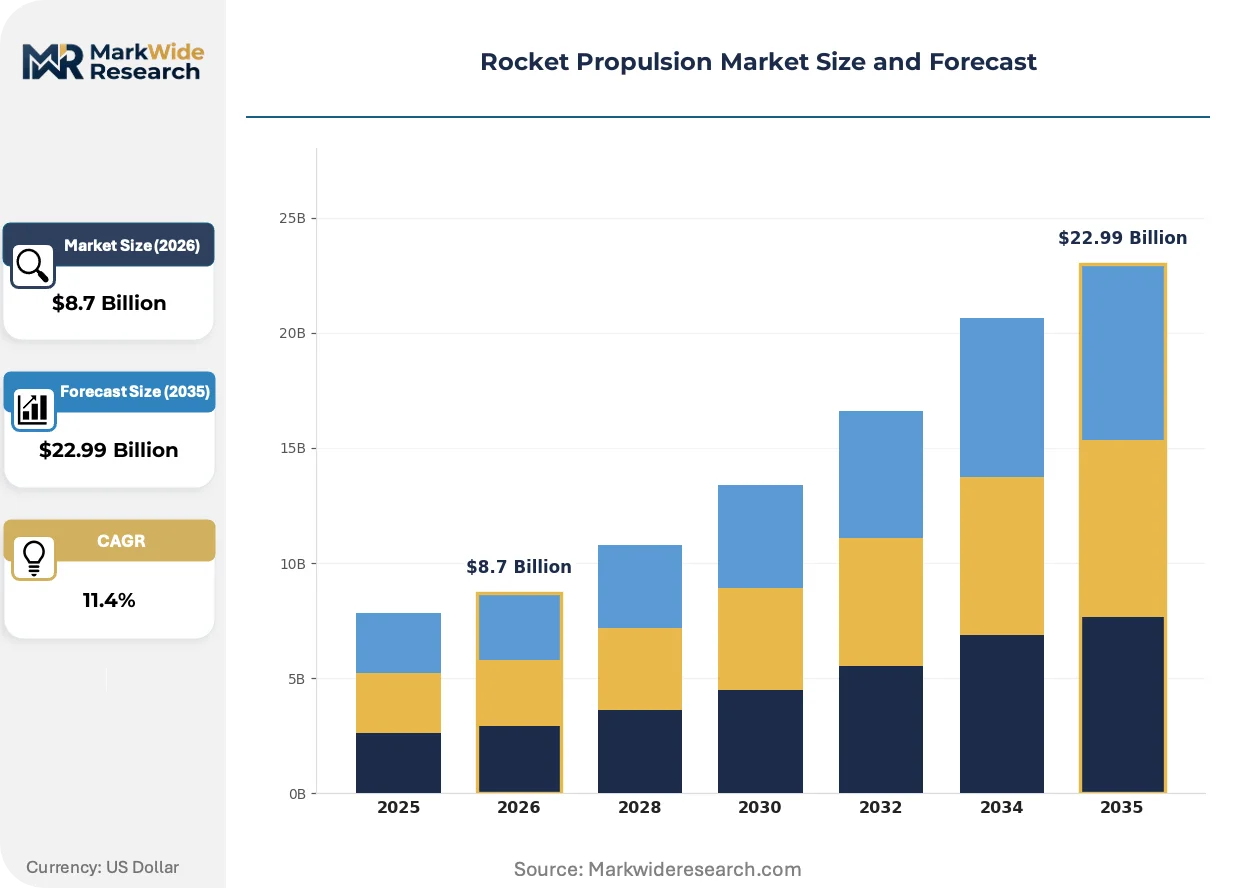
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propulsion Type: Chemical Rocket Engines, Electric Propulsion, Nuclear Thermal, Hybrid Rockets, Cold Gas Thrusters Technology: Liquid Propellant, Solid Propellant, Ion Thrusters, Hall Effect Thrusters, Arcjets Application: Satellite Launch, Space Exploration, Missile Systems, Launch Vehicles, Space Tourism End User: Government Space Agencies, Private Aerospace Firms, Defense Contractors, Research Institutes |
| Companies Covered | SpaceX, Blue Origin, Northrop Grumman, Lockheed Martin, Boeing, Aerojet Rocketdyne, Mitsubishi Heavy Industries, Safran, IHI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rocket Propulsion Market Trends and Innovations
Propulsion technology trajectories diverge between launch and in-space applications, with chemical systems optimizing for thrust density while electric alternatives maximize specific impulse for long-duration missions. This bifurcation reshapes supplier specialization and R&D allocation.
Methane-oxygen staged combustion cycles are supplanting kerosene-oxygen engines in medium-to-heavy lift vehicles due to cleaner combustion residue and reduced refurbishment overhead. Commercial launch operators prioritize methane for its compatibility with autogenous pressurization systems that eliminate helium dependence. Full-flow staged combustion architectures are supplanting gas-generator cycles in next-generation engine development programs, enabling higher chamber pressures and improved thrust-to-weight ratios.
REACH chemical restrictions in Europe are forcing reformulation of hydrazine-based monopropellants for satellite attitude control systems. ESA's Clean Space initiative accelerates funding for ammonium dinitramide and hydroxylammonium nitrate alternatives with reduced toxicity profiles. Satellite prime contractors in France and Germany are requalifying propulsion subsystems to maintain access to EU institutional launch contracts.
Fixed-price milestone contracts are displacing cost-plus development arrangements for engine qualification programs. NASA and the U.S. Space Force now require flight-proven hardware demonstrations before production authorization. This payment structure concentrates development risk on propulsion suppliers and favors entities with captive launch vehicle integration capabilities.
Rocket Propulsion Market Segmentation
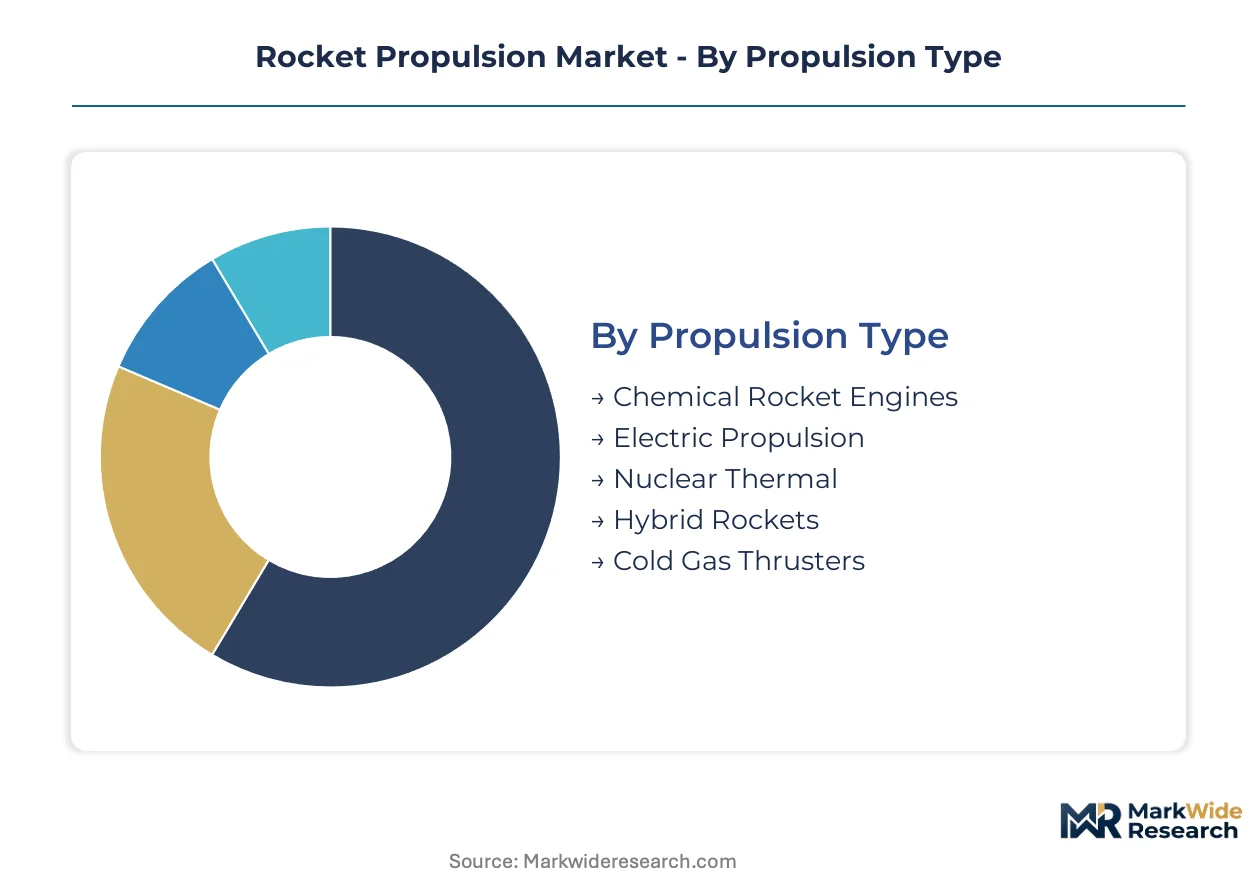
Propulsion segmentation separates volume-driven satellite launch applications from margin-rich deep-space exploration contracts. Technology choices cascade through supply chain requirements, certification timelines, and refurbishment economics that reshape supplier positioning.
Propulsion Type:
Margin pools concentrate in chemical systems for heavy-lift ascent missions and electric alternatives for long-duration station-keeping.
- Chemical Rocket Engines:Liquid bi-propellant and solid motor systems generate thrust through controlled combustion of fuel and oxidizer. Satellite constellation deployment in the United States absorbs the dominant production volume, with SpaceX and Blue Origin driving demand for reusable liquid engines. Domestic sourcing mandates from the FAA and U.S. Department of Defense restrict foreign supplier participation in classified programs.
- Electric Propulsion:Hall effect thrusters and ion engines accelerate propellant ions using electromagnetic fields to achieve specific impulses exceeding 3000 seconds. Commercial satellite manufacturers in Europe prioritize these systems for orbital transfer and station-keeping under ESA Clean Space toxicity reduction mandates. REACH chemical restrictions accelerate hydrazine replacement with ammonium dinitramide formulations.
- Nuclear Thermal:Fission reactor-heated hydrogen propulsion for crewed Mars transit architectures.
- Hybrid Rockets:Combined liquid oxidizer and solid fuel systems for suborbital tourism vehicles.
- Cold Gas Thrusters:Compressed nitrogen or helium systems for precision attitude control and rendezvous operations.
Chemical engines hold installed capacity. Electric propulsion is rotating up the share rankings.
Technology:
Technology selection tracks the tension between thrust density requirements for launch and fuel efficiency priorities for in-space maneuvering.
- Liquid Propellant:Pump-fed or pressure-fed systems using cryogenic or storable propellants enable throttle control and engine restart. Methane-oxygen staged combustion cycles are supplanting kerosene-oxygen in next-generation launch vehicles due to cleaner residue profiles. Autogenous pressurization eliminates helium dependence, compressing ground operations for rapid reuse.
- Solid Propellant:Cast composite grain motors deliver high thrust-to-weight ratios without turbomachinery complexity. Defense applications in the United States anchor stable demand through classified ballistic missile and strategic deterrent programs. Northrop Grumman dominates domestic production with vertically integrated propellant mixing and case winding capabilities.
- Ion Thrusters:Electrostatic acceleration of xenon or krypton ions for deep-space science missions.
- Hall Effect Thrusters:Closed electron drift systems with magnetic field confinement for commercial satellite propulsion.
- Arcjets:Electrothermal heating of hydrazine for moderate specific impulse augmentation.
Liquid systems command development investment. Solid motors defend revenue stability through defense procurement.
Application:
Application segmentation separates high-cadence commercial launch from low-volume, extended-qualification exploration contracts.
- Satellite Launch:Low Earth orbit broadband constellations drive unit demand for both primary launch vehicle engines and satellite-integrated propulsion. Reusable system mandates from NASA and the FAA compress cost structures and accelerate technology refresh cycles. Fixed-price milestone contracts now require flight-proven hardware demonstrations before production authorization.
- Space Exploration:Crewed lunar and Mars missions concentrate margin pools through low-volume, high-reliability engine procurement. NASA Artemis program requirements dictate domestic sourcing for critical propulsion components with extended qualification timelines. Human-rating standards impose additive manufacturing certification delays for 3D-printed combustion chambers.
- Missile Systems:Strategic and tactical defense applications with classified performance specifications.
- Launch Vehicles:Expendable and reusable booster stages for commercial and government payload insertion.
- Space Tourism:Suborbital passenger vehicles with emphasis on safety redundancy and rapid turnaround.
Satellite launch absorbs volume leadership. Space exploration captures margin concentration through mission assurance premiums.
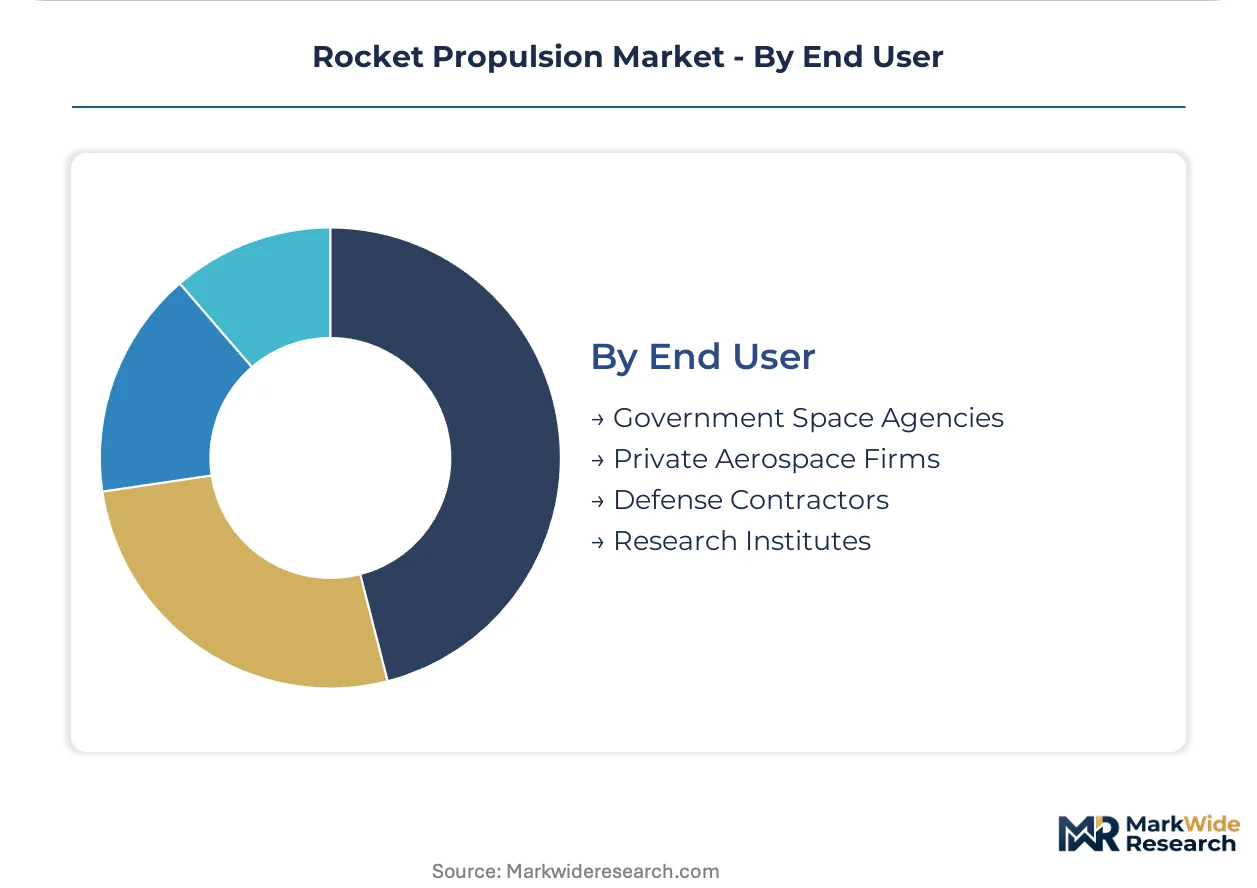
End User:
End user structure bifurcates between institutional procurement with mission assurance requirements and commercial operators optimizing for cost per kilogram to orbit.
- Government Space Agencies:NASA, ESA, and ISRO drive demand through exploration roadmaps and technology demonstration missions. Procurement rules mandate domestic content thresholds and extended qualification protocols that favor incumbent suppliers with established flight heritage. India's Satish Dhawan Space Centre expansion opens foreign partnership channels for heavy-lift engine co-development.
- Private Aerospace Firms:Commercial launch operators prioritize rapid refurbishment and standardized engine interfaces for constellation deployment. Vertical integration across engine design, manufacturing, and launch operations compresses cycle times and captures recurring flight revenue. SpaceX and Blue Origin anchor domestic supply chains with captive production capabilities.
- Defense Contractors:Classified national security space programs with restricted foreign content requirements.
- Research Institutes:University and laboratory propulsion test programs with small-quantity, high-variety procurement patterns.
Government agencies anchor qualification standards. Private operators are gaining procurement volume fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys reusable liquid engines at commercial cadence while Europe prioritizes electric propulsion for satellite station-keeping under toxicity mandates. India and Japan concentrate on heavy-lift co-development partnerships, diverging from China's state-directed launch vehicle consolidation.
United States
Commercial constellation deployment drives demand for rapid-refurbishment liquid engines. FAA streamlined licensing for flight-proven vehicles accelerates operational tempo. SpaceX and Blue Origin anchor domestic supply chains through captive manufacturing in Texas and Florida.
China
State-directed launch vehicle programs consolidate propulsion development under state-owned enterprises. MIIT standards govern satellite launch frequency and orbital slot allocation. Yangtze River Delta clusters concentrate liquid engine test facilities and solid motor production bases.
India
ISRO's commercial arm seeks foreign partnerships for heavy-lift engine qualification. Satish Dhawan Space Centre expansion opens procurement channels for co-development agreements. Andhra Pradesh hosts integrated launch facilities with growing private sector participation.
Japan
METI-funded programs advance methane-oxygen staged combustion cycles for next-generation vehicles. H3 launch vehicle procurement concentrates margin in domestic propulsion suppliers. Tanegashima Space Center maintains East Asian launch capacity with precision orbital insertion capabilities.
Germany
ESA Clean Space mandates accelerate hydrazine replacement with ammonium dinitramide formulations. REACH chemical restrictions force satellite prime contractors to requalify attitude control subsystems. Bavaria hosts Hall effect thruster development clusters serving European institutional contracts.
Rocket Propulsion Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in propulsion supply. SpaceX and Blue Origin compress cycle times through captive manufacturing and launch operations. Northrop Grumman defends solid motor revenue through defense procurement. Competitive moves concentrate on reusable system certification and green propellant transition.
Within the integrated launch operator tier, SpaceX exemplifies vertical control across engine design, manufacturing, and flight operations. Blue Origin occupies a position anchored in liquid hydrogen-oxygen development for orbital-class vehicles. Northrop Grumman represents the defense-stable archetype through classified solid motor programs.
| Leading Market Players |
|---|
| SpaceX |
| Blue Origin |
| Northrop Grumman |
| Lockheed Martin |
| Boeing |
| Aerojet Rocketdyne |
| Mitsubishi Heavy Industries |
| Safran |
| IHI Corporation |
| Others |
Pricing and Supply Chain Analysis
Fixed-price milestone contracts for engine qualification programs lock in supply access for domestic launch operators while compressing price visibility for foreign suppliers facing U.S. domestic sourcing mandates. NASA and the U.S. Space Force now require flight-proven hardware demonstrations before production authorization, binding supplier cash flows to technical achievement gates.
Pricing Analysis
Long-term offtake agreements dominate procurement for reusable liquid engines, with SpaceX and Blue Origin securing multi-year production slots that freeze unit costs against nickel-based superalloy volatility. Price differentiation rests on certification grade—human-rating standards command substantial premiums over commercial satellite launch tiers—and volume scale, where constellation deployment contracts extract economies from standardized engine interfaces. Cost compression in the expendable engine tier is intensifying as reusable flight-proven hardware displaces single-use alternatives. Small satellite manufacturers exhibit highest price sensitivity, while deep-space exploration contractors prioritize mission assurance over unit economics.
Supply Chain Analysis
Port congestion on U.S. Gulf Coast trade lanes elevates inbound logistics costs for cryogenic propellant handling equipment and specialized turbopump castings. Manufacturing concentrates in the United States, France, and Japan, with domestic production anchored in Texas and Florida launch clusters. Supply chains draw from concentrated nickel-based superalloy suppliers for high-temperature components and helium reserves for pressure-fed systems. Single-source vulnerability in aerospace-grade alloy qualification creates bottlenecks for new engine programs. Distribution runs through vertically integrated launch operators with captive manufacturing, bypassing traditional tiered supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified turbopump engineers and additive manufacturing technicians with flight-heritage credentials represent the scarcest capabilities, constraining how quickly new engine architectures reach production scale.
For Market Incumbents: Secure additive manufacturing certification pathways ahead of FAA human-rating deadlines to capture refurbishment economics from reusable system mandates. Anchor supply relationships with domestic superalloy producers before capacity constraints tighten, as emerging launch operators bid for limited qualification slots. The shift from cost-plus to fixed-price contracts threatens margin stability for suppliers without captive launch integration. For New Entrants and Emerging Players: Differentiate on green propellant formulations—specifically ammonium dinitramide alternatives—to capture ESA Clean Space procurement preference and REACH-compliant satellite contracts. The Indian heavy-lift co-development channel offers the most penetrable geography, with ISRO's commercial arm actively seeking foreign propulsion partnerships. A joint-qualification approach with established test facilities accelerates flight heritage accumulation without full infrastructure investment. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors suppliers with demonstrated reusable flight cycles and green propellant qualification progress. Long-term viability hinges on positioning ahead of hydrazine replacement mandates across European institutional programs. Watch FAA streamlined licensing throughput as the inflection signal—accelerated flight-proven vehicle certification indicates operational tempo scaling that rewards production-ready capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Engine Certification | FAA streamlined licensing for flight-proven vehicles accelerates revenue capture from constellation deployment contracts. |
| Green Propellant Transition | ESA Clean Space mandates for ADN formulations open procurement preference for REACH-compliant satellite manufacturers. |
| Additive Manufacturing Scale-Up | 3D-printed combustion chambers reduce refurbishment overhead for methane-oxygen staged combustion engines. |
| Domestic Superalloy Integration | Backward integration into nickel-based alloy supply hedges against qualification timeline extensions from concentrated sources. |
| Heavy-Lift Co-Development Partnership | ISRO's Satish Dhawan expansion creates foreign technology access channels outside U.S. domestic sourcing restrictions. |
Research Methodology
A spread of perspectives from propulsion engineering directors, launch vehicle program managers, satellite procurement leads, and FAA certification specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through NASA contract announcements, FAA licensing databases, ESA procurement records, and SEC filings from publicly traded aerospace suppliers. Bottom-up engine production estimates and top-down launch demand projections were triangulated against customs data for superalloy trade flows.
Segmentation dimensions modeled include propulsion type, technology architecture, application mission profile, and end-user procurement category across the analysis window. CAGRs were derived from installed base replacement rates and new constellation deployment schedules. Forecast inputs incorporated reusable flight-proven engine accumulation curves and green propellant qualification timelines from ESA technology roadmaps.
The analysis sits within stated boundaries; outcomes outside sustained launch cadence growth or accelerated domestic sourcing enforcement would require recalibration. Forecasts reflect assumptions about FAA licensing efficiency and REACH chemical restriction implementation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Narrow-Body Turbofan Engine Shop Visit Services Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Aircraft Engine Nacelle Market
Aircraft Engine Systems and Services
Angle of Attack Sensor Market
Aircraft Engine Systems and Services
Global Aircraft Engine Fuel Systems Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Gas Turbine Service Market