
 Helicopter Engine Market | 2026-2036
Helicopter Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter Engine Market Intelligence
A generational gap in specialized aerospace engineering talent is unwinding the pace of next-generation powertrain development, forcing manufacturers to invest in training. Safran SA specializes in turboshaft engines for a broad spectrum of civil and military helicopters. GE Aerospace leverages its vast experience in military contracts to secure large-volume orders. Rolls-Royce Holdings plc competes on high-performance engine solutions for medium and heavy-lift rotorcraft, differentiating its portfolio.
A helicopter engine is a specialized gas turbine power plant engineered for the high power-to-weight ratio required for vertical flight. Its core includes a compressor, combustor, and turbine that drive the main and tail rotor systems. Turboshaft engine designs dominate the product landscape, offering superior efficiency for most rotorcraft classes. Demand from military forces constitutes a primary end-user segment, setting stringent requirements for engine durability, reliability, and performance under extreme conditions.
Regulatory oversight from the United States' FAA and compliance with European standards like CE marking dictates airworthiness certification. Concurrently, environmental frameworks including the EU Green Deal and Japan's METI-supported initiatives are establishing stricter emissions and noise standards. Engine manufacturers must therefore balance demands for increased power output with evolving sustainability mandates to maintain market access.
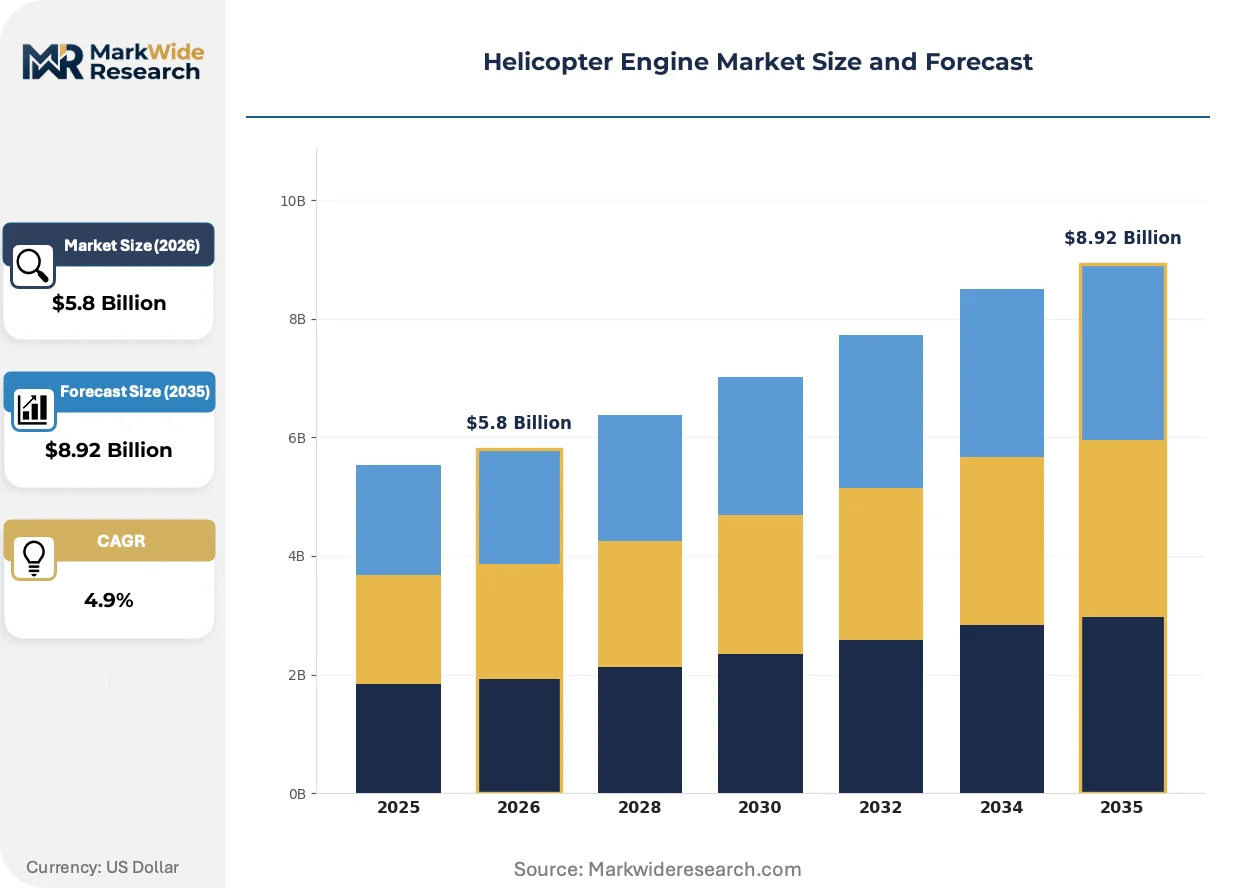
Market Dynamics
A critical shortage of specialized aerospace engineers is slowing next-generation powertrain development. This talent gap forces manufacturers to fund extensive internal training and university partnerships to secure a future skills pipeline, impacting project timelines across the industry.
Growth Catalysts
- Emergency Services Growth:Demand from search and rescue and medical evacuation sectors requires engines with high reliability and rapid power response for time-sensitive missions.
- Sustainability Mandates:Frameworks like the EU Green Deal drive development of engines compatible with Sustainable Aviation Fuels (SAFs), catalyzing fleet modernization programs.
- Military Modernization Cycles:United States helicopter fleet upgrades create consistent, large-volume demand for advanced turboshaft engines meeting strict performance specifications.
Market Restraints
- Material Cost Volatility:Engine production relies on specialty materials like cobalt and nickel-based superalloys, whose prices are volatile and subject to supply chain disruptions.
- Stringent Certification:Lengthy and costly airworthiness certification from bodies like the FAA and EASA creates high barriers to entry and delays new engine introductions.
- Supplier Concentration:A limited number of suppliers for critical forged components like turbine disks creates production bottlenecks and increases dependency risk for manufacturers.
Strategic Opportunities
- Hybrid-Electric Propulsion:Developing hybrid-electric powertrains for light helicopters and Urban Air Mobility (UAM) platforms presents a key opportunity for new engine architectures.
- Southeast Asian Expansion:The archipelagic geography of nations like Indonesia and the Philippines is an underpenetrated market for helicopter transport, driving utility rotorcraft demand.
- Additive Manufacturing:Using additive manufacturing for complex components can reduce weight and shorten supply chains, offering a competitive edge in production efficiency.
Industry Challenges
- Specialized Talent Scarcity:A generational gap persists, with a shortage of engineers expert in high-temperature metallurgy and advanced combustion systems needed for next-generation designs.
- Legacy System Integration:Integrating digitally controlled engines with older helicopter airframes presents significant technical and financial challenges for upgrade programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter Engine Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.92 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turboshaft, Turbojet, Turboprop, Piston Technology: Aftercooler, Variable Geometry Turbocharger, Free Turbine, Digital Engine Control Application: Search & Rescue, Agricultural Spraying, Law Enforcement, Firefighting, Passenger Transport End User: Airlines, Military Forces, Emergency Services, Private Operators |
| Companies Covered | RTX Corporation, Pratt & Whitney Canada, Safran SA, Kawasaki Heavy Industries Ltd., IHI Corporation, GE Aerospace, Honeywell International Inc., MTU Aero Engines, Rolls-Royce Holdings plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter Engine Market Strategic Shifts & Innovations
The dual pressures of environmental sustainability and operational performance are redefining powertrain design. Engine manufacturers balance these conflicting demands, leading to innovative architectures and materials that cater to specific mission requirements.
Advanced composite materials, like Ceramic Matrix Composites (CMCs), are used in engine hot sections for lower weight and higher thermal efficiency. Military and heavy-lift civil operators are primary adopters, seeking performance gains despite high initial costs. The adoption of CMCs is bifurcating the market between premium-priced engines and conventional metallic designs.
Europe's ReFuelEU Aviation initiative is a key regulatory driver. The policy mandates increasing blends of Sustainable Aviation Fuel (SAF), compelling manufacturers to certify engines for full SAF compatibility. The region's civil and parapublic helicopter sectors are most affected, accelerating R&D into fuel system and combustor modifications.
A shift from outright engine purchasing to power-by-the-hour (PBH) service agreements is underway. This model transfers maintenance and availability risk to the engine manufacturer, altering traditional aftermarket revenue streams. This trend is most visible among large fleet operators in North America, especially within corporate and emergency medical services.
Helicopter Engine Market Segmentation
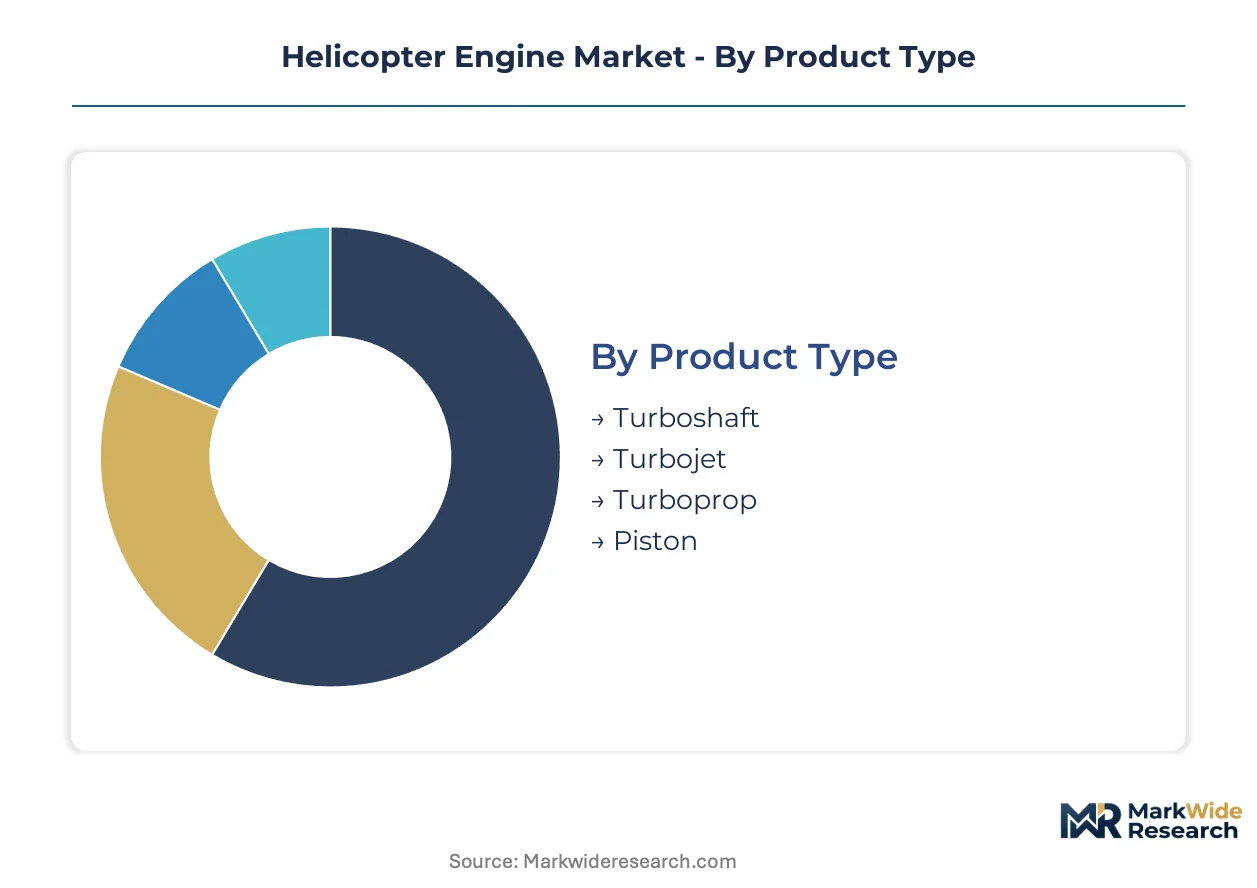
The helicopter engine market exhibits distinct segmentation, reflecting the diverse operational demands and technological requirements across its end-user base. Understanding these segments is crucial for manufacturers to tailor product development, certification strategies, and market penetration efforts effectively.
Product Type:
Regulatory bodies like the FAA in the United States and EASA in Europe influence product type adoption through certification standards and operational requirements for different rotorcraft classes.
- Turboshaft:This engine type dominates the market, characterized by its high power-to-weight ratio and shaft power delivery to the rotor system. Demand is concentrating in military rotorcraft and large civil transport helicopters across the United States and France.
- Turbojet:Primarily designed for thrust generation, turbojet engines are less common in helicopters, typically reserved for niche high-speed or experimental applications. Demand arises from specialized military programs or advanced research initiatives in countries such as Russia and China.
- Turboprop:While prevalent in fixed-wing aircraft, turboprop engines are rarely used for direct helicopter propulsion, sometimes serving as auxiliary power units.
- Piston:Piston engines power smaller, lighter helicopters, offering simpler maintenance and lower initial costs for entry-level and recreational aircraft.
Turboshaft engines handle the majority of throughput; advanced turboshaft designs are the fastest mover on share due to continuous innovation.
Technology:
Specific technological advancements enhance engine performance across various mission profiles, from high-altitude operations to fuel efficiency for extended flights.
- Digital Engine Control:Full Authority Digital Engine Control (FADEC) systems optimize engine performance, improve fuel efficiency, and provide critical diagnostic data in real-time. Demand is high from new generation military and commercial rotorcraft in the United States and France.
- Free Turbine:This design mechanically separates the gas generator from the power turbine, allowing independent rotor speed control and enhancing operational flexibility. Demand comes from medium and heavy-lift helicopters requiring adaptable power delivery in Germany and Italy.
- Variable Geometry Turbocharger:Variable geometry turbochargers improve engine response and efficiency across varying altitudes and atmospheric conditions.
- Aftercooler:Aftercoolers reduce the air intake temperature, thereby increasing air density and engine power output for enhanced performance.
Digital Engine Control systems are central to modern powertrain integration, while free turbine designs continue to offer critical operational flexibility.
Application:
Diverse operational requirements from various public and private sector entities drive specialized engine configurations across the market.
- Search & Rescue:This application requires engines with high reliability, rapid power response, and extended endurance capabilities for critical, time-sensitive missions. Demand is strong from government agencies and parapublic operators in Canada and Australia.
- Passenger Transport:Focuses on smooth operation, low noise levels, and fuel efficiency for corporate, VIP, and offshore platform transport services. Demand originates from commercial fleet operators in the United Arab Emirates and the United Kingdom.
- Agricultural Spraying:Demands robust engines capable of sustained low-altitude operations and resistance to environmental contaminants.
- Law Enforcement:Requires agile engines for surveillance, rapid deployment, and pursuit operations in both urban and rural environments.
- Firefighting:Needs powerful engines for heavy-lift water drops and sustained operations under challenging, high-temperature conditions.
Emergency Services applications are expanding most quickly, while passenger transport maintains a consistent demand base.
End User:
The concentrated purchasing power of large end-user segments significantly influences engine development cycles and production volumes.
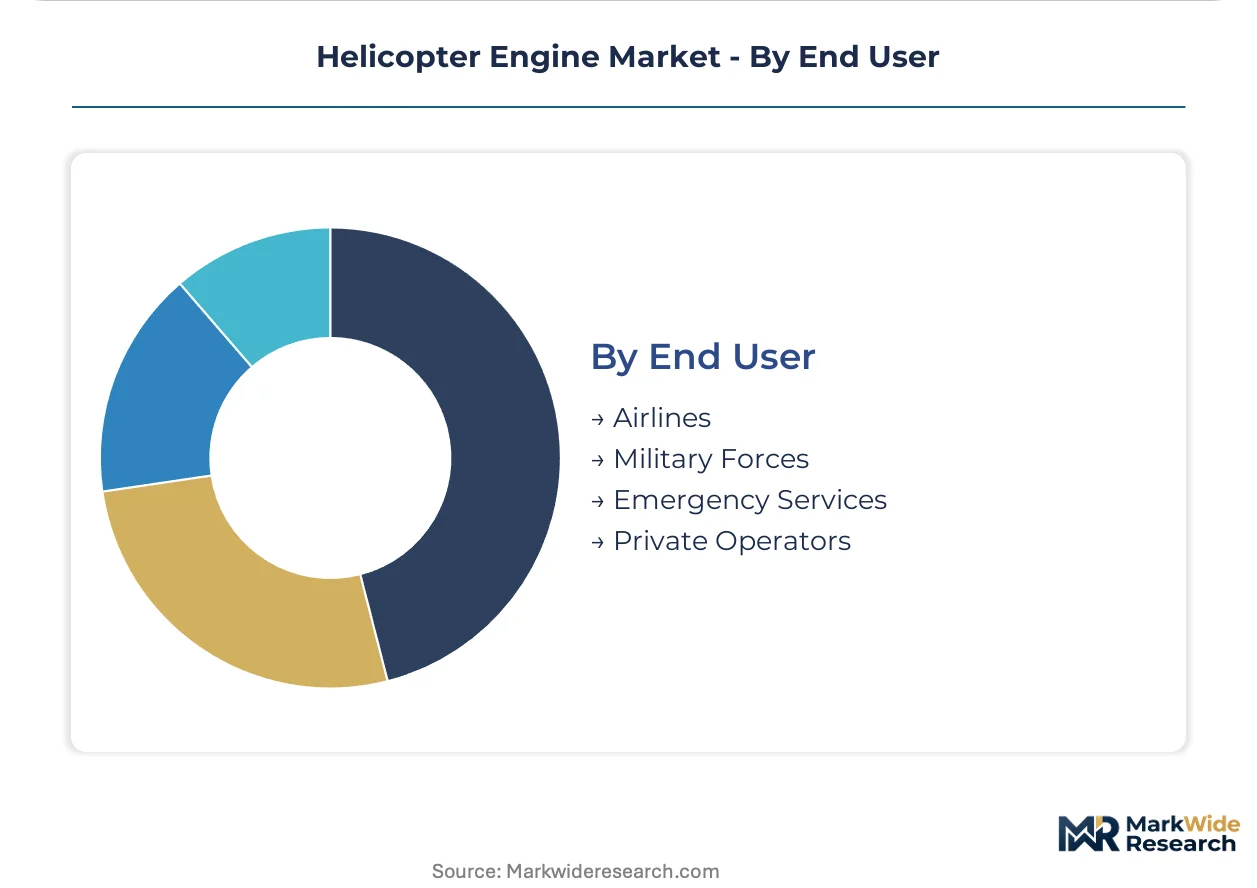
- Military Forces:This segment sets stringent requirements for engine durability, performance under extreme conditions, and operational readiness for combat, transport, and reconnaissance missions. Demand is consistently high from the United States Department of Defense and European defense ministries.
- Emergency Services:This includes medical evacuation, law enforcement, and search and rescue, requiring engines optimized for rapid deployment, reliability, and specific power profiles for critical missions. Demand from national emergency response agencies in Germany and Japan is substantial.
- Private Operators:This segment seeks engines balancing performance, fuel efficiency, and lower maintenance costs for corporate, personal, and charter use.
- Airlines:Primarily uses helicopters for niche regional connections or offshore oil and gas transport, demanding high reliability and operational efficiency.
Military Forces account for the largest share of high-performance engine procurement, with Emergency Services showing substantial growth in recent years.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for helicopter engines varies significantly by geography, with military and private operator fleets dominating demand in some regions. Other areas prioritize emergency services and civil transport applications. This regional differentiation influences engine development and market penetration strategies globally.
United States
United States military modernization cycles and extensive private operator fleets drive consistent demand for advanced turboshaft engines. FAA airworthiness certification dictates stringent requirements for new engine introductions. Manufacturers in states like Ohio and Connecticut actively develop next-generation powertrains.
France
French demand concentrates on advanced turboshaft engines for military rotorcraft and sophisticated civil transport. Compliance with CE marking and the EU Green Deal mandates engine compatibility with sustainable aviation fuels. Companies in the Paris region, such as Safran SA, focus on R&D for future-proof propulsion systems.
Germany
Germany's market requires robust engines for medium and heavy-lift rotorcraft, alongside specialized units for emergency services. The EU Green Deal significantly influences engine development, pushing for lower emissions and noise. Munich-based manufacturers, including MTU Aero Engines, prioritize free turbine designs for enhanced operational flexibility.
Canada
Canadian demand for helicopter engines stems primarily from active search and rescue and medical evacuation sectors. National aviation authorities enforce strict reliability and rapid response criteria for these applications. Companies in Quebec, like Pratt & Whitney Canada, develop specialized engines to meet demanding operational profiles.
Japan
Japanese emergency services and a strong focus on environmental sustainability drive engine demand for quiet and efficient rotorcraft. METI-supported initiatives establish stringent emissions and noise standards for new designs. Manufacturers in the Tokyo region, such as IHI Corporation, invest in technologies compatible with sustainability mandates.
Helicopter Engine Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the helicopter engine market. These dominant players, often large aerospace conglomerates, control significant intellectual property and manufacturing capabilities. The competitive landscape features integrated turboshaft engine manufacturers, high-performance solution providers, and niche component specialists. Companies pursue strategic partnerships and technology licensing agreements to expand their portfolio and geographic reach.
Within the integrated turboshaft engine manufacturing segment, GE Aerospace exemplifies a player leveraging extensive military contract experience for securing large-volume orders across various platforms. Safran SA, a French aerospace company, represents a broad spectrum turboshaft engine specialist, serving both civil and military helicopters with diverse power requirements. Rolls-Royce Holdings plc, a UK-based engineering company, occupies a position focused on high-performance engine solutions, differentiating its portfolio for medium and heavy-lift rotorcraft applications. These entities collectively anchor the market's premium and high-performance tiers, influencing broader industry standards and technological trajectories.
| Leading Market Players |
|---|
| RTX Corporation |
| Pratt & Whitney Canada |
| Safran SA |
| Kawasaki Heavy Industries Ltd. |
| IHI Corporation |
| GE Aerospace |
| Honeywell International Inc. |
| MTU Aero Engines |
| Rolls-Royce Holdings plc |
| Others |
Cost & Logistics Intelligence
FAA airworthiness certification gates engine supply qualification and influences pricing differentiation across the helicopter engine market. This stringent oversight ensures only compliant systems reach end-users.
Pricing Analysis
Long-term contract-based offtake agreements define the dominant pricing model for helicopter engines, especially for military and large civil fleet operators. Price differentiation stems from engine performance specifications, such as power-to-weight ratio, and the level of after-sales service bundling, including power-by-the-hour arrangements. Pricing pressure stems from intense competition among a few dominant manufacturers for high-volume military contracts. Military forces are least price-sensitive due to stringent performance requirements, while private operators exhibit higher price sensitivity.
Supply Chain Analysis
Inbound logistics costs, particularly for specialty material shipments from regions like China and the Democratic Republic of Congo, impact helicopter engine production. Geographic supply concentration for critical forged components like turbine disks exists in countries such as the United States and Germany. Raw material dependencies include cobalt and nickel-based superalloys. A key supply chain risk is supplier concentration for critical components, leading to production bottlenecks. Downstream distribution typically runs through direct manufacturer sales and authorized service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The helicopter engine market represents a defensive moat story, underpinned by significant regulatory entrenchment through stringent airworthiness certification processes. This creates high barriers to entry for new competitors.
For Market Incumbents: Fortify core turboshaft engine portfolios by accelerating R&D into Sustainable Aviation Fuel compatibility and advanced composite materials. Invest in training programs and university partnerships to address the specialized talent scarcity, mitigating the threat of delayed next-generation powertrain development. Strengthen channel control through expanded power-by-the-hour service agreements, locking in aftermarket revenues against potential alternative propulsion technologies.
For New Entrants and Emerging Players: Lead with hybrid-electric powertrain development for light helicopters and Urban Air Mobility platforms, targeting underpenetrated segments. Focus on Southeast Asia's archipelagic geography as a penetrable market for utility rotorcraft. Develop additive manufacturing capabilities to offer a competitive edge in production efficiency and reduce material cost volatility. Target specialized niches such as agricultural spraying or law enforcement with tailored, cost-effective engine solutions.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the advanced turboshaft engine development segment, indicating sustained long-term viability for established players. Focus on acquiring companies with specialized expertise in high-temperature metallurgy or digital engine control systems for next-generation designs. The long product development cycles and stringent certification requirements offer stable returns over a five-to-ten-year window. Watch for increased private equity investment in hybrid-electric propulsion startups as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF Compatibility Certification | Ensures market access in regions with strict environmental mandates like Europe. |
| Additive Manufacturing Investment | Reduces component weight and shortens supply chains for next-generation engines. |
| Power-by-the-Hour Expansion | Transfers maintenance risk to manufacturers and secures recurring aftermarket revenue. |
| Hybrid-Electric Powertrain R&D | Captures new market opportunities in Urban Air Mobility and light helicopter segments. |
| Specialized Talent Development | Addresses the generational gap in aerospace engineering for future engine designs. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings. Interviews included helicopter OEM procurement leads, engine design engineers, MRO managers, and military aviation officers. Secondary data sources comprised FAA and EASA airworthiness directives, and company annual filings. This approach ensures robust bottom-up and top-down triangulation of market insights.
Sensitivity analysis on key market variables informs the forecast framework, projecting market evolution across the analysis window. Segmentation dimensions modeled include product type, technology, application, end-user, and regional demand patterns. Compound annual growth rates were derived from historical trends and projected technological adoption rates. Key forecast inputs include military modernization budgets and Sustainable Aviation Fuel mandates.
Forecasts assume regulatory continuity in FAA and EASA standards; material policy shifts would require re-modeling. The analysis reflects current geopolitical stability and raw material supply chain configurations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Narrow-Body Turbofan Engine Shop Visit Services Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
Angle of Attack Sensor Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
America Aircraft Engines Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market
Aircraft Engine Systems and Services
General Aviation Engines Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market