
 Aircraft Engine Blade Market | 2026-2036
Aircraft Engine Blade Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Engine Blade Market Intelligence
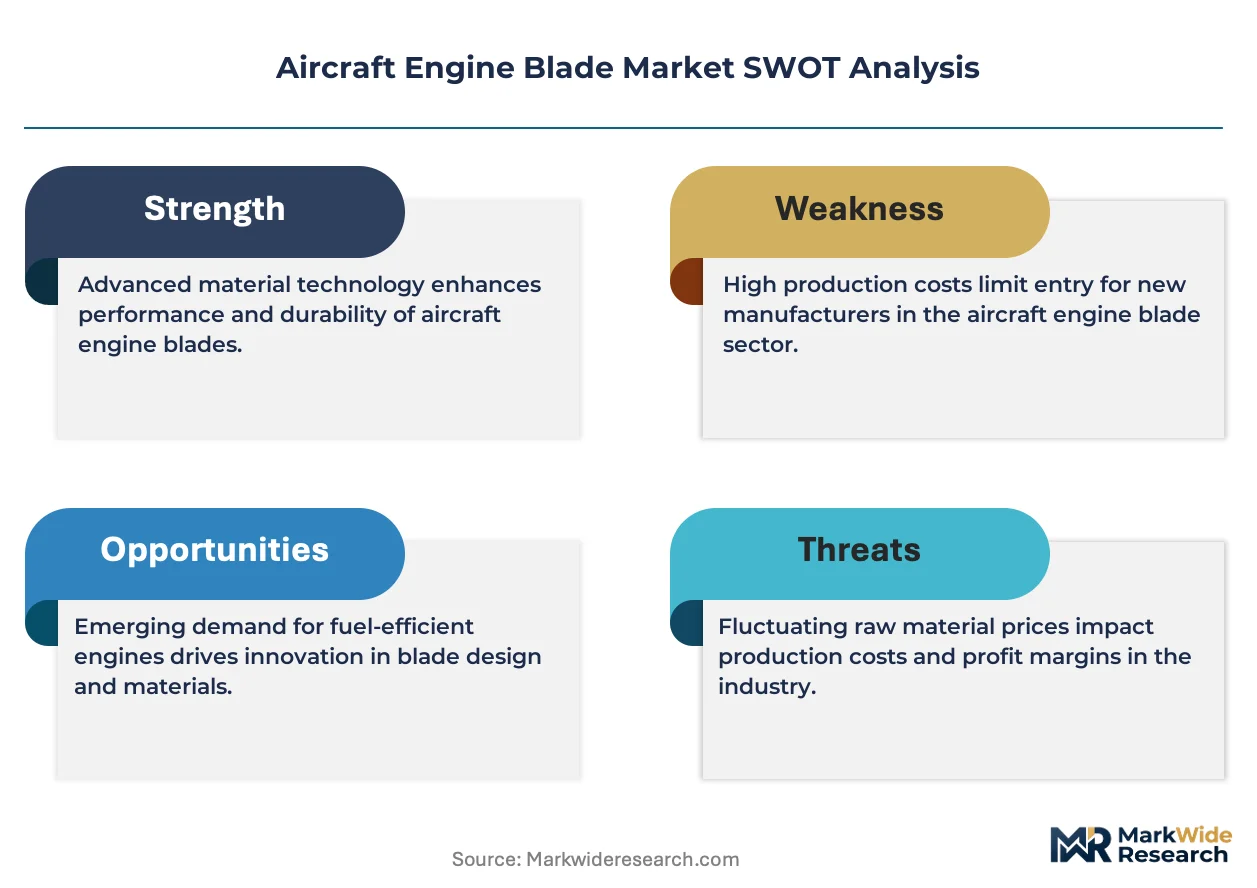
The EU Green Deal's sustainable aviation mandates are broadening the competitive landscape for advanced engine components. General Electric Company leverages its extensive R&D in composite materials to meet new efficiency targets. Safran SA specializes in high-pressure turbine blade technology for next-generation engines. MTU Aero Engines AG competes through its expertise in specialized manufacturing and advanced repair services for high-value components.
An aircraft engine blade is a critical airfoil component within a gas turbine engine, designed to either compress air or extract energy from high-velocity gas flows. These components are engineered from advanced materials like nickel or titanium alloys to withstand extreme temperatures, high rotational speeds, and significant stress. In application, their primary purpose is to enable the thermodynamic cycle that generates thrust. Composite materials are gaining share over traditional alloys due to weight reduction benefits. Fan blades represent a significant portion of the market by volume, while high-pressure turbine blades command the highest value due to material and cooling complexity.
Certification from bodies like the FAA in the United States and EASA in Europe sets stringent airworthiness and material traceability standards. These regulations directly influence design cycles and the qualification process for new materials and manufacturing methods, such as those used in additive manufacturing. Stakeholder success depends on navigating the trade-offs between manufacturing cost, material performance, and lifecycle emissions.
Market Dynamics
The aircraft engine blade market's evolution is governed by the imperative to enhance thermodynamic efficiency. This pressure, driven by both airline operating economics and stringent environmental regulations, is accelerating the industrialization of advanced materials and manufacturing processes like additive manufacturing to meet next-generation performance targets.
Growth Catalysts
- Fleet Modernization Mandates:The EU Green Deal and ICAO's CORSIA scheme compel airlines to invest in new-generation, fuel-efficient aircraft, directly stimulating demand for engines featuring advanced blade technologies.
- Civil Aviation Expansion:Sustained growth in passenger and cargo air traffic, particularly in China and India, drives orders for new narrow-body and wide-body aircraft, creating a consistent demand stream for engine components.
- Advanced Material Adoption:The maturation of ceramic matrix composites (CMCs) and advanced single-crystal superalloys enables higher engine operating temperatures, leading to significant improvements in fuel burn and thrust.
Market Restraints
- Raw Material Volatility:The supply and cost of strategic metals like titanium, nickel, and cobalt are subject to significant geopolitical and market volatility, creating cost pressures for blade manufacturers.
- Stringent Certification Cycles:New blade designs, materials, and manufacturing methods face extensive and costly qualification processes from bodies like the FAA and EASA, which can delay market entry.
- Manufacturing Complexity:The production of turbine blades, especially those with complex internal cooling geometries or made from single-crystal alloys, requires highly specialized equipment and expertise, limiting the supplier base.
Strategic Opportunities
- MRO Market Expansion:Developing advanced repair and coating capabilities for blades in high-growth MRO hubs, such as those in the Middle East and Southeast Asia, presents a significant service revenue opportunity.
- Alternative Propulsion Systems:Designing specialized fan blades and turbine components for emerging hybrid-electric and hydrogen-fueled engine architectures offers a pathway into next-generation aviation platforms.
- Additive Manufacturing Services:Offering certified, 3D-printed metal blades as a service for low-volume, legacy, or prototype engine programs can capture niche, high-margin demand from MROs and specialty engine developers.
Industry Challenges
- Specialized Talent Scarcity:A critical shortage of skilled labor, including metallurgists, non-destructive inspection technicians, and engineers with expertise in computational fluid dynamics, constrains production and innovation.
- High Capital Investment:The qualification and scaling of advanced manufacturing lines, particularly for additive manufacturing and automated inspection, require substantial upfront capital expenditure.
- Intellectual Property Protection:Safeguarding proprietary blade designs, cooling channel configurations, and unique alloy compositions is a persistent challenge in a globally competitive environment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Engine Blade Market |
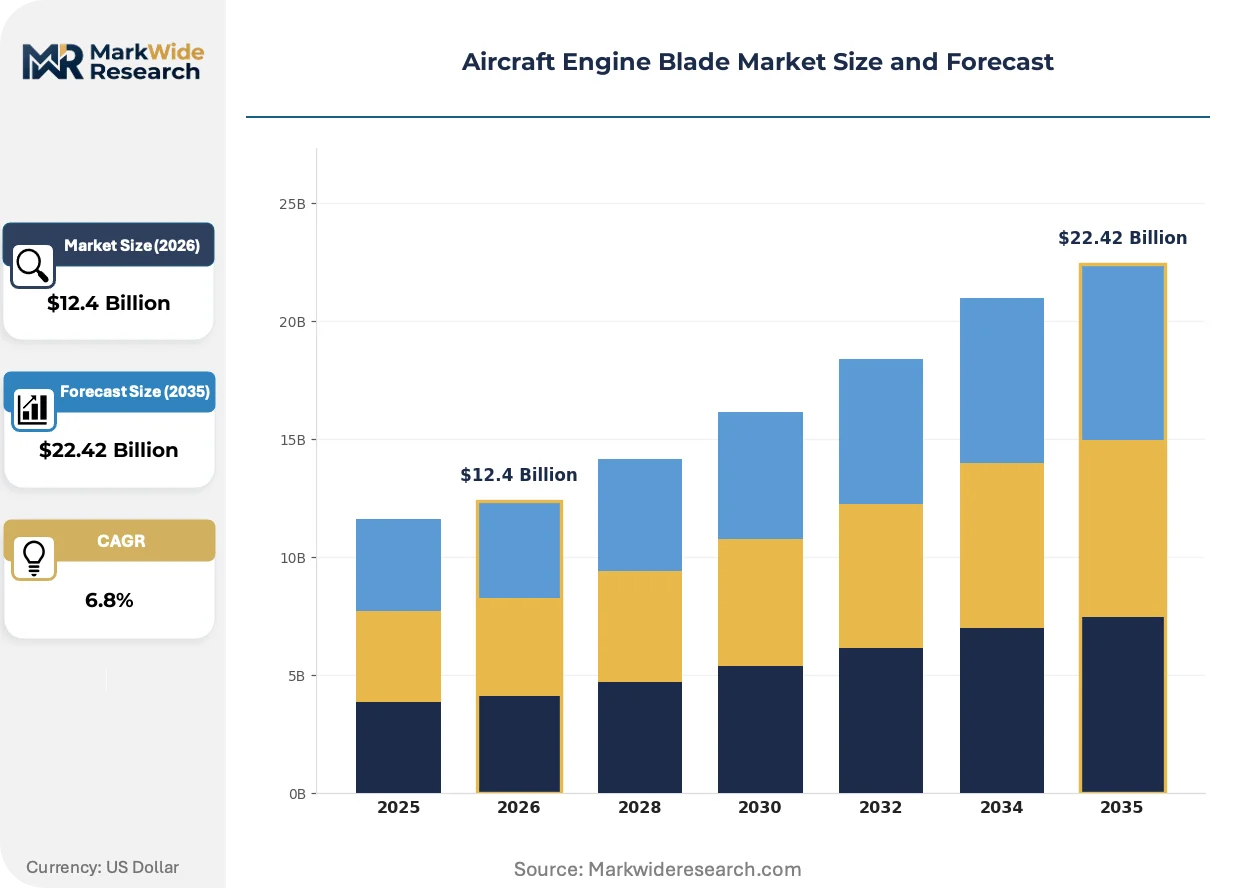
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Blade Type: Fan Blade, Compressor Blade, Turbine Blade, Exhaust Blade Material: Nickel Alloys, Titanium Alloys, Composite Materials, Steel Application: Civil Aviation, Military Aviation, Business Jets, Helicopters Manufacturing Process: Casting, Forging, Machining, Additive Manufacturing |
| Companies Covered | General Electric Company, Safran SA, Raytheon Technologies Corporation, Albany International Corp., Alcoa Corporation, MTU Aero Engines AG, Pratt & Whitney, GE Aerospace, GKN Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Engine Blade Market Strategic Shifts & Innovations
The industrial logic of the aircraft engine blade sector is being reconfigured by the convergence of digital engineering and materials science. This synthesis allows for the creation of components that are not only lighter and more heat-resistant but are also designed for an entire lifecycle of performance and sustainability.
Additive manufacturing, particularly powder bed fusion techniques, allows for the production of turbine blades with highly complex internal cooling channels that are impossible to create with traditional casting. Engine OEMs and advanced MRO providers are adopting this for rapid prototyping and the production of non-critical components. This capability is decentralizing component manufacturing away from a few specialized foundries, enabling more distributed and responsive supply chains.
Regulations from the FAA and EASA are increasingly mandating comprehensive lifecycle traceability for critical engine parts. This forces manufacturers to implement digital tracking systems that record a blade's history from raw material melt to in-service performance and eventual retirement. The high-pressure turbine blade segment is most affected, as producers must now provide verifiable data on material provenance and manufacturing process integrity to meet airworthiness standards.
Airlines are progressively shifting from transactional component purchases toward long-term, performance-based service contracts for entire engine systems. This model transfers the risk and cost of blade maintenance and replacement to the engine manufacturer, creating a powerful incentive to design for maximum on-wing lifespan. The trend is most visible in the global wide-body aircraft market, where engine reliability is a primary determinant of operational efficiency.
Aircraft Engine Blade Market Segmentation
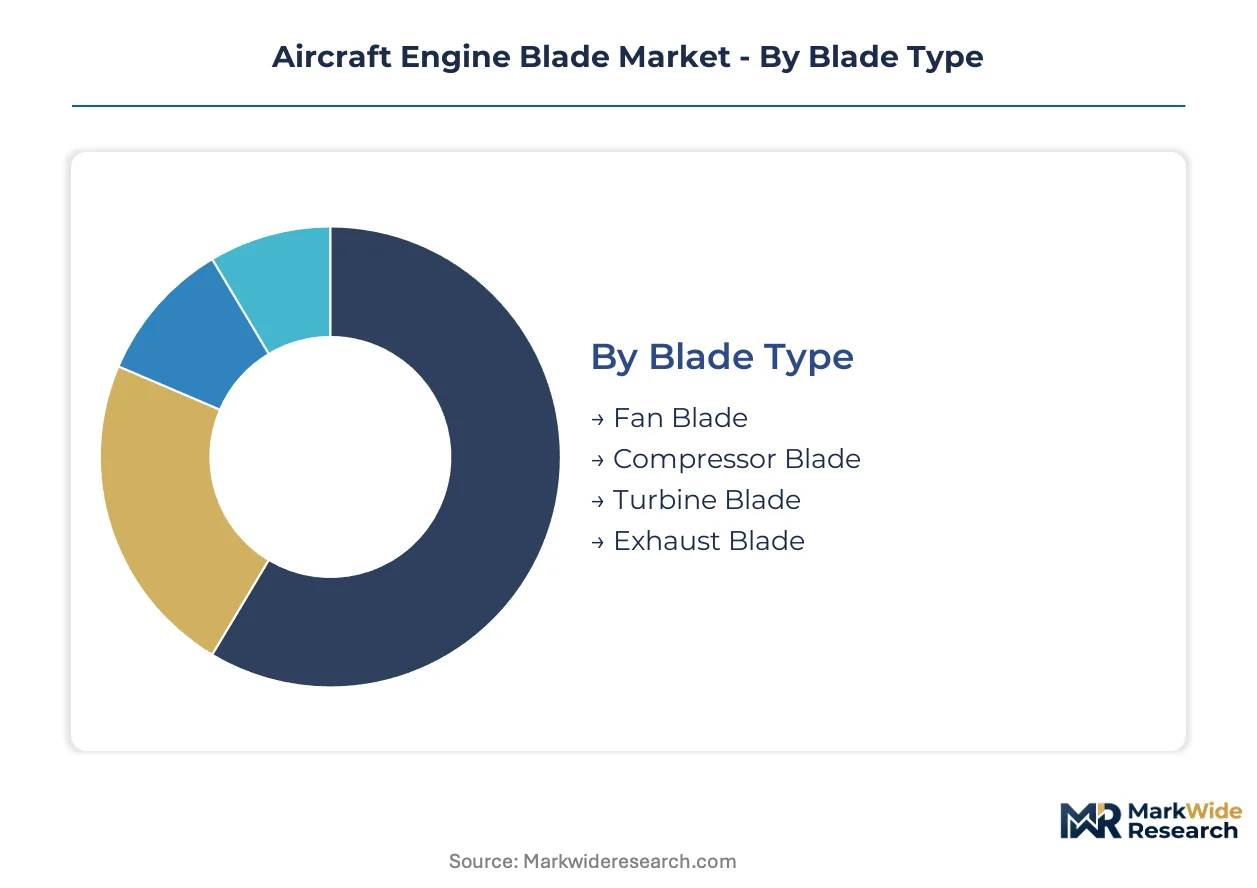
Understanding the segmentation of the aircraft engine blade market provides clarity on demand drivers and technological shifts. Different blade types, materials, applications, and manufacturing processes exhibit distinct value chains and growth trajectories. This granular view enables stakeholders to strategically allocate resources and anticipate competitive shifts.
Blade Type:
Supply concentration for specific blade types reflects the specialized expertise and capital investment required for their production.
- Fan Blade:These large, front-mounted airfoils generate significant thrust by accelerating air through the engine core and around it. Demand for fan blades is concentrating in new-generation, fuel-efficient aircraft programs due to their direct impact on engine bypass ratio.
- Turbine Blade:Located in the hot section, these components extract energy from high-velocity, high-temperature gas flows to drive the compressor. High-pressure turbine blades command premium value due to their advanced material requirements and intricate cooling channel designs for extreme operating conditions.
- Compressor Blade:These airfoils progressively compress incoming air, increasing its pressure before combustion.
- Exhaust Blade:Positioned at the rear of the engine, these guide the exhaust gases to optimize thrust and reduce noise.
Today's leader: Fan Blade. Tomorrow's challenger: Turbine Blade.
Material:
The cost tier of materials directly influences the overall production economics and performance characteristics of engine blades.
- Composite Materials:These advanced materials, often ceramic matrix composites (CMCs), offer superior strength-to-weight ratios and high-temperature resistance. Their adoption is accelerating in next-generation engines for significant fuel efficiency gains and reduced operational weight, particularly in high-bypass turbofans.
- Nickel Alloys:Superalloys based on nickel provide exceptional strength and creep resistance at very high temperatures, making them essential for turbine section components. Demand for nickel alloys remains strong, driven by the need for extreme thermal stability in the hot section of modern jet engines.
- Titanium Alloys:These alloys offer excellent strength and corrosion resistance, primarily used in compressor and fan sections due to their lighter weight.
- Steel:Traditional steel alloys are utilized in less critical sections or for specific structural components where high-temperature performance is not the primary driver.
Composite Materials are expanding most quickly, while Nickel Alloys maintain a critical performance niche.
Application:
Volume demand across different aircraft applications dictates manufacturing scale and design priorities for engine blades.
- Civil Aviation:This segment encompasses blades for commercial passenger and cargo aircraft, from narrow-body to wide-body jets. Fleet modernization mandates and sustained growth in global air traffic, especially in China and India, are driving substantial demand for new engine blades.
- Military Aviation:Blades for military aircraft, including fighter jets, transport planes, and bombers, require specialized designs for extreme performance and durability. This sector sees consistent demand due to defense spending and aircraft upgrades, particularly for advanced combat platforms.
- Business Jets:This niche segment requires blades optimized for smaller, high-performance engines, emphasizing reliability and lower noise profiles for corporate travel.
- Helicopters:Rotorcraft engines use blades designed for vertical lift and propulsion, often requiring robust materials to withstand unique operational stresses and vibrations.
Civil Aviation demand is climbing fastest, with Military Aviation providing a stable base.
Manufacturing Process:
The maturity of manufacturing processes ranges from established techniques to disruptive innovations, each with distinct cost and capability profiles.
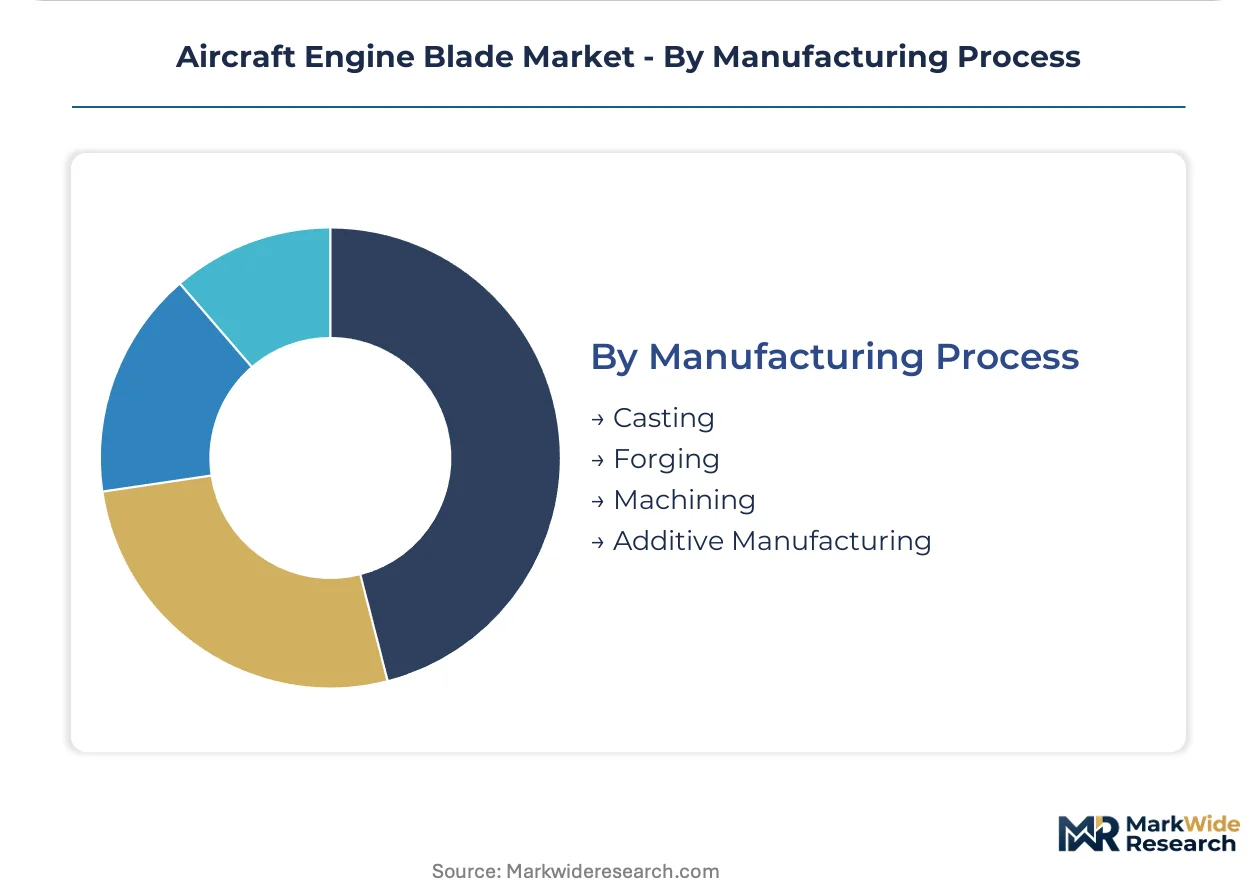
- Additive Manufacturing:This process, particularly powder bed fusion, builds complex blade geometries layer by layer, enabling intricate internal cooling channels. Its adoption is driven by the need for rapid prototyping, reduced material waste, and the production of highly optimized, lightweight components.
- Machining:This traditional subtractive process uses precision tools to shape blades from solid billets or castings, achieving tight tolerances and smooth surface finishes. Demand for machining remains critical for final finishing and for producing blades from hard-to-work alloys where additive manufacturing is not yet fully certified.
- Casting:This method involves pouring molten metal into molds to form blades, commonly used for initial shapes before further processing.
- Forging:Forging shapes metal through compressive forces, improving grain structure and mechanical properties, often used for high-strength components.
Additive Manufacturing shows the steepest expansion trajectory, while Machining remains essential for precision finishing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metallurgical and aerospace engineering talent pools in established aviation centers anchor the global aircraft engine blade market. These hubs drive innovation in advanced materials and manufacturing processes for next-generation engine components, concentrating demand in countries with robust aerospace manufacturing ecosystems.
United States
United States demand is driven by extensive military aviation upgrades and commercial fleet modernization programs. The FAA certification process sets stringent airworthiness standards for new blade designs. Connecticut's "Aerospace Alley" focuses on advanced engine component manufacturing, fostering innovation.
Germany
Germany's market activity centers on civil aviation engine development and robust MRO services for European fleets. EASA regulations significantly influence the design and repair of critical engine components. The Munich aerospace cluster specializes in high-value turbine blade production, supporting engine manufacturers.
China
China's demand is accelerating due to ambitious domestic aerospace manufacturing expansion and rapid civil aviation growth. The country's GB standards guide material and manufacturing process integrity for locally produced engine blades. Xi'an serves as a major hub for domestic aircraft engine production and advanced material research.
India
India experiences significant demand from fleet expansion for passenger and cargo air traffic and ongoing defense modernization initiatives. The country's national aviation authorities oversee certification of imported and domestically produced engine parts. Bengaluru's aerospace ecosystem focuses on MRO services and component manufacturing for aircraft platforms.
France
France's market is propelled by new generation engine programs and its strong export-driven aerospace industry. EASA airworthiness directives shape the development and qualification of advanced engine components. Toulouse, a major aerospace center, focuses on engine integration and blade technology advancements.
Aircraft Engine Blade Market Key Industry Players
The competitive structure tilts toward a mix of vertically integrated engine OEMs and specialized component manufacturers. These major players control critical intellectual property and advanced manufacturing capabilities essential for complex blade geometries. Strategic archetypes include large aerospace conglomerates, niche material specialists focusing on high-temperature alloys, and advanced MRO solution providers. Dominant competitive moves involve significant R&D investment in new materials, strategic partnerships for next-generation engine platforms, and targeted capacity expansion.
On the premium-tier vector, General Electric Company (GE) exemplifies a global aerospace conglomerate, leveraging extensive R&D in composite materials for efficiency targets. Safran SA, a French public limited company, occupies a position as a specialist in high-pressure turbine blade technology for next-generation engines. MTU Aero Engines AG, a German stock corporation, anchors the market through its expertise in specialized manufacturing and advanced repair services for high-value components, often collaborating with OEMs.
| Leading Market Players |
|---|
| General Electric Company |
| Safran SA |
| Raytheon Technologies Corporation |
| Albany International Corp. |
| Alcoa Corporation |
| MTU Aero Engines AG |
| Pratt & Whitney |
| GE Aerospace |
| GKN Aerospace |
| Others |
Cost & Logistics Intelligence
Airline operating economics, driven by fuel costs and environmental regulations, compel engine manufacturers to pursue efficiency gains, which in turn influences blade material and design choices, impacting overall component pricing.
Pricing Analysis
Bundled service contracts, shifting risk to engine manufacturers, influence blade pricing significantly. The dominant pricing structure is hybrid, combining long-term performance-based agreements with transactional component sales. Price differentiation stems from the certification level, particularly FAA and EASA approvals, and the material performance of high-pressure turbine blades. Pricing pressure stems from airlines' continuous drive for lower operating costs. Civil aviation buyers exhibit higher price sensitivity compared to military procurement.
Supply Chain Analysis
Reverse logistics for critical engine blades, including advanced repair and coating capabilities, are expanding in MRO hubs like those in the Middle East. Supply concentration for advanced materials and specialized manufacturing resides in the United States, Germany, and France. Raw material dependencies include nickel alloys, titanium alloys, and ceramic matrix composites. Commodity price volatility for strategic metals presents a structural risk. Distribution runs through direct sales to OEMs and specialized MRO service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft engine blade market presents a geographic-arbitrage opportunity, as manufacturing costs and regulatory compliance burdens vary significantly between established aerospace hubs and emerging production centers.
For Market Incumbents: Hedge against the decentralizing impact of additive manufacturing by investing heavily in proprietary material science and advanced repair service capabilities. Incumbents should pursue strategic partnerships for next-generation engine platforms, securing long-term certification advantages against emerging entrants. Specialized talent scarcity represents a threat to innovation velocity. Investing in advanced MRO hubs can extend product lifecycle value.
For New Entrants and Emerging Players: A price-point gap exists between premium, certified components and more accessible alternatives for specific applications, creating entry opportunities. Target low-volume, legacy engine programs or specialized components for alternative propulsion systems. The MRO market expansion in Southeast Asia offers a penetrable segment. Offer certified, 3D-printed metal blades as a service, leveraging rapid prototyping for specialty engine developers.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized component manufacturers possessing unique intellectual property in advanced materials or additive manufacturing processes. Long-term viability hinges on companies that can navigate stringent certification cycles for next-generation engine platforms. Acquisition targets should include niche material specialists focusing on high-temperature alloys. Practitioners should monitor new engine platform certifications for early signals of market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Composite Material R&D | This enhances engine efficiency and reduces weight, meeting EU Green Deal mandates. |
| Expand Additive Manufacturing Capacity | This enables complex blade geometries and faster production cycles for specialized components. |
| Develop Specialized MRO Capabilities | This captures service revenue in high-growth MRO hubs like those in the Middle East. |
| Form Strategic Partnerships with OEMs | This secures long-term supply agreements for next-generation engine platforms. |
| Focus on Alternative Propulsion Component Design | This positions manufacturers for future hybrid-electric and hydrogen-fueled engine architectures. |
Research Approach
Bottom-up civil aviation modeling reconciled against top-down engine OEM tracking forms the analytical core, drawing from primary interviews with engine design engineers, MRO procurement specialists, material scientists, and aerospace regulators. This primary data validates secondary research from FAA and EASA certification databases, aerospace industry association reports, OEM financial filings, and trade publications, ensuring a comprehensive view.
The input-output matrix frames the forecast framework, modeling market dynamics across the analysis window. Segmentation dimensions include blade type, material, application, manufacturing process, and engine platform generation. Compound Annual Growth Rates were derived through a regression analysis of historical trends and projected future demand. Key inputs include new aircraft delivery schedules and airline fleet modernization plans.
Caveats apply where geopolitical instability or shifts in sustainable aviation mandates could materially shift the outlook, even though forecasts reflect documented assumptions. Practitioners should monitor raw material supply chain disruptions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Narrow-Body Turbofan Engine Shop Visit Services Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market
Aircraft Engine Systems and Services
America Aircraft Engines Market
Aircraft Engine Systems and Services
Turbofan Engines Market