
 Advanced Materials for Flying Cars Market | 2026-2036
Advanced Materials for Flying Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Materials for Flying Cars Market Outlook
Urban air mobility operators is bifurcating procurement between established aerospace primes and emerging eVTOL startups. Toray Industries, Inc. dominates carbon fiber prepreg supply for airframe prototypes. Solvay anchors its position through high-performance polymer formulations. Mitsubishi Chemical Carbon Fiber and Composites, Inc. extends its reach into specialized resin systems for vertical takeoff applications.
Advanced materials for flying cars encompass fiber-reinforced composites, titanium aluminide alloys, and ceramic matrix composites engineered to withstand cyclic aerodynamic loading while minimizing mass below 1,500 kg per passenger unit. These materials enable electric vertical takeoff and landing vehicles to achieve the thrust-to-weight ratios required for commercial operation. Composites lead material type demand due to their specific strength advantages in monocoque structures. Nanotechnology within the technology segment shows the fastest trajectory as manufacturers embed sensing capabilities directly into laminate layups. OEMs represent the deepest end user margin pool because they control design authority and qualification timelines.
FAA powered-lift certification standards and EU AI Act autonomous flight provisions are forcing material suppliers to document traceability across every batch. EASA's special condition frameworks for eVTOL airworthiness create parallel compliance obligations in Europe. Stakeholders must monitor how regulator harmonization between FAA and EASA affects qualification testing costs and timeline predictability.
Market Dynamics
FAA powered-lift certification standards are compressing material qualification timelines while eVTOL developers accelerate prototype testing cycles. This regulatory velocity is forcing suppliers to pre-validate composite batches before design freeze.
Growth Catalysts
- Lightweighting Mandates:Urban air mobility operators require thrust-to-weight ratios above 1.2 for commercial viability, driving fiber-reinforced composite adoption in monocoque structures.
- EU AI Act Autonomous Flight Provisions:Embedded sensing requirements in laminate layups are creating demand for nanotechnology-enabled smart materials with real-time structural health monitoring.
- California-Texas eVTOL Clustering:Geographic concentration of airframe developers in these states is generating localized supply chain pull for carbon fiber prepreg and specialized resin systems.
Market Restraints
- Titanium Sponge Volatility:Titanium aluminide alloy production faces input cost pressure from sponge supply concentration in Russia and Kazakhstan.
- Carbon Fiber Oligopoly:Prepreg supply concentrates among three Japanese and European suppliers, creating qualification bottleneck risks for new eVTOL entrants.
- Ceramic Matrix Composite Brittleness:Thermal shock resistance limitations in CMC turbine components restrict their deployment in high-cycle propulsion systems.
Strategic Opportunities
- India PLI Scheme for Aerospace:Production-linked incentives for advanced materials manufacturing could attract composite prepreg localization for Asian eVTOL supply chains.
- Digital Thread Integration:Convergence of blockchain batch traceability with automated fiber placement is enabling real-time qualification documentation for regulators.
- Aftermarket Service Unbundling:Structural health monitoring data monetization creates recurring revenue streams independent of initial airframe sales.
Industry Challenges
- Automated Fiber Placement Technician Scarcity:Aerospace-grade AFP programming expertise concentrates among legacy defense contractors, constraining eVTOL startup hiring pipelines.
- FAA-EASA Harmonization Friction:Divergent special condition frameworks for powered-lift airworthiness force duplicate testing campaigns, extending certification timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Materials for Flying Cars Market |
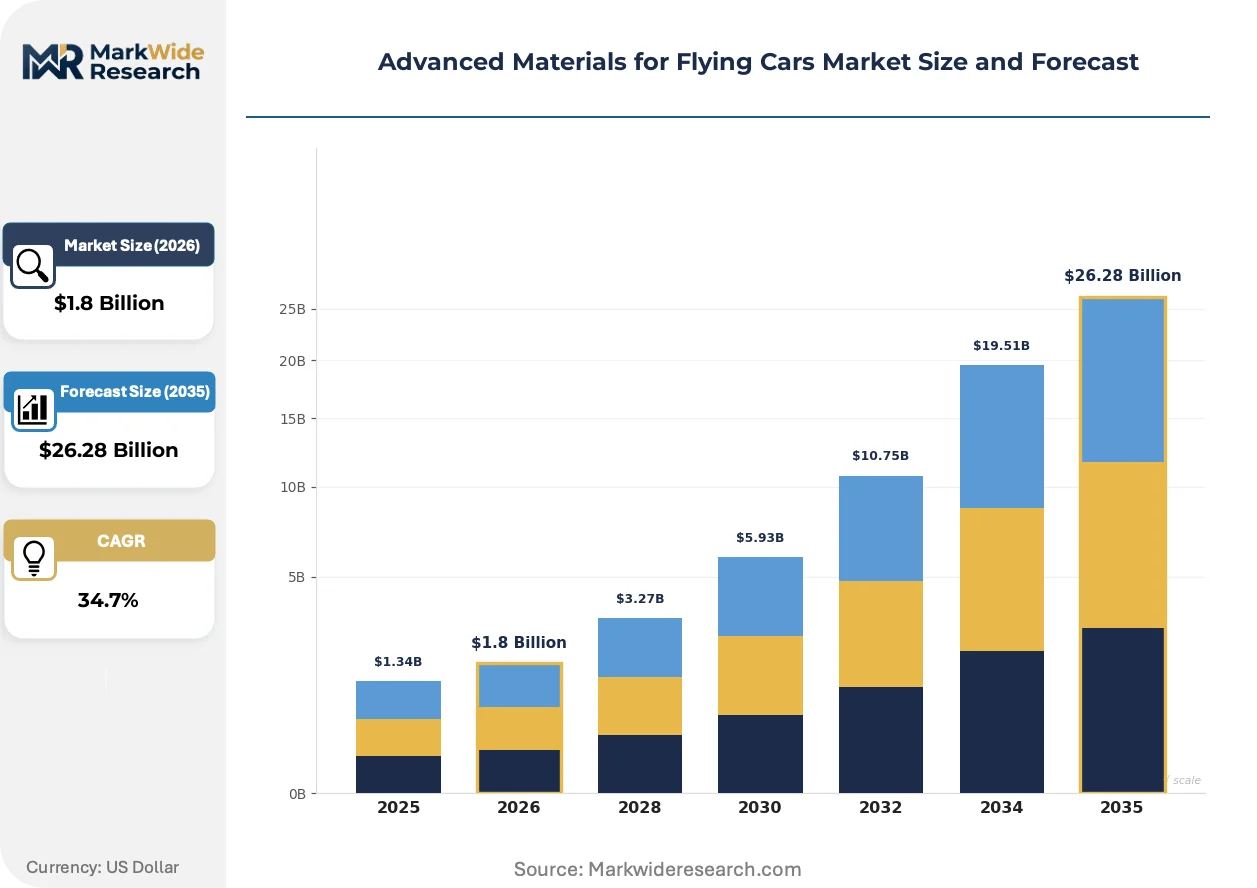
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Composites, Alloys, Polymers, Ceramics Application: Aerospace, Automotive, Infrastructure, Electronics End User: OEMs, Tier-1 Suppliers, Government Agencies, Research Institutions Technology: 3D Printing, Nanotechnology, Coatings, Smart Materials |
| Companies Covered | Kloeckner Metals Corporation, Mitsubishi Chemical Carbon Fiber and Composites, Inc., Tencom Ltd., Owens Corning, Solvay, Toray Industries, Inc., Blue Force Technologies, Saint-Gobain S.A., SGL Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Materials for Flying Cars Market Strategic Shifts
Material innovation in flying cars centers on embedding intelligence into structural components while regulatory frameworks force traceability automation. These shifts are compressing traditional aerospace development cycles.
Thermoplastic composites are displacing thermoset prepregs in primary airframe structures due to their weldability and recyclability advantages. Joby Aviation and Archer Aviation have adopted carbon fiber PEEK layups for their production-intent prototypes. This transition is displacing autoclave-dependent manufacturing, enabling out-of-autoclave processing that cuts cycle times from weeks to days.
EASA's special condition frameworks for eVTOL airworthiness are mandating damage tolerance analysis for composite primary structures that exceeds traditional Part 25 requirements. Material suppliers must now submit statistical process control data across every batch rather than representative sampling. European OEMs are responding by integrating inline inspection systems during automated fiber placement.
Airframe developers are consolidating supplier relationships around qualified material sets rather than qualifying multiple sources per component. This concentration is visible most acutely in California, where three eVTOL manufacturers have standardized on identical carbon fiber prepreg specifications from a single qualified supplier. The practice reduces qualification overhead but amplifies supply concentration risk.
Advanced Materials for Flying Cars Market Segmentation
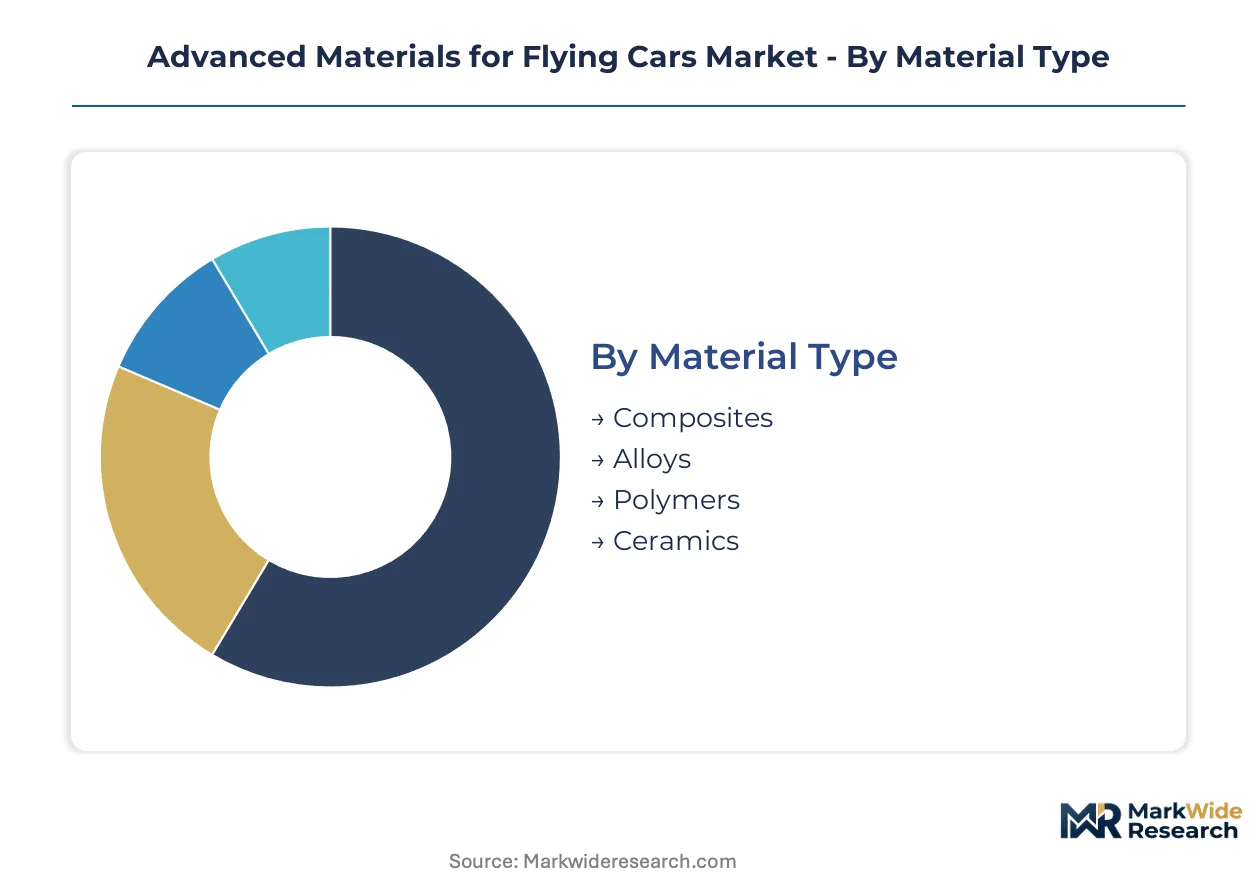
Segmentation in advanced materials for flying cars reveals how supply chains bifurcate between domestic qualification hubs and export-dependent manufacturing nodes. Understanding these splits exposes where procurement leverage concentrates and where regulatory alignment creates competitive moats.
Material Type:
Domestic demand in the United States concentrates on thermoplastic composites and titanium aluminides, while Asian supply chains export carbon fiber prepreg to California and Texas eVTOL clusters. European manufacturers source ceramic matrix composites primarily from domestic qualified suppliers.
- Composites:Fiber-reinforced polymer matrices, predominantly carbon fiber-epoxy and carbon fiber-PEEK layups, deliver specific strength ratios exceeding 300 MPa/(g/cm³). Demand clusters in California eVTOL prototyping facilities where Joby Aviation and Archer Aviation have standardized on identical prepreg specifications from Toray Industries. FAA powered-lift certification timelines compress qualification windows, forcing batch pre-validation before design freeze.
- Alloys:Titanium aluminide intermetallics and high-strength aluminum-lithium formulations withstand cyclic aerodynamic loading above 10,000 flight hours. Procurement concentrates in Texas manufacturing corridors where legacy aerospace infrastructure supports vacuum arc remelting capabilities. Titanium sponge supply concentration in Russia and Kazakhstan creates input cost volatility that threatens margin stability.
- Polymers:High-performance thermoplastics including PEEK, PEKK, and polyphenylene sulfide enable out-of-autoclave processing.
- Ceramics:Ceramic matrix composites provide thermal protection in high-temperature propulsion zones.
Composites command the established base. The steepest expansion runs through alloys as thrust-to-weight requirements intensify.
Application:
Application segmentation tracks how material specifications diverge between flight-critical structures and ground-support systems, with cost tiers separating certified airframe components from non-certified infrastructure elements.
- Aerospace:Primary airframe structures, propulsion housings, and rotor blade spars require damage tolerance analysis exceeding traditional Part 25 requirements. EASA special condition frameworks mandate statistical process control data across every composite batch, driving inline inspection system adoption during automated fiber placement in European OEM facilities.
- Automotive:Ground-based charging infrastructure and transport trailers utilize lower-grade fiber-reinforced polymers without full aerospace qualification overhead. Manufacturing concentrates in Michigan and Ohio automotive corridors where existing compression molding capacity repurposes for eVTOL ground support equipment.
- Infrastructure:Vertiport landing pads and maintenance facilities deploy corrosion-resistant coatings and structural composites.
- Electronics:Avionics enclosures and power distribution systems require EMI-shielding polymers and thermally conductive ceramics.
Aerospace absorbs the premium pricing tier. Infrastructure applications are climbing the fastest as vertiport construction accelerates.
End User:
End user segmentation reflects customer type concentration, where design authority control separates margin-rich OEM relationships from price-sensitive government procurement.
- OEMs:eVTOL developers including Joby Aviation, Archer Aviation, and Lilium retain full design authority and qualification timeline control. These manufacturers consolidate supplier relationships around single qualified material sets per component, amplifying supply concentration risk but reducing qualification overhead. OEMs represent the deepest margin pool through multi-year development contracts.
- Tier-1 Suppliers:Structural fabricators and subsystem integrators purchase qualified materials under OEM-directed specifications. These suppliers face compressed payment terms and limited pricing power as OEMs unbundle aftermarket service revenue streams.
- Government Agencies:NASA and military research programs fund early-stage material development through SBIR contracts.
- Research Institutions:MIT, Stanford, and TU Munich academic laboratories pilot nanotechnology-enabled smart materials.
OEMs dominate procurement volume. Research institutions are expanding most quickly as EU funding programs accelerate.
Technology:
Technology segmentation tracks manufacturing process maturity, with volume scale separating established automated fiber placement from emerging additive methods still seeking qualification pathways.
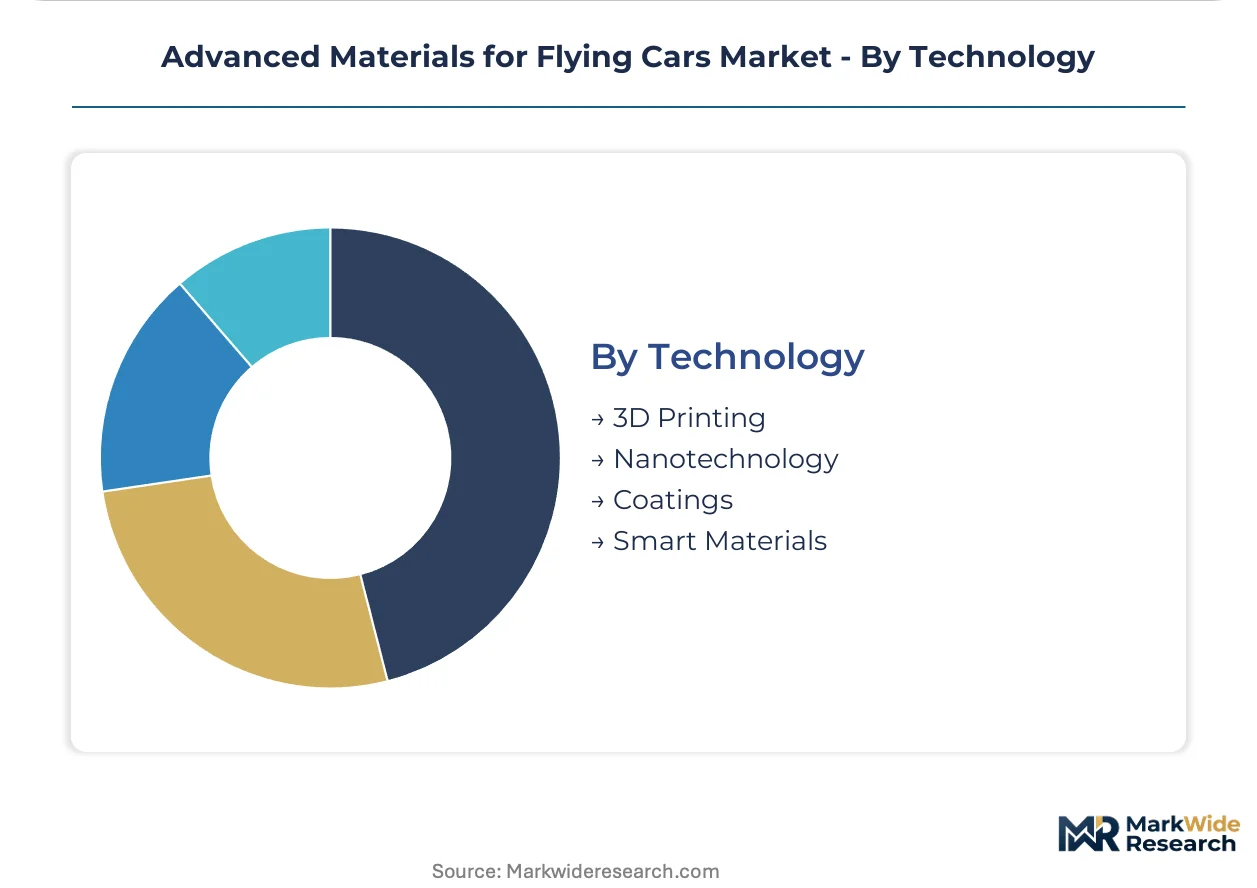
- 3D Printing:Laser powder bed fusion and directed energy deposition of titanium aluminide alloys enable topology-optimized bracket geometries impossible through conventional machining. Adoption concentrates in prototyping phases where design iteration speed outweighs qualification uncertainty; production transition awaits FAA acceptance criteria for powder bed fusion microstructure consistency.
- Nanotechnology:Embedded carbon nanotube sensing networks and graphene-enhanced resin systems provide real-time structural health monitoring capabilities. EU AI Act autonomous flight provisions mandate embedded sensing in laminate layups, creating regulatory-pull demand for smart material qualification.
- Coatings:Environmental barrier coatings and erosion-resistant surface treatments extend component service life.
- Smart Materials:Shape-memory alloys and piezoelectric actuators enable adaptive aerodynamic surfaces.
Coatings anchor current deployment. Nanotechnology shows the steepest expansion trajectory as regulatory sensing mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese carbon fiber prepreg exports flow directly into California and Texas eVTOL prototyping facilities, while European OEMs source ceramic matrix composites from domestic qualified suppliers under EASA special conditions.
United States
FAA powered-lift certification timelines compress material qualification windows, forcing batch pre-validation before design freeze. The Infrastructure Investment and Jobs Act funds vertiport construction across metropolitan corridors. California hosts Joby Aviation and Archer Aviation facilities where identical Toray Industries prepreg specifications have become the de facto standard.
Germany
EASA special condition frameworks mandate statistical process control data across every composite batch rather than representative sampling. EU AI Act autonomous flight provisions create regulatory-pull demand for embedded sensing capabilities. Bavarian OEM facilities integrate inline inspection systems during automated fiber placement to satisfy documentation requirements.
Japan
Carbon fiber oligopoly concentration among domestic suppliers creates qualification bottleneck risks for new eVTOL entrants worldwide. METI industrial policy supports aerospace-grade prepreg capacity expansion. Toray Industries anchors supply relationships with California-Texas eVTOL clusters through multi-year development contracts.
China
Domestic eVTOL developers accelerate prototype testing cycles, driving demand for titanium aluminide alloys and high-performance thermoplastics. MIIT standards for low-altitude economy aircraft reshape material qualification pathways. Yangtze River Delta manufacturing corridors host emerging airframe developers seeking to localize composite supply chains.
India
PLI scheme production-linked incentives for advanced materials manufacturing attract composite prepreg localization interest from Asian eVTOL supply chains. DGFT export promotion frameworks support aerospace-grade carbon fiber capacity expansion. Karnataka and Maharashtra industrial corridors host early-stage conversations between domestic fabricators and international OEMs.
Advanced Materials for Flying Cars Market Competitive Environment
Listed leaders compete with private specialists across material qualification timelines, creating a tiered structure where public companies anchor supply capacity and private entities capture niche certification expertise. Three archetypes dominate: Japanese carbon fiber conglomerates with vertically integrated precursor-to-prepreg operations, European chemical specialists with high-performance polymer formulations, and North American metals distributors with aerospace-grade alloy stocking programs. Competitive moves concentrate on strategic partnerships with eVTOL developers and capacity expansion near California-Texas demand clusters.
Among Japanese suppliers, Toray Industries, Inc. and Mitsubishi Chemical Carbon Fiber and Composites, Inc. occupy positions exemplifying the integrated conglomerate archetype. Solvay represents the European chemical specialist tier. These three entities anchor the supplier base through distinct qualification relationships with OEM development programs.
| Leading Market Players |
|---|
| Kloeckner Metals Corporation |
| Mitsubishi Chemical Carbon Fiber and Composites, Inc. |
| Tencom Ltd. |
| Owens Corning |
| Solvay |
| Toray Industries, Inc. |
| Blue Force Technologies |
| Saint-Gobain S.A. |
| SGL Carbon |
| Others |
Value Chain & Pricing Dynamics
Ninety-day carbon fiber prepreg lead times from Japanese suppliers to California eVTOL facilities concentrate pricing power among Toray Industries and Mitsubishi Chemical, forcing OEMs to absorb volatility through long-term offtake commitments rather than spot-market flexibility.
Pricing Analysis
Thermoset-to-thermoplastic generational pricing gaps separate legacy autoclave-dependent composites from out-of-autoclave PEEK layups commanding premium positioning. Three-tier pricing structure across aerospace-qualified, automotive-grade, and industrial-specification levels reflects FAA certification investment recovery. Cost compression in thermoset tiers intensifies because Joby Aviation and Archer Aviation have standardized procurement around identical qualified specifications. Tier-1 structural fabricators face acute price sensitivity as OEMs unbundle aftermarket revenue, while OEMs themselves absorb premium pricing through multi-year development contract structures.
Supply Chain Analysis
Titanium sponge concentration in Russia and Kazakhstan creates a chokepoint that threatens margin stability across titanium aluminide alloy production. Raw material dependencies draw from Japanese carbon fiber precursor, European high-performance polymer formulations, and North American vacuum arc remelting capacity. Single-source vulnerability runs through Toray Industries' dominance in aerospace-grade prepreg supply to California-Texas eVTOL clusters. Distribution runs through qualified supplier relationships rather than open-market channels, with batch traceability documentation flowing directly from fiber placement facilities to FAA certification dossiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. FAA and EASA qualification timelines embed switching costs that protect incumbent supplier relationships across multi-year OEM development programs.
For Market Incumbents: Consolidate supplier relationships around single qualified material sets per component to reduce qualification overhead, while expanding carbon fiber prepreg capacity in Texas manufacturing corridors to capture localized demand from Archer Aviation and emerging eVTOL developers. Threats from thermoplastic composite displacement by startups require backward integration into PEEK resin formulation to maintain specification control. For New Entrants and Emerging Players: Lead with nanotechnology-enabled smart materials targeting EU AI Act autonomous flight provisions, where embedded sensing mandates create regulatory-pull demand absent entrenched competition. The most penetrable white space sits in structural health monitoring data monetization services, with a go-to-market angle positioning around aftermarket service unbundling independent of initial airframe sales. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FAA-EASA harmonization friction extends certification timelines and embeds qualified supplier moats. Acquisition targets should concentrate on automated fiber placement programming specialists where capability scarcity constrains eVTOL startup scaling. The signal to watch is India PLI scheme implementation attracting composite prepreg localization for Asian supply chain diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Toray Industries' captive PAN precursor supply secures margin control against raw material volatility. |
| Digital Thread Integration | Blockchain batch traceability convergence with automated fiber placement satisfies FAA documentation requirements in real time. |
| Long-term Supply Agreement | Multi-year prepreg offtake contracts between Japanese suppliers and California eVTOL clusters lock in volume commitments. |
| Capacity Expansion in Qualified Geography | Texas manufacturing corridor investments leverage legacy aerospace infrastructure for vacuum arc remelting capabilities. |
| Technology Licensing | PEEK thermoplastic composite formulations licensed to emerging Asian fabricators accelerate out-of-autoclave adoption. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FAA certification databases, EASA special condition frameworks, and customs trade data for carbon fiber prepreg imports. Interviews with eVTOL platform engineers, composite procurement leads at Tier-1 structural fabricators, automated fiber placement technicians, and regulatory affairs specialists at OEMs combined with bottom-up modeling of material consumption per airframe and top-down triangulation against disclosed supplier relationships.
Segmentation dimensions modeled include material type, application tier, end-user category, and manufacturing technology across the projection horizon. CAGRs derive from regression analysis of procurement volume trajectories against FAA powered-lift certification pipeline disclosures. Industry-specific forecast inputs incorporate eVTOL prototype-to-production transition timelines and vertiport construction funding flows from Infrastructure Investment and Jobs Act allocations.
The analysis sits within stated boundaries; outcomes outside sustained FAA-EASA regulatory alignment or titanium sponge supply stability would require recalibration. Forecasts reflect documented assumptions regarding OEM consolidation around single qualified material sets and thermoplastic composite displacement rates. Practitioners should keep alternative scenarios live as India PLI scheme implementation and China MIIT low-altitude economy standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Stealth Coating Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market
Aerospace and Aircraft Materials
Aerographite Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Aircraft Insulation Materials Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market