
 Angle of Attack Sensor Market | 2026-2036
Angle of Attack Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Angle of Attack Sensor Market Analysis
Sensor-as-a-service maintenance contracts is recalibrating how angle of attack systems generate recurring revenue for suppliers. Honeywell International Inc leverages its integrated avionics platform to bundle predictive maintenance with hardware sales. Collins Aerospace anchors its position through proprietary calibration protocols that lock airlines into long-term service agreements. Garmin Ltd competes in the general aviation retrofit segment with simplified installation packages.
An angle of attack sensor measures the angle between an aircraft's wing chord line and the relative wind vector, typically employing vane, probe, or flush-mounted pressure differential designs with operational tolerances below 0.1 degrees to trigger stall warnings. Electromechanical vane sensors dominate commercial installations due to proven reliability in icing conditions, while optical and radar variants are gaining traction in UAV applications where miniaturization and electromagnetic immunity matter. Digital technology architectures now command premium positioning as airlines prioritize integrated flight-control data buses over standalone analog outputs.
FAA airworthiness directives and EASA certification standards mandate redundant angle of attack inputs for transport-category aircraft, forcing fleet-wide upgrades and new-build integration. The EU AI Act and emerging autonomous-flight frameworks in the United States are extending sensor requirements into unmanned and urban air mobility platforms. Stakeholders must monitor how software-defined airworthiness certification reshapes hardware qualification pathways.
Market Dynamics
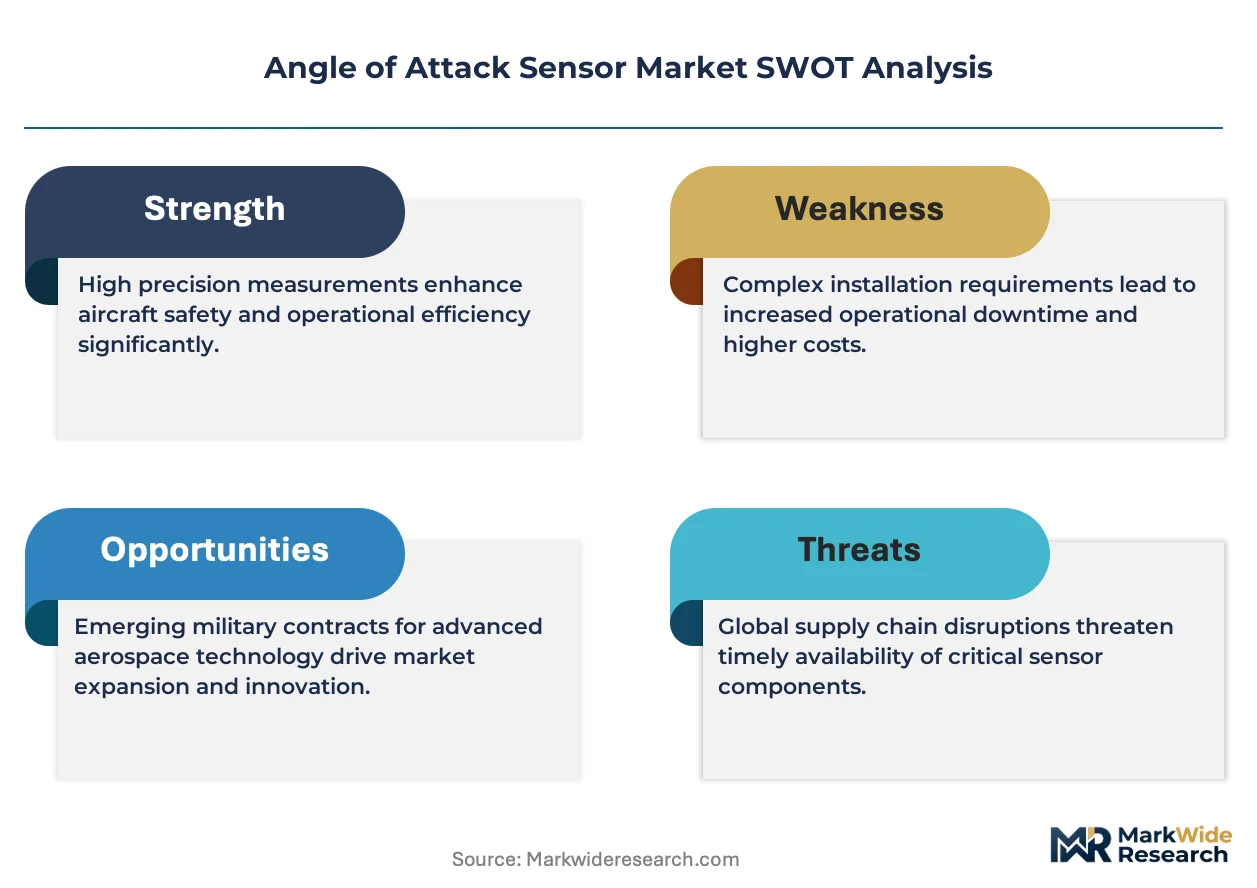
Airworthiness mandates from FAA and EASA are forcing fleet-wide sensor retrofits and new-build integration, compressing replacement cycles and concentrating procurement decisions among major carriers and OEMs. This regulatory pressure is the dominant structural force reshaping supplier relationships and technology roadmaps.
Growth Catalysts
- FAA Airworthiness Directives:Mandated redundant angle of attack inputs for transport-category aircraft are compelling airlines to accelerate hardware upgrades across aging fleets.
- Urban Air Mobility:Emerging autonomous-flight frameworks in the United States are extending sensor requirements into unmanned platforms and electric vertical takeoff aircraft.
- Electromechanical Vane Sensors:Proven reliability in icing conditions continues to drive specification preferences among commercial aviation maintenance planners.
Market Restraints
- Calibration Protocol Concentration:Proprietary service agreements from dominant suppliers lock airlines into captive maintenance relationships, limiting vendor switching.
- Platinum-Based Heating Elements:Input cost volatility for thermal anti-icing components squeezes margin predictability for electromechanical sensor manufacturers.
- Optical Sensor Substitution:UAV platforms increasingly specify radar and optical variants where electromagnetic immunity outweighs proven commercial aviation reliability standards.
Strategic Opportunities
- India Fleet Expansion:Low-cost carriers in the subcontinent are modernizing narrow-body fleets, creating retrofit demand for digital-architecture angle of attack systems.
- Sensor-as-a-Service Contracts:Predictive maintenance bundling is displacing transactional hardware sales with recurring revenue streams among integrated avionics suppliers.
- EU AI Act Convergence:Software-defined airworthiness certification pathways are opening qualification routes for algorithm-enhanced sensor diagnostics in European markets.
Industry Challenges
- Flight Control Integration Complexity:Airlines face extended downtime and certification documentation burdens when retrofitting digital sensors onto legacy analog flight data architectures.
- Calibration Technician Scarcity:Specialized avionics maintenance facilities report bottlenecks in qualified personnel capable of executing proprietary alignment protocols within required tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angle of Attack Sensor Market |
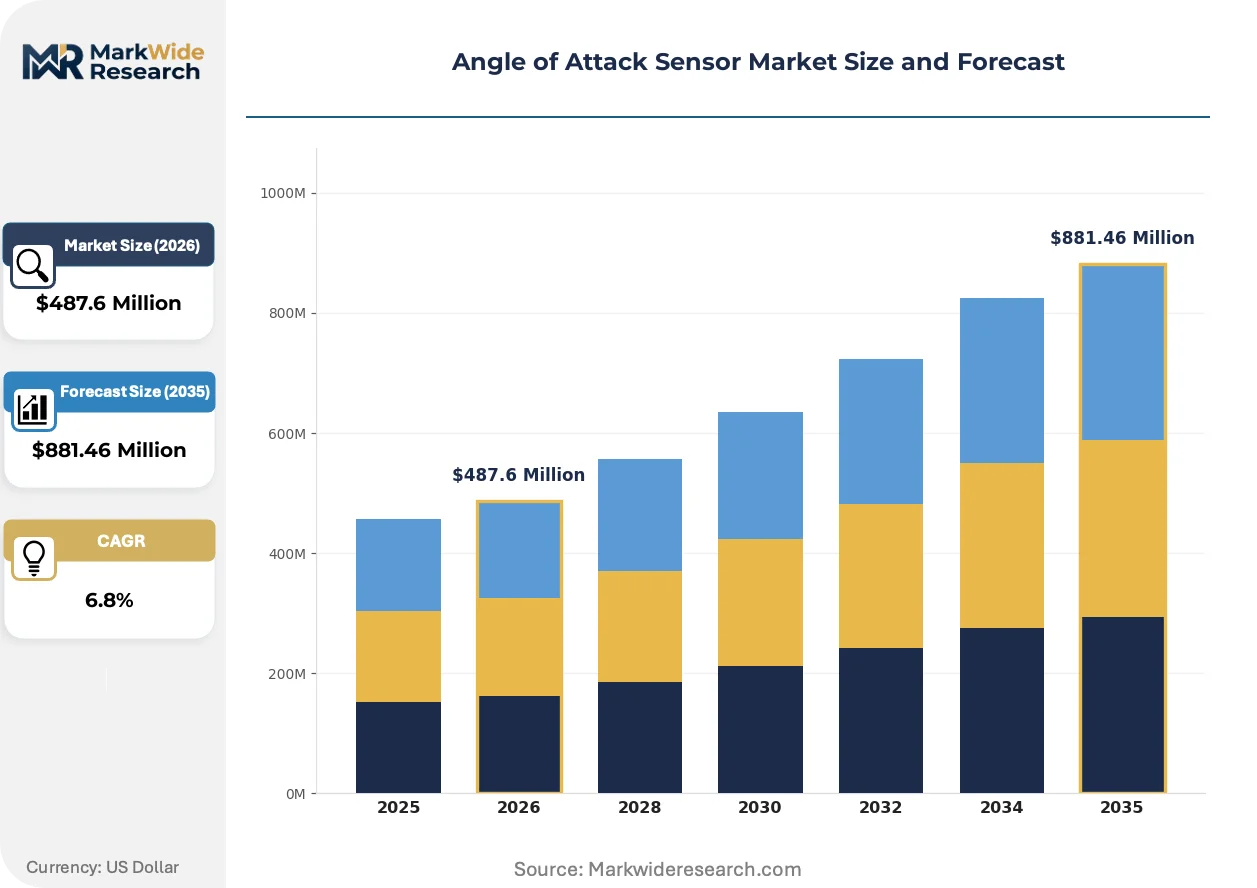
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electromechanical, Optical, Radar, Ultrasonic Application: Commercial Aviation, Military Aviation, UAVs, Spacecraft Technology: Digital, Analog, Hybrid, Wireless End User: Airlines, Defense Contractors, Aerospace Manufacturers, Research Institutions |
| Companies Covered | Honeywell International Inc, Collins Aerospace, Thales Group, AMETEK Inc, Garmin Ltd, TransDigm Group Inc, Curtiss-Wright, TE Connectivity, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angle of Attack Sensor Market Emerging Trajectories
Digital sensor architectures are displacing analog outputs as airlines prioritize integrated flight-control data buses, while regulatory frameworks accelerate hardware qualification for autonomous platforms. This technological and policy convergence is compressing product lifecycles and reshaping competitive positioning.
Flush-mounted pressure differential designs are expanding into commercial aviation applications previously dominated by vane sensors. Regional carriers and cargo operators are adopting these configurations to reduce icing vulnerability and simplify maintenance access. The technology is expanding into narrow-body retrofit programs where operational tolerance requirements below 0.1 degrees can be met without electromechanical complexity.
EASA certification standards for stall-warning redundancy are tightening hardware specifications across European-registered fleets. Airlines operating under these mandates must demonstrate independent sensor channels with dissimilar failure modes, forcing architecture redesigns. Transport-category aircraft in Germany, France, and the Netherlands are responding with accelerated procurement of dual-string digital systems.
Maintenance contract unbundling is fragmenting traditional supplier relationships in the general aviation segment. Owner-operators and flight schools are purchasing simplified installation packages through direct channels rather than OEM-authorized service centers. This pattern is most visible in the United States, where Garmin and aftermarket distributors are capturing retrofit volume previously controlled by factory-authorized dealers.
Angle of Attack Sensor Market Segmentation
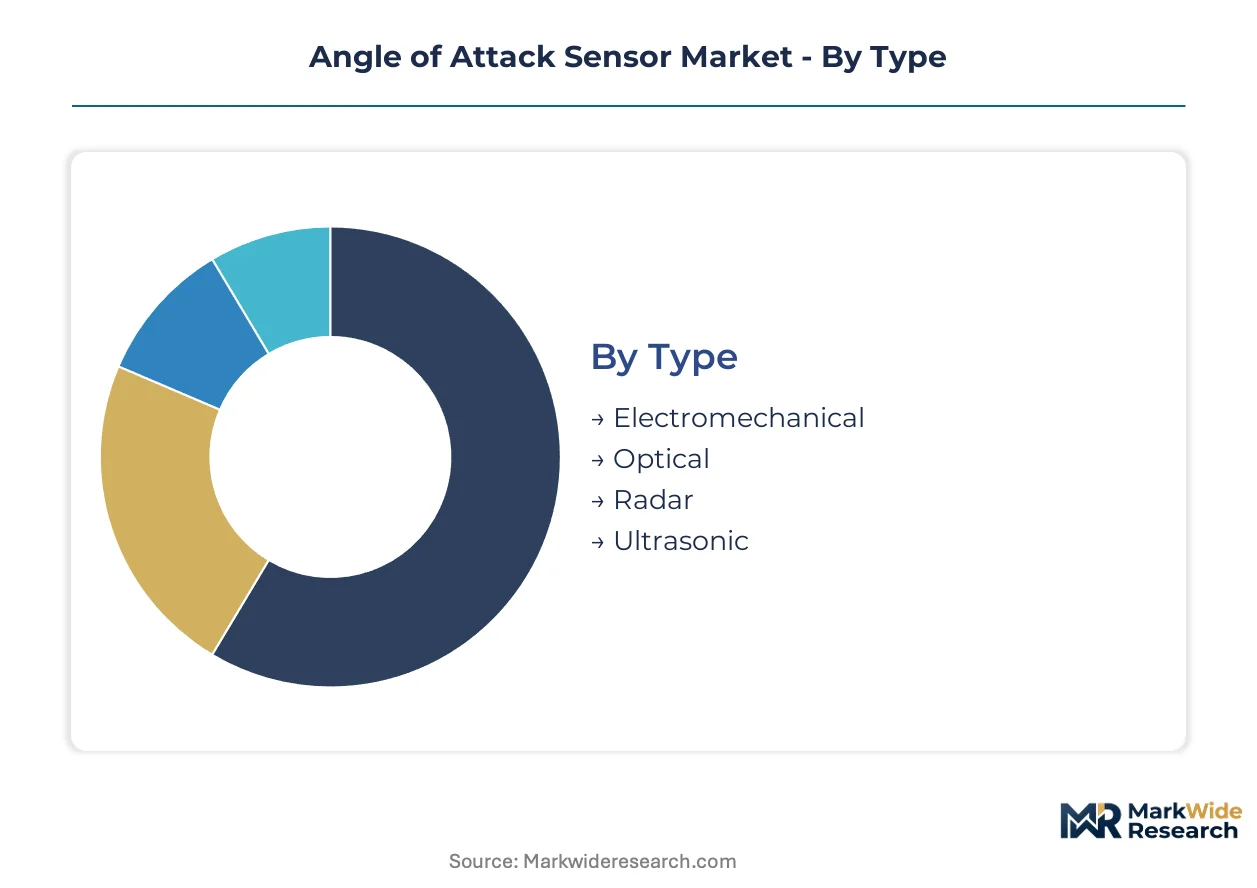
Angle of attack sensor procurement follows sharply divergent certification pathways across aviation sectors. FAA and EASA mandates create tiered hardware specifications that reshape supplier priorities and technology roadmaps differently for each segment cluster.
Type:
Certification burden varies dramatically by sensing mechanism, with electromechanical designs carrying decades of airworthiness precedent while optical and radar variants navigate emerging autonomous-flight frameworks.
- Electromechanical:Vane-based mechanisms with platinum heating elements deliver operational tolerances below 0.1 degrees in icing conditions. Commercial aviation fleets in the United States specify these for transport-category aircraft under FAA airworthiness directives mandating redundant stall-warning inputs.
- Optical:Solid-state designs using laser interferometry eliminate moving parts and reduce maintenance intervals. UAV platforms in urban air mobility trials favor these for electromagnetic immunity and miniaturization advantages where traditional reliability standards are less binding.
- Radar:Radio-frequency sensing penetrates adverse weather without probe exposure. Defense contractors specify these for military aviation applications requiring all-weather operational envelopes.
- Ultrasonic:Acoustic time-of-flight measurement offers corrosion resistance in maritime patrol environments. Research institutions deploy these for experimental flight-test programs.
Leading the category by volume: Electromechanical. Expanding most quickly: Optical.
Application:
End-use environment dictates sensor architecture tradeoffs between precision, durability, and integration complexity.
- Commercial Aviation:Narrow-body and wide-body fleets require dual-string digital systems with dissimilar failure modes under EASA stall-warning redundancy standards. Airlines operating in Germany, France, and the Netherlands are accelerating procurement to meet tightened specifications.
- Military Aviation:Fighter and transport platforms demand hardened electronics against electromagnetic pulse threats. Defense contractors in the United States integrate these with classified flight-control architectures.
- UAVs:Miniaturized optical and radar variants serve autonomous platforms where weight constraints outweigh proven commercial reliability standards.
- Spacecraft:Vacuum-rated electromechanical designs with extended temperature ranges support re-entry vehicle control surfaces.
Commercial Aviation dominates procurement value. UAVs climb the fastest as autonomous-flight frameworks extend sensor requirements.
Technology:
Signal processing architecture determines integration cost and airworthiness qualification pathway.
- Digital:Integrated flight-control data buses command premium positioning as airlines prioritize ARINC 429 and MIL-STD-1553 compatibility over standalone outputs. Retrofit programs face extended downtime when replacing legacy analog architectures.
- Analog:Voltage-output designs persist in general aviation fleets where certification documentation burdens outweigh performance gains. Owner-operators in the United States purchase simplified installation packages through direct distribution channels.
- Hybrid:Dual-output configurations bridge analog legacy and digital upgrade paths. Regional carriers adopt these for phased fleet modernization.
- Wireless:RF-linked sensors reduce wiring weight in experimental and unmanned platforms. Research institutions pilot these for swarm-vehicle coordination.
Digital systems lead installed base growth. Wireless gains share fastest in UAV and urban air mobility segments.
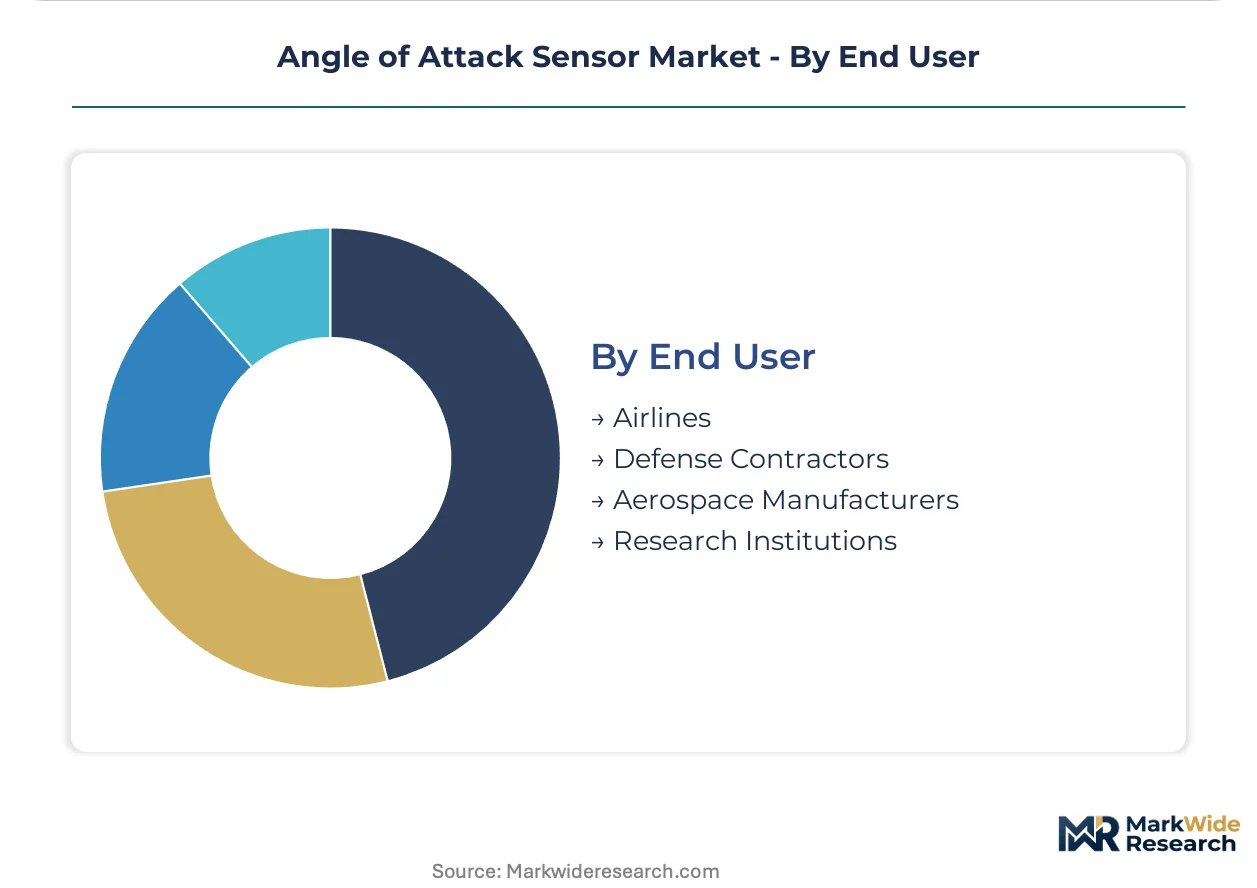
End User:
Procurement authority concentration shapes contract structure and service bundling strategies.
- Airlines:Major carriers in the United States drive replacement cycles through fleet-wide retrofit mandates. Predictive maintenance bundling displaces transactional hardware sales with recurring revenue streams.
- Defense Contractors:Long-term sustainment contracts with classified performance specifications lock suppliers into captive calibration relationships.
- Aerospace Manufacturers:Boeing and Airbus tier-1 suppliers integrate sensors at airframe assembly, embedding hardware decisions into new-build procurement.
- Research Institutions:Experimental programs purchase simplified installation packages with minimal service obligations.
Airlines lead category volume. Aerospace Manufacturers represent the steepest expansion trajectory as new-build rates accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the United States and Germany, while fleet expansion in India and Southeast Asia drives consumption growth. Regulatory divergence between FAA and EASA certification timelines shapes procurement patterns across these markets.
United States
Boeing's production ramp and major carrier retrofit programs concentrate sensor demand in Washington State and the Midwest. FAA airworthiness directives mandate redundant angle of attack inputs, compressing replacement cycles for narrow-body fleets. Dallas-Fort Worth and Atlanta maintenance hubs report extended backlogs for digital-architecture installations.
Germany
Lufthansa Group's fleet modernization and Airbus supplier integration anchor procurement volumes in Bavaria and Hamburg. EASA stall-warning redundancy standards require dissimilar failure-mode architectures, forcing dual-string system adoption. Munich's avionics cluster specializes in calibration protocols for European-registered transport aircraft.
India
IndiGo and SpiceJet narrow-body expansions generate retrofit demand exceeding domestic supplier capacity. The country's Directorate General of Civil Aviation aligns certification requirements with FAA standards, accelerating hardware imports. Bangalore's aerospace parks host maintenance facilities for sensor calibration and flight-control integration.
France
Airbus final assembly lines in Toulouse embed sensor procurement into new-build supply chains. EASA's tightened hardware specifications for stall-warning systems mandate independent sensor channels. The Occitanie region's aerostructure suppliers coordinate tier-1 integration for European export markets.
Japan
ANA and JAL fleet renewal programs prioritize electromechanical vane sensors for icing-condition reliability. METI's aerospace industrial policy supports domestic sensor calibration capabilities. Nagoya's Chubu region maintains specialized facilities for flight-control system certification documentation.
Angle of Attack Sensor Market Vendor Landscape
Top-tier vendors anchor integrated avionics platforms, while specialized sensor fabricators compete on certification speed and retrofit packaging. The market structures around three tiers: full-stack avionics houses, dedicated sensor OEMs, and aftermarket distributors. Two strategic archetypes dominate—suppliers bundling predictive maintenance contracts and those locking airlines through proprietary calibration protocols. Consolidation pressure intensifies as tier-1 aerospace manufacturers integrate sensor decisions into airframe assembly contracts.
Within the integrated systems tier, Honeywell International Inc and Collins Aerospace exemplify platform-centric positioning that captures recurring service revenue. Garmin Ltd occupies a distinct position in simplified installation packages for general aviation retrofit channels. These three companies represent the spectrum from enterprise-grade bundled offerings to direct-distribution accessibility.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Collins Aerospace |
| Thales Group |
| AMETEK Inc |
| Garmin Ltd |
| TransDigm Group Inc |
| Curtiss-Wright |
| TE Connectivity |
| L3Harris Technologies |
| Others |
Supply Flow & Price Mechanics
Platinum price volatility on the London Metal Exchange cascades through electromechanical vane sensor manufacturing, compressing margins for heating-element suppliers and forcing tiered pricing stratification across certification-grade hardware tiers.
Pricing Analysis
Margin tightening in standard-grade hardware reflects platinum input cost escalation and captive calibration protocol premiums. Three-tier pricing structure across FAA-certified, EASA-certified, and general aviation levels segments buyer access. Airlines with fleet-wide retrofit mandates show lowest price sensitivity, while owner-operators in direct-distribution channels drive hardest negotiation. Cost-down pressure on analog-to-digital upgrade packages accelerates as regional carriers phase legacy architectures.
Supply Chain Analysis
Sensor refurbishment and calibration return flows concentrate service revenue in Germany and the United States, where proprietary alignment protocols lock aftermarket relationships. Manufacturing draws from precision machining clusters in Japan, platinum heating-element suppliers in South Africa, and avionics integration facilities in France. Single-source vulnerability for platinum-group metals exposes margin predictability to commodity swings. Distribution runs through OEM-authorized service centers and tier-1 aerospace manufacturer assembly contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration technician scarcity props pricing power for incumbent service providers, constraining capacity expansion and sustaining premium capture for proprietary protocol holders.
For Market Incumbents: Hedge platinum price exposure through long-term metal offtake agreements and backward integration into heating-element fabrication. Lock airline relationships via predictive maintenance bundling before sensor-as-a-service competitors scale. Optical sensor substitution in UAV segments threatens electromechanical volume; accelerate digital-architecture certification investment. For New Entrants and Emerging Players: Enter via simplified installation packages for general aviation retrofit channels, where maintenance contract unbundling fragments incumbent control. India's narrow-body fleet expansion offers most penetrable geography for digital-architecture angle of attack systems lacking domestic supplier capacity. Target direct distribution partnerships with aftermarket avionics distributors in the United States. For Investors and Strategic Acquirers: Distressed-cycle entries favor calibration-capable mid-cap specialists in Germany and Japan, where technician scarcity sustains service-margin premiums. Long-term viability hinges on software-defined airworthiness qualification pathways opening algorithm-enhanced diagnostic routes. Monitor EU AI Act implementation timelines and FAA autonomous-flight framework publication as inflection signals for sensor requirement expansion into urban air mobility platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Protocol Acquisition | Captures recurring service revenue from airlines locked into proprietary alignment requirements. |
| Digital Architecture Certification | Unlocks EASA dual-string redundancy mandates and FAA new-build integration contracts. |
| Platinum Supply Hedging | Stabilizes margin predictability for electromechanical vane sensor heating elements. |
| Urban Air Mobility Partnership | Positions optical and radar variants for emerging autonomous-flight sensor requirements. |
| India Distribution Buildout | Addresses retrofit demand exceeding domestic supplier capacity in narrow-body fleet expansion. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with avionics maintenance directors, airline procurement managers, tier-1 aerospace supplier executives, and FAA certification engineers. FAA airworthiness directives, EASA certification standards, and DGCA alignment protocols provided regulatory boundary conditions. Bottom-up sensor shipment analysis triangulated against top-down fleet retrofit spending estimates from airline capital expenditure disclosures.
Granularity extended to sensing mechanism, application sector, signal architecture, and end-user procurement authority across the projection horizon. CAGRs derived from fitted trend analysis against fleet expansion schedules and regulatory mandate compliance timelines. Modeled inputs included Boeing and Airbus delivery forecasts, platinum price trajectory assumptions, and technician training pipeline capacity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated autonomous-flight framework adoption or platinum supply disruption scenarios. Practitioners should monitor FAA urban air mobility policy releases and EU AI Act software-defined certification pathway finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Narrow-Body Turbofan Engine Shop Visit Services Market
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Gas Turbine Service Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Aero Engine Coatings Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market