
 Global Naval Ship Propeller Market | 2026-2036
Global Naval Ship Propeller Market Size, Share, and Industry Trends Forecast 2026-2036
Global Naval Ship Propeller Market Outlook
Buyer concentration among defense organizations is hardening as NATO members and Indo-Pacific navies consolidate procurement through fewer prime contractors. Wärtsilä Corporation leverages its integrated propulsion systems to anchor long-term service contracts with European navies. Mecklenburger Metallguss GmbH specializes in large-diameter nickel-aluminum-bronze castings for surface combatants. Hyundai Heavy Industries Co., Ltd. dominates naval construction in South Korea, securing captive demand for in-house propeller production.
Naval ship propellers are hydrodynamic thrust devices, typically cast from nickel-aluminum-bronze or high-strength stainless steel alloys, machined to precise pitch tolerances within fractions of a degree to optimize cavitation performance and radiated noise signatures under varying operational loads. Controllable pitch propellers command premium positioning among defense end users due to their maneuverability advantages in littoral operations, while fixed pitch variants sustain volume demand across auxiliary and patrol vessel classes. Composite materials represent the fastest-growing material category as navies prioritize acoustic reduction and corrosion resistance in extended deployment cycles.
ISO 484/2 thrust measurement standards, NATO STANAG acoustic requirements, and national defense procurement codes collectively shape propeller design specifications and vendor qualification pathways. The US Navy's MIL-S-901D shock testing protocols and the EU's REACH substance restrictions on copper-based antifouling coatings are redirecting material selection toward compliant alloy formulations. Stakeholders must monitor evolving submarine detection thresholds and alternative energy propulsion hybrids as these forces redefine performance benchmarks and supplier technical requirements.
Market Dynamics
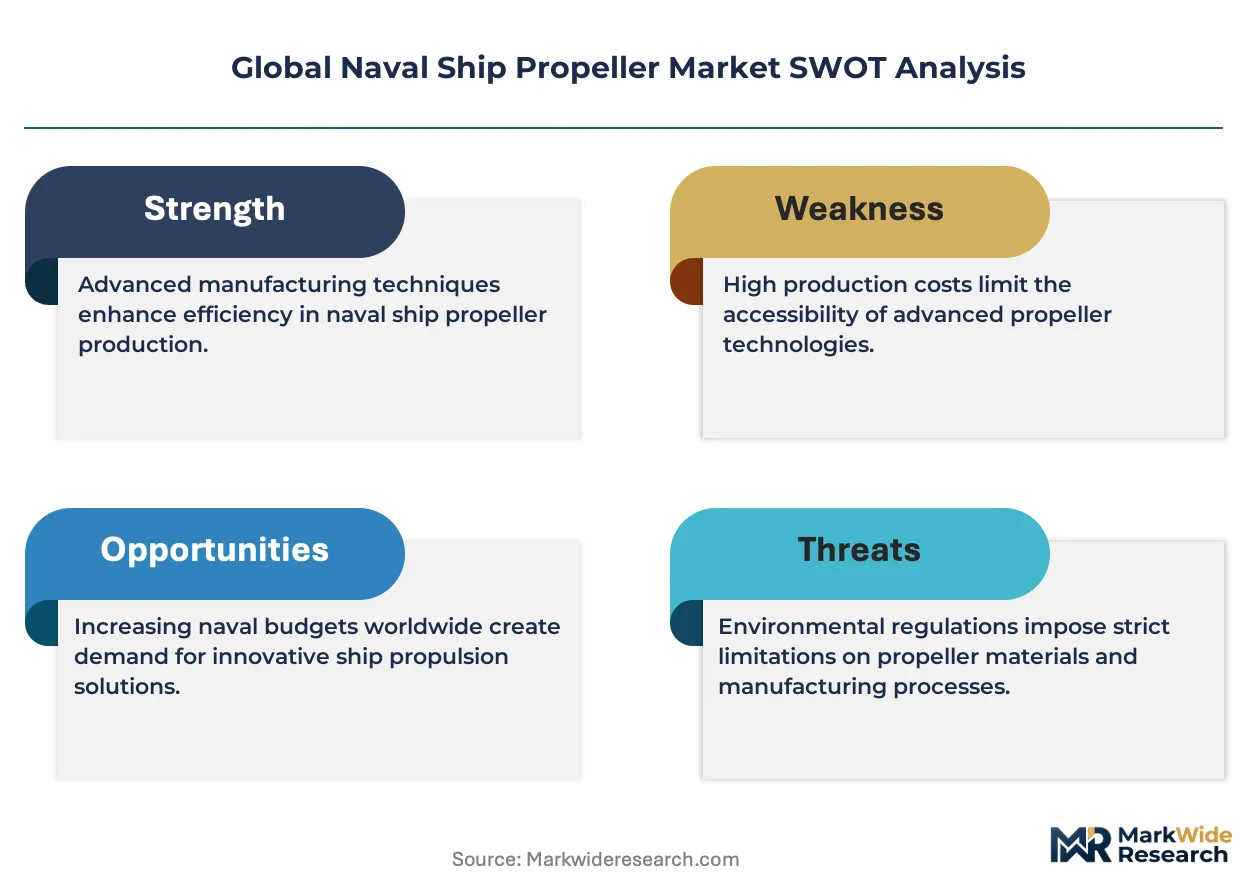
Naval ship propeller procurement is tightening around acoustic signature compliance as NATO STANAG standards and national stealth mandates harden performance thresholds for surface combatants and submarines alike.
Growth Catalysts
- NATO STANAG acoustic requirements:Alliance navies in Norway, Germany, and Poland are mandating lower radiated noise signatures, forcing fleet-wide propeller upgrades and new-build specifications that favor precision-machined controllable pitch systems.
- Composite material innovations:Carbon-fiber reinforced polymer blades are displacing traditional nickel-aluminum-bronze in littoral combat vessels, delivering corrosion immunity and weight reductions that extend operational range.
- Asia-Pacific fleet modernization:Defense procurement agencies in South Korea, Japan, and Australia are accelerating destroyer and frigate construction programs, generating sustained demand for large-diameter propeller castings.
Market Restraints
- Nickel and copper alloy price volatility:Nickel-aluminum-bronze input costs fluctuate with mining output from Indonesia and the Philippines, compressing foundry margins and destabilizing long-term contract pricing.
- Foundry capacity concentration:Large-diameter propeller casting capabilities cluster in Mecklenburg-Vorpommern, South Korea's Ulsan corridor, and select Japanese shipbuilding zones, creating single-source vulnerability for critical diameters above six meters.
- REACH substance restrictions:ECHA regulations on copper-based antifouling coatings are forcing alloy reformulation R&D, extending qualification timelines and raising non-recurring engineering costs for European suppliers.
Strategic Opportunities
- Unmanned surface vessel propulsion:Naval drone programs in the United States and United Kingdom require compact, high-efficiency propellers with minimal maintenance profiles, opening a design space distinct from manned combatant specifications.
- Hybrid-electric propulsion integration:Convergence of battery storage systems with conventional shaft lines demands propellers optimized for variable-speed operation across diesel, electric, and combined modes.
- EU Green Deal shipyard incentives:European defense procurement frameworks are attaching sustainability criteria to vessel construction contracts, favoring suppliers with verified low-carbon casting processes and circular material recovery.
Industry Challenges
- Five-axis CNC machining expertise:Precision pitch tolerance grinding to fractions of a degree requires specialized operator training that outpaces vocational pipeline output in Germany, Japan, and South Korea.
- MIL-S-901D shock certification timelines:US Navy combatant propellers must survive high-impact testing protocols that extend qualification cycles by 18-24 months, delaying revenue recognition and tying up engineering resources.
- Legacy shaft alignment integration:New propeller designs must interface with existing stern tube configurations in mid-life vessel upgrades, constraining hydrodynamic optimization and requiring costly custom adapter fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Naval Ship Propeller Market |
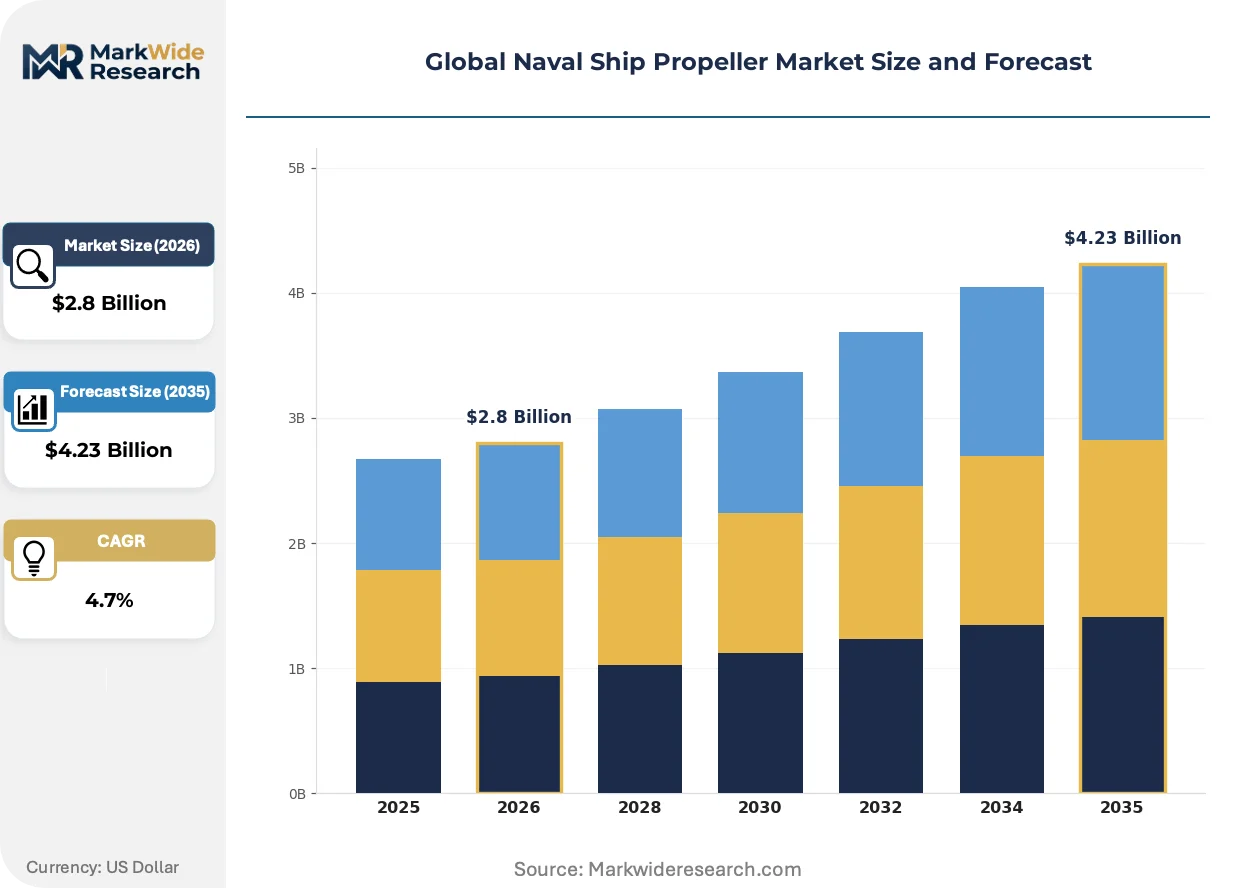
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fixed Pitch, Controllable Pitch, Shrouded, Ducted Material: Bronze, Aluminum, Stainless Steel, Composite Application: Naval Vessels, Cargo Ships, Passenger Ships, Research Vessels End User: Defense Organizations, Shipping Companies, Research Institutions, Government Agencies |
| Companies Covered | Hyundai Heavy Industries Co., Ltd., Mecklenburger Metallguss GmbH, Kongsberg Gruppen ASA, Caterpillar Inc., VEEM Ltd., MAN Energy Solutions SE, Kawasaki Heavy Industries, Ltd., ANDRITZ AG, Wärtsilä Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Naval Ship Propeller Market Strategic Shifts
Material science breakthroughs and procurement model restructuring are compressing traditional design-to-delivery cycles while elevating acoustic performance to a primary competitive differentiator in naval propulsion.
Composite blade architectures are rewriting the trade-off between structural strength and radiated noise. Carbon-fiber reinforced polymer laminates with tailored stiffness profiles now permit thinner section designs that suppress cavitation inception across broader operating envelopes. Royal Navy Type 26 frigates and US Navy Constellation-class variants are specifying hybrid metal-composite hubs, compressing the viable supplier base to firms with autoclave curing and non-destructive testing capabilities.
REACH substance restrictions on copper biocides are redirecting antifouling strategies toward ultrasonic systems and silicone-based coatings. ECHA regulatory pressure is forcing foundries to document alloy trace element content and eliminate legacy lead-bearing solders from assembly operations. German and Norwegian naval procurement offices are now requiring Environmental Product Declarations as technical bid prerequisites, filtering out suppliers without ISO 14001-certified production lines.
Buyer concentration among defense ministries is consolidating specification authority within fewer prime contractors. Long-term availability contracts covering 25-year service life are displacing transactional spare-part purchasing, locking propeller suppliers into integrated logistics support commitments. South Korea's Defense Acquisition Program Administration and Australia's Department of Defence are pioneering outcome-based maintenance frameworks where propeller vendors guarantee mean-time-between-failure rates rather than unit delivery.
Global Naval Ship Propeller Market Segmentation
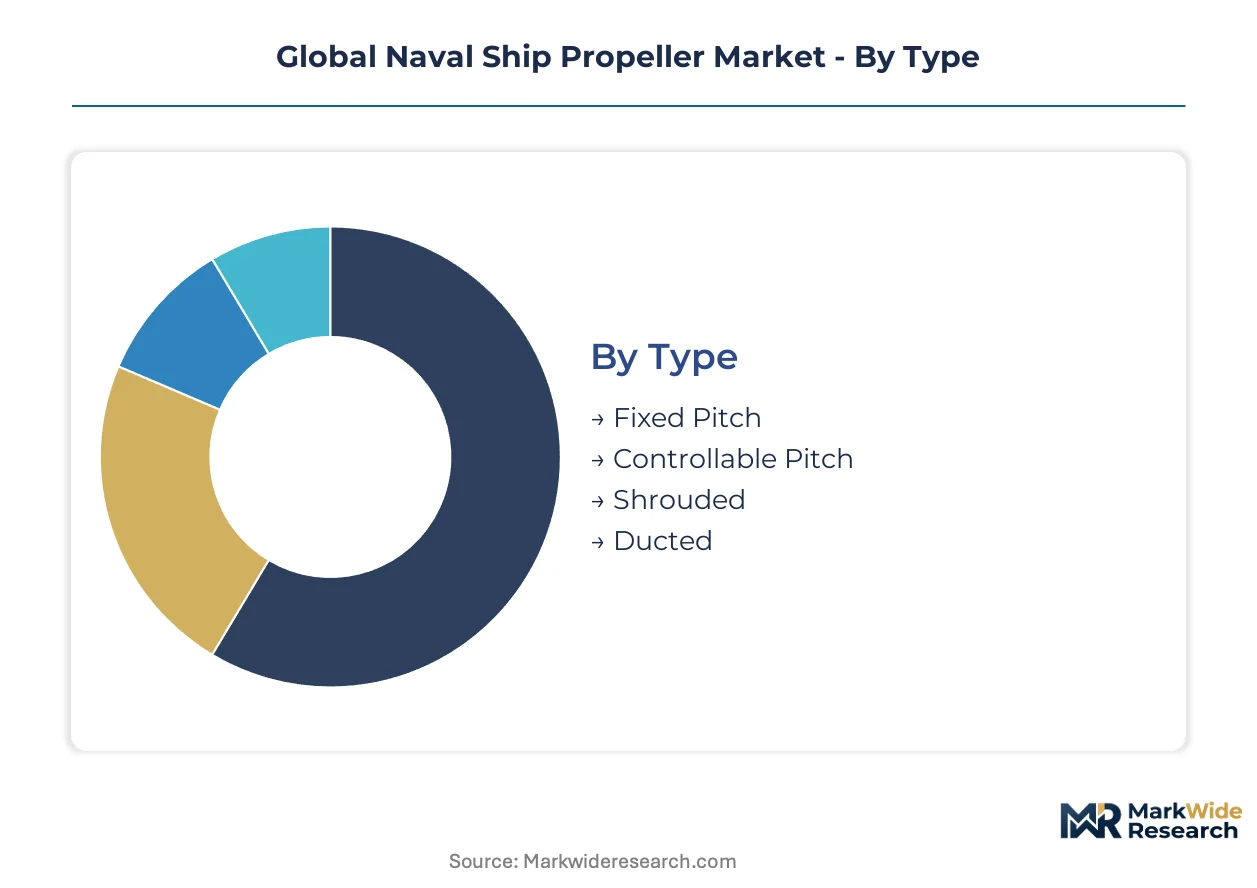
Propeller procurement patterns diverge sharply across vessel classes and operational profiles. Defense buyers prioritize acoustic stealth and shock survivability, while commercial operators emphasize fuel efficiency and maintenance intervals.
Type:
Defense procurement officers select propeller architectures based on maneuverability requirements and signature constraints rather than unit cost alone.
- Controllable Pitch:Blade angle modulation enables rapid thrust reversal and precise station-keeping in littoral zones. NATO navies in Norway and Germany specify these systems for frigate and destroyer programs to meet STANAG acoustic thresholds.
- Fixed Pitch:Single-piece castings deliver lower acquisition cost and mechanical simplicity. Demand concentrates in South Korea's patrol vessel and auxiliary fleet construction, where procurement favors proven designs with minimal moving parts.
- Shrouded:Annular duct designs suppress tip vortex cavitation for submarine and mine countermeasure applications.
- Ducted:Accelerating nozzles improve bollard pull efficiency for tugs and amphibious assault craft.
Volume sits with Fixed Pitch; growth tilts toward Controllable Pitch.
Material:
Foundry capabilities and alloy supply chains determine which material classes dominate regional procurement.
- Composite:Carbon-fiber reinforced polymer laminates deliver weight reductions and corrosion immunity for extended deployment cycles. Royal Navy Type 26 frigates and US Navy Constellation-class vessels specify hybrid metal-composite hubs, expanding the fastest.
- Bronze:Nickel-aluminum-bronze castings remain the baseline for large-diameter surface combatant propellers. Mecklenburg-Vorpommern foundries and South Korea's Ulsan corridor anchor global supply.
- Stainless Steel:High-strength martensitic grades serve ice-class requirements and high-speed craft.
- Aluminum:Lower-density alloys suit small-craft and unmanned surface vessel applications.
Procurement volume clusters on Bronze; Composite captures the steepest expansion trajectory.
Application:
Vessel operational profiles dictate propeller diameter, blade count, and cavitation margin specifications.
- Naval Vessels:Surface combatants and submarines demand precision-machined blades with radiated noise signatures below detection thresholds. Australia's destroyer construction and Japan's frigate programs sustain demand for large-diameter castings.
- Cargo Ships:Merchant fleets prioritize propulsive efficiency over acoustic stealth, favoring fixed-pitch designs with optimized wake-adapted blade geometries.
- Passenger Ships:Cruise and ferry operators specify vibration-dampened configurations for passenger comfort.
- Research Vessels:Scientific missions require low-noise propulsion to avoid disturbing marine mammal surveys and acoustic sensor deployments.
Cargo Ships absorb the highest unit volume; Naval Vessels command premium pricing tiers.
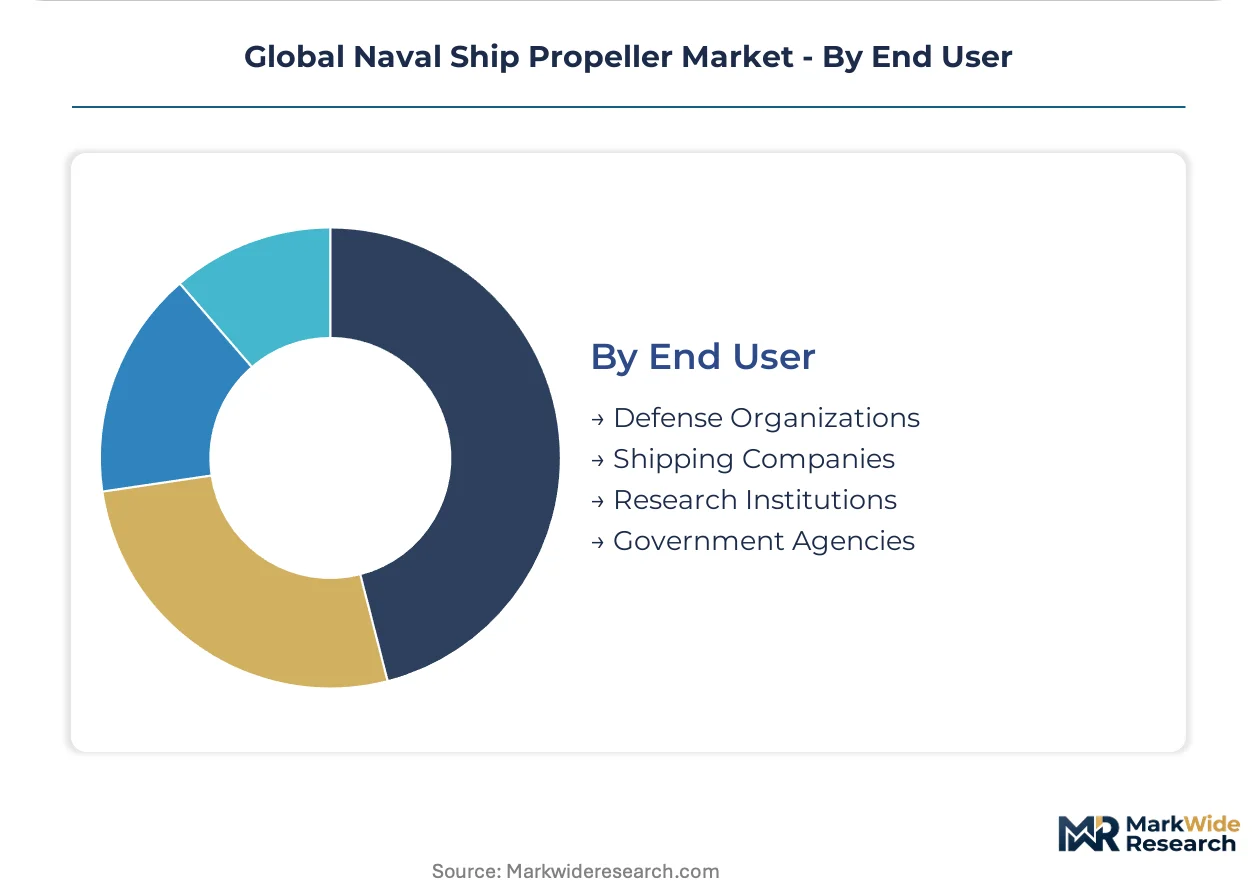
End User:
Contracting authority and funding mechanisms separate defense procurement from commercial purchasing patterns.
- Defense Organizations:Long-term availability contracts spanning 25-year service lives displace transactional spare-part purchasing. South Korea's Defense Acquisition Program Administration and Australia's Department of Defence lock suppliers into integrated logistics support with guaranteed mean-time-between-failure rates.
- Shipping Companies:Container lines and bulk operators select propellers based on total cost of ownership models with fuel efficiency as the primary variable.
- Government Agencies:Coast guards and maritime patrol services balance commercial off-the-shelf availability with mission-specific modifications.
- Research Institutions:Academic and governmental science bodies procure specialized low-signature propulsion for oceanographic survey platforms.
Defense Organizations concentrate procurement value; Shipping Companies sustain replacement demand volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentration is hardening around naval shipbuilding clusters in Germany, South Korea, Norway, and Japan, with foundry capacity and prime contractor relationships determining regional market access.
Germany
Thyssenkrupp Marine Systems and German Naval Yards drive demand for large-diameter nickel-aluminum-bronze castings in frigate and submarine programs. ECHA REACH substance restrictions on copper-based coatings force alloy reformulation R&D across Mecklenburg-Vorpommern foundries. The Rostock-Stralsund corridor anchors European propeller casting capacity, with Mecklenburger Metallguss GmbH specializing in precision-machined combatant propellers.
South Korea
Hyundai Heavy Industries Co., Ltd. and Daewoo Shipbuilding & Marine Engineering consolidate destroyer and frigate construction under the Defense Acquisition Program Administration. MFDS certification requirements and national stealth mandates elevate acoustic signature standards for new-build propellers. The Ulsan-Gyeongsang corridor integrates captive propeller production within vertically organized shipbuilding conglomerates, reducing external supplier penetration.
Norway
Kongsberg Gruppen ASA and Umoe Mandal shape procurement for littoral combat vessels and mine countermeasures through NATO STANAG acoustic compliance frameworks. The Norwegian Defence Materiel Agency mandates lower radiated noise signatures, favoring controllable pitch systems with composite blade options. The Bergen-Stavanger maritime cluster concentrates hydrodynamic R&D and specialized machining expertise for arctic-capable propulsion.
Japan
Japan Marine United and Mitsubishi Heavy Industries sustain indigenous frigate and destroyer programs under Ministry of Defense guidelines. METI industrial standards and JIS certification requirements filter foreign supplier participation in naval propulsion. The Nagasaki-Kure shipbuilding zone maintains dedicated foundry capacity for high-strength stainless steel propellers serving ice-class and high-speed craft applications.
United States
General Dynamics Electric Boat and Huntington Ingalls Industries drive submarine and surface combatant construction through US Navy long-term availability contracts. MIL-S-901D shock testing protocols and DOD acquisition regulations extend qualification timelines for propeller suppliers. The Newport News-Groton defense corridor concentrates nuclear and conventional naval construction, with limited domestic large-diameter casting capacity forcing reliance on qualified European foundries.
Global Naval Ship Propeller Market Competitive Environment
German foundries anchor the precision-casting tier; South Korean shipbuilders hold captive production advantages. The vendor base stratifies between integrated marine propulsion system providers and specialized propeller manufacturers. Three archetypes dominate: conglomerate-affiliated foundries with captive demand, independent precision casters serving NATO navies, and diversified industrial groups with propulsion portfolio extensions. Competitive moves center on long-term availability contracting and composite material qualification partnerships.
Among diversified industrial groups, Wärtsilä Corporation and Kongsberg Gruppen ASA exemplify integrated marine propulsion providers whose system-level positioning locks in propeller supply through bundled service agreements. Mecklenburger Metallguss GmbH represents the independent precision-casting archetype, occupying a specialized position within NATO naval supply chains.
| Leading Market Players |
|---|
| Hyundai Heavy Industries Co., Ltd. |
| Mecklenburger Metallguss GmbH |
| Kongsberg Gruppen ASA |
| Caterpillar Inc. |
| VEEM Ltd. |
| MAN Energy Solutions SE |
| Kawasaki Heavy Industries, Ltd. |
| ANDRITZ AG |
| Wärtsilä Corporation |
| Others |
Value Chain & Pricing Dynamics
Five-axis CNC machining expertise concentrated in Germany's Rostock-Stralsund corridor and South Korea's Ulsan-Gyeongsang belt feeds directly into pricing-tier spreads, with labor-cost differentials between these clusters creating substantial gaps between premium precision-machined controllable pitch systems and standard fixed-pitch castings.
Pricing Analysis
Volume concentrates in fixed-pitch nickel-aluminum-bronze castings for patrol and auxiliary fleets, while margins accrue to controllable pitch systems with NATO STANAG acoustic certification. Price differentiation hinges on MIL-S-901D shock qualification status and five-axis machining tolerance grades. Cost compression in standard-tier castings is intensifying because Indonesian and Philippine nickel output volatility destabilizes alloy input costs. Shipping companies exhibit highest price sensitivity through total cost of ownership models, whereas defense procurement offices prioritize guaranteed mean-time-between-failure rates over unit acquisition cost.
Supply Chain Analysis
Freight costs for large-diameter propeller castings exceeding six meters constrain supplier selection to foundries with direct deep-water port access, privileging Mecklenburg-Vorpommern, South Korea's Ulsan corridor, and Japan's Nagasaki-Kure zone. Raw material flows draw from Indonesian nickel mines, Philippine copper concentrates, and German specialty alloy formulations. Single-source vulnerability pervades diameters above six meters where only three qualified foundries operate globally. Distribution runs through prime contractor shipyards with captive in-house production or long-term availability contracts locking in integrated logistics support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The naval ship propeller market functions as a vertical-integration race where control over five-axis CNC machining talent and composite autoclave curing capabilities determines contract access, with backward integration into specialty alloy foundries serving as the critical upstream lever.
For Market Incumbents: Anticipate composite blade displacement of traditional nickel-aluminum-bronze in littoral combat vessels by securing autoclave curing partnerships and non-destructive testing certifications before qualification timelines harden. Lock in long-term nickel supply agreements with Indonesian mining consortiums to buffer alloy price volatility. Defend against emerging composite specialists by embedding integrated logistics support clauses into 25-year availability contracts that guarantee mean-time-between-failure rates. For New Entrants and Emerging Players: Unmanned surface vessel programs in the United States and United Kingdom represent the most penetrable buyer archetype, with compact high-efficiency propeller specifications distinct from manned combatant requirements. Target hybrid-electric propulsion integration projects where variable-speed optimization across diesel, electric, and combined modes demands new design expertise rather than legacy foundry relationships. Enter through outcome-based maintenance frameworks pioneered by South Korea's Defense Acquisition Program Administration and Australia's Department of Defence. For Investors and Strategic Acquirers: The window for entry favors independent precision casters with NATO STANAG qualification and existing MIL-S-901D certification rather than greenfield foundry investments. Long-term viability rests on positioning for the 25-year service life contracting shift displacing transactional spare-part purchasing. Watch for EU Green Deal shipyard incentives attaching sustainability criteria to vessel construction contracts as the inflection signal favoring suppliers with ISO 14001-certified production lines and verified low-carbon casting processes.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Qualification Partnership | Secures access to Royal Navy Type 26 and US Navy Constellation-class hybrid hub specifications. |
| Long-term Nickel Supply Agreement | Buffers margin compression from Indonesian and Philippine mining output fluctuations. |
| Five-axis CNC Machining Capacity Expansion | Addresses vocational pipeline shortages in Germany, Japan, and South Korea. |
| Integrated Logistics Support Contracting | Locks in 25-year revenue streams through guaranteed mean-time-between-failure commitments. |
| EU Green Deal Compliance Certification | Qualifies bidding for European defense procurement frameworks with sustainability prerequisites. |
Study Parameters
Document review covered NATO STANAG acoustic requirement filings, MIL-S-901D shock testing protocols, ECHA REACH substance restriction guidance, and national defense procurement codes, complemented by interviews with naval shipyard procurement directors, foundry operations managers, five-axis CNC machining specialists, composite materials engineers, and defense acquisition program administrators. Secondary validation drew from customs and trade data on nickel-aluminum-bronze alloy flows, SEC filings of diversified marine propulsion providers, and shipbuilding production databases. Bottom-up propeller unit demand estimates triangulated against top-down naval fleet modernization budget allocations.
Segment-level projections across controllable pitch, fixed pitch, shrouded, and ducted architectures incorporate material class transitions, vessel class construction pipelines, and end-user contracting model shifts. The analytical framework models propulsion system integration complexity, certification tier penetration, and regional shipbuilding cluster capacity throughout the forecast period. CAGRs derive from weighted average of historical defense procurement cycles and projected fleet replacement schedules. Industry-specific inputs include NATO STANAG acoustic threshold evolution and composite blade adoption curves in littoral combat vessel programs.
Revisions become necessary when ECHA regulatory enforcement intensifies copper-based coating restrictions, Indonesian nickel export policies shift, or submarine detection threshold breakthroughs redefine radiated noise requirements. Forecasts reflect documented assumptions on defense budget continuity and alloy supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Coastal Patrol Military Vessels Market
Naval Warfare
Anti-Ship Missile Defense System Market
Naval Warfare
Naval Vessels Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Naval Radar Systems Market
Naval Warfare
Naval Artillery System Market
Naval Warfare
Sea-Based Remote Weapon Systems Market
Naval Warfare
Military Marine Vessel Engines Market
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Military Frigate Market
Naval Warfare
Europe Naval Vessels Market
Naval Warfare
Marine Radar Market
Naval Warfare
Combat Management System Market
Naval Warfare
Naval Combat Systems Market