
 Middle-East and Africa Aircraft Engine Market | 2026-2036
Middle-East and Africa Aircraft Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Aircraft Engine Market Foresight
EU F-Gas Regulation is hardening export compliance for engine manufacturers serving Middle-East and Africa carriers, raising certification costs for refrigerant-dependent MRO workflows. General Electric Company sustains technology leadership through its advanced turbofan architectures deployed across Gulf airline fleets. Rolls-Royce plc anchors aftermarket revenue through TotalCare service contracts with Emirates and Qatar Airways. Safran SA leverages its LEAP engine joint venture to compete on narrow-body platforms serving African low-cost carriers.
Aircraft engines are gas turbine or piston-driven propulsion systems generating thrust through controlled combustion, with turbofan variants achieving bypass ratios exceeding ten-to-one for commercial fuel efficiency. Their primary function converts thermal energy into mechanical work to power fixed-wing and rotary-wing aircraft across civilian and defense missions. Turbofan engines dominate commercial aviation applications across the Middle-East and Africa, capturing the largest share of installed base value as Gulf mega-carriers prioritize fuel-efficient wide-body propulsion. Military aviation represents a concentrated but growing segment as Saudi Arabia and Egypt expand fighter jet modernization programs requiring indigenous overhaul partnerships.
Saudi Arabia's General Authority of Civil Aviation and South Africa's civil aviation regulator enforce engine emissions standards aligned with ICAO Annex 16, while the EU AI Act shapes predictive maintenance software deployed on African airline fleets through European OEM partnerships. These frameworks elevate compliance spending but create certified supplier advantages for established MRO networks. Stakeholders must monitor how carbon border adjustments on European routes reshape engine retirement cycles for carriers dependent on EU airspace access.
Market Dynamics
Wide-body fleet renewal cycles across Gulf Cooperation Council carriers are compressing procurement timelines, forcing engine OEMs to accelerate certification workflows while maintaining ICAO Annex 16 emissions compliance.
Growth Catalysts
- ICAO Annex 16 Phase 4 Standards:South Africa's civil aviation regulator is advancing compliance deadlines for engine overhauls, stimulating aftermarket demand for certified MRO providers.
- Low-Cost Carrier Expansion:African budget airlines are adding narrow-body capacity, driving turbofan procurement through lease-finance structures.
- Wide-Body Procurement Acceleration:Emirates and Etihad Airways are advancing twin-aisle fleet replacement programs, concentrating demand for high-thrust propulsion systems in the United Arab Emirates.
Market Restraints
- EU F-Gas Export Friction:The European Union's fluorinated gas regulation is hardening refrigerant-dependent MRO workflows, elevating certification costs for Middle-East and Africa-serving facilities.
- Specialized Alloy Supply Concentration:Superalloy forging capacity for high-pressure turbine blades concentrates in a limited supplier base, exposing procurement timelines to single-source risk.
- Technical Limitation on Open-Rotor Architectures:Noise and integration constraints have stalled un-ducted fan commercialization, leaving incumbent turbofan designs without near-term propulsive efficiency alternatives.
Strategic Opportunities
- Egyptian Military Modernization:Fighter jet procurement programs are creating demand for indigenous overhaul partnerships and technology transfer arrangements.
- Predictive Maintenance Convergence:Sensor fusion with edge analytics is enabling condition-based overhaul scheduling, reducing unplanned engine removals for African operators with limited spare availability.
- Saudi GACA Localization Incentives:The General Authority of Civil Aviation is structuring domestic MRO investment frameworks to capture in-region engine maintenance value.
Industry Challenges
- Certified Technician Scarcity:Gas turbine specialist training pipelines across the Middle-East and Africa lag fleet expansion rates, constraining overhaul shop throughput.
- Dual-Use Technology Licensing Complexity:Military-civilian engine component overlap triggers export control review delays, extending procurement cycles for defense-linked operators.
- Legacy Fleet Interoperability:Digital engine health monitoring retrofit onto 1990s-era powerplants requires proprietary data bus adapters, fragmenting fleet standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Aircraft Engine Market |
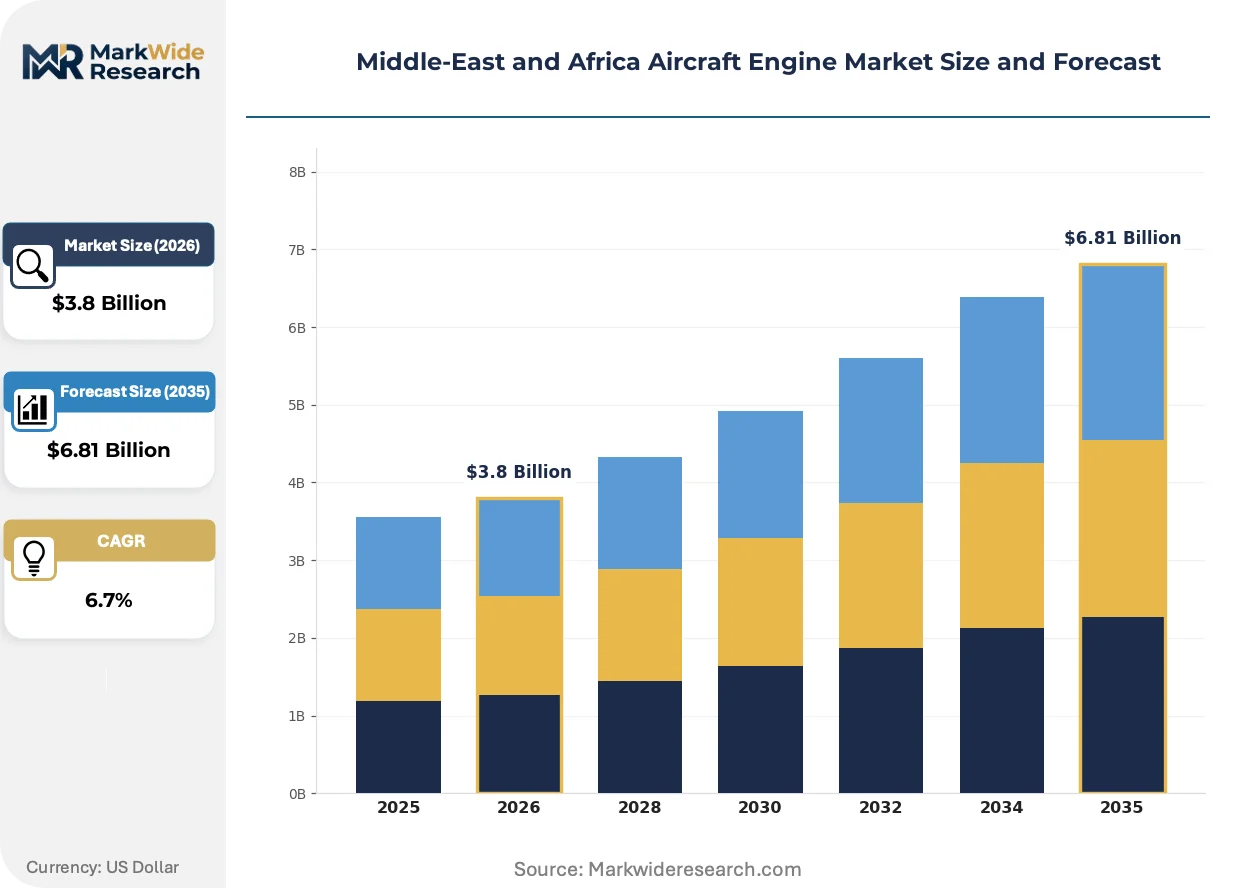
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Turbofan, Turboprop, Turbojet, Piston Application: Commercial Aviation, Military Aviation, Business Aviation, Helicopters Technology: Hybrid, Electric, Conventional, Advanced Turbofan End User: Airlines, Cargo Operators, Government Agencies, Private Operators |
| Companies Covered | Safran SA, Rolls-Royce plc, General Electric Company, RTX Corporation, Honeywell International Inc., MTU Aero Engines AG, Emirates Engineering, Turkish Technic Inc., Air France Industries KLM Engineering & Maintenance, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Aircraft Engine Market Shifts & Advancements
Propulsion architecture evolution is intersecting with emissions compliance pressure and aftermarket service restructuring, reshaping how carriers procure and maintain engine assets across the region.
Additive manufacturing of nickel superalloy turbine components is modularizing repair workflows for high-pressure sections. MRO facilities in Dubai and Johannesburg are adopting powder-bed fusion for blade tip restoration, compressing turnaround times from weeks to days. This distributed manufacturing model is modularizing traditional centralized overhaul economics.
The EU AI Act is imposing algorithmic transparency requirements on predictive maintenance software deployed through European OEM partnerships. African airlines utilizing cloud-based engine health monitoring must now document training data provenance and decision audit trails. Narrow-body operators with European route exposure are prioritizing certified-AI diagnostic platforms over uncertified alternatives.
Power-by-the-hour contracts are displacing traditional time-and-material overhaul arrangements among Gulf mega-carriers. Emirates and Qatar Airways are unbundling maintenance from acquisition finance, treating engine availability as a utility rather than a capital asset. This procurement behavior shift concentrates most visibly in wide-body fleet management strategies across the United Arab Emirates.
Middle-East and Africa Aircraft Engine Market Segmentation
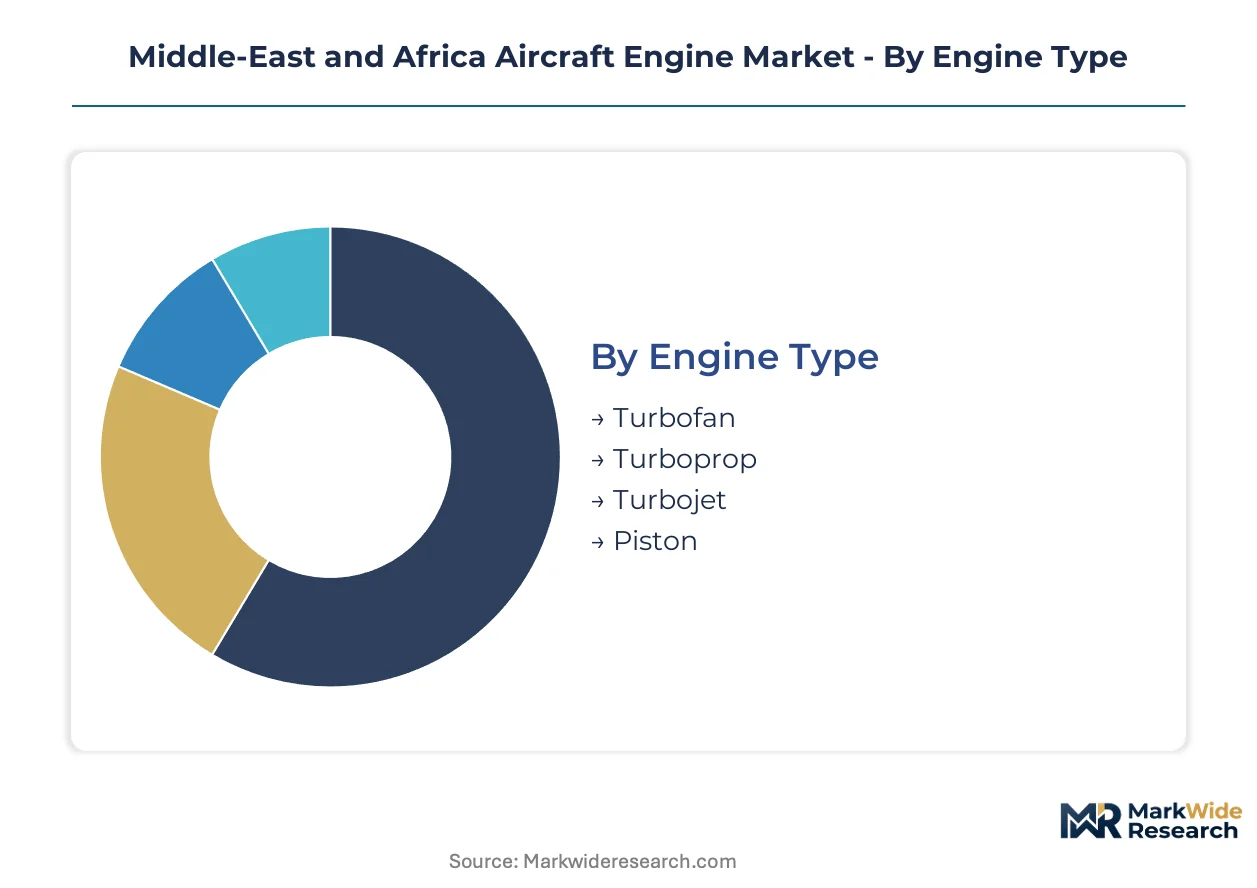
Engine procurement patterns across the Middle-East and Africa diverge sharply by mission profile and ownership structure. Fleet composition dictates technology selection, overhaul economics, and regulatory compliance pathways for operators spanning Gulf mega-carriers to African bush aviation.
Engine Type:
Capital intensity peaks with wide-body turbofan architectures requiring billion-dollar certification programs and specialized alloy supply chains.
- Turbofan:High-bypass designs dominate commercial fleets serving Emirates, Etihad, and Qatar Airways. UAE procurement concentrates demand for thrust ratings exceeding 100,000 pounds, with ICAO Annex 16 Phase 4 compliance compressing replacement cycles.
- Turboprop:Gas turbine core driving propeller systems serves African regional connectivity and Saudi Arabian domestic routes. Ethiopian Airlines and Airlink deploy these for short-haul efficiency where runway infrastructure limits jet operations.
- Turbojet:Pure jet propulsion without bypass flow persists in military fighter applications across Egypt and Saudi Arabia. Indigenous overhaul partnerships are emerging around these powerplants under technology transfer agreements.
- Piston:Reciprocating internal combustion engines power general aviation and training fleets. South African flight schools and private operators in Kenya sustain demand for these lower-cost propulsion systems.
Turbofan architectures absorb the bulk of installed capacity; turboprop configurations are expanding most quickly across African regional networks.
Application:
Mission-criticality determines maintenance regime intensity and spare parts inventory depth across operator categories.
- Commercial Aviation:Scheduled passenger and cargo services require continuous airworthiness management under GACA and South African CAA oversight. Emirates' wide-body fleet renewal compresses procurement timelines for high-thrust variants.
- Military Aviation:Fighter jet and transport platforms demand dual-use technology licensing compliance. Egyptian Air Force modernization programs are creating indigenous MRO capacity through offset agreements.
- Business Aviation:Corporate and VIP transport segments prioritize dispatch reliability over unit economics. Lagos and Johannesburg FBOs are expanding engine-on-wing support for this operator class.
- Helicopters:Rotary-wing missions span offshore oil support in the Gulf of Guinea to medevac services in the Horn of Africa. Turboshaft variants face distinct sand ingestion challenges in desert operating environments.
Commercial aviation commands the deepest MRO infrastructure investment; military applications are gaining share fastest through Saudi and Egyptian procurement programs.
Technology:
Propulsion architecture maturity shapes certification risk and aftermarket revenue predictability for OEM service contracts.
- Hybrid:Combined thermal-electric systems remain pre-commercial for large commercial applications. Gulf carriers are monitoring demonstrator programs for future narrow-body compatibility.
- Electric:Battery and fuel-cell propulsion targets urban air mobility and short-haul commuter segments. Dubai's vertiport planning is accommodating these zero-emission architectures.
- Conventional:Established turbofan and turboprop designs with decades of operational data dominate current fleet composition. African operators prioritize proven reliability over unproven efficiency gains.
- Advanced Turbofan:Next-generation architectures with geared fans and ceramic matrix composites. LEAP and PW1000G families are penetrating narrow-body fleets through lease-finance structures.
Conventional technology retains the largest installed base; advanced turbofan designs are climbing the fastest through Gulf carrier fleet renewal.
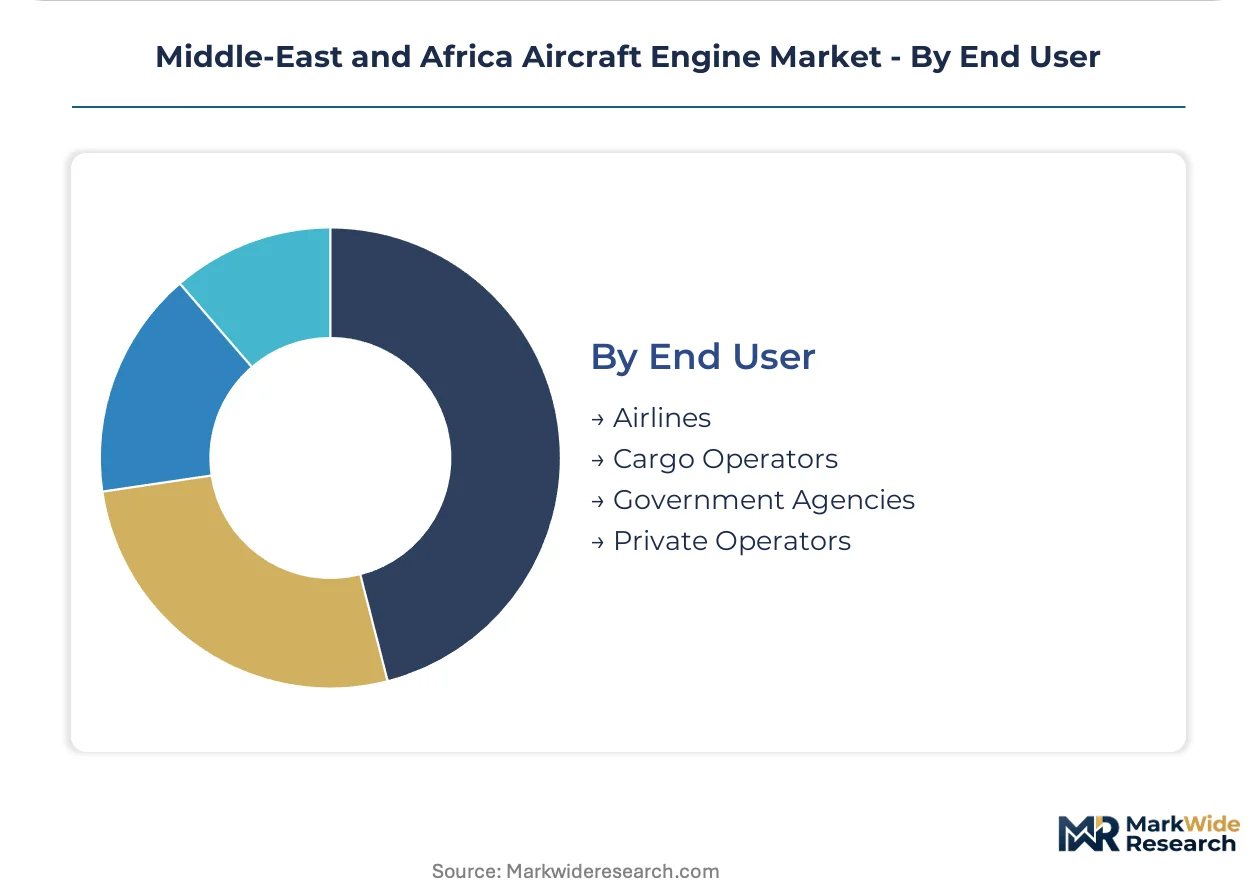
End User:
Balance sheet capacity and route network density determine engine acquisition financing structures and power-by-the-hour contract penetration.
- Airlines:Scheduled carriers with IATA operational safety audit certification manage the largest engine portfolios. Ethiopian Airlines and Royal Air Maroc are expanding their owned spare engine pools.
- Cargo Operators:Dedicated freighter fleets prioritize engine durability over passenger comfort metrics. Emirates SkyCargo and Qatar Airways Cargo are converting passenger wide-bodies to extend engine economic life.
- Government Agencies:State air wings and presidential fleets operate outside commercial regulatory frameworks. These entities often maintain captive MRO capability for sovereignty reasons.
- Private Operators:Individual and corporate owners face distinct residual value risk on engine assets. Fractional ownership models are emerging in South Africa to distribute overhaul cost exposure.
Airlines deploy the greatest engine count; cargo operators are gaining share fastest through dedicated freighter conversion demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai South's aviation district and Saudi Arabia's King Salman Aerospace Cluster are concentrating MRO investment and engine logistics infrastructure. These zones attract OEM service subsidiaries and specialized alloy suppliers seeking proximity to Gulf carrier fleets. Tax incentives for in-region maintenance value capture are accelerating facility commitments.
United Arab Emirates
Emirates and Etihad Airways are compressing wide-body fleet renewal timelines, concentrating demand for high-thrust turbofan procurement in Dubai and Abu Dhabi. The General Civil Aviation Authority enforces ICAO Annex 16 Phase 4 emissions standards with accelerated compliance deadlines. Dubai South's aviation district hosts expanding engine-on-wing support capabilities serving the mega-carrier installed base.
Saudi Arabia
Fighter jet modernization programs and domestic route expansion are stimulating military and civil turbofan demand. The General Authority of Civil Aviation structures localization incentives to capture in-region MRO value through technology transfer arrangements. The King Salman Aerospace Cluster in Riyadh is attracting joint venture partnerships for indigenous overhaul capacity.
South Africa
The civil aviation regulator is tightening emissions compliance timelines for engine overhauls, stimulating aftermarket demand for certified MRO providers. South African Airways' fleet restructuring and regional carrier expansion sustain turboprop and narrow-body turbofan requirements. Johannesburg's OR Tambo precinct concentrates specialized turbine blade repair and non-destructive testing capabilities.
Egypt
Egyptian Air Force modernization programs are creating demand for fighter jet propulsion systems and indigenous overhaul partnerships. Military-civilian dual-use technology licensing frameworks shape procurement cycles for defense-linked operators. Cairo's industrial zones host emerging joint ventures targeting turbojet maintenance capabilities under offset agreements.
Qatar
Qatar Airways' wide-body fleet expansion sustains demand for high-bypass turbofan architectures and power-by-the-hour service contracts. The Qatar Civil Aviation Authority aligns emissions enforcement with ICAO Annex 16 standards. Doha's Hamad International Airport precinct supports expanding engine logistics and quick-turn maintenance infrastructure.
Middle-East and Africa Aircraft Engine Market Competitive Landscape
North American and European producers anchor the premium-tier OEM segment; Gulf-based MRO specialists hold the aftermarket service tier. The market structure concentrates around three to four integrated propulsion system suppliers controlling high-thrust turbofan certification, while regional maintenance providers fragment across narrow-body and turboprop support. Strategic archetypes include full-service OEMs with captive leasing arms, independent MRO networks with airline affiliations, and state-linked joint ventures seeking technology transfer. Competitive moves center on power-by-the-hour contract unbundling from acquisition finance and additive manufacturing adoption for distributed repair workflows.
Within the OEM tier, General Electric Company and Rolls-Royce plc exemplify full-service propulsion suppliers with established Gulf carrier relationships. Safran SA occupies a position through its LEAP engine joint venture, targeting narrow-body platforms serving African low-cost carriers. These entities represent the integrated design-certification-service archetype dominating high-thrust commercial applications.
| Leading Market Players |
|---|
| Safran SA |
| Rolls-Royce plc |
| General Electric Company |
| RTX Corporation |
| Honeywell International Inc. |
| MTU Aero Engines AG |
| Emirates Engineering |
| Turkish Technic Inc. |
| Air France Industries KLM Engineering & Maintenance |
| Others |
Supply & Pricing Matrix
Sovereign-backed MRO joint ventures in Saudi Arabia and the UAE anchor supply discipline through technology transfer mandates, compressing pricing power for independent overhaul shops while elevating certified-procedure premiums across the Gulf Cooperation Council.
Pricing Analysis
Short lead-time premiums dominate pricing behavior for high-pressure turbine blade replacements, with spot inventory discounts emerging for surplus CFM56 and V2500 modules. Three-tier pricing structure across OEM-certified, airline-affiliated, and independent MRO levels separates Emirates' power-by-the-hour contracts from Ethiopian Airlines' time-and-material arrangements. Pricing pressure stems from EU F-Gas compliance costs elevating refrigerant-dependent workflow expenses. African low-cost carriers exhibit highest price sensitivity, while Gulf mega-carriers prioritize availability guarantees over unit cost.
Supply Chain Analysis
ICAO Annex 16 certification gates restrict superalloy forging capacity to qualified suppliers in the United States, United Kingdom, and France, fragmenting procurement timelines for high-pressure turbine components. Nickel, cobalt, and rhenium superalloys feed from concentrated mining operations in Australia, Canada, and the Democratic Republic of Congo. Single-source vulnerability concentrates in single-crystal casting facilities serving GE and Rolls-Royce architectures. Distribution runs through Dubai South's bonded logistics zone and Johannesburg's OR Tambo aerospace precinct.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU F-Gas Regulation and ICAO Annex 16 Phase 4 standards erect barrier-to-entry moats for certified MRO networks, marginalizing uncertified competitors.
For Market Incumbents: Hedge exposure to legacy fleet retirement by securing additive manufacturing certifications for distributed blade repair workflows. Defend service contract renewal rates at Emirates and Qatar Airways through predictive maintenance software compliant with EU AI Act algorithmic transparency requirements. Capacity expansion in Saudi Arabia's King Salman Aerospace Cluster captures localization incentives before indigenous joint ventures mature.
For New Entrants and Emerging Players: Sensor-fusion diagnostics for turboprop fleets serving African regional carriers offers the most penetrable white-space target, as Ethiopian Airlines and Airlink lag wide-body operators in condition-based overhaul adoption. Target Egyptian military offset agreements for turbojet maintenance partnerships under technology transfer frameworks. Go-to-market leverage rests on edge-analytics platforms requiring minimal cloud infrastructure for operators with intermittent connectivity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap MRO specialists with ICAO-certified capabilities in South Africa and Nigeria during fleet restructuring periods. Long-term viability hinges on power-by-the-hour contract penetration rates across African airline portfolios. Watch Emirates and Etihad procurement announcements for wide-body engine selection decisions as inflection indicators for aftermarket revenue concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Power-by-the-Hour Contract Expansion | Unbundles maintenance from acquisition finance for Gulf mega-carriers treating engine availability as utility service. |
| Additive Manufacturing Certification | Enables Dubai and Johannesburg MRO facilities to compress high-pressure blade repair turnaround from weeks to days. |
| Predictive Maintenance Platform Deployment | Satisfies EU AI Act training-data provenance requirements for African airlines with European route exposure. |
| Indigenous Overhaul Joint Venture | Captures Saudi GACA localization incentives through technology transfer arrangements with Egyptian military programs. |
| Superalloy Supply Diversification | Reduces single-source risk for high-pressure turbine blade forging capacity concentrated in limited qualified supplier base. |
Research Methodology
Document review covered regulatory filings from ICAO, EU EASA, and national aviation authorities across the Middle-East and Africa, complemented by interviews with MRO facility directors, fleet procurement managers at Emirates and Ethiopian Airlines, engine OEM service contract executives, and superalloy supplier technical leads. Secondary validation drew from customs trade databases, airline annual reports, aerospace cluster investment disclosures, and ICAO emissions compliance registries. Bottom-up fleet inventory analysis triangulated against top-down market size estimates from OEM delivery disclosures.
Historical delivery patterns cross-referenced against expert panel input on fleet renewal timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include engine type, application mission profile, technology maturity tier, and end-user balance sheet capacity. CAGRs derived from installed base growth rates, replacement cycle compression, and aftermarket service contract penetration assumptions. Forecast inputs incorporated EU F-Gas compliance cost trajectories and Saudi localization incentive program commitments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carbon border adjustment implementation on European routes or sudden superalloy supply disruptions. Forecasts reflect documented assumptions on fleet renewal timing and regulatory enforcement intensity. A model refresh is warranted upon material change in ICAO Annex 16 Phase 4 compliance deadlines or Gulf carrier wide-body procurement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Aero Engine Coatings Market
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
General Aviation Engines Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Gas Turbine Service Market
Aircraft Engine Systems and Services
Aircraft Engine Nacelle Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market