
 Aviation Gas Turbine Market | 2026-2036
Aviation Gas Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Gas Turbine Market Analysis
Southeast Asia is tilting toward maintenance, repair, and overhaul capacity expansion as regional air traffic surges. GE Aerospace leverages its vertical integration across compressor and turbine blade manufacturing to sustain delivery timelines. Pratt & Whitney anchors the narrowbody propulsion segment through its geared turbofan architecture. Rolls-Royce competes on widebody engine life-cycle service contracts, locking in aftermarket revenue streams.
An aviation gas turbine is a rotary internal combustion engine that converts fuel energy into mechanical work through continuous combustion, with core sections operating at pressure ratios exceeding 40:1 in modern high-bypass designs. It generates thrust or shaft power for aircraft propulsion across commercial, military, and unmanned platforms. Turbofan engines dominate the product type landscape due to their fuel efficiency advantage on medium-haul routes. Military aviation applications command premium pricing for survivability-hardened designs. Biofuels compatibility is emerging as a critical fuel type differentiator as operators face tightening emissions benchmarks.
The FAA enforces airworthiness standards under Part 33 certification, while the EPA regulates aircraft engine emissions under the Clean Air Act, jointly elevating R&D spending on low-NOx combustors. EASA's CS-E certification requirements and the EU Green Deal's aviation decarbonization targets are compressing development cycles for European manufacturers. Stakeholders must weigh sustainable aviation fuel infrastructure readiness against engine hardware retrofit economics when allocating capital across product portfolios.
Market Dynamics
Fleet renewal cycles and tightening emissions mandates are compressing development timelines for next-generation propulsion systems. Manufacturers face simultaneous pressure to certify higher bypass ratios while integrating sustainable aviation fuel compatibility into existing architectures.
Growth Catalysts
- ReFuelEU Aviation Mandate:Binding SAF blending requirements are forcing engine hardware retrofits and accelerating R&D into fuel-flexible combustor designs across European operators.
- NextGen Airspace Modernization:The FAA's trajectory-based operations are driving demand for engines with enhanced thrust responsiveness and reduced time-in-trail separation capabilities.
- Narrowbody Fleet Density:United States domestic carriers are concentrating procurement on high-cycle turbofans for single-aisle routes, pulling delivery slots forward.
Market Restraints
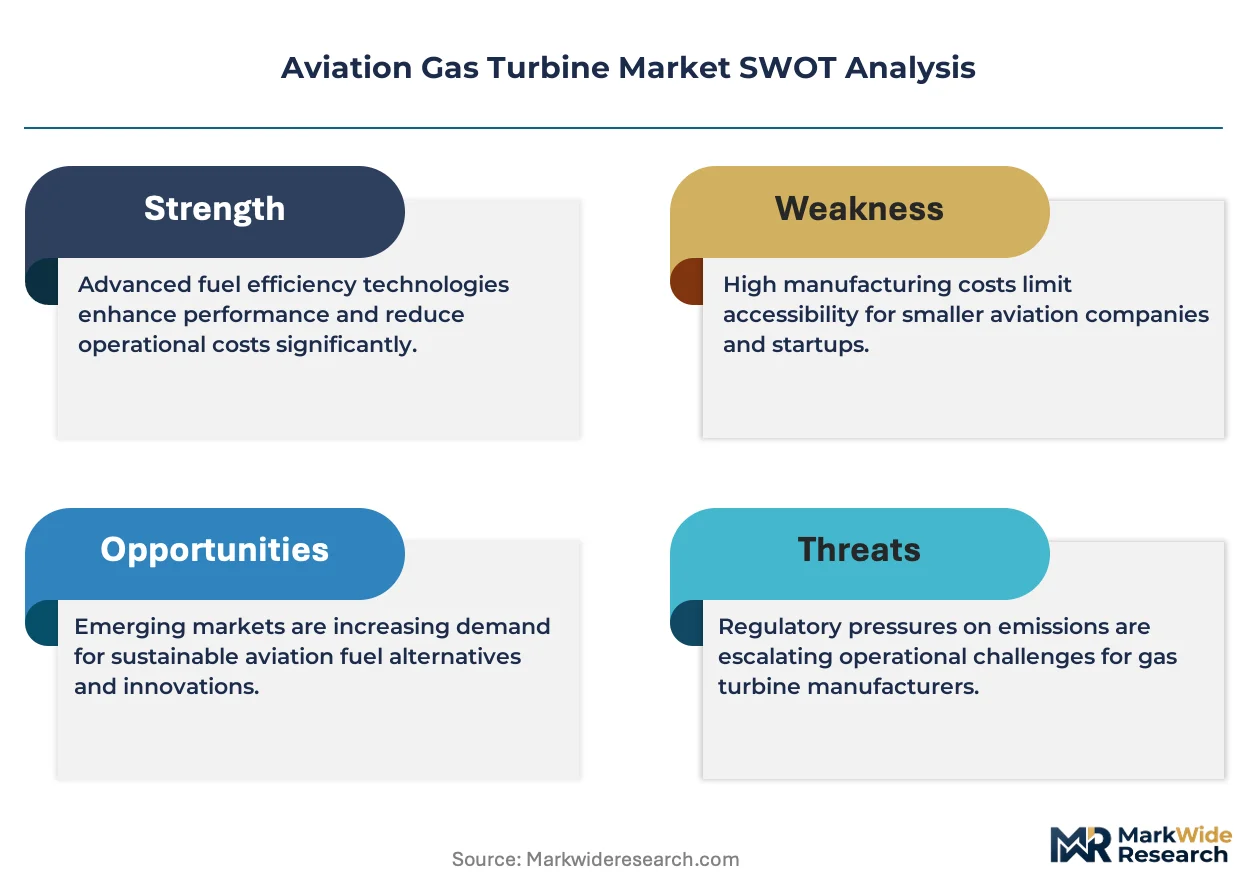
- Superalloy Supply Concentration:Single-source dependence on vacuum induction melting capacity in the United States creates vulnerability for turbine blade casting schedules.
- CS-E Certification Friction:EASA's evolving noise and emissions stringency is extending type certification timelines for clean-sheet engine programs by 18-24 months.
- Electrification Substitution:Hybrid-electric propulsion architectures for sub-50 seat regional aircraft are capturing venture funding and pilot program commitments.
Strategic Opportunities
- Southeast Asia MRO Expansion:Singapore and Indonesia are building engine overhaul capacity to capture turnaround traffic from Chinese and Indian carriers.
- Digital Twin Convergence:Physics-based modeling fused with flight data analytics is enabling predictive maintenance contracts that lock in aftermarket revenue.
- US PLI-Analog Incentives:Domestic content requirements in defense procurement are creating captive demand for sovereign-source turbine component manufacturing.
Industry Challenges
- Ceramic Matrix Composite Integration:Scaling CMC turbine shroud production to match OEM assembly rates requires capital-intensive autoclave capacity expansion.
- Part 33 Certification Backlog:FAA resource constraints are delaying amended type certificate approvals for derivative engines with modified combustors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Gas Turbine Market |
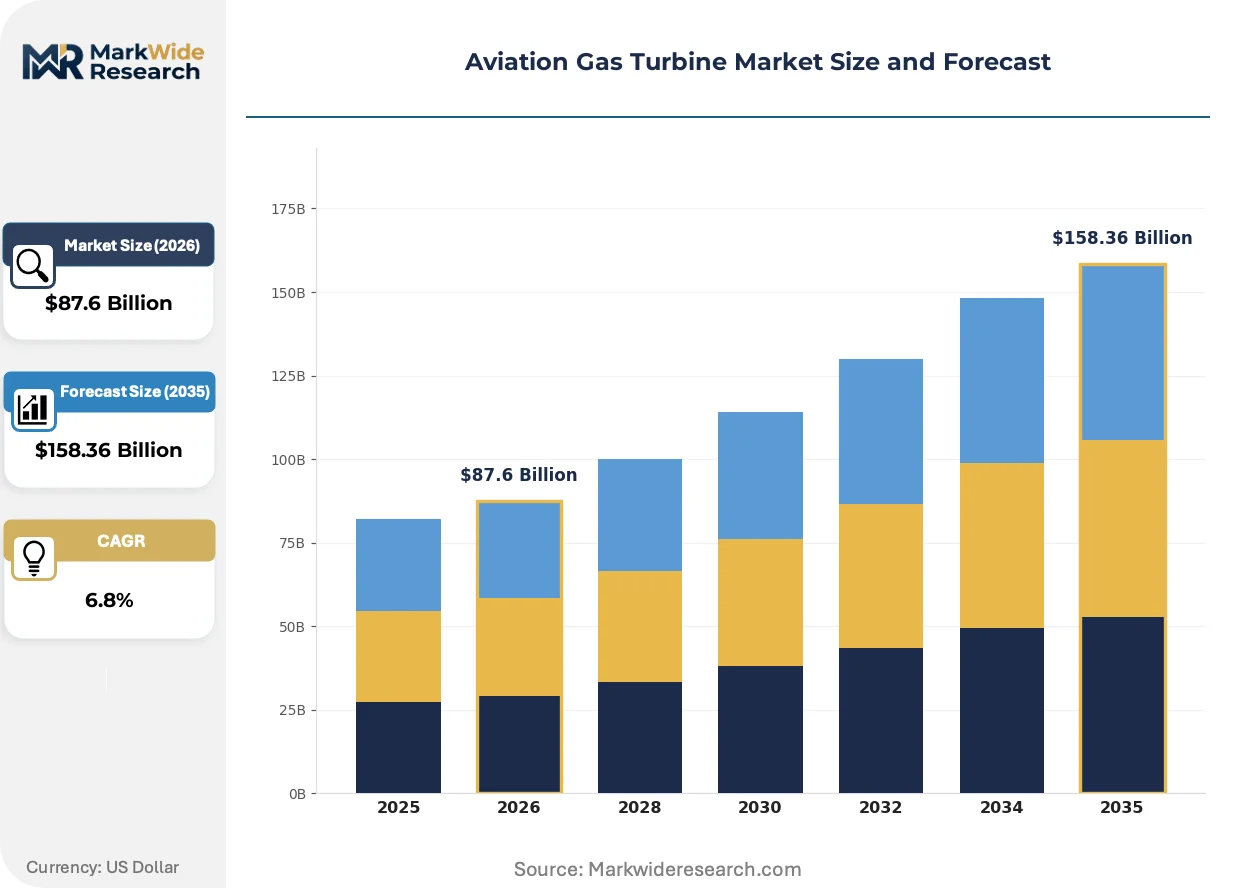
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbojet, Turbofan, Turboprop, Ramjet Application: Commercial Aviation, Military Aviation, Business Aviation, UAVs End User: Airlines, Military Organizations, Charter Services, Aircraft Manufacturers Fuel Type: Jet A, Jet A-1, Avgas, Biofuels |
| Companies Covered | GE Aerospace, Rolls-Royce, Pratt & Whitney, Safran Aircraft Engines, Siemens Energy, Mitsubishi Heavy Industries, Honeywell Aerospace, IHI Corporation, MTU Aero Engines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Gas Turbine Market Emerging Trajectories
Propulsion architecture is converging with digital infrastructure and alternative fuel systems. Three interconnected developments are redefining competitive positioning in engine manufacturing and aftermarket services.
Additive manufacturing is digitizing turbine component production. GE Aerospace and Pratt & Whitney have qualified laser powder bed fusion for fuel nozzle geometries that previously required 20-part assemblies. Commercial aviation engine programs are adopting these processes for low-volume, high-complexity castings. The technology is digitizing supply chain configuration by collapsing tier-2 machining and brazing operations into single-step builds.
EPA aircraft engine emissions standards under the Clean Air Act are tightening NOx thresholds for newly certified engines. The regulatory compression is forcing combustor redesigns with lean-premixed pre-vaporized architectures. Widebody engine programs face the steepest compliance burden, with manufacturers accelerating staged combustion demonstrations to meet 2028 implementation windows.
Power-by-the-hour contracts are displacing transactional spare parts purchasing. Low-cost carriers in Southeast Asia and Latin America are unbundling maintenance from original equipment procurement, favoring third-party MRO providers with component repair authority. The shift is most pronounced among airlines operating narrowbody fleets on high-utilization schedules where downtime minimization overrides OEM service premiums.
Aviation Gas Turbine Market Segmentation
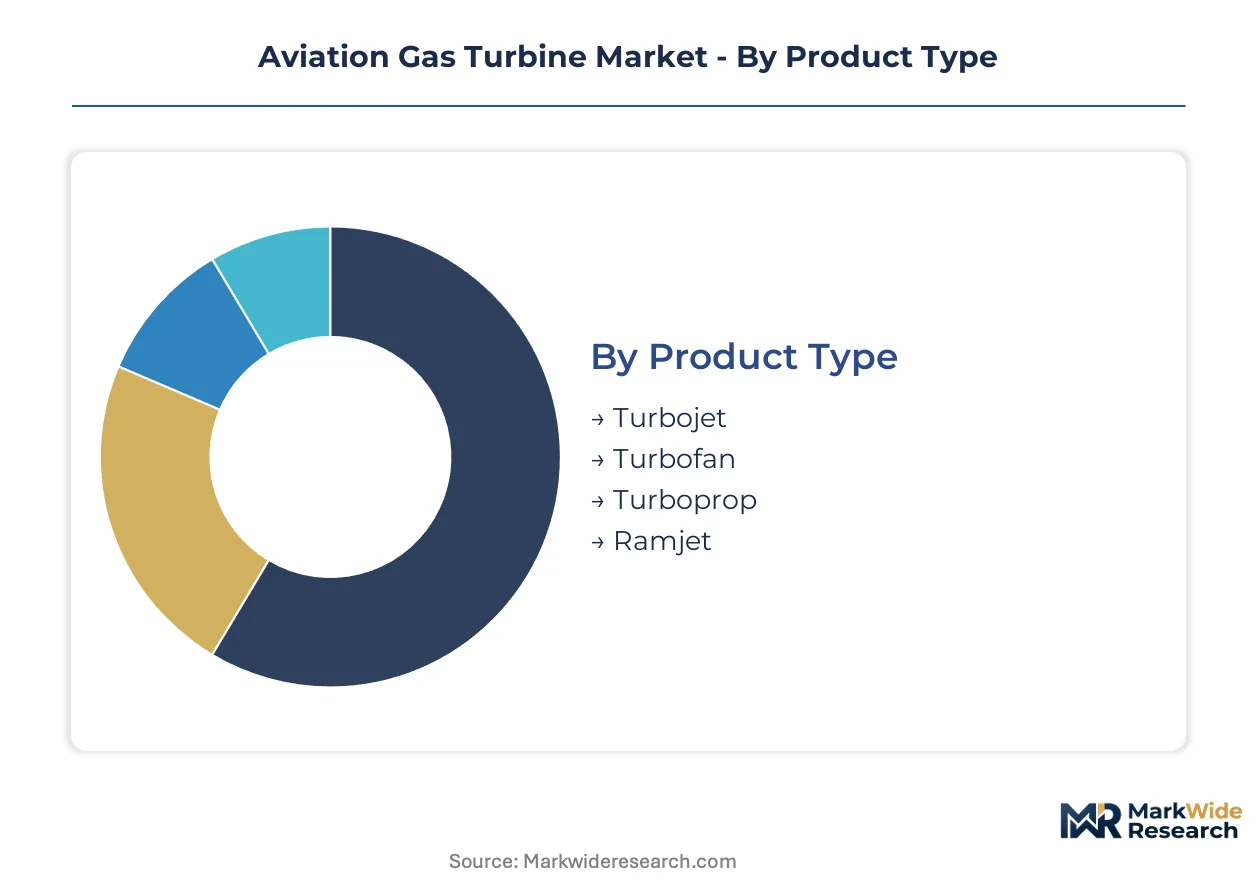
Segmentation in aviation gas turbines reveals how engineering specifications, regulatory boundaries, and operator economics create distinct procurement patterns. Manufacturers configure product portfolios around thrust class, mission profile, and fuel system architecture rather than pursuing universal platforms.
Product Type:
Thrust generation architecture determines fuel burn rates, noise signatures, and maintenance intervals across fleet operations.
- Turbofan:High-bypass designs with bypass ratios exceeding 10:1 dominate medium-haul commercial routes. United States domestic carriers are concentrating procurement on these engines for narrowbody fleet renewal, pulling forward delivery slots from GE Aerospace and Pratt & Whitney.
- Turbojet:Pure jet configurations without bypass airflow serve supersonic and military interceptor applications where frontal area minimization overrides efficiency. Demand concentrates in defense procurement programs with survivability-hardened requirements commanding premium pricing.
- Turboprop:Gas turbine core driving propeller systems through reduction gearing serves regional routes under 500 nautical miles. Southeast Asian operators favor these for short-haul island networks where runway length constraints limit jet operations.
- Ramjet:Compression achieved through forward motion rather than mechanical stages powers hypersonic weapons and experimental aircraft. Military organizations anchor demand with specialized test infrastructure requirements.
Turbofan holds installed capacity. Turboprop is rotating up the share rankings.
Application:
Mission duration, payload requirements, and airspace classification segment demand across operator types with divergent certification needs.
- Commercial Aviation:Scheduled passenger and cargo operations on certified air carrier routes. Fleet renewal cycles at United States domestic airlines are compressing development timelines for next-generation propulsion systems with higher bypass ratios.
- Military Aviation:Combat, transport, and surveillance missions requiring hardened electronics and debris-tolerant designs. The US Department of Defense procurement anchors volume with sovereign-source component mandates under domestic content requirements.
- Business Aviation:Corporate and private operator fleets emphasizing dispatch reliability and cabin noise reduction. Charter services in the Middle East are expanding long-range jet acquisitions with extended service contracts.
- UAVs:Unmanned platforms spanning tactical reconnaissance to high-altitude endurance missions. Hybrid-electric architectures are capturing venture funding for sub-50 seat applications, threatening small turbofan substitution.
Commercial Aviation commands revenue concentration. UAVs are climbing the fastest on unit volume.
End User:
Procurement authority and operating model economics shape engine selection criteria and aftermarket engagement terms.
- Airlines:Network carriers and low-cost operators with high-cycle utilization schedules. Power-by-the-hour contracts are displacing transactional spare parts purchasing among Southeast Asian and Latin American carriers.
- Military Organizations:Defense ministries with lifecycle cost accounting and sovereign maintenance requirements. The US PLI-analog incentives create captive demand for domestic turbine component manufacturing.
- Charter Services:On-demand operators with irregular utilization patterns favoring flexible maintenance windows. Premium-mid-economy pricing differentiation separates fractional ownership from ad-hoc charter.
- Aircraft Manufacturers:OEMs procuring engines for new airframe programs under sole-source or competitive selection. EASA's CS-E certification friction extends type certification timelines for clean-sheet engine programs.
Airlines hold aftermarket contract value. Military Organizations are expanding through offset agreements.
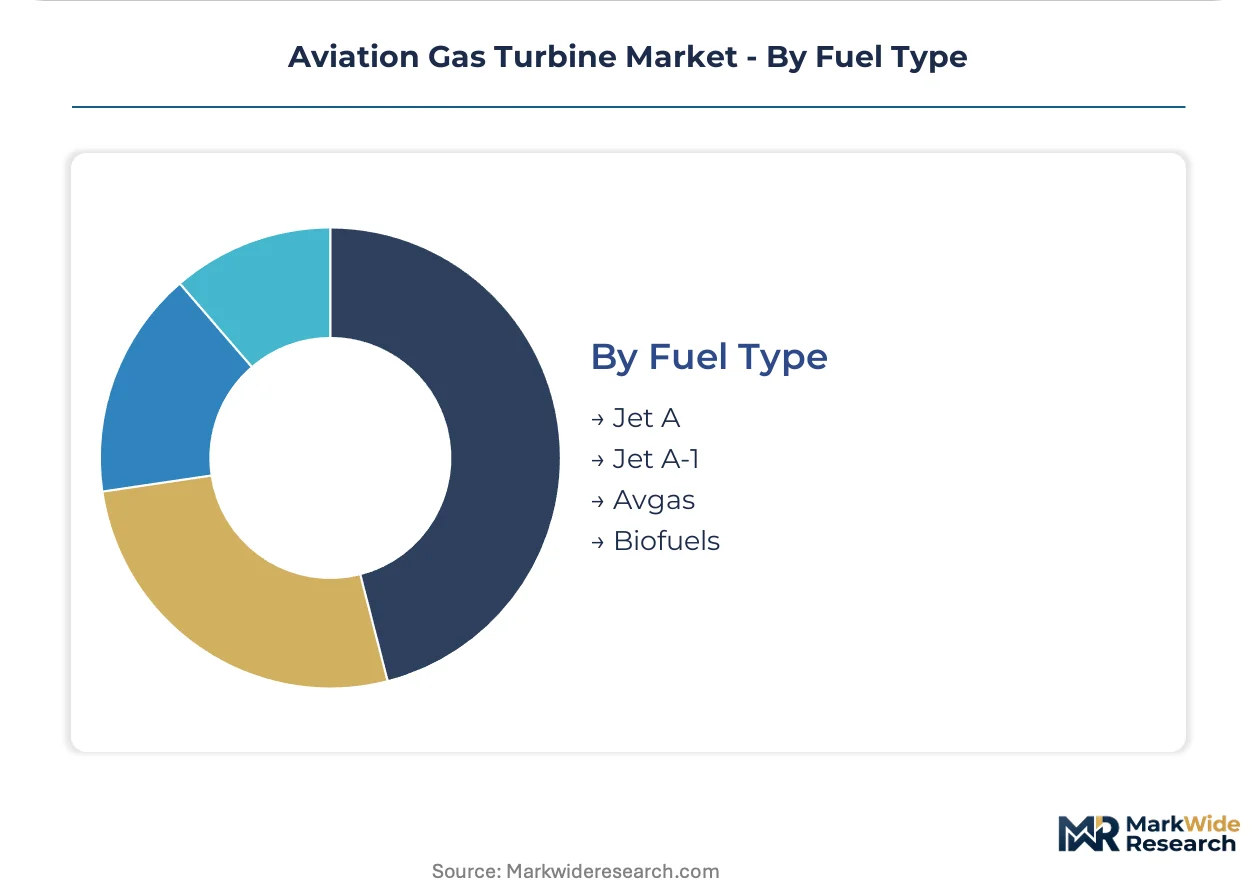
Fuel Type:
Energy density, availability infrastructure, and emissions compliance define fuel system compatibility requirements.
- Jet A:Kerosene-based fuel standard in the United States with freeze point specifications for high-altitude operations. The EPA's Clean Air Act emissions standards are tightening NOx thresholds for engines certified on this fuel.
- Jet A-1:Lower freeze point variant specified by ICAO for international operations. European operators face ReFuelEU Aviation blending mandates forcing hardware retrofits for fuel-flexible combustor designs.
- Avgas:High-octane gasoline for piston engines in general aviation and training aircraft. Demand concentrates in flight schools and private owner segments with legacy fleet compositions.
- Biofuels:Sustainable aviation fuel from hydroprocessed esters and fatty acids or Fischer-Tropsch synthesis. Compatibility is emerging as a critical differentiator as operators face tightening emissions benchmarks from the EU Green Deal.
Jet A-1 holds distribution infrastructure. Biofuels are gaining share fastest on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation gas turbine consumption patterns diverge sharply by geography: United States carriers prioritize narrowbody fleet renewal with high-cycle turbofans, while European operators accelerate sustainable aviation fuel retrofits under binding mandates. Southeast Asian markets concentrate on maintenance capacity buildout to capture surging regional traffic.
United States
Domestic carriers are compressing delivery timelines for single-aisle engine procurement as fleet renewal cycles peak. The FAA's NextGen trajectory-based operations mandate drives demand for enhanced thrust responsiveness in new certifications. Manufacturing clusters in Ohio and North Carolina anchor turbine blade casting and compressor assembly operations.
Germany
Engine life-cycle service contracts dominate procurement economics as operators seek locked-in aftermarket revenue streams. EASA's CS-E certification requirements extend type approval timelines for clean-sheet programs by 18-24 months. Munich and Hamburg host specialized MRO facilities serving Central European carrier networks.
Singapore
Maintenance, repair, and overhaul capacity expansion is capturing turnaround traffic from Chinese and Indian operators. The city-state's aviation regulator en stringent noise and emissions standards aligned with ICAO Annex 16. Seletar Aerospace Park concentrates engine overhaul infrastructure with OEM-authorized repair authority.
United Kingdom
Widebody engine programs command premium positioning through long-term service agreements covering life-limited parts. The Civil Aviation Authority implements EPA-equivalent emissions standards under bilateral recognition agreements. Derby maintains turbine manufacturing heritage with specialized combustor testing facilities.
Japan
Industrial participation in international engine programs sustains domestic aerospace supply chain viability. METI coordinates technology transfer agreements under offset arrangements with foreign OEMs. Nagoya and Tokyo clusters specialize in precision casting and ceramic matrix composite component fabrication.
Aviation Gas Turbine Market Vendor Landscape
Capability concentration sits with full-system integrators; scale advantage sits with modular specialists and national champions. The market structures around three tiers: propulsion system architects controlling core architecture, tier-1 component specialists capturing critical rotating assemblies, and regional fabricators serving aftermarket repair networks. Dominant competitive moves include backward integration into superalloy supply and strategic partnerships for sustainable aviation fuel certification.
Within the propulsion architect tier, GE Aerospace and Rolls-Royce exemplify divergent strategic positioning. GE Aerospace anchors the narrowbody segment through compressor and turbine manufacturing integration. Rolls-Royce occupies the widebody service contract vector with life-cycle revenue models. Pratt & Whitney sits between these archetypes with geared turbofan architecture specialization.
| Leading Market Players |
|---|
| GE Aerospace |
| Rolls-Royce |
| Pratt & Whitney |
| Safran Aircraft Engines |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| Honeywell Aerospace |
| IHI Corporation |
| MTU Aero Engines |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific freight corridors from Nagoya to Seattle transmit superalloy casting cost volatility into downstream engine pricing, concentrating margin pressure on OEMs while enabling geographic price differentiation between Asian MRO hubs and Western manufacturing clusters.
Pricing Analysis
Price spreads between United States and Southeast Asian maintenance contracts exceed thirty percent on equivalent thrust-class overhauls. Three-tier pricing structure across premium, standard, and economy levels separates OEM-authorized service from independent MRO and parts-only procurement. Pricing pressure stems from low-cost carriers unbundling maintenance from original equipment procurement. Airlines operating narrowbody fleets on high-utilization schedules exhibit lowest price sensitivity; charter services with irregular utilization patterns negotiate most aggressively on hourly rates.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for vacuum induction melting feedstock. Superalloy supply concentrates in the United States, Germany, and Japan for turbine blade casting operations. Raw material dependencies rest on nickel-cobalt superalloys, ceramic matrix composite precursors, and precision-forged titanium compressor disks. Single-source vulnerability in vacuum arc remelting capacity creates bottleneck risk for high-pressure turbine components. Distribution runs through OEM-direct contracts for new engines and authorized MRO networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to commercial airline fleet renewal waves following pandemic-era deferrals. Narrowbody engine procurement cycles at United States domestic carriers validate the upswing trajectory.
For Market Incumbents: Entrench aftermarket revenue through predictive maintenance contracts fused with digital twin analytics. Capture sovereign-source manufacturing mandates under US PLI-analog defense procurement incentives. Counter hybrid-electric substitution threats in sub-50 seat regional segments by accelerating fuel-flexible combustor certification. Deepen backward integration into superalloy supply to insulate casting schedules from single-source vulnerability.
For New Entrants and Emerging Players: Pursue ceramic matrix composite component fabrication for turbine shroud applications where OEM assembly rates outstrip qualified supplier capacity. Target Singapore and Indonesia MRO expansion zones where engine overhaul demand exceeds authorized repair infrastructure. Penetrate through specialized repair authority for life-limited parts rather than competing on new engine development cycles.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core aerospace turbine divisions. Long-term viability centers on aftermarket contract lock-in rather than cyclical new equipment sales. Monitor ReFuelEU Aviation mandate compliance timelines as inflection indicator for fuel-flexible combustor retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Convergence | Physics-based modeling fused with flight data analytics enables predictive maintenance contracts that lock in aftermarket revenue. |
| Sustainable Aviation Fuel Certification | ReFuelEU Aviation blending mandates force hardware retrofits and accelerate R&D into fuel-flexible combustor designs. |
| Ceramic Matrix Composite Scale-Up | Capital-intensive autoclave capacity expansion addresses turbine shroud production bottlenecks matching OEM assembly rates. |
| Southeast Asia MRO Expansion | Singapore and Indonesia build engine overhaul capacity to capture turnaround traffic from Chinese and Indian carriers. |
| Sovereign-Source Manufacturing | Domestic content requirements in US defense procurement create captive demand for turbine component manufacturing. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FAA certification databases, EASA type approval records, and airline fleet planning disclosures. Primary interviews engaged propulsion system architects, MRO operations directors, airline procurement executives, and superalloy supply specialists. Secondary validation drew from customs trade data, SEC aerospace segment filings, and ICAO emissions compliance reports. Bottom-up engine delivery forecasts triangulated against top-down airline capex projections across the analysis window.
Forecast inputs span thrust class segmentation, fleet renewal cycle timing, regulatory certification timelines, and sustainable aviation fuel infrastructure readiness. Modeled dimensions include product type architecture, application mission profile, end-user procurement authority, and fuel system compatibility. CAGRs derived from regression against historical delivery patterns and projected airline capacity expansion. Industry-specific inputs incorporate CS-E certification friction timelines and Part 33 amendment backlogs.
Macroeconomic conditions sit as an overlay; deviation in jet fuel price volatility, interest rate environments for aircraft financing, or trade policy on superalloy feedstock would shift the trajectory. Material shifts in EPA NOx threshold implementation or EASA noise stringency enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Global Aircraft Engine Fuel Systems Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
America Aircraft Engines Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Angle of Attack Sensor Market
Aircraft Engine Systems and Services
Gas Turbine Service Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Rocket Propulsion Market