
 Commercial Aircraft Gas Turbine Engine Market | 2026-2036
Commercial Aircraft Gas Turbine Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Gas Turbine Engine Market Analysis
The commercial aircraft gas turbine engine market is consolidating around a widening gap between ultra-high-bypass turbofans for widebody platforms and mature workhorse designs serving the narrowbody installed base. GE Aerospace leverages its vertical integration across core architectures and materials science to sustain pricing power in the premium tier. Pratt & Whitney competes through geared turbofan technology leadership, while Rolls-Royce anchors its position in superfan development for next-generation long-haul aircraft.
A commercial aircraft gas turbine engine converts thermal energy from compressed and combusted air into mechanical thrust through sequential compressor, combustor, and turbine stages, with modern turbofans achieving bypass ratios exceeding 10:1 for propulsive efficiency above fifty percent. Turbofan engines dominate current order books as airlines prioritize fuel efficiency on single-aisle routes, while turboprop configurations retain structural relevance in regional connectivity markets where runway length and operating economics constrain jet operations. Component-level demand concentrates in turbine and compressor segments, where superalloy casting complexity and thermal barrier coating sophistication determine supplier margins and aftermarket capture rates.
FAA certification standards under Part 33 and EASA CS-E engine requirements shape product development timelines and market access conditions for all manufacturers seeking dual-jurisdiction approval. EPA aircraft emission guidelines and ICAO Carbon Offsetting and Reduction Scheme for International Aviation obligations force engine makers to prioritize combustor redesign and sustainable aviation fuel compatibility in current research programs. Stakeholders must monitor how China’s CAAC indigenous certification pathway for CJ-1000A engines alters competitive dynamics in the largest narrowbody demand market outside North America and Europe.
Market Dynamics
Fleet renewal cycles at low-cost carriers are compressing engine procurement timelines, while ICAO Annex 16 Volume III emissions standards force simultaneous combustor redesign and sustainable aviation fuel compatibility investments across all OEM development programs.
Growth Catalysts
- Narrowbody Fleet Renewal:Southwest Airlines and Ryanair procurement programs are accelerating turbofan engine orders for next-generation single-aisle platforms, concentrating demand in the installed base replacement cycle.
- FAA Part 33 Certification Pathway:Streamlined dual-jurisdiction approval processes with EASA CS-E requirements are reducing time-to-market for new engine architectures seeking United States and European market access.
- Superalloy Casting Advances:Thermal barrier coating sophistication in turbine and compressor segments is extending time-on-wing metrics and expanding aftermarket service revenue capture for component suppliers.
Market Restraints
- Titanium and Nickel Alloy Volatility:Superalloy input cost fluctuations are compressing supplier margins in turbine blade and disk manufacturing, with spot price sensitivity concentrated in forged rotating components.
- Geographic Supply Concentration:Precision casting capacity for single-crystal turbine blades clusters in specialized foundries, creating bottleneck risk for engine OEMs dependent on third-party superalloy component sourcing.
- Bypass Ratio Physical Limits:Fan diameter expansion on ultra-high-bypass architectures is approaching nacelle integration and ground clearance constraints, capping propulsive efficiency gains from geometric scaling alone.
Strategic Opportunities
- China CAAC Indigenous Certification:The CJ-1000A engine pathway through China's national aviation regulator creates white space for domestic narrowbody propulsion systems serving COMAC C919 fleet expansion.
- Sustainable Aviation Fuel Compatibility:ICAO CORSIA obligations and EPA aircraft emission guidelines are mandating combustor redesign programs that reward early-mover OEMs with certified multi-fuel architectures.
- Regional Turboprop Connectivity:Runway-constrained markets in Southeast Asia and sub-Saharan Africa retain structural demand for gas turbine turboprop configurations where jet economics prove unviable.
Industry Challenges
- Specialized Welding and Coating Talent:Superalloy joining processes and thermal spray application expertise face generational workforce gaps, extending qualification timelines for critical repair station operations.
- Dual-Jurisdiction Certification Synchronization:FAA-EASA harmonization gaps in engine test sequence requirements force redundant validation campaigns, inflating development budgets for global market entry.
- Legacy Fleet MRO Integration:Digital thread compatibility between predictive maintenance platforms and 1990s-era engine monitoring systems requires costly avionics bridge solutions for mixed-fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Gas Turbine Engine Market |
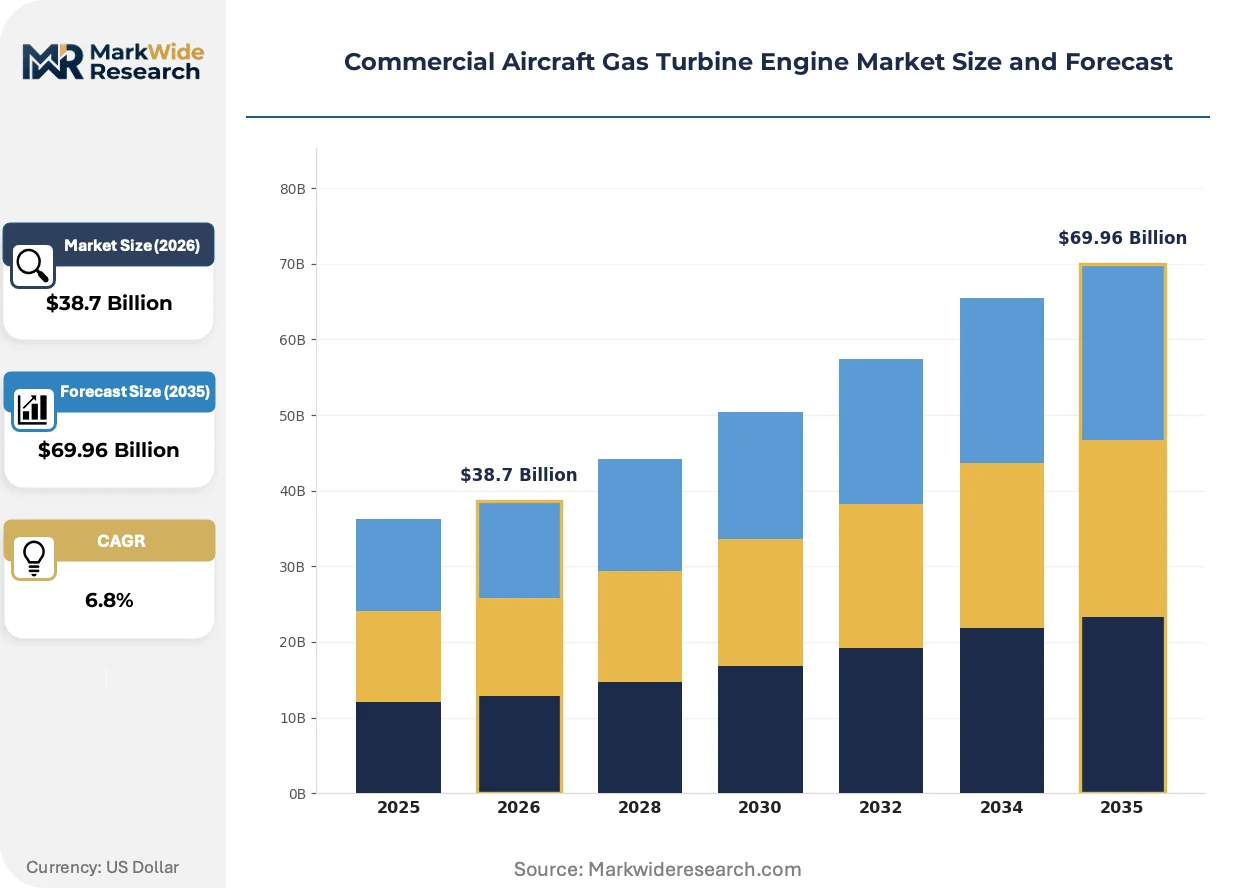
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
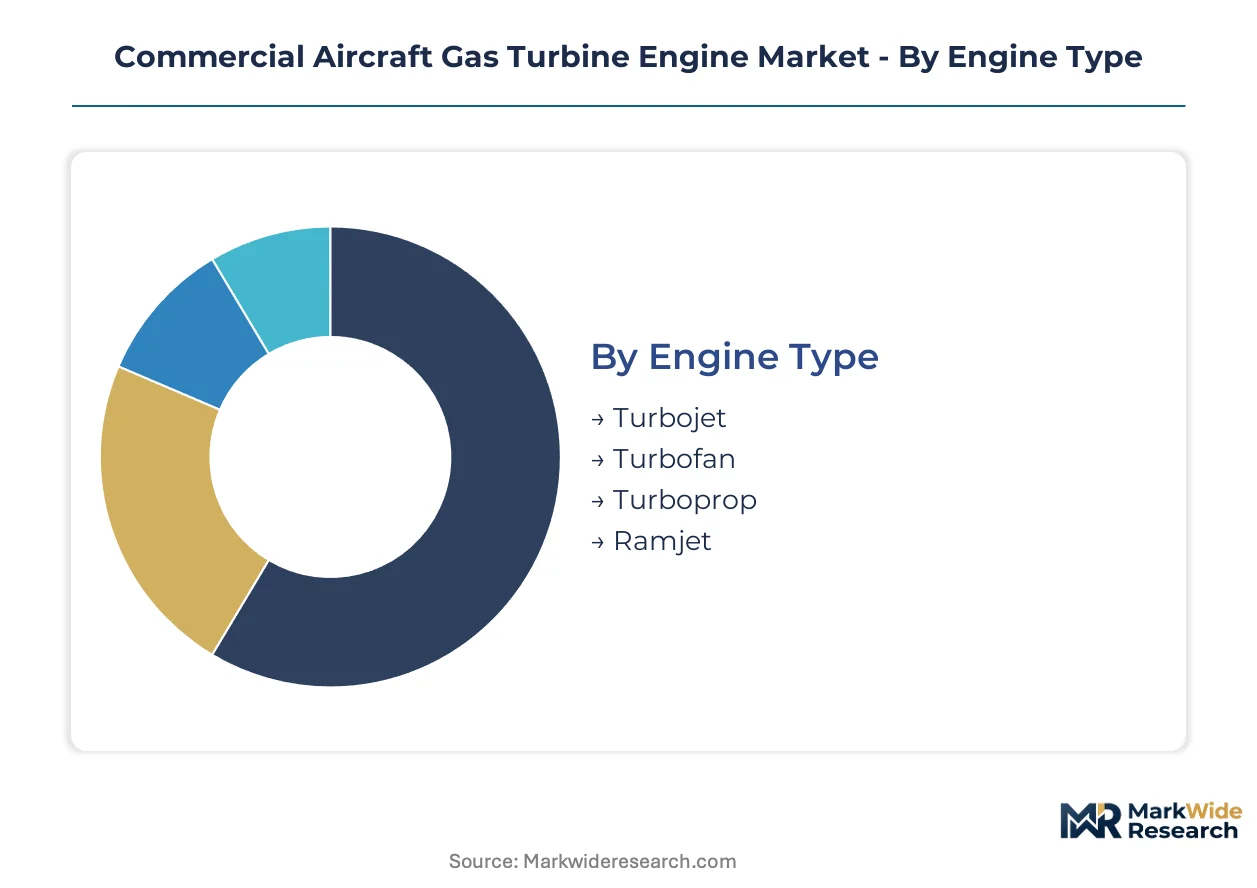
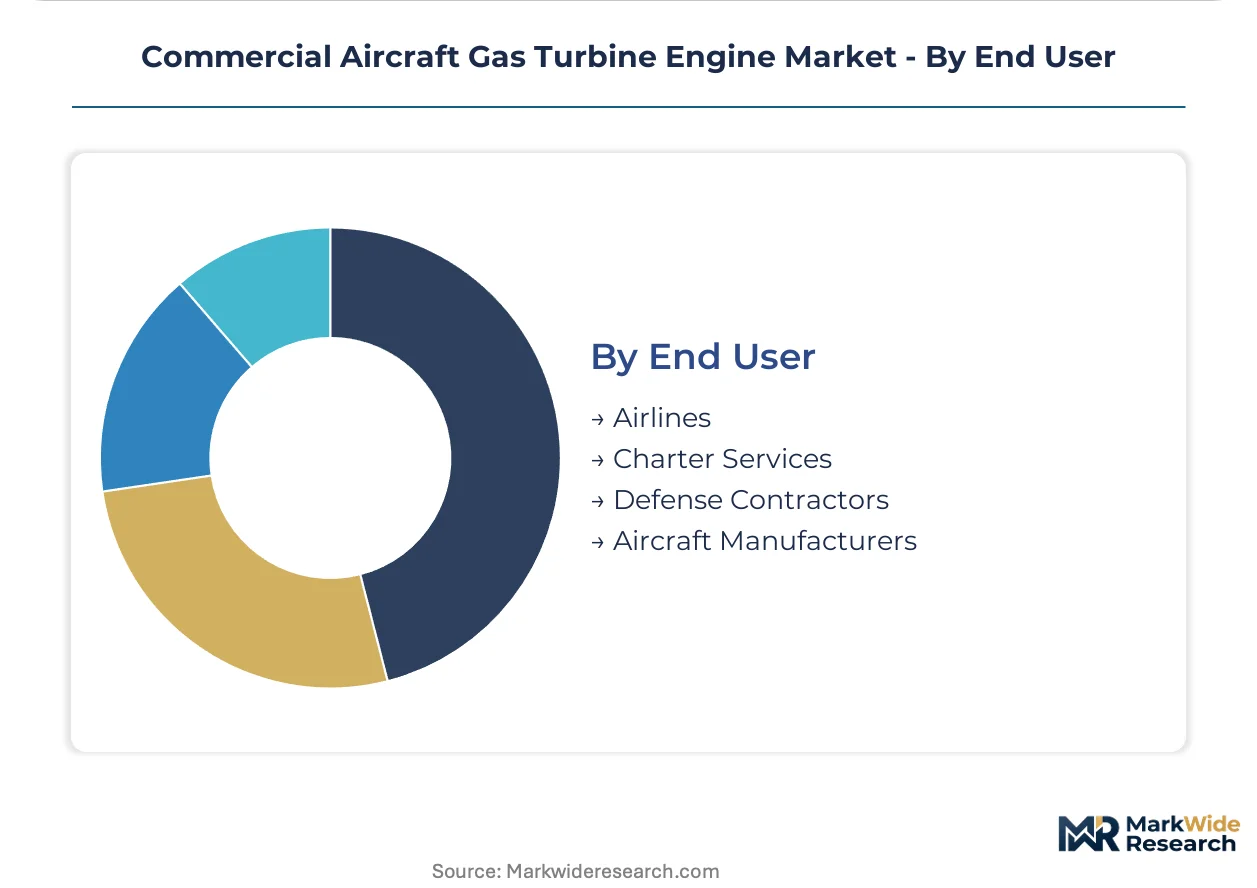
| Segmentation | Engine Type: Turbojet, Turbofan, Turboprop, Ramjet Application: Commercial Aviation, Cargo Transport, Private Jets, Military Aviation Component: Fan, Compressor, Turbine, Exhaust End User: Airlines, Charter Services, Defense Contractors, Aircraft Manufacturers |
| Companies Covered | GE Aerospace, Pratt & Whitney, Rolls-Royce, CFM International, Safran Aircraft Engines, MTU Aero Engines, Honeywell Aerospace, IHI Corporation, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Gas Turbine Engine Market Emerging Trajectories
Propulsion architecture is bifurcating between mature narrowbody workhorse designs and experimental widebody superfan concepts, with materials science and regulatory compliance timelines determining competitive positioning across each tier.
Additive manufacturing of nickel superalloy turbine vanes is electrifying repair and replacement part economics for legacy engine programs. MRO providers at Delta TechOps and Lufthansa Technik are adopting powder-bed fusion for non-rotating hot-section components, compressing lead times from sixteen weeks to under four while eliminating forging die capital for low-volume legacy parts.
ICAO Carbon Offsetting and Reduction Scheme for International Aviation obligations are forcing combustor redesign priorities across GE Aerospace, Pratt & Whitney, and Rolls-Royce engineering centers. The regulatory pressure is diverting R&D bandwidth from performance optimization to fuel-flexible injection systems capable of handling synthetic paraffinic kerosene blends up to one hundred percent, with European operators facing the most accelerated compliance timelines under EU Green Deal aviation decarbonization targets.
Power-by-the-hour contracting is consolidating maintenance spend decisions at airline fleet management offices, displacing traditional transactional parts procurement. Lessors like AerCap and SMBC Aviation Capital are bundling engine coverage into lease rates, channeling aftermarket revenue toward OEM-affiliated service networks and compressing independent MRO market access for non-captive repair stations in Singapore and the United Arab Emirates.
Commercial Aircraft Gas Turbine Engine Market Segmentation
Engine procurement decisions in commercial aviation split across performance requirements, airframe integration constraints, and aftermarket service economics. Fleet planners weigh thrust-specific fuel consumption against maintenance interval predictability when selecting propulsion architectures for route networks.
Engine Type:
Airline procurement teams prioritize bypass ratio and thermal efficiency metrics when evaluating propulsion systems for fleet renewal programs.
- Turbofan:High-bypass architectures dominate narrowbody and widebody commercial platforms, achieving propulsive efficiency above fifty percent through fan diameters exceeding ten feet. Southwest Airlines and Ryanair concentrate turbofan orders in single-aisle renewal cycles, driven by ICAO Annex 16 Volume III fuel-burn compliance deadlines.
- Turboprop:Gas turbine configurations with power turbines driving propellers retain structural relevance in regional connectivity markets where runway length constraints exclude jet operations. Southeast Asian and sub-Saharan African carriers source turboprop engines for short-haul routes where operating economics favor lower cruise speeds and reduced fuel burn over block time optimization.
- Turbojet:Pure jet propulsion without bypass airflow serves specialized military and supersonic applications where simplicity outweighs efficiency penalties.
- Ramjet:Air-breathing supersonic combustion engines operate exclusively in defense and experimental aircraft programs requiring sustained high-Mach flight regimes.
Volume sits with turbofan architectures; growth tilts toward turboprop configurations in emerging regional markets.
Application:
Route network density and payload-distance requirements determine engine selection across operational categories.
- Commercial Aviation:Scheduled passenger service generates the dominant share of engine flight hours and aftermarket revenue. US-based carriers anchor demand through Boeing final assembly sourcing in Washington and South Carolina, with fleet renewal programs accelerating procurement timelines at low-cost operators.
- Cargo Transport:Dedicated freighter operations prioritize engine durability and time-on-wing metrics over passenger comfort considerations. Express logistics operators specify derated thrust configurations to extend overhaul intervals on high-cycle domestic networks.
- Private Jets:Business aviation platforms demand compact high-thrust engines with reduced noise signatures for airport access flexibility.
- Military Aviation:Defense applications require combat-rated engines with augmented thrust modes and foreign object damage tolerance for austere field operations.
Commercial aviation commands installed base scale; cargo transport exhibits the steepest expansion trajectory as e-commerce logistics reshape air freight demand.
Component:
Supplier margins concentrate in hot-section manufacturing where superalloy casting complexity creates qualification barriers.
- Turbine:Single-crystal superalloy blades and thermal barrier coating systems determine engine performance limits and maintenance intervals. Precision casting capacity clusters in specialized foundries, creating bottleneck risk for OEMs dependent on third-party sourcing of rotating components.
- Compressor:Multi-stage axial compressors achieve pressure ratios exceeding forty through advanced aerodynamic profiles and variable stator vane mechanisms. Additive manufacturing adoption at Delta TechOps and Lufthansa Technik is compressing repair lead times for legacy compressor vanes through powder-bed fusion processes.
- Fan:Large-diameter bypass fans generate the majority of propulsive thrust on modern architectures, with composite blade technology enabling weight reduction and damage tolerance improvements.
- Exhaust:Mixer and nozzle assemblies manage thrust vectoring and noise suppression requirements across variable flight regimes.
Turbine components anchor aftermarket revenue capture; compressor segments gain share fastest through MRO technology adoption.
End User:
Procurement authority and financing structures differentiate buyer categories across the value chain.
- Airlines:Operating lessors and flag carriers negotiate power-by-the-hour contracts that consolidate maintenance spend decisions at fleet management offices. AerCap and SMBC Aviation Capital bundle engine coverage into lease rates, channeling aftermarket revenue toward OEM-affiliated service networks.
- Aircraft Manufacturers:Boeing anchors OEM sourcing decisions through final assembly line concentration in the United States, with engine selection locked at airframe program launch. Airframe-engine integration timelines span years, creating captive demand for certified propulsion partners.
- Charter Services:Fractional ownership and ad-hoc operators prioritize engine availability and rapid turnaround over long-term cost optimization.
- Defense Contractors:Military procurement programs operate through separate certification pathways with classified performance requirements and sovereign supply chain mandates.
Airlines control flight hour generation; aircraft manufacturers determine platform-level engine specification lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Everett anchors global turbofan assembly activity through Boeing's Washington final assembly lines, while Charleston complements widebody engine integration. FAA Part 33 certification pathways synchronize with EASA CS-E requirements, creating dual-jurisdiction approval corridors that shape procurement geography.
United States
Southwest Airlines and United Airlines fleet renewal programs concentrate turbofan demand in the single-aisle replacement cycle. FAA emissions standards under ICAO Annex 16 Volume III tighten fuel-burn certification requirements for new engine architectures. Washington state's Puget Sound corridor hosts precision casting foundries supplying superalloy turbine blades to GE Aerospace and Pratt & Whitney assembly operations.
China
COMAC C919 fleet expansion drives indigenous engine development through the CJ-1000A certification pathway at CAAC. The country's national aviation regulator advances domestic propulsion system approval timelines parallel to Western standards. Shanghai's Yangtze River Delta manufacturing cluster integrates aero-engine supply chains with COMAC final assembly operations.
United Kingdom
Rolls-Royce superfan development programs anchor next-generation long-haul propulsion research. EU Green Deal aviation decarbonization targets accelerate combustor redesign investments for sustainable aviation fuel compatibility. Derby's East Midlands engineering corridor concentrates turbine blade casting capacity and thermal barrier coating research facilities.
Germany
Lufthansa Technik MRO adoption of additive manufacturing compresses repair lead times for legacy engine components. EASA CS-E harmonization gaps with FAA test sequences force redundant validation campaigns for global market entry. Munich's Bavarian aerospace cluster hosts MTU Aero Engines hot-section manufacturing and powder-bed fusion technology centers.
Japan
IHI Corporation and Kawasaki Heavy Industries supply precision-forged rotating components to global engine OEMs. METI industrial policy supports superalloy joining process research addressing generational workforce gaps in specialized welding expertise. Nagoya's Chubu region integrates turbine disk forging capacity with aerospace material science research institutes.
Commercial Aircraft Gas Turbine Engine Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and aftermarket capture depth. The market consolidates around three OEMs controlling widebody and narrowbody platform approvals, with tier-one suppliers capturing rotating component economics. Strategic archetypes include vertically integrated engine OEMs, specialized hot-section component foundries, and MRO service networks bundling power-by-the-hour contracts. Dominant competitive moves span strategic partnerships for dual-jurisdiction certification and capacity expansion in precision casting for single-crystal turbine blades.
Within the integrated OEM tier, GE Aerospace, Pratt & Whitney, and Rolls-Royce occupy positions defined by core architecture specialization and materials science capabilities. GE Aerospace exemplifies vertical integration across compressor and turbine stages, while Pratt & Whitney represents geared turbofan technology differentiation. Rolls-Royce anchors the superfan development vector for next-generation long-haul platforms. CFM International and Safran Aircraft Engines sit within the joint-venture archetype, combining OEM scale with national supply chain access. MTU Aero Engines and Honeywell Aerospace exemplify the tier-one supplier position, capturing component-level margins without full engine system certification burden.
| Leading Market Players |
|---|
| GE Aerospace |
| Pratt & Whitney |
| Rolls-Royce |
| CFM International |
| Safran Aircraft Engines |
| MTU Aero Engines |
| Honeywell Aerospace |
| IHI Corporation |
| Kawasaki Heavy Industries |
| Others |
Supply Flow & Price Mechanics
Engine OEM procurement concentration at Boeing and Airbus airframe programs locks pricing power with vertically integrated manufacturers like GE Aerospace and Rolls-Royce. Power-by-the-hour contracts dominate commercial aviation, bundling maintenance spend into lease rates and shifting price negotiation leverage toward OEM-affiliated service networks.
Pricing Analysis
Value-based pricing anchored to flight-hour throughput and time-on-wing performance metrics governs commercial turbofan procurement. Price differentiation rests on certification tier—FAA Part 33 and EASA CS-E dual-jurisdiction approvals command premium positioning over single-certification architectures—and thermal efficiency ratings under ICAO Annex 16 Volume III standards. Cost compression in the regional turboprop segment is intensifying because sustainable aviation fuel compatibility investments are diverting R&D budgets from performance optimization. Low-cost carriers exhibit the highest price sensitivity, prioritizing derated thrust configurations and extended overhaul intervals over maximum efficiency ratings.
Supply Chain Analysis
Single-source vulnerability sits with precision casting foundries in the United States, United Kingdom, and Japan supplying single-crystal superalloy turbine blades. Raw material dependencies center on titanium sponge from Russia and Kazakhstan, nickel alloys from Canada and Australia, and cobalt from the Democratic Republic of Congo. Tariff exposure on forged rotating components creates margin volatility for tier-one suppliers like MTU Aero Engines and IHI Corporation. Distribution runs through OEM captive service networks and independent MRO facilities at Delta TechOps and Lufthansa Technik.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as FAA-EASA harmonization gaps in certification test sequences force redundant validation campaigns that weaker capitalized suppliers cannot absorb.
For Market Incumbents: Acquire precision casting capacity in the East Midlands and Puget Sound corridors to secure single-crystal turbine blade supply against generational workforce gaps in specialized welding expertise. Defend margin position through backward integration into thermal barrier coating application and powder-bed fusion repair technology for legacy fleet MRO capture. For New Entrants and Emerging Players: The price-point gap between premium widebody superfan architectures and mature narrowbody workhorse designs creates entry space for regional turboprop specialists serving Southeast Asian runway-constrained markets. Target COMAC C919 fleet expansion through CAAC indigenous certification partnerships as the most penetrable geography. Pursue sustainable aviation fuel compatibility certification as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors tier-one component suppliers with captive superalloy forging relationships and established EASA CS-E approval pathways. Long-term viability hinges on aftermarket service network density and power-by-the-hour contract backlogs. Watch CAAC CJ-1000A certification timeline acceleration as the inflection signal indicating competitive displacement risk in China's narrowbody demand market.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Casting Capacity Expansion | Secures single-crystal turbine blade supply against foundry bottlenecks in Derby and Nagoya clusters. |
| Sustainable Aviation Fuel Certification | Positions OEMs for EU Green Deal compliance ahead of ICAO CORSIA enforcement timelines. |
| Dual-Jurisdiction Certification Investment | Reduces redundant FAA-EASA test campaigns and accelerates time-to-market for new architectures. |
| Additive Manufacturing Technology Adoption | Compresses legacy component repair lead times at Lufthansa Technik and Delta TechOps facilities. |
| Power-by-the-Hour Contract Bundling | Channels aftermarket revenue toward OEM-affiliated networks and displaces independent MRO access. |
Methodological Framework
Multi-period observation of fleet renewal cycles, certification pathway timelines, and superalloy input cost movements anchored the trend analysis, supplemented by interviews with engine program directors at GE Aerospace and Pratt & Whitney, MRO operations heads at Lufthansa Technik, fleet procurement managers at Southwest Airlines and Ryanair, and precision casting foundry executives in Washington state and Derby. Secondary validation drew from FAA type certificate databases, EASA CS-E certification records, ICAO Annex 16 compliance filings, and SEC 10-K disclosures from listed aerospace suppliers. Bottom-up segment sizing triangulated against top-down OEM production forecasts.
Input-output matrices modeled turbofan and turboprop demand across the projection horizon by engine type, application category, component segment, and end-user procurement structure. Growth trajectories incorporated airframe delivery schedules, retirement age distributions for installed base replacement, and sustainable aviation fuel compatibility investment cycles. CAGRs were derived from segment-level volume projections and value-per-unit assumptions calibrated to OEM pricing disclosures.
Inputs from regulatory filing databases and OEM production announcements were available through the study window; gaps in CAAC CJ-1000A development timeline transparency introduce uncertainty bands around China market share projections. Forecasts reflect assumptions regarding fleet renewal acceleration at low-cost carriers and ICAO emissions standard enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Global Aircraft Engine Fuel Systems Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
General Aviation Engines Market
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market
Aircraft Engine Systems and Services
Aircraft Engine Nacelle Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market