
 Aircraft Lubricant Market | 2026-2036
Aircraft Lubricant Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Lubricant Market Analysis
Consolidation among full-service airlines and the rise of low-cost carriers is repositioning procurement power toward larger fleet operators with centralized lubricant contracts. Shell plc leverages its aviation division's global blending network to sustain long-term supply agreements with major carriers. Exxon Mobil Corporation anchors its position through backward integration into base oil refining and additive formulation.
Aircraft lubricants are formulated synthetic or mineral-based fluids engineered to operate across temperature extremes from minus 54 degrees Celsius to above 200 degrees Celsius, delivering wear protection, thermal stability, and corrosion inhibition to turbine engines, hydraulic systems, and airframe components. Engine oils dominate product type revenue due to high consumption rates tied to flight cycles and oil-change intervals. MRO Services represents the fastest-growing application segment as aging fleets extend operational lifespans through heavy maintenance visits.
FAA regulations under 14 CFR Part 43 govern lubricant approval and change intervals for US-registered aircraft, while SAE International standards define performance benchmarks that shape OEM qualification requirements. The EPA monitors waste lubricant disposal under RCRA hazardous waste provisions, influencing reformulation toward longer-drain and lower-toxicity chemistries. Stakeholders must track evolving OEM specifications and regulatory pressure on per- and polyfluoroalkyl substance content in specialty lubricant formulations.
Market Dynamics
The aircraft lubricant sector is experiencing a structural squeeze between tightening military specifications and commercial fleet consolidation, with SAE AS5780 and MIL-PRF-23699 revisions forcing reformulation cycles that compress product lifecycles and concentrate supplier qualification power.
Growth Catalysts
- Military Aviation Procurement:Defense fleet expansion programs in the United States and allied nations are extending heavy maintenance schedules, driving recurring lubricant consumption for turbine engine overhauls and hydraulic system servicing.
- Extended-Drain Formulations:Advanced synthetic base stocks and ashless additive packages are enabling longer oil-change intervals, creating value propositions that align with airline cost-reduction targets while maintaining SAE performance benchmarks.
- Aging Fleet Demographics:Commercial aircraft operating beyond original design lifespans require intensified MRO activity, particularly in North American and European corridors where mature fleets dominate airspace.
Market Restraints
- Specialty Additive Concentration:Supply of high-performance anti-wear and extreme-pressure additives remains concentrated among a limited set of chemical producers, exposing formulators to input volatility and qualification delays.
- PFAS Regulatory Pressure:The EPA's scrutiny of per- and polyfluoroalkyl substances under RCRA hazardous waste provisions is forcing premature phase-out of fluorinated lubricant chemistries before fully validated alternatives reach scale.
- Base Oil Refining Capacity:Group III and Group IV synthetic base oil production is geographically concentrated in the US Gulf Coast and select Asian refining hubs, limiting supply flexibility for regional blenders.
Strategic Opportunities
- Urban Air Mobility:Electric-vertical-takeoff-and-landing aircraft developers in the United States and Germany are specifying novel thermal management fluids and lightweight greases for electric motor bearings and reduction gearboxes.
- Sustainable Aviation Fuel Alignment:Lubricant formulators can capture carbon-intensity reduction credits by aligning product portfolios with EU Green Deal sustainability disclosure requirements and airline ESG procurement mandates.
- Digital Condition Monitoring:Integration of real-time oil analysis sensors with predictive maintenance platforms creates aftermarket service attachment opportunities for lubricant suppliers with diagnostic capabilities.
Industry Challenges
- OEM Qualification Timelines:Approval cycles for new lubricant formulations under FAA 14 CFR Part 43 and equivalent EASA certification pathways extend 18-36 months, delaying revenue recognition for R&D investments.
- Tribology Expertise Scarcity:The specialized knowledge required for high-temperature bearing lubrication and aviation grease rheology is retiring from the workforce faster than universities and technical institutes can replenish pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Lubricant Market |
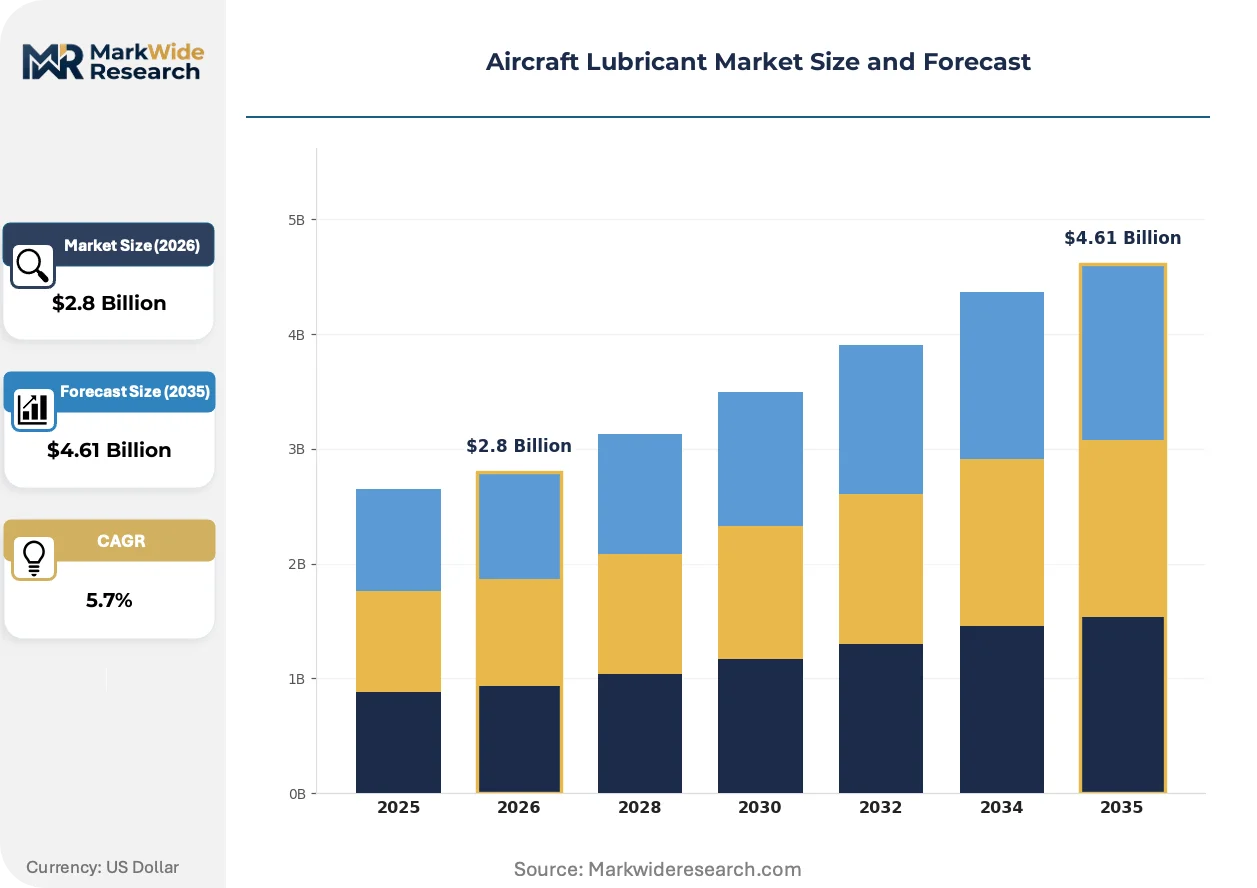
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Fluids, Engine Oils, Greases, Specialty Lubricants Application: Commercial Aviation, Military Aviation, General Aviation, MRO Services End User: Airlines, Aircraft Manufacturers, Maintenance Providers, Cargo Operators Distribution Channel: Direct Sales, Authorized Distributors, Online Retailers, Service Centers |
| Companies Covered | Shell plc, Exxon Mobil Corporation, BP plc, TotalEnergies SE, Chevron Corporation, Eastman Chemical Company, LANXESS Corporation, The Chemours Company, NYCO S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Lubricant Market Emerging Trajectories
Synthetic chemistry advances and regulatory toxicity restrictions are converging to redefine performance benchmarks, while digitalization of maintenance operations is altering how lubricant value is measured and procured across aviation supply chains.
Ionic liquid lubricant formulations are integrating into next-generation turbine engine oils to deliver superior thermal-oxidative stability at temperatures exceeding 220 degrees Celsius. Major engine OEMs are qualifying these chemistries for narrowbody and widebody platforms entering service this decade. The technology is integrating high-performance tribology with extended-drain service intervals, compressing the total cost of ownership calculus for fleet operators.
REACH restrictions on persistent organic pollutants and the EU F-Gas Regulation are compelling European formulators to eliminate certain chlorinated and fluorinated thickeners from aviation grease portfolios. The industrial consequence is accelerated R&D spending on polyurea and complex soap-thickened alternatives that maintain shear stability across temperature extremes. Military and commercial segments operating within European Economic Area jurisdictions are responding by dual-qualifying products that satisfy both legacy MIL-SPEC and emerging EU chemical safety registrations.
Airline procurement departments are consolidating lubricant purchasing into multi-year framework agreements with performance-based pricing mechanisms tied to fleet reliability metrics. The traditional spot-buy and distributor-mediated channel is yielding to direct supplier relationships managed through integrated supply chain platforms. This behavioral shift is most visible among US-based network carriers and European low-cost operators with centralized technical procurement functions.
Aircraft Lubricant Market Segmentation
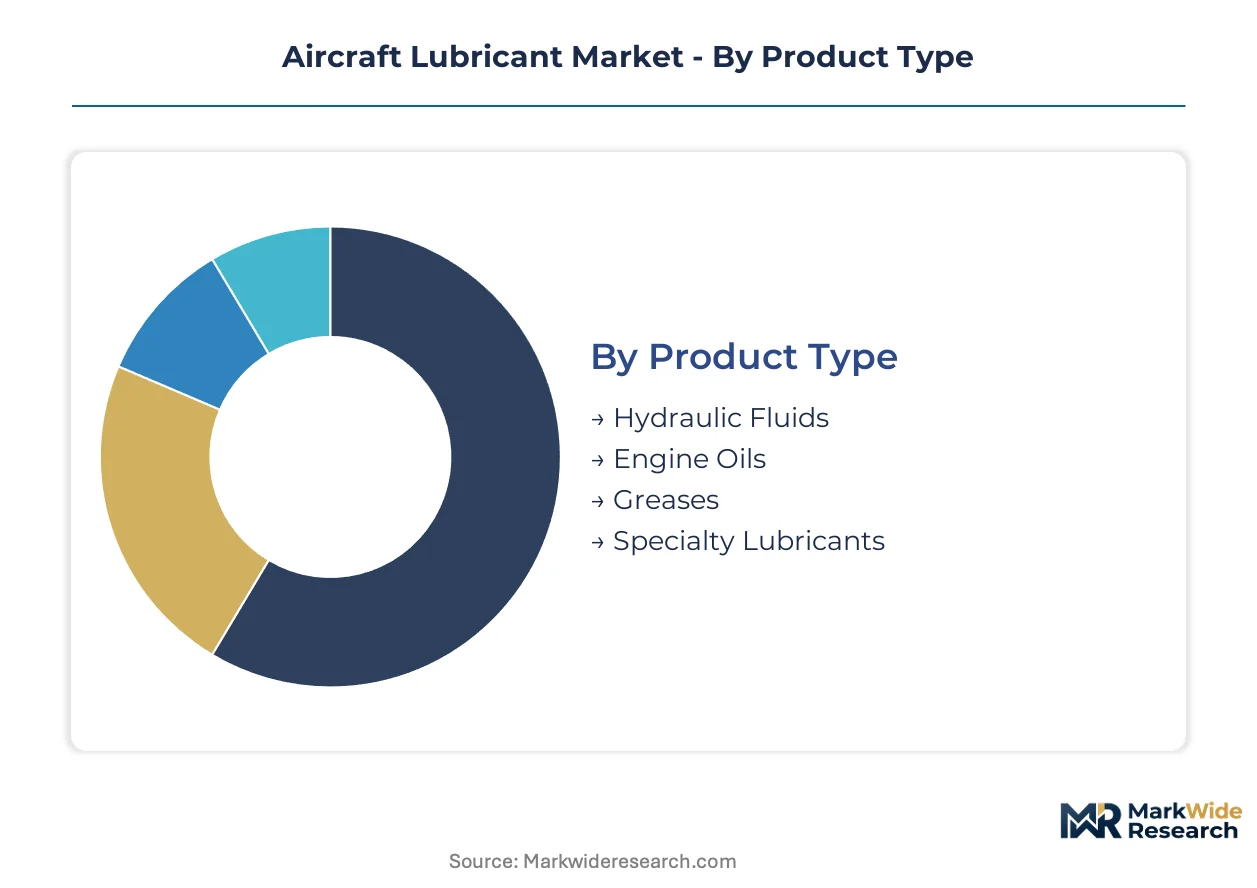
Aircraft lubricant procurement patterns diverge sharply across operational contexts, with military specifications demanding MIL-PRF-23699 compliance while commercial fleets prioritize extended-drain economics. Understanding these segment boundaries clarifies where formulation investments concentrate and which qualification pathways dominate supplier R&D allocation.
Product Type:
Engine oils command the largest volume position, yet specialty lubricants extract the highest per-unit margins through narrow qualification windows and limited approved suppliers.
- Engine Oils:Synthetic turbine oils formulated to SAE AS5780 and MIL-PRF-23699 specifications deliver thermal-oxidative stability across minus 54 to above 200 degrees Celsius operating ranges. Demand concentrates in United States defense corridors and European commercial MRO hubs where flight-cycle intensity drives consumption. Fleet operators prioritize extended-drain formulations to reduce turnaround costs during heavy maintenance visits.
- Hydraulic Fluids:Fire-resistant phosphate ester and synthetic hydrocarbon formulations power flight control actuators and landing gear systems under extreme pressure differentials. Procurement clusters with Boeing and Airbus final assembly lines in Washington State and Toulouse, where OEM fill specifications govern airline initial provisioning contracts. FAA 14 CFR Part 43 compliance timelines stretch supplier qualification cycles.
- Greases:Complex soap-thickened and polyurea-based formulations lubricate high-temperature bearings and airframe joints. REACH restrictions on chlorinated thickeners are accelerating reformulation cycles among European blenders.
- Specialty Lubricants:Ionic liquid and perfluoropolyether chemistries serve niche applications including space-rated mechanisms and extreme-temperature seals. Military aerospace procurement in the United States sustains limited production runs.
Mature deployment sits with Engine Oils. Newer deployment is concentrated in Specialty Lubricants.
Application:
Commercial aviation generates the baseline volume foundation, while MRO Services is expanding most quickly as aging fleets extend operational lifespans through intensified maintenance programs.
- MRO Services:Third-party and airline-affiliated maintenance facilities consume lubricants through engine overhauls, hydraulic system flushes, and landing gear servicing. Activity concentrates in Singapore, Dubai, and the United States Gulf Coast corridors where widebody fleets stage heavy maintenance visits. Extended-drain synthetic formulations reduce labor hours and aircraft downtime.
- Commercial Aviation:Scheduled airline operations drive recurring consumption through flight-cycle-based oil changes and routine line maintenance. Network carriers in the United States and low-cost operators in Europe are consolidating procurement into multi-year framework agreements with integrated supply chain platforms.
- Military Aviation:Defense fleet expansion programs in the United States and allied nations extend heavy maintenance schedules for turbine engine overhauls. MIL-PRF-23699 specifications constrain approved supplier lists.
- General Aviation:Piston engine oils and mineral-based hydraulic fluids serve private and training aircraft fleets. Demand fragments across thousands of small operators with spot-buy purchasing patterns.
Volume leadership remains with Commercial Aviation. Steepest expansion trajectory belongs to MRO Services.
End User:
Airlines wield consolidated procurement power through centralized technical purchasing functions, while Maintenance Providers capture aftermarket service attachment opportunities.
- Airlines:Full-service and low-cost carriers negotiate multi-year lubricant supply agreements tied to fleet reliability metrics and carbon-intensity reduction targets. United States network carriers and European budget operators have eliminated distributor intermediaries in favor of direct supplier relationships.
- Maintenance Providers:Independent MRO facilities and OEM service networks specify lubricants during engine overhauls and component repairs. Singapore and Dubai-based providers are integrating digital condition monitoring to capture predictive maintenance contracts.
- Aircraft Manufacturers:Boeing in Washington State and Airbus in Toulouse specify initial fill lubricants for new aircraft deliveries, locking in airline provisioning contracts through OEM-approved product lists.
- Cargo Operators:Integrated freight carriers and express delivery fleets operate high-utilization schedules that accelerate oil degradation and shorten change intervals.
Contract concentration sits with Airlines. Technical specification authority rests with Aircraft Manufacturers.
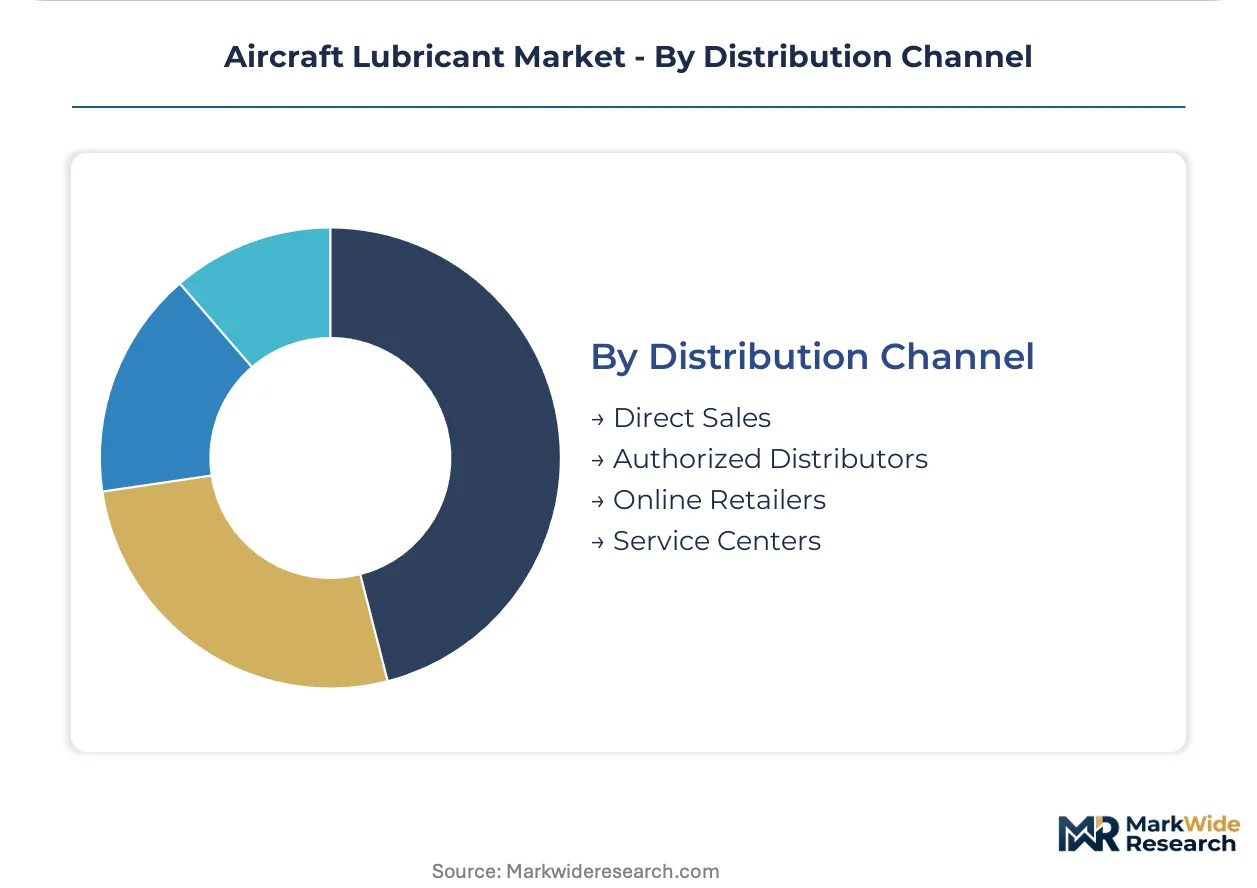
Distribution Channel:
Direct sales capture the premium tier through long-term agreements, while authorized distributors retain relevance for fragmented general aviation demand.
- Direct Sales:Lubricant suppliers negotiate framework agreements directly with airline procurement departments and defense procurement agencies. Shell plc and Exxon Mobil Corporation leverage global blending networks to sustain these relationships.
- Authorized Distributors:Regional stockists serve maintenance providers and general aviation operators with smaller volume requirements and irregular purchasing patterns.
- Service Centers:OEM-affiliated and independent MRO facilities procure lubricants as part of integrated maintenance packages, capturing aftermarket value through technical service bundling.
- Online Retailers:Digital platforms address small-volume general aviation and piston engine oil demand with limited penetration into turbine lubricant categories.
Volume scale concentrates in Direct Sales. Channel fragmentation persists in Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement corridors in the United States concentrate military aviation lubricant demand, while commercial MRO clusters in Germany and Singapore anchor aftermarket consumption. Fleet operator consolidation is redirecting procurement power toward centralized technical purchasing functions in select national markets.
United States
Defense fleet expansion and heavy turbine engine overhaul schedules drive recurring lubricant consumption for MIL-PRF-23699 compliant formulations. FAA regulations under 14 CFR Part 43 govern approval timelines and change intervals for US-registered aircraft. The Gulf Coast corridor hosts concentrated blending capacity serving both domestic carriers and export markets.
Germany
REACH restrictions on persistent organic pollutants and the EU F-Gas Regulation are compelling accelerated reformulation of aviation greases toward polyurea-thickened alternatives. ECHA chemical safety registrations shape dual-qualification requirements for products serving both military and commercial segments. The Hamburg and Munich industrial clusters house specialized additive research facilities.
Singapore
Third-party MRO facilities consume lubricants through widebody engine overhauls and hydraulic system servicing for fleets staging heavy maintenance visits. The country's national aviation regulator enforces alignment with EASA certification pathways for lubricant approvals. Changi Aviation Park anchors regional distribution for Asia-Pacific carrier procurement.
France
OEM final assembly specifications from Toulouse govern initial fill lubricant contracts for new aircraft deliveries. ANSM chemical safety oversight intersects with EU Green Deal sustainability disclosure requirements for airline ESG procurement. The Occitanie region concentrates specialized grease manufacturing for high-temperature bearing applications.
United Kingdom
Network carrier consolidation into multi-year framework agreements is eliminating distributor intermediaries in favor of direct supplier relationships. The Civil Aviation Authority maintains lubricant approval pathways parallel to EASA standards post-regulatory transition. London Heathrow and Manchester maintenance corridors drive line maintenance consumption for short-haul fleets.
Aircraft Lubricant Market Vendor Landscape
United States producers anchor the premium synthetic tier; European specialists hold formulation expertise for REACH-compliant alternatives. Supplier qualification power concentrates among blenders with backward integration into base oil refining and captive additive supply. Three archetypes dominate: integrated majors with global blending networks, regional specialists with MIL-SPEC approvals, and chemical producers supplying high-performance additive packages. Competitive moves center on capacity expansion in synthetic base oil production and strategic partnerships with engine OEMs for co-development qualification.
Within the integrated major tier, Shell plc and Exxon Mobil Corporation exemplify global supply architectures with sustained long-term agreements. BP plc occupies a position bridging European regulatory compliance with defense procurement corridors. These entities represent the scale-driven end where centralized airline purchasing functions concentrate contract awards.
| Leading Market Players |
|---|
| Shell plc |
| Exxon Mobil Corporation |
| BP plc |
| TotalEnergies SE |
| Chevron Corporation |
| Eastman Chemical Company |
| LANXESS Corporation |
| The Chemours Company |
| NYCO S.A. |
| Others |
Supply Flow & Price Mechanics
Backward integration into base oil refining and additive formulation anchors supplier pricing power in the aircraft lubricant sector, with Exxon Mobil Corporation's captive Group IV synthetic production and Shell plc's global blending network creating tiered cost positions that resist spot-market volatility. This upstream control concentrates margin capture among integrated majors while forcing non-integrated blenders into distributor-mediated channels with compressed economics.
Pricing Analysis
Volume leadership in engine oils extracts thin margins through flight-cycle-driven consumption, while specialty lubricants command premium positioning via narrow MIL-PRF-23699 qualification windows and limited approved supplier lists. Three-tier pricing structure across OEM-qualified premium, SAE-compliant standard, and spot-market economy levels differentiates by certification grade and volume commitment. Pricing pressure stems from airline procurement consolidation into multi-year framework agreements with performance-based pricing tied to fleet reliability metrics. Low-cost carriers exhibit highest price sensitivity through centralized technical purchasing functions, whereas military aviation procurement shows lowest sensitivity due to specification-locked supplier lists.
Supply Chain Analysis
Domestic-content mandates in United States defense procurement reshape sourcing patterns, requiring MIL-PRF-23699 qualified production within FAA-jurisdictional facilities for military aviation contracts. Geographic supply concentration centers on the United States Gulf Coast for Group III and Group IV synthetic base oils, Germany for REACH-compliant additive research, and Singapore for Asia-Pacific MRO distribution. Raw material dependencies draw from phosphate ester fire-resistant chemistries, ashless anti-wear additive packages, and polyurea grease thickeners. Single-source vulnerability persists in high-performance anti-wear additive concentration among limited chemical producers. Distribution runs through direct sales to airline procurement departments and defense agencies, with authorized distributors serving fragmented general aviation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft lubricant market reads as a cost-of-compliance story where SAE AS5780 and MIL-PRF-23699 specification revisions erect barrier-to-entry moats that protect qualified incumbents from commodity competition. Regulatory approval timelines stretching 18-36 months under FAA 14 CFR Part 43 and EASA certification pathways concentrate supplier qualification power among blenders with established OEM relationships.
For Market Incumbents: Deepen backward integration into synthetic base oil production and captive additive supply to defend margin position against formulation cost volatility. Expand blending capacity in Singapore and Dubai MRO corridors to capture aftermarket service attachment opportunities. Invest in ionic liquid R&D qualification with engine OEMs to preempt next-generation turbine oil specifications. For New Entrants and Emerging Players: Ionic liquid thermal management fluids for electric-vertical-takeoff-and-landing aircraft represent a technology-first wedge into an underpenetrated urban air mobility segment with unestablished supplier relationships. Target German and United States eVTOL developers with novel lightweight greases for electric motor bearings. Pursue co-development partnerships with battery-electric aircraft OEMs before qualification pathways crystallize. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated majors seeking MIL-SPEC qualification portfolios and regional blending assets. Long-term viability favors blenders with demonstrated OEM co-development relationships and backward integration into base oil supply. Watch for PFAS regulatory acceleration as an inflection indicator forcing premature phase-out of fluorinated chemistries and consolidation toward REACH-compliant formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Additional synthetic base oil refining on the US Gulf Coast reduces import dependency for regional blenders. |
| Backward Integration | In-house production of ashless additive packages insulates formulators from supply concentration volatility. |
| Long-term Supply Agreement | Multi-year framework contracts with United States network carriers lock in volume against spot-market erosion. |
| Joint Venture | Co-development partnerships with engine OEMs accelerate ionic liquid qualification timelines for next-generation oils. |
| Green Manufacturing Transition | PFAS-free formulation portfolios align with EPA RCRA hazardous waste provisions and EU REACH restrictions. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with lubricant formulation chemists, airline procurement directors, MRO facility managers, and defense procurement officers. FAA 14 CFR Part 43 documentation, EASA certification databases, SAE International standards repositories, and MIL-SPEC qualification records provided regulatory benchmarking. Bottom-up volume estimates from fleet operator consumption patterns converged with top-down value projections from supplier revenue disclosures.
Granularity-level modeling disaggregated demand across product type, application, end user, and distribution channel dimensions, with additional segmentation by military versus commercial specification tiers. CAGRs derived from trend extrapolation of flight-cycle intensity, fleet age demographics, and MRO visit frequency across the analysis window. Industry-specific forecast inputs incorporated OEM delivery schedules, defense procurement timelines, and REACH regulatory phase-out calendars.
Several conditions sit outside the modeled scope, including unannounced PFAS regulatory acceleration, sudden military conflict-driven fleet activation, and breakthrough solid-state lubricant technologies displacing liquid formulations. Forecasts reflect documented assumptions regarding specification stability and qualification pathway continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
America Aircraft Engines Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
General Aviation Engines Market
Aircraft Engine Systems and Services
Angle of Attack Sensor Market
Aircraft Engine Systems and Services
Aero Engine Coatings Market
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Gas Turbine Service Market
Aircraft Engine Systems and Services
Helicopter Engine Market