
 Aeroengine Accessory Drive Train Market | 2026-2036
Aeroengine Accessory Drive Train Market Size, Share, and Industry Trends Forecast 2026-2036
Aeroengine Accessory Drive Train Market Intelligence
AS9100 certification for quality management systems is redrawing the supplier landscape, mandating stringent process controls and complete traceability for all components. Safran Aircraft Engines leverages its extensive portfolio of gearbox technologies to serve both civil and military programs. Collins Aerospace differentiates through its integrated systems approach, combining drive trains with engine controls and power generation. Rolls-Royce sustains its market position through deep-rooted relationships with major airframers.
An aeroengine accessory drive train is a system of gears, shafts, and couplings that transmits power from the engine core to vital aircraft accessories. These systems operate at extreme rotational speeds and require specialized high-strength metal alloys for gearboxes and bearings to ensure reliability. Gearboxes represent the most complex and highest value component type within the system. While mechanical technology remains dominant, hybrid and electrical systems are gaining share, particularly for new platforms in commercial aviation and business jet applications.
Regulatory oversight from bodies like the FAA in the United States, EASA in Europe, and the CAAC in China governs the entire lifecycle through type certification and airworthiness directives. These agencies mandate rigorous testing and validation to ensure flight safety and system reliability under all operating conditions. The central challenge for designers and manufacturers is managing the increasing power-offtake requirements for new aircraft systems while simultaneously pursuing aggressive weight reduction targets.
Market Dynamics
The central dynamic shaping the aeroengine accessory drive train market is the architectural tension between rising electrical power-offtake demands for modern avionics and the unyielding mandate for weight reduction to improve overall aircraft fuel efficiency.
Growth Catalysts
- Next-Generation Aircraft Demand:Fleet modernization programs for narrow-body aircraft in the commercial aviation sector create a direct and sustained demand pull for advanced, lightweight accessory drive train systems.
- Material Science Advancements:The development and qualification of new high-strength, low-weight metal alloys and composite materials for gearboxes and housings enable designs that can handle higher rotational speeds and thermal loads.
- AS9100 Certification Mandates:Adherence to the AS9100 quality management standard is becoming a prerequisite for supplier qualification, driving process improvements and enhancing component reliability across the supply base.
Market Restraints
- High-Cost Specialty Materials:The market's reliance on exotic materials like titanium and nickel-based superalloys for gears and bearings creates high input costs and exposes manufacturers to price volatility in commodity markets.
- Thermal Management Limits:Increasing power density within gearboxes generates significant heat, posing a fundamental engineering restraint that requires complex and heavy cooling solutions, which counteracts weight-reduction goals.
- Extended Certification Cycles:The stringent and lengthy type certification processes mandated by regulatory bodies like the FAA and EASA add years and significant cost to new product development, slowing innovation.
Strategic Opportunities
- Hybrid-Electric Propulsion Systems:The industry's transition towards more-electric aircraft architectures opens a significant opportunity for novel drive train designs that integrate power electronics and high-voltage electrical generation.
- Predictive Maintenance Services:Leveraging sensor data and digital twin models to offer advanced predictive maintenance and health monitoring services for gearboxes presents a new, high-margin revenue stream for MRO providers.
- Urban Air Mobility Platforms:The emerging market for electric vertical take-off and landing (eVTOL) aircraft creates a new application space for compact, high-reliability, and electrically driven accessory drive train technologies.
Industry Challenges
- Multidisciplinary Skills Gap:A shortage of engineers with combined expertise in high-speed mechanical gear systems, power electronics, and software controls complicates the development of integrated, more-electric systems.
- Capital-Intensive Testing Infrastructure:Validating drive train reliability requires massive capital investment in specialized test rigs that can simulate the extreme temperature, vibration, and altitude conditions of flight.
- Legacy System Integration:Integrating advanced electrical and hybrid drive trains into existing aircraft platforms presents significant engineering challenges related to system compatibility, power management, and airworthiness certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aeroengine Accessory Drive Train Market |
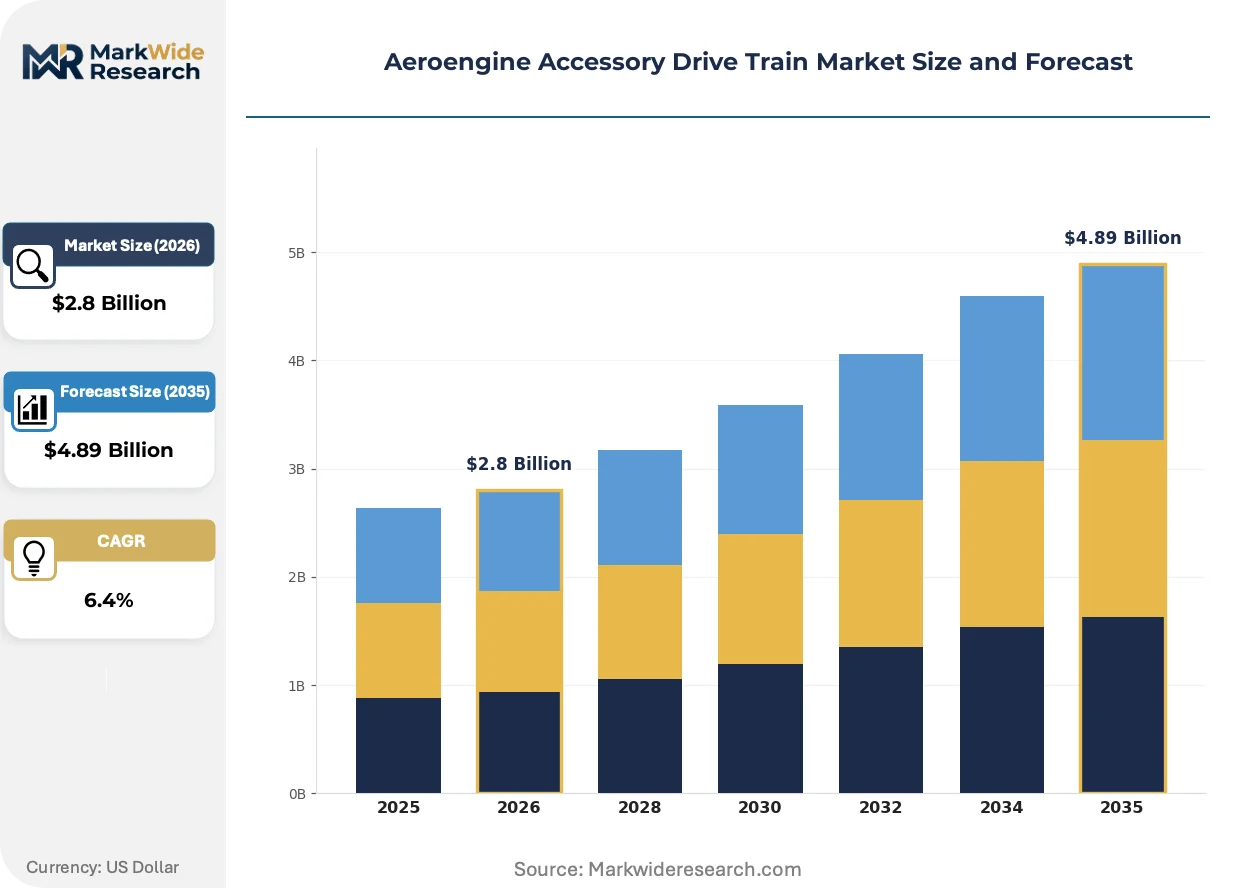
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Gearbox, Coupling, Pulleys, Bearings Technology: Mechanical, Hydraulic, Electrical, Hybrid End User: Aerospace Manufacturers, MRO Providers, OEMs, Airlines Application: Commercial Aviation, Military Aviation, Business Jets, UAVs |
| Companies Covered | Safran Aircraft Engines, GE Aviation, Collins Aerospace, Rolls-Royce, Pratt & Whitney, Honeywell Aerospace, GKN Aerospace, Liebherr-Aerospace, Moog Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aeroengine Accessory Drive Train Market Strategic Shifts & Innovations
A fundamental re-evaluation of aircraft power architecture is underway, driven by the dual objectives of electrification and enhanced operational efficiency. This shift influences everything from component material selection to the very definition of a drive train system.
Hybrid-electric gearbox architectures integrate electrical motor-generators directly within the drive train. These systems are being adopted by designers of new aircraft platforms to provide supplemental power and enable more efficient engine operation. This technology is displacing the traditional, purely mechanical power transmission for accessory systems, allowing for more flexible packaging and improved thermal management within the nacelle.
Regulatory frameworks are tightening to ensure system integrity and supply chain quality. The AS9100 standard, for instance, imposes strict requirements for process control and complete component traceability from raw material to finished part. This affects the entire supplier ecosystem, compelling smaller manufacturers to invest significantly in sophisticated quality management systems to participate in programs for airframers in the United States and Europe.
Airframers and engine OEMs are altering their sourcing strategies, moving from procuring individual components to acquiring fully integrated power transmission systems. This change disrupts the traditional model for component suppliers, creating an advantage for Tier 1 integrators capable of delivering a complete, pre-validated module. The shift is most pronounced in new commercial aircraft programs originating from aerospace clusters in France and the United States.
Aeroengine Accessory Drive Train Market Segmentation
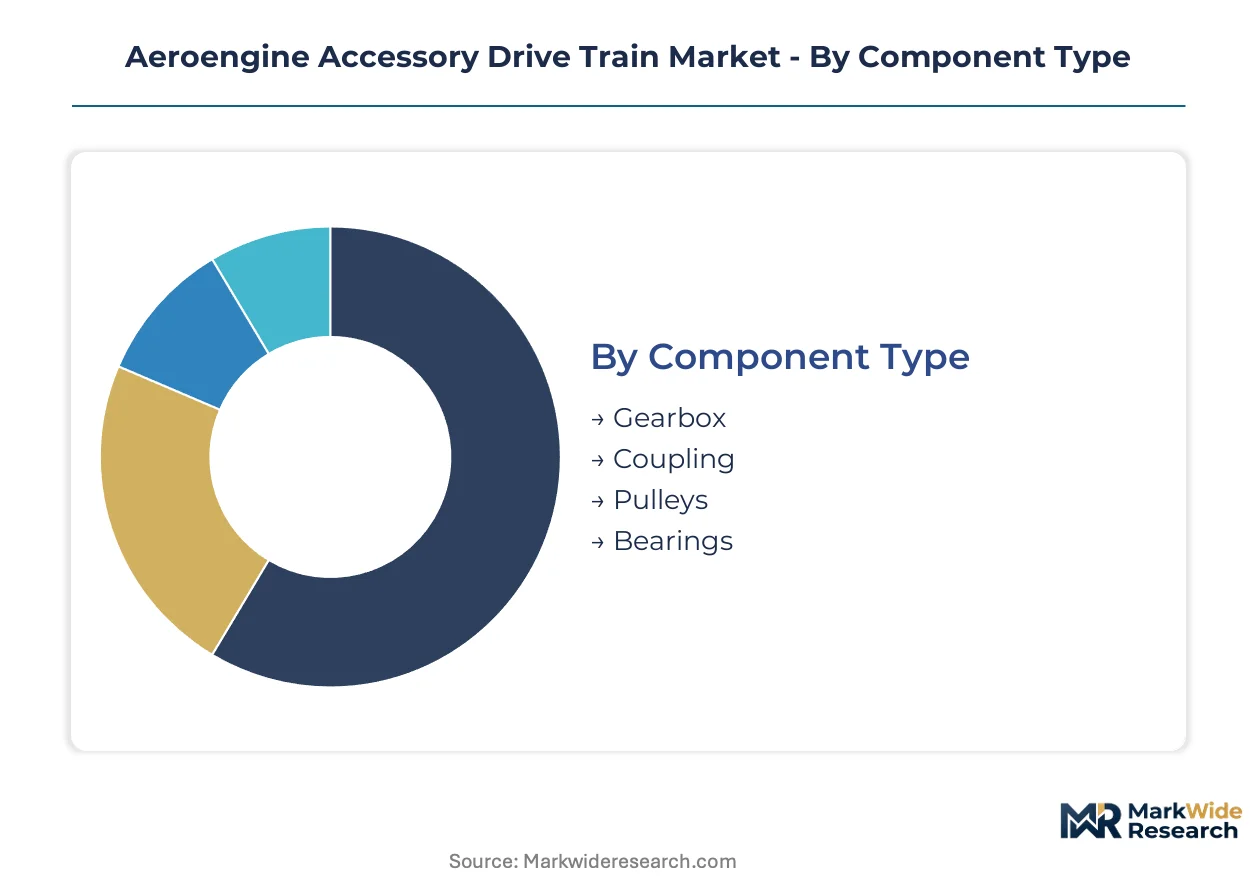
The aeroengine accessory drive train market's segmentation highlights the diverse technical requirements and operational demands across different aviation sectors. Understanding these distinct segments is crucial for manufacturers to tailor product development, optimize material selection, and navigate complex regulatory landscapes.
Component Type:
Regulatory bodies like the FAA in the United States and EASA in Europe impose stringent certification requirements that differentiate accessory drive train components based on their critical function and potential impact on flight safety.
- Gearbox:This system of gears, shafts, and casings transmits power from the engine core to various aircraft accessories. Commercial aviation and military programs demand advanced gearboxes to manage increasing power off-take requirements while simultaneously reducing overall system weight.
- Bearings:These critical components support rotating shafts, operating at extreme speeds and temperatures within the drive train. Next-generation aircraft designs in Europe and the United States require specialized high-strength bearings to ensure reliability and extend service intervals under demanding conditions.
- Coupling:These mechanical devices connect rotating shafts, accommodating misalignment and transmitting torque efficiently across the system.
- Pulleys:Used in belt-driven systems within the accessory drive train for power transmission to various auxiliary components.
Established volume favors Gearbox; emerging adoption favors advanced Bearings designed for high-speed electrical systems.
Technology:
The selection of accessory drive train technology directly correlates with the specific aircraft application and its operational demands.
- Mechanical:These traditional systems rely on gears and shafts for direct power transmission from the engine. Commercial narrow-body aircraft and military platforms in France and the United States primarily utilize mechanical drive trains due to their proven reliability and robust performance.
- Hybrid:This technology integrates mechanical power transmission with electrical motor-generators to optimize power distribution. New commercial aviation programs and urban air mobility platforms in Europe are adopting hybrid systems to improve efficiency and enable more-electric aircraft architectures.
- Hydraulic:These systems use pressurized fluid to transmit power to accessories, commonly found in older aircraft designs for specific functions.
- Electrical:This technology employs electric motors and generators for power distribution, gaining traction in smaller aircraft and future concepts.
Mechanical systems continue to underpin the market, while hybrid solutions represent the fastest-growing trajectory.
End User:
Different end-user segments engage with the market at various stages of the product lifecycle, influencing demand patterns for both new systems and aftermarket services.
- Aerospace Manufacturers:These companies build aircraft, integrating engines and their accessory systems into the final platform.
- MRO Providers:Maintenance, Repair, and Overhaul organizations service and repair existing drive train components throughout their operational life. Global MRO networks in the United States and Singapore require extensive spare parts and specialized repair capabilities for aging aircraft fleets.
- OEMs:Original Equipment Manufacturers integrate accessory drive trains into new aeroengines and aircraft platforms during the design and production phases. Major engine manufacturers like Safran and Rolls-Royce drive demand for advanced, pre-validated drive train modules for their civil and military programs.
- Airlines:Operators of commercial aircraft, requiring reliable and maintainable accessory drive trains for their fleets to ensure operational efficiency and safety.
OEMs drive initial demand for new systems, while MRO Providers ensure sustained operational readiness.
Application:
The operational requirements and regulatory environments of different aircraft applications significantly shape the design and procurement of accessory drive train systems.
- Commercial Aviation:This segment includes passenger and cargo aircraft, demanding high reliability, fuel efficiency, and extended service life from drive train components. Next-generation narrow-body aircraft programs from Airbus in France and Boeing in the United States are the primary drivers for new drive train systems.
- Military Aviation:This category encompasses fighter jets, transport aircraft, and helicopters, prioritizing performance, ruggedness, and survivability in extreme operating conditions. Defense programs in the United Kingdom and the United States require robust accessory drive trains capable of operating in challenging environments.
- Business Jets:These smaller, private aircraft require compact, efficient, and often quieter drive train solutions tailored for executive travel.
- UAVs:Unmanned Aerial Vehicles are increasingly seeking lightweight, highly integrated, and electrically driven accessory power systems for diverse missions.
Commercial Aviation remains the largest segment by volume, with UAVs showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government investments in defense modernization programs are stimulating demand for advanced aeroengine accessory drive trains across key regions. These initiatives focus on fleet upgrades and next-generation platform development. Policy frameworks from national aviation authorities ensure stringent safety and performance standards for all components.
United States
Demand for next-generation military aircraft and commercial fleet upgrades drives innovation in drive train systems. The FAA mandates rigorous type certification for all flight-critical components. Aerospace clusters in Seattle and Wichita concentrate on advanced manufacturing and system integration.
France
France's strong commercial aviation sector, particularly for narrow-body aircraft, creates sustained demand for efficient drive trains. EASA regulations enforce stringent quality and safety standards for all aerospace parts. Toulouse serves as a major European hub for aircraft assembly and component development.
United Kingdom
Military aviation programs and extensive engine MRO activities underpin the market in the United Kingdom. The UK's CAA oversees airworthiness directives for complex engine systems. Aerospace engineering firms in Derby and Bristol contribute significantly to advanced engine design.
Germany
German aerospace companies are focusing on advancements in hybrid-electric propulsion systems for future aircraft platforms. EASA certification is critical for bringing new drive train technologies to market. Munich and Hamburg host significant aerospace research and development facilities, fostering innovation.
China
China's rapid expansion of its domestic commercial aviation fleet fuels substantial demand for accessory drive trains. CAAC regulations are evolving to promote local production and ensure component quality. Xi'an and Shanghai are emerging centers for aerospace manufacturing and assembly capabilities.
Aeroengine Accessory Drive Train Market Key Industry Players
Listed leaders compete with private specialists across integrated system solutions and specialized component manufacturing. The market exhibits consolidation among top-tier integrators but remains fragmented for niche component suppliers. Strategic archetypes include full-system providers, material science innovators, and dedicated MRO specialists. Companies often engage in strategic partnerships and portfolio diversification to enhance their market reach.
On the premium-tier vector, Safran Aircraft Engines and Collins Aerospace exemplify integrated system approaches, offering comprehensive drive train solutions. Rolls-Royce occupies a position as a major engine OEM, integrating drive train modules into its broader propulsion systems. These entities anchor the market for advanced, high-value accessory drive train components, often leveraging extensive R&D capabilities.
| Leading Market Players |
|---|
| Safran Aircraft Engines |
| GE Aviation |
| Collins Aerospace |
| Rolls-Royce |
| Pratt & Whitney |
| Honeywell Aerospace |
| GKN Aerospace |
| Liebherr-Aerospace |
| Moog Inc. |
| Others |
Cost & Logistics Intelligence
Long-term contractual agreements for original equipment components lock in both supply access and price visibility for aeroengine accessory drive trains over multi-year aircraft programs. This contract structure mitigates short-term price volatility for critical flight-safety parts.
Pricing Analysis
AS9100 certification level creates the primary price differentiation for accessory drive train components, reflecting the stringent quality and traceability requirements. Pricing models are predominantly contract-based long-term offtake agreements with aerospace manufacturers. Customization level for specific aircraft platforms also influences pricing. Cost compression in new commercial aviation platforms is intensifying due to aggressive weight reduction targets. Airlines represent the most price-sensitive buyers, while military programs prioritize performance and reliability over cost.
Supply Chain Analysis
Extended lead times for specialized components characterize the accessory drive train supply chain, driven by complex manufacturing processes. Geographic supply concentration centers in aerospace clusters within France, the United States, and the United Kingdom. Raw material dependencies include high-strength metal alloys like titanium and nickel-based superalloys, alongside specialized high-speed bearings. Single-source vulnerability for highly engineered components poses a structural risk to the supply chain. Distribution runs directly from Tier 1 integrators to aeroengine OEMs and airframers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aeroengine accessory drive train market functions as a defensive moat, underpinned by stringent regulatory entrenchment from bodies like the FAA and EASA, creating high barriers to entry.
For Market Incumbents: Consolidate core technology portfolios to counter the threat of new hybrid-electric propulsion systems. Invest heavily in advanced material science R&D to meet aggressive weight reduction targets for commercial aviation. Leverage extensive OEM relationships to secure long-term contracts against emerging competition. Deepen vertical integration into specialized component manufacturing to control input costs.
For New Entrants and Emerging Players: Specialized MRO services for next-generation hybrid systems represent a service-layer gap where incumbents under-serve. Target urban air mobility platforms as a penetrable application space for compact, electrically driven systems. A go-to-market angle focusing on rapid prototyping and agile certification for niche applications can gain traction. Develop integrated power electronics solutions for more-electric aircraft architectures.
For Investors and Strategic Acquirers: Niche component manufacturers with advanced material science expertise offer attractive acquisition targets for long-term portfolio growth. The market offers stable returns over a 5-10 year window, driven by sustained aircraft demand. Watch for consolidation among Tier 1 integrators as a signal of market maturity and value creation. Companies with strong intellectual property in hybrid-electric drive train technologies are particularly valuable.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Hybrid-Electric R&D | Integrates power electronics for future aircraft platforms. |
| Expand AS9100 Certified Manufacturing | Secures supplier qualification for airframers in the United States. |
| Develop Predictive Maintenance Solutions | Creates new high-margin revenue streams for MRO providers. |
| Strategic Partnerships with eVTOL Developers | Accesses emerging urban air mobility application space. |
| Advanced Materials Qualification | Enables lighter, more durable gearboxes for commercial aviation. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, OEM technical specifications, and aerospace industry reports. Primary interviews engaged aeroengine engineers, MRO managers, procurement leads at airframers, and regulatory compliance officers. This approach ensured robust bottom-up and top-down triangulation of market data.
Component type, technology, end user, application, and regional regulatory compliance formed the segmentation dimensions modeled across the analysis window. Compound Annual Growth Rates (CAGRs) were derived through a proprietary analytical framework, considering historical trends and projected market shifts. Key forecast inputs included aircraft delivery schedules and MRO contract renewals.
Underlying assumptions cover stable regulatory frameworks and consistent aerospace investment, with deviation risk concentrated in material supply disruptions and new aircraft program delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Gas Turbine Service Market
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Aero Engine Coatings Market
Aircraft Engine Systems and Services
Aircraft Engine Nacelle Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market