
 Commercial Aircraft Engines Market | 2026-2036
Commercial Aircraft Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Engines Market Outlook
Power-by-the-hour leasing and engine pooling arrangements are narrowing the capital barrier for regional airlines seeking new-generation propulsion systems. CFM International leverages its LEAP architecture to sustain manufacturing scale across dual supply chains. Pratt & Whitney anchors its competitive stance through geared turbofan technology leadership. Rolls-Royce differentiates via long-term TotalCare service contracts that control aftermarket revenue streams.
A commercial aircraft engine is a gas turbine propulsion system that generates thrust through a core compressor-turbine assembly driving a bypass fan, typically achieving bypass ratios exceeding 10:1 on modern wide-body platforms. Its primary function is to convert chemical energy from jet fuel into mechanical work that propels fixed-wing aircraft during commercial passenger and cargo operations. Turbofan configurations dominate installed fleet value, with high-bypass designs capturing the bulk of margin pools on long-haul routes. Turboprop applications retain structural importance in regional connectivity markets where runway length and fuel efficiency constrain jet alternatives. Biofuel compatibility within Jet A-1 specifications is emerging as a critical engineering parameter as operators face escalating carbon compliance obligations.
The FAA enforces Part 33 certification standards that dictate noise, emissions, and durability thresholds for engines entering US-registered service, while the EU Green Deal and EASA's evolving CO2 standard for large aircraft shape product development priorities for European-bound equipment. Engine Alliance and GE Aerospace navigate divergent regulatory timelines as China’s CAAC and India's DGCA adopt increasingly stringent local certification protocols. Stakeholders must monitor how sustainable aviation fuel mandates in multiple jurisdictions alter engine combustion system design roadmaps and aftermarket retrofit requirements.
Market Dynamics
ICAO's Carbon Offsetting and Reduction Scheme for International Aviation is compressing engine certification timelines while forcing combustion system redesigns that favor high-bypass architectures over legacy turbofan generations.
Growth Catalysts
- Fleet renewal mandates:Southeast Asian low-cost carriers are accelerating narrow-body replacements under national emissions reduction frameworks.
- Jet A-1 biofuel compatibility:Combustor engineering now prioritizes sustainable aviation fuel tolerance as ICAO benchmarks tighten.
- Airport infrastructure expansion:India's domestic aviation sector is absorbing additional engine capacity as runway and terminal construction advances.
Market Restraints
- Superalloy supply concentration:Precision-cast turbine blade sourcing clusters in limited supplier geographies, exposing OEMs to input volatility.
- Dual certification friction:Divergent FAA Part 33 and EASA CO2 standard timelines force redundant testing protocols.
- Turboprop substitution ceiling:Regional jet engines face displacement pressure where runway constraints favor propeller systems.
Strategic Opportunities
- Power-by-the-hour penetration:Leasing structures are unlocking new-generation propulsion access for capital-constrained regional carriers.
- Aftermarket control architectures:Long-term service contracts are capturing lifetime revenue streams previously lost to third-party MRO providers.
- CAAC certification alignment:Engine platforms validated under China's evolving local protocols gain preferential access to domestic fleet procurement.
Industry Challenges
- Geared turbofan integration complexity:Maintenance networks face skill gaps in planetary gear system diagnostics and repair.
- Multi-jurisdiction certification lag:India's DGCA adoption of ICAO-aligned standards creates approval bottlenecks for new engine introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Engines Market |
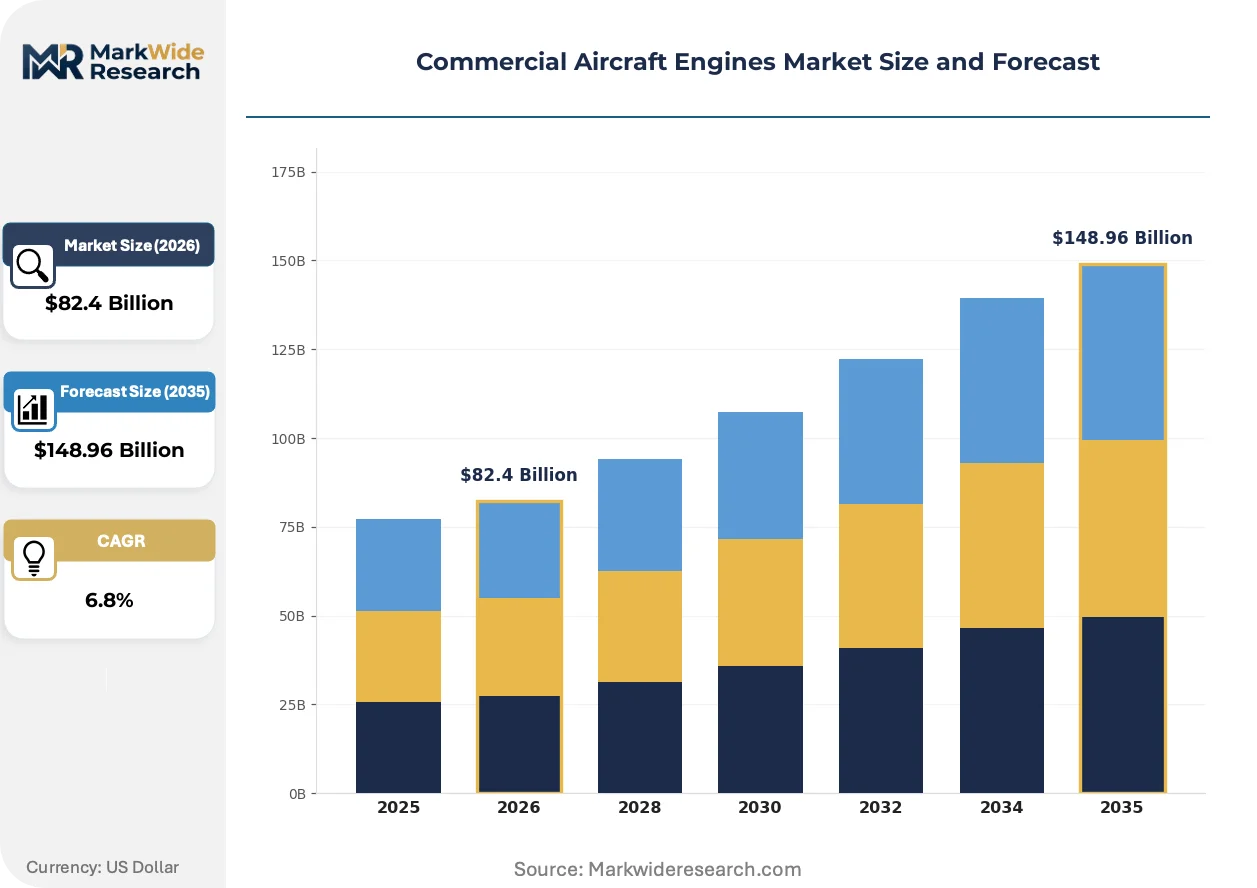
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $148.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Turbofan, Turboprop, Turbojet, Piston Application: Commercial Aviation, Cargo Transport, Private Jets, Military Operations Fuel Type: Jet A, Jet A-1, Biofuel, Aviation Gasoline Manufacturer Type: OEMs, MRO Providers, Engine Parts Suppliers, Aftermarket Service |
| Companies Covered | GE Aerospace, CFM International, Pratt & Whitney, Rolls-Royce, Safran Aircraft Engines, MTU Aero Engines, Honeywell Aerospace, IHI Corporation, Engine Alliance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Engines Market Strategic Shifts
Digital twin architectures are virtualizing how engine performance data flows between OEMs and operators, collapsing the feedback loop from flight operations to design iteration.
Advanced sensor arrays embedded in hot-section components are virtualizing condition monitoring by transmitting real-time thermal and vibrational data to ground-based analytics platforms. Full-service carriers with wide-body fleets are adopting these systems fastest, driven by TotalCare-style contract structures that transfer operational risk to manufacturers. This virtualization is compressing unscheduled removal rates and extending on-wing intervals beyond traditional hard-time limits.
The EU Green Deal's aviation emissions framework is mandating CO2 performance thresholds that exceed ICAO baseline standards, forcing engine makers to prioritize European-bound equipment for early technology insertion. EASA's evolving certification protocols now weight sustainable aviation fuel combustion efficiency more heavily than legacy smoke and noise metrics. Wide-body engine programs face the steepest redesign obligations, with European network carriers demanding documentation trails that support future SAF blend-rate increases.
Engine pooling arrangements are displacing traditional unit-purchase models among regional airlines seeking fleet flexibility without capital deployment. Lessors and independent pool operators are capturing maintenance control previously held by OEM service networks, particularly in Southeast Asian markets where low-cost carrier growth outpaces internal technical staffing. India's expanding domestic routes exhibit the strongest pooling adoption, as airport infrastructure growth enables hub-and-spoke network densities that justify shared spare engine inventories.
Commercial Aircraft Engines Market Segmentation
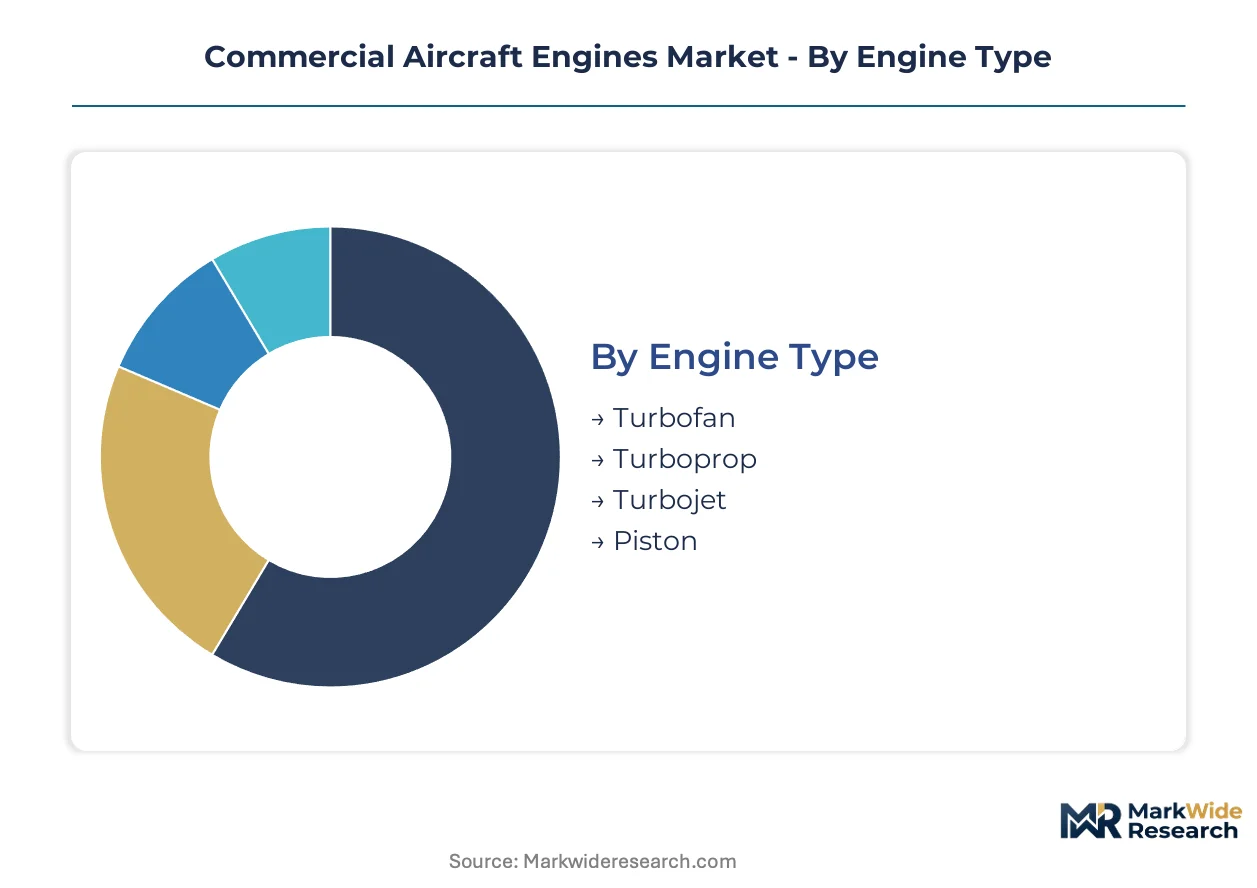
Engine segmentation in this market reflects divergent technical architectures and service models that shape procurement economics. Turbofan dominance in long-haul fleets contrasts with turboprop resilience in regional connectivity, while fuel compatibility and aftermarket control architectures increasingly determine vendor selection criteria.
Engine Type:
Mature high-bypass architectures anchor installed fleet value, while emerging propulsion formats respond to runway constraints and emissions benchmarks.
- Turbofan:High-bypass configurations exceeding 10:1 ratios convert chemical energy through core compressor-turbine assemblies driving bypass fans. Demand concentrates in Southeast Asian low-cost carrier fleet renewals where ICAO emissions benchmarks favor new-generation architectures over legacy systems.
- Turboprop:Gas turbine engines driving propellers through reduction gearboxes achieve superior fuel efficiency on short-haul routes. India's expanding regional airport infrastructure absorbs turboprop capacity where runway length constraints exclude jet alternatives.
- Turbojet:Pure jet configurations without bypass fans retain limited commercial relevance for specialized speed-sensitive applications.
- Piston:Reciprocating internal combustion engines serve training aircraft and very light private aviation segments with minimal commercial fleet penetration.
Turbofan handles the majority of throughput; turboprop is the fastest mover on share.
Application:
Cost tier differentiation separates capital-intensive scheduled operations from flexible asset-light models.
- Commercial Aviation:Scheduled passenger services on narrow-body and wide-body platforms generate the bulk of engine flight hours. India's domestic sector expansion under DGCA-aligned certification protocols drives new-engine introductions.
- Cargo Transport:Dedicated freighter operations and converted passenger aircraft sustain engine demand through e-commerce logistics growth. Southeast Asian hub airports absorb converted wide-body capacity for intra-Asia freight networks.
- Private Jets:Business aviation applications prioritize engine reliability and residual value over unit economics.
- Military Operations:Defense procurement operates under separate certification and funding frameworks with limited commercial technology transfer.
Commercial aviation commands the dominant revenue pool; cargo transport is expanding most quickly on fleet conversion activity.
Fuel Type:
Margin structure tracks compatibility engineering investments and regulatory compliance trajectories across jurisdictions.
- Jet A:Standard kerosene-based turbine fuel dominates North American operations with established supply chain infrastructure.
- Jet A-1:Lower freeze-point variant serves long-haul international routes with cold-weather operational requirements.
- Biofuel:Sustainable aviation fuel blends meeting Jet A-1 specifications are forcing combustor redesigns under EU Green Deal and ICAO CORSIA frameworks. EASA certification protocols now weight SAF combustion efficiency above legacy smoke metrics.
- Aviation Gasoline:Piston engine fuel retains niche application in training and recreational aviation.
Jet A-1 handles the majority of throughput; biofuel is gaining share fastest on regulatory mandate acceleration.
Manufacturer Type:
Customer type fragmentation separates integrated OEM control from independent service competition.
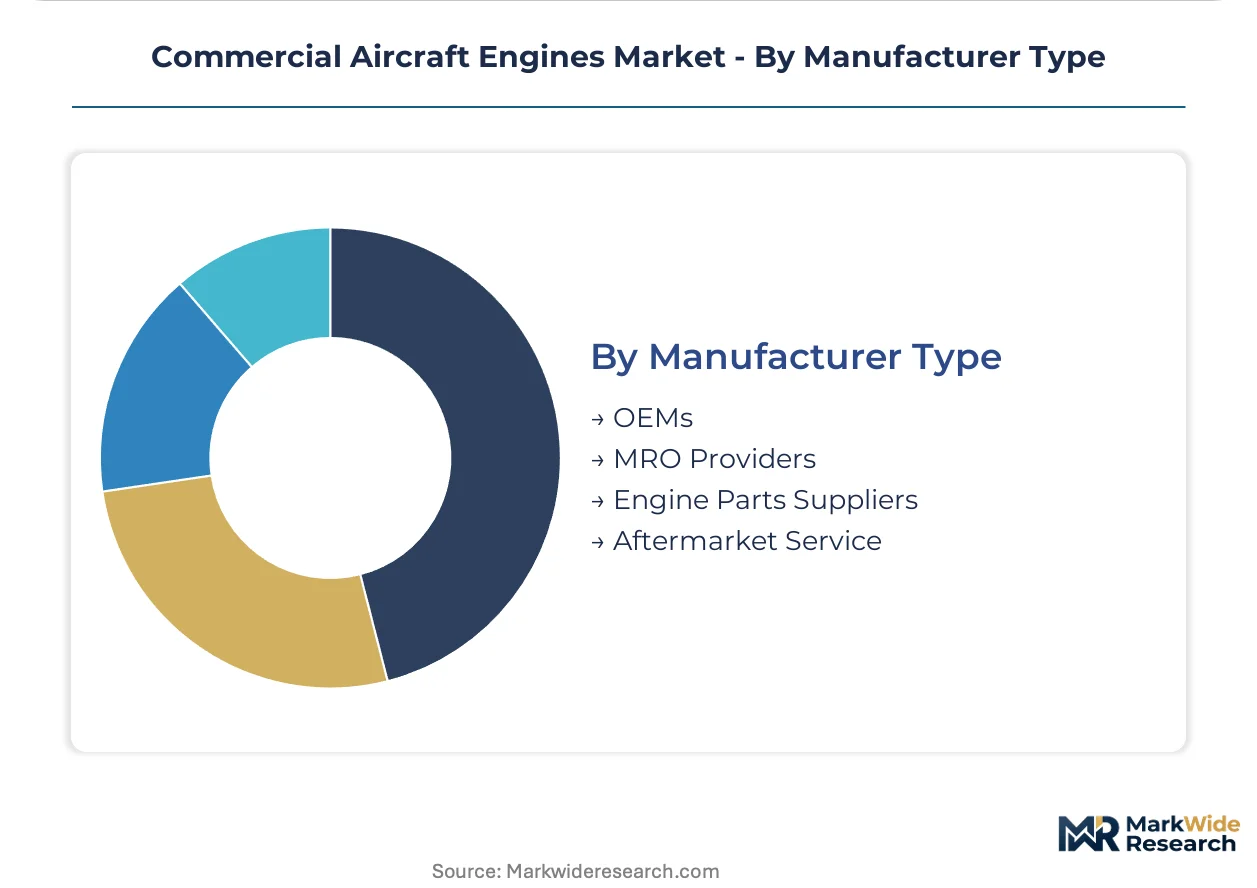
- OEMs:Original equipment manufacturers design, produce, and certify complete engine systems. Power-by-the-hour leasing structures from CFM International and Pratt & Whitney narrow capital barriers for regional airlines seeking new-generation propulsion.
- MRO Providers:Maintenance, repair, and overhaul specialists compete for aftermarket revenue previously captured by OEM service networks. Independent pool operators in Southeast Asia capture technical control as low-cost carrier growth outpaces internal staffing.
- Engine Parts Suppliers:Precision-cast turbine blade and superalloy component vendors face input volatility from concentrated sourcing geographies.
- Aftermarket Service:Long-term TotalCare-style contracts transfer operational risk to manufacturers while capturing lifetime revenue streams.
OEMs retain the majority of value chain control; MRO providers are climbing the fastest on engine pooling adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ICAO's CORSIA framework and national emissions reduction programs are redirecting fleet procurement toward jurisdictions with accelerated certification timelines and infrastructure investment cycles.
United States
FAA Part 33 certification standards govern new engine introductions for US-registered carriers, with American Airlines and Delta Air Lines driving narrow-body renewal programs. The EPA's evolving aircraft emissions guidelines complement federal procurement incentives for sustainable aviation fuel-compatible propulsion systems. GE Aerospace and Pratt & Whitney anchor manufacturing and engineering clusters across Ohio, Connecticut, and North Carolina.
China
CAAC certification protocols are tightening local content requirements for engines powering COMAC's C919 and future wide-body programs. The country's dual carbon goals accelerate demand for high-bypass turbofans in domestic trunk routes connecting Beijing, Shanghai, and Guangzhou. Shenyang and Xi'an host precision manufacturing facilities supplying turbine components to both indigenous and joint-venture engine programs.
India
DGCA-aligned certification standards are creating approval bottlenecks for new engine introductions even as IndiGo and Air India expand narrow-body fleets. The PLI scheme for aerospace components attracts precision casting investments for turbine blade production. Bengaluru and Hyderabad concentrate MRO infrastructure development as airport expansion proceeds in Delhi, Mumbai, and secondary cities.
Germany
EASA's CO2 standards for large aircraft exceed ICAO baselines, forcing combustion system redesigns prioritizing European-bound equipment. MTU Aero Engines maintains development and manufacturing presence in Munich and Hannover, supplying modules to global OEM programs. Hamburg's aviation cluster coordinates between engine makers and Airbus final assembly lines for A320neo family aircraft.
United Kingdom
Rolls-Royce's Derby headquarters anchors a supply chain network extending to Bristol and Birmingham for advanced manufacturing and testing. The UK's Jet Zero Council framework channels public funding toward hydrogen and SAF-compatible propulsion research. TotalCare-style service contracts originating from British engineering centers capture aftermarket revenue across Middle Eastern and Asia-Pacific operator fleets.
Commercial Aircraft Engines Market Competitive Environment
Channel-controlling players compete with product-specialist players across a consolidated OEM tier and fragmented supplier base. Three strategic archetypes dominate: integrated propulsion system designers, modular component specialists, and aftermarket service consolidators. Competitive moves center on long-term service contract structures and power-by-the-hour leasing arrangements that transfer operational risk from operators to manufacturers.
Within the integrated OEM tier, GE Aerospace and Rolls-Royce occupy positions exemplifying divergent strategic emphases on narrow-body versus wide-body platform coverage. CFM International, as a joint-venture structure, represents the collaborative archetype for scaling manufacturing across dual supply chains. Pratt & Whitney anchors the geared turbofan technology vector through its PurePower platform family.
| Leading Market Players |
|---|
| GE Aerospace |
| CFM International |
| Pratt & Whitney |
| Rolls-Royce |
| Safran Aircraft Engines |
| MTU Aero Engines |
| Honeywell Aerospace |
| IHI Corporation |
| Engine Alliance |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Frankfurt cargo corridor cost volatility feeds directly into engine OEM pricing power, as superalloy ingot shipments from European forges concentrate manufacturing margin control while Southeast Asian low-cost carriers face divergent lease-rate spreads based on MRO network proximity.
Pricing Analysis
Certification level (FAA Part 33 versus EASA CO2-grade) creates the primary spread between premium and standard engine tiers. Power-by-the-hour leasing dominates transactional structure, with ICAO CORSIA-aligned engines commanding measurable premiums over legacy turbofan generations. Cost compression in regional airline procurement is intensifying because engine pooling arrangements displace unit-purchase capital deployment. Charter operators exhibit highest price sensitivity; full-service carriers with TotalCare contracts demonstrate lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for precision-cast turbine blade sourcing. Manufacturing concentrates in Germany, the United Kingdom, and Japan for hot-section superalloy components. Raw material dependencies center on nickel-based superalloys, ceramic thermal barrier coatings, and titanium forgings. Single-source vulnerability persists for planetary gear systems in geared turbofan architectures. Distribution runs through OEM-captive service networks and independent MRO pool operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as sustainable aviation fuel mandates splinter certification requirements across jurisdictions, creating technology niches for combustor redesign specialists and aftermarket retrofit providers.
For Market Incumbents: Build aftermarket data moats through digital twin architectures that virtualize condition monitoring and collapse unscheduled removal rates. Deepen upstream control over superalloy casting capacity in Germany and Japan to defend against input volatility. Anchor competitive position by accelerating CAAC certification alignment for China-bound equipment ahead of joint-venture localization mandates. For New Entrants and Emerging Players: Pursue turboprop engine pooling services in India's expanding regional airport infrastructure where runway constraints exclude jet alternatives and internal technical staffing lags fleet growth. Target MRO diagnostics software for geared turbofan planetary gear systems where maintenance networks face acute skill gaps. Lead with power-by-the-hour leasing structures that transfer operational risk and narrow capital barriers for capital-constrained carriers. For Investors and Strategic Acquirers: Independent pool operators with Southeast Asian hub coverage represent the most defensible acquisition archetype as low-cost carrier growth outpaces OEM service network expansion. Long-term viability hinges on aftermarket control architectures capturing lifetime revenue streams previously fragmented across third-party MRO providers. Watch ICAO CORSIA enforcement trajectory as the inflection signal determining which engine platforms retain residual value versus premature obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| SAF-Compatible Combustor Redesign | EASA CO2 standards now weight sustainable aviation fuel combustion efficiency above legacy smoke metrics for European-bound equipment. |
| Digital Twin Architecture Deployment | Virtualized performance data flows between GE Aerospace and operators compress feedback loops from flight operations to design iteration. |
| Engine Pooling Network Expansion | Shared spare engine inventories in Southeast Asia capture maintenance control as IndiGo and Air India narrow-body fleets expand. |
| CAAC Certification Pathway Investment | Local protocol alignment unlocks preferential access to COMAC C919 and future wide-body programs in China's domestic trunk routes. |
| TotalCare-Style Service Contract Structuring | Long-term operational risk transfer to Rolls-Royce captures aftermarket revenue streams across Middle Eastern operator fleets. |
Study Parameters
Operator-level perspectives from fleet planning directors, MRO procurement managers, power-by-the-hour contract negotiators, and DGCA certification officials anchored the qualitative base. Primary interviews combined with secondary validation from FAA Part 33 type certificate databases, EASA certification documentation, ICAO CORSIA implementation reports, and customs trade data for superalloy component flows. Bottom-up engine unit forecasts triangulated against top-down aviation traffic projections across the analysis window.
Scenario-bracketing framed the analytical approach with low, base, and high cases reflecting divergent SAF mandate acceleration timelines and CAAC localization requirements. Segmentation dimensions modeled include engine architecture type, application category, fuel compatibility tier, and manufacturer service model. CAGRs derived from fitted growth curves applied to installed base retirement schedules and new-delivery backlogs. Forecast inputs incorporated ICAO emissions benchmark tightening trajectories and India's PLI scheme precision casting capacity additions.
Macroeconomic conditions sit as an overlay; deviation in jet fuel price volatility, aviation traffic recovery patterns, or superalloy commodity costs would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline convergence and sustainable aviation fuel blend-rate adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
General Aviation Engines Market
Aircraft Engine Systems and Services
Narrow-Body Turbofan Engine Shop Visit Services Market
Aircraft Engine Systems and Services
America Aircraft Engines Market
Aircraft Engine Systems and Services
Global Aircraft Engine Fuel Systems Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
Aero Engine Coatings Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Helicopter Engine Market