
 Aircraft Circuit Breakers Market | 2026-2036
Aircraft Circuit Breakers Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Circuit Breakers Market Intelligence
A gradual transition from single-source agreements to multi-sourcing strategies is rebalancing supplier relationships for airframe manufacturers. Eaton Corporation leverages its extensive portfolio to secure positions on multiple new and legacy platforms. Safran specializes in integrated power distribution systems, offering complete electrical solutions to major OEMs. Collins Aerospace, a unit of Raytheon Technologies Corporation, competes on the basis of its deep system integration capabilities within the broader avionics ecosystem.
An aircraft circuit breaker is an automatic switch designed to protect an aircraft's electrical circuits from damage caused by overcurrent or short circuits. These devices are qualified to precise trip-time characteristics under extreme vibration and temperature conditions. Thermal-magnetic types remain the standard in legacy fleets, but solid-state circuit breakers are gaining share in new aircraft designs for commercial jets. The single-pole technology configuration dominates by volume due to its widespread use in individual circuits.
Regulations from the FAA in the United States and the EASA in Europe mandate stringent certification for all electrical components. These standards, including AS9100 for aerospace quality management systems, govern design, manufacturing, and performance verification. Future investment decisions will hinge on developing components compliant with evolving standards for high-voltage DC systems in next-generation aircraft.
Market Dynamics
The fundamental market dynamic is the architectural shift toward More Electric Aircraft, which increases the quantity and sophistication of required circuit protection devices. This transition pressures suppliers to develop lighter, more intelligent components that can manage complex electrical loads and integrate with modern avionics.
Growth Catalysts
- More Electric Architectures:The transition to MEA designs in new aircraft substantially increases the number of electrical systems, directly expanding the volume of circuit breakers required per airframe for both primary and secondary power distribution.
- Commercial Aviation Production:Rising build rates for commercial jets, centered in established aerospace manufacturing clusters in the United States and France, provide a consistent volume demand for both new and replacement circuit breakers.
- Evolving Safety Standards:Heightened airworthiness standards from regulators like the FAA and EASA mandate more advanced and reliable circuit protection, especially for systems critical to flight safety, encouraging upgrades from older technologies.
Market Restraints
- Qualification and Certification Costs:The extreme testing and lengthy certification cycles required by aviation authorities for any new component design create high barriers to entry and slow the pace of technological adoption.
- Supplier Concentration:Dependence on a few highly specialized and qualified suppliers creates potential supply chain bottlenecks and limits the negotiating power of airframe manufacturers for pricing and terms.
- Legacy Fleet Dominance:The long operational life of aircraft means a large installed base of legacy fleets relies on older, thermal-magnetic circuit breaker technology, complicating modern retrofits and system upgrades.
Strategic Opportunities
- High-Voltage DC Systems:Developing circuit breakers specifically designed for the unique challenges of high-voltage DC power distribution presents a significant opportunity as next-generation commercial and military aircraft adopt these architectures.
- Integrated Health Monitoring:Embedding diagnostic and prognostic capabilities into solid-state circuit breakers allows for predictive maintenance, creating a new value proposition for airlines focused on maximizing aircraft uptime and safety.
- Urban Air Mobility Platforms:The emerging Urban Air Mobility market, with its unique electric propulsion and power distribution needs, offers a new application segment for compact, lightweight, and highly reliable circuit protection devices.
Industry Challenges
- Certification Pathways:Navigating the complex and time-consuming certification processes with the FAA and EASA for novel technologies like solid-state breakers remains a significant operational hurdle for component manufacturers.
- Legacy System Integration:Ensuring the seamless backward compatibility of new, intelligent circuit breakers with the existing electrical systems of older aircraft during retrofit programs presents a major technical challenge.
- Specialized Talent Acquisition:Securing engineering talent with expertise in power electronics and embedded software is a key hurdle for developing advanced solid-state devices and maintaining a competitive edge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Circuit Breakers Market |
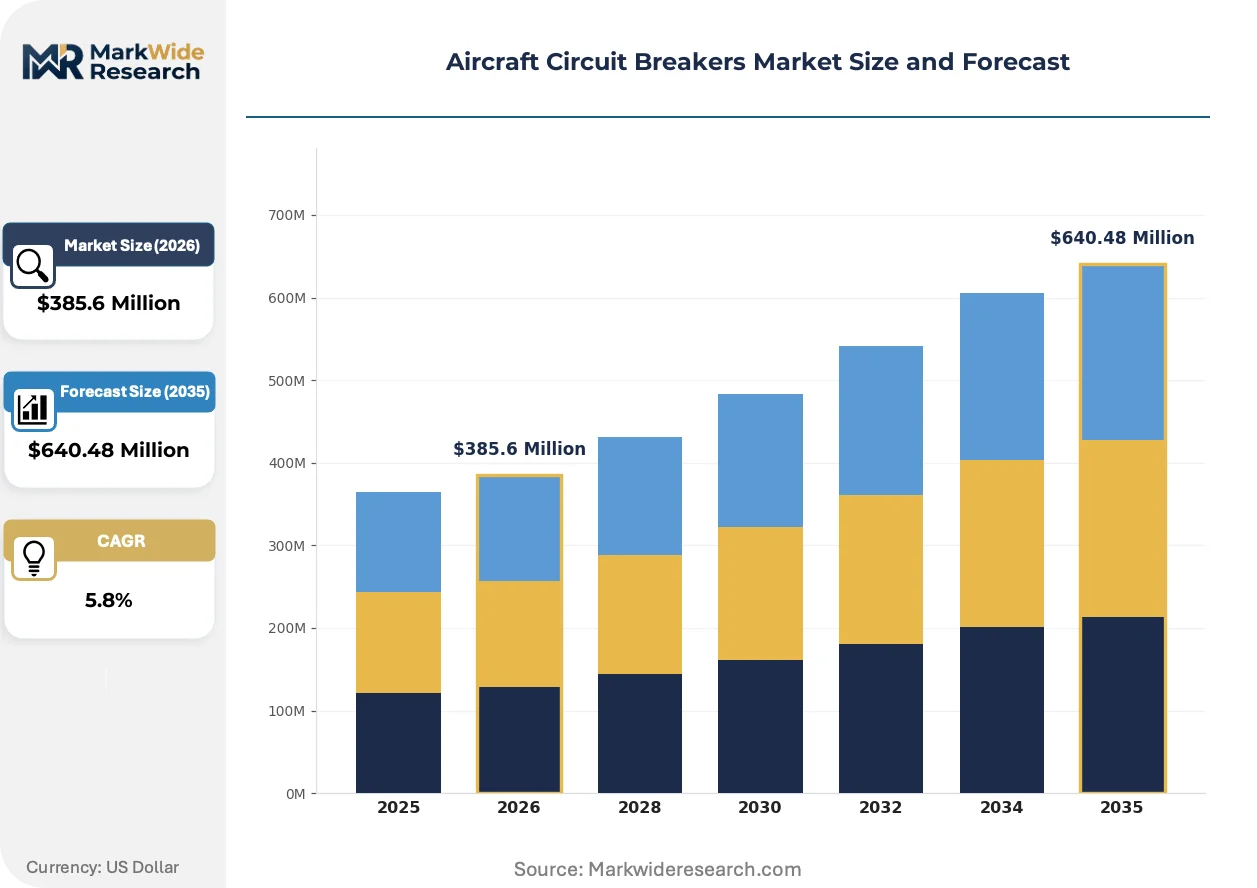
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal, Magnetic, Thermal Magnetic, Hydraulic Magnetic, Solid State Technology: Single-Pole, Multi-Pole, Molded Case, Miniature, Air Circuit Application: Commercial Jets, Military Aircraft, Business Jets, Helicopters, General Aviation End User: Aircraft Manufacturers, Maintenance Facilities, Repair Stations, Airlines, Aerospace Suppliers |
| Companies Covered | Sensata Technologies, Astronics Corporation, Safran, Eaton Corporation, Raytheon Technologies Corporation, Crouzet, TE Connectivity, Woodward, Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Circuit Breakers Market Strategic Shifts & Innovations
Intelligent power management is fundamentally altering the role of circuit protection within the aircraft. The transition moves beyond simple overcurrent defense toward integrated, data-driven systems that enhance safety and operational efficiency across the entire electrical architecture.
Solid-state circuit breakers use semiconductor devices to interrupt current, offering faster trip times and no moving parts. They are being adopted primarily in new commercial jet designs and military platforms where performance and reliability are paramount. This technology is consolidating the function of multiple mechanical breakers and fuses into a single, programmable, and lighter unit.
Evolving FAA and EASA regulations are establishing stricter requirements for electrical system fault tolerance and isolation, particularly for MEA architectures. This regulatory pressure compels airframers to adopt advanced circuit protection that can be integrated into the aircraft's overall health management system. The commercial jets segment is most affected, driving investment in components that meet these heightened safety and performance standards.
Airframe manufacturers are increasingly moving away from single-source agreements toward multi-sourcing strategies for critical components like circuit breakers. This shift diversifies the supply chain, reducing risk and increasing cost competition among qualified vendors. This trend is most prominent among major OEMs in the United States and France, who are re-evaluating long-term supplier relationships for both new and legacy aircraft programs.
Aircraft Circuit Breakers Market Segmentation
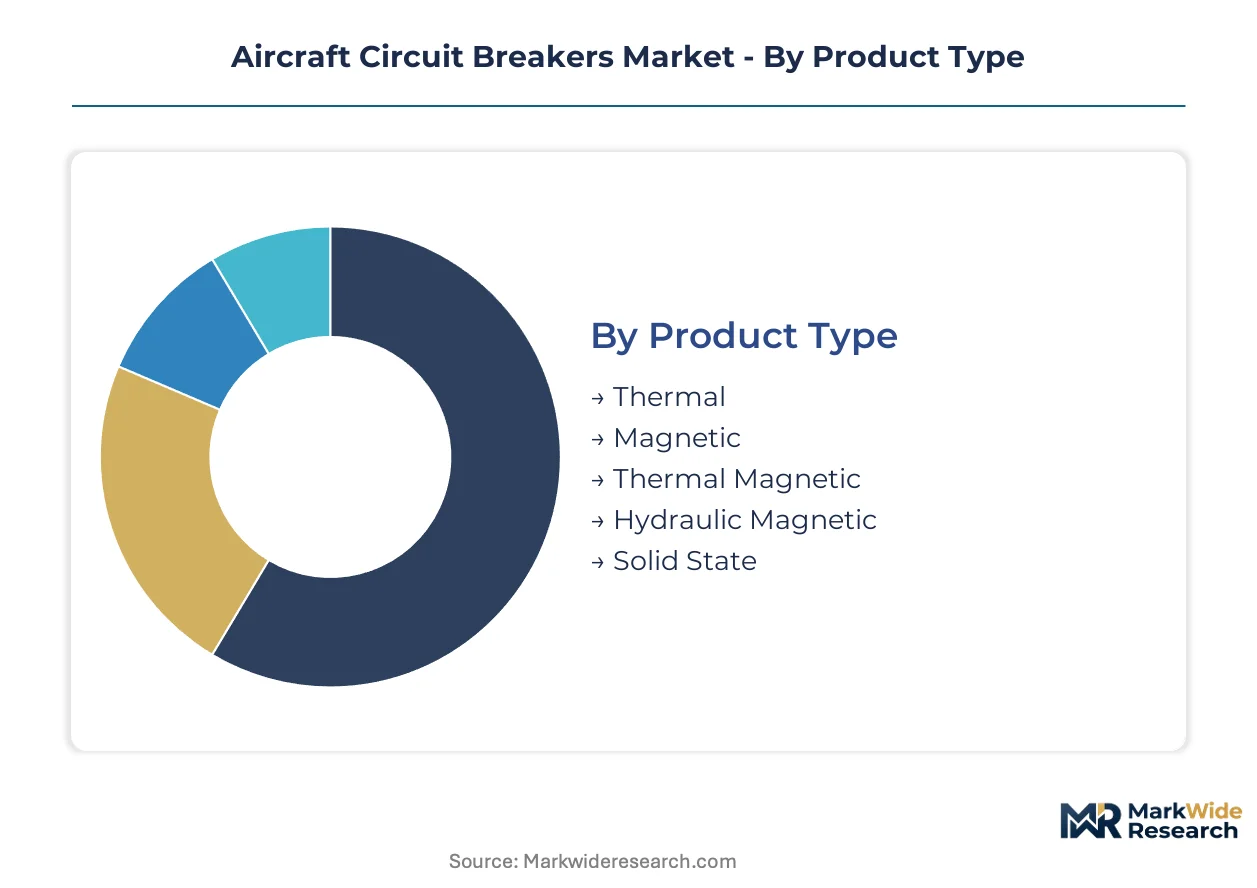
Understanding the segmentation within the aircraft circuit breakers market is essential for identifying specific demand drivers and technological shifts. This detailed categorization helps stakeholders pinpoint areas of high growth, understand evolving regulatory impacts, and adapt to changing aircraft electrical architectures.
Product Type:
Supply for aircraft circuit breakers is concentrating on advanced product types that meet evolving performance demands in modern aircraft. Manufacturers are prioritizing solutions that offer enhanced safety and integration capabilities.
- Solid State:These circuit breakers utilize semiconductor technology to interrupt current, offering significantly faster trip times and extended operational life due to the absence of moving parts. Demand is concentrating in new commercial jet designs and advanced military platforms, driven by requirements for rapid fault isolation and reduced weight.
- Thermal Magnetic:Combining thermal and magnetic trip mechanisms, these devices protect against both sustained overloads and instantaneous short circuits, remaining a standard in legacy aircraft fleets. Demand is strong in maintenance, repair, and overhaul operations for existing commercial and general aviation aircraft, supported by their proven reliability and cost-effectiveness.
- Thermal:Thermal circuit breakers rely on a bimetallic strip that heats and bends to interrupt current during sustained overloads. This type is prevalent in applications where precise, time-delayed protection is sufficient.
- Magnetic:Magnetic circuit breakers respond instantaneously to short circuits using an electromagnetic coil, providing rapid protection without being affected by ambient temperature fluctuations. These are often found in sensitive electronic systems.
- Hydraulic Magnetic:These breakers combine hydraulic fluid damping with magnetic tripping, offering a time delay inversely proportional to the overcurrent magnitude, suitable for applications with high inrush currents.
Today's leader: Thermal Magnetic. Tomorrow's challenger: Solid State.
Technology:
Volume demand for aircraft circuit breaker technology is driven by the fundamental electrical architecture of the aircraft, dictating the configuration and complexity of protection devices. Each technology addresses specific circuit protection needs.
- Single-Pole:This configuration interrupts current in a single conductor, dominating by volume due to its widespread use in individual circuits across all aircraft types. Its simplicity and compact size make it ideal for protecting numerous isolated loads in commercial and military aircraft.
- Multi-Pole:Multi-pole circuit breakers simultaneously disconnect multiple conductors in a circuit, essential for protecting three-phase power systems or ensuring complete isolation of critical loads. Adoption is expanding in more complex electrical systems found in larger commercial jets and advanced military platforms, where coordinated protection is paramount.
- Molded Case:Molded case circuit breakers are enclosed in a molded insulating material, offering robust protection for higher current applications and main power distribution within aircraft. These are common in primary power distribution units.
- Miniature:Miniature circuit breakers are compact devices designed for lower current applications where space and weight are critical constraints. They are increasingly used in avionics and secondary power systems.
- Air Circuit:Air circuit breakers use air as an arc quenching medium, typically employed in very high current applications for main power distribution and generator protection in larger aircraft.
Single-pole configurations maintain significant market presence, while multi-pole systems show the steepest expansion trajectory.
Application:
The application of aircraft circuit breakers directly correlates with the operational demands and certification requirements of different aircraft types. Each segment presents unique challenges for electrical system protection.
- Commercial Jets:This segment includes large passenger and cargo aircraft, driving significant demand for both thermal-magnetic and solid-state circuit breakers due to high production rates and stringent safety regulations from the FAA and EASA. The transition to More Electric Aircraft architectures in commercial jets increases the quantity and sophistication of required protection devices.
- Military Aircraft:Covering fighters, bombers, transport aircraft, and surveillance platforms, this segment demands highly robust, reliable, and often specialized circuit breakers capable of operating under extreme environmental conditions. Procurement is influenced by defense budgets and technological advancements in the United States and France.
- Business Jets:Business jets require compact and lightweight circuit breakers to support advanced avionics and passenger comfort systems, balancing performance with size constraints. This segment values reliability and minimal maintenance.
- Helicopters:Helicopters utilize circuit breakers designed to withstand high vibration and harsh operational environments, protecting critical flight control and navigation systems. Demand here focuses on durability and performance under stress.
- General Aviation:This broad category includes smaller, privately owned aircraft where cost-effectiveness and ease of maintenance are important considerations for circuit breaker selection.
Commercial jets continue to be the largest segment, with military aircraft gaining share fastest due to modernization programs.
End User:
Customer type for aircraft circuit breakers reflects the diverse stakeholders involved in an aircraft's lifecycle, from initial build to long-term maintenance. Each end-user group has distinct procurement needs and priorities.
- Aircraft Manufacturers:Major airframe manufacturers like Boeing and Airbus are primary customers, integrating circuit breakers into new aircraft designs and production lines. They prioritize advanced, certified components that meet rigorous design specifications and contribute to overall aircraft system integration.
- Airlines:Airlines purchase circuit breakers for fleet maintenance, repair, and overhaul (MRO) operations, ensuring the continued airworthiness and safety of their operational aircraft. They focus on component reliability, availability, and cost-efficiency for their extensive fleets.
- Maintenance Facilities:Independent MRO facilities and authorized service centers procure circuit breakers for repairs and scheduled maintenance on various aircraft types. These facilities require access to a wide range of certified parts for diverse legacy and modern aircraft.
- Repair Stations:Specialized repair stations focus on component-level maintenance and overhauls, including electrical systems, requiring specific types of circuit breakers for component refurbishment. Their demand is highly specialized based on the components they service.
- Aerospace Suppliers:These companies often supply sub-assemblies or integrated electrical systems to aircraft manufacturers, incorporating circuit breakers as part of larger component packages.
Aircraft manufacturers remain critical direct purchasers, with airlines expanding most quickly as they manage extensive fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence across regions creates opportunities for production optimization, as manufacturers seek to balance stringent certification requirements with cost-effective manufacturing hubs. Proximity to established aerospace manufacturing centers in the United States and France remains a critical factor for suppliers of advanced electrical components.
United States
The United States drives significant demand for advanced circuit breakers due to its large commercial jet production and military aircraft modernization programs. Regulations from the FAA mandate rigorous testing and certification for all new electrical system components. Major aerospace clusters in Seattle, Wichita, and Southern California concentrate significant manufacturing and R&D activities.
France
France serves as a core European aerospace manufacturing hub, with robust demand for circuit breakers driven by Airbus production and defense sector investments. EASA regulations ensure high airworthiness standards for electrical systems integrated into new aircraft designs. The Toulouse region anchors extensive aerospace manufacturing, including integrated power distribution system development.
Germany
German aerospace manufacturing contributes to European demand, particularly for specialized aircraft components and advanced electrical systems. The EASA framework guides the development and certification of circuit breakers for commercial and military platforms. Bavaria and Hamburg host significant aerospace engineering and production facilities, focusing on precision components.
Japan
Japanese aerospace companies contribute to global supply chains, with a growing focus on advanced materials and precision electrical components. The Japan Civil Aviation Bureau (JCAB) oversees airworthiness standards, influencing circuit breaker specifications for domestic and international programs. Nagoya and Tokyo feature key aerospace manufacturing and research centers, supporting next-generation aircraft development.
United Kingdom
The United Kingdom maintains a strong aerospace sector, contributing to both commercial and defense aircraft programs. UK Civil Aviation Authority (CAA) standards align closely with EASA requirements for electrical system reliability and safety. Bristol and Derby are significant aerospace engineering and manufacturing hubs, driving demand for specialized circuit protection.
Aircraft Circuit Breakers Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue integrated power management solutions and high-voltage DC system components. The market structure is characterized by a few large, diversified aerospace suppliers alongside specialized component manufacturers. Strategic partnerships between component suppliers and airframe manufacturers are a dominant competitive move, alongside continuous portfolio diversification into advanced electrical architectures.
Within the integrated systems tier, Safran and Eaton Corporation exemplify comprehensive electrical solution providers, leveraging their extensive product portfolios to secure positions on new aircraft platforms. Collins Aerospace, a unit of Raytheon Technologies Corporation, anchors the deep system integration capabilities within the broader avionics ecosystem. These companies focus on delivering complete, certified electrical solutions rather than individual components.
| Leading Market Players |
|---|
| Sensata Technologies |
| Astronics Corporation |
| Safran |
| Eaton Corporation |
| Raytheon Technologies Corporation |
| Crouzet |
| TE Connectivity |
| Woodward |
| Collins Aerospace |
| Others |
Cost & Logistics Intelligence
Semiconductor component pricing, influenced by global demand and manufacturing capacity, cascades through the aircraft circuit breaker supply chain, impacting overall system costs for advanced solid-state devices. This dynamic influences procurement strategies for airframe manufacturers and MRO providers.
Pricing Analysis
Input-cost pass-through remains a significant factor for aircraft circuit breaker manufacturers, particularly for specialized alloys and semiconductor materials. Pricing models are predominantly contract-based long-term offtake agreements with major OEMs. Price differentiation stems from rigorous certification levels, such as FAA and EASA approvals, and the specific performance characteristics required for critical flight systems. Pricing pressure originates from airframe manufacturers seeking cost efficiencies through multi-sourcing strategies. Airlines, managing extensive legacy fleets, exhibit the highest price sensitivity for replacement thermal-magnetic units.
Supply Chain Analysis
Reverse logistics for aircraft circuit breakers, encompassing refurbishment and remanufacturing flows, primarily supports MRO operations for existing fleets. Geographic supply concentration centers in the United States, France, and Germany, reflecting established aerospace manufacturing hubs. The supply chain draws from specialized alloys for thermal-magnetic types and advanced semiconductor components for solid-state devices. Single-source vulnerability for highly specialized components represents a key structural risk. Distribution runs through direct channels to aircraft manufacturers and specialized aerospace distributors for aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, driven by a pronounced demand-shift toward premium specifications required for More Electric Aircraft architectures.
For Market Incumbents:
Deepen investment in solid-state circuit breaker technology, focusing on high-voltage DC system compatibility and integrated health monitoring. This mitigates the threat from emerging specialized component providers offering advanced electrical solutions. Secure long-term development contracts with major airframe manufacturers by demonstrating superior certification expertise and system integration capabilities. Expand R&D efforts into lighter, more intelligent components that can manage complex electrical loads efficiently.
For New Entrants and Emerging Players:
Specialized MRO distributors represent a viable channel partner for introducing novel circuit protection solutions to specific fleet segments. Target the Urban Air Mobility (UAM) market, which requires compact, lightweight, and highly reliable circuit breakers for electric propulsion systems. This segment offers a penetrable entry point for innovative solid-state technologies. Focus go-to-market strategies on collaborative development with UAM airframe developers, emphasizing rapid prototyping and agile certification pathways.
For Investors and Strategic Acquirers:
Consolidation pressure builds where specialized solid-state technology and deep system integration capabilities are scarce. Long-term viability remains strong for companies positioned at the forefront of MEA and high-voltage DC system development. Target acquisition candidates include niche technology firms specializing in advanced power electronics or those with proven track records in rapid aviation certification. Practitioners should monitor the adoption rates of new aircraft platforms incorporating high-voltage DC systems for early signals of market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Solid-State R&D | Accelerates development of faster, lighter circuit breakers for More Electric Aircraft. |
| Secure Long-Term OEM Contracts | Ensures consistent volume demand and integration into new commercial jet programs. |
| Develop High-Voltage DC Solutions | Addresses future power distribution requirements for next-generation military aircraft. |
| Expand MRO Service Offerings | Captures aftermarket revenue from legacy fleets and extends product lifecycle for airlines. |
| Form UAM Technology Partnerships | Penetrates the emerging Urban Air Mobility market with compact, specialized protection devices. |
Research Approach
Bottom-up commercial jets application modeling reconciled against top-down aircraft manufacturer tracking forms the analytical core of this study. This approach combines primary interviews with aerospace engineers, MRO facility managers, procurement officers at OEMs, and regulatory compliance specialists. Secondary validation leverages FAA and EASA airworthiness directives, aerospace trade publications, OEM financial reports, and patent databases to ensure data integrity.
The input-output matrix framing guides the forecast framework across the modeling period. Segmentation dimensions modeled include product type, technology, application, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were calculated from historical data and projected trends, incorporating key industry-specific inputs such as aircraft production rates and More Electric Aircraft adoption curves throughout the forecast period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory changes for new electrical systems and material supply disruptions. Forecasts reflect assumptions regarding technological advancements and market acceptance. Practitioners should monitor shifts in defense spending and evolving MEA standards for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Global Aircraft Electrification Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aerospace and Military Auxiliary Power Unit (APU) Market
Aircraft Power Systems
Global Aircraft Micro Turbine Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Aircraft Electrical Power Distribution Systems Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Aircraft Cooling Turbines Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market