
 Aircraft Cooling Turbines Market | 2026-2036
Aircraft Cooling Turbines Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Cooling Turbines Market Analysis
Project finance tied to long-term aftermarket service contracts is fragmenting competitive access in the aircraft cooling turbines sector. Honeywell International Inc. leverages its integrated environmental control systems portfolio to capture recurring revenue streams. Collins Aerospace anchors its position through deep OEM relationships and flight-critical thermal management expertise. Safran S.A. competes via specialized pneumatic system architectures optimized for narrow-body platforms.
Aircraft cooling turbines are turbomachinery devices that extract energy from compressed bleed air to drive refrigeration cycles, typically operating at rotational speeds exceeding 50,000 RPM to achieve cabin temperature reduction below ambient conditions at altitude. These units serve the essential commercial purpose of maintaining pressurized cabin environments and avionics thermal stability across variable flight regimes. The axial product category dominates installed base volumes due to legacy platform compatibility, while variable speed technology captures expanding margin pools as airlines prioritize fuel-burn reduction through adaptive cooling loads. Electric technology segments show accelerated development timelines as airframers pursue more-electric aircraft architectures that displace traditional pneumatic bleed systems.
FAA airworthiness standards and EASA CS-25 certification requirements govern turbine efficiency benchmarks and failure-mode containment protocols, directly shaping R&D allocation and product qualification timelines for suppliers. EPA regulations on aircraft emissions indirectly pressure thermal system optimization as reduced engine bleed improves overall propulsion efficiency. Stakeholders must monitor the pace of more-electric aircraft transitions to determine whether pneumatic cooling turbine architectures face accelerated obsolescence or extended retrofit cycles.
Market Dynamics
The transition toward more-electric aircraft architectures is compressing demand for traditional pneumatic cooling turbines while simultaneously creating qualification windows for hybrid thermal management systems that bridge legacy and emerging power architectures.
Growth Catalysts
- FAA airworthiness standards:Tightening certification requirements for thermal management efficiency are forcing fleet operators to accelerate replacement cycles on aging cooling turbine units.
- Narrow-body platform expansion:Airlines in India and Southeast Asia are adding single-aisle aircraft at rates that outstrip wide-body deliveries, concentrating demand for compact, high-RPM cooling turbine configurations.
- Bleed air optimization:Advanced variable-speed turbine designs reduce engine bleed extraction by modulating cooling loads against actual cabin thermal demand rather than fixed output curves.
Market Restraints
- Specialized alloy supply:Nickel-based superalloys for high-speed turbine rotors face concentrated sourcing from a limited supplier base in the United States and Germany, exposing manufacturers to input volatility.
- Electric architecture substitution:More-electric aircraft programs at Boeing and Airbus are piloting vapor compression cycles that eliminate pneumatic bleed entirely, threatening long-term installed base economics for cooling turbine OEMs.
- EASA CS-25 containment protocols:Failure-mode certification requirements for high-speed rotating machinery extend qualification timelines and elevate non-recurring engineering costs for new product introductions.
Strategic Opportunities
- Retrofit aftermarket in China:Aging commercial fleets operated by domestic carriers present conversion opportunities as CAAC adopts harmonized standards with FAA and EASA thermal efficiency benchmarks.
- Urban air mobility thermal systems:Electric vertical takeoff platforms require compact environmental control units that adapt cooling turbine principles to battery thermal management architectures.
- ISO 1540 aircraft electrical standards:Harmonization of power quality specifications is creating common qualification pathways for suppliers seeking to serve both traditional pneumatic and emerging electric thermal system markets.
Industry Challenges
- High-speed bearing engineering talent:The specialized knowledge required for magnetic and air-bearing designs at rotational speeds exceeding 50,000 RPM remains concentrated among a narrow cohort of turbomachinery specialists.
- Dual certification complexity:Suppliers must simultaneously maintain FAA and EASA qualification while navigating divergent interpretation of turbine efficiency test protocols, fragmenting R&D resources.
- Legacy platform integration:New cooling turbine designs must maintain physical and control interface compatibility with environmental control systems installed on aircraft delivered two decades prior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Cooling Turbines Market |
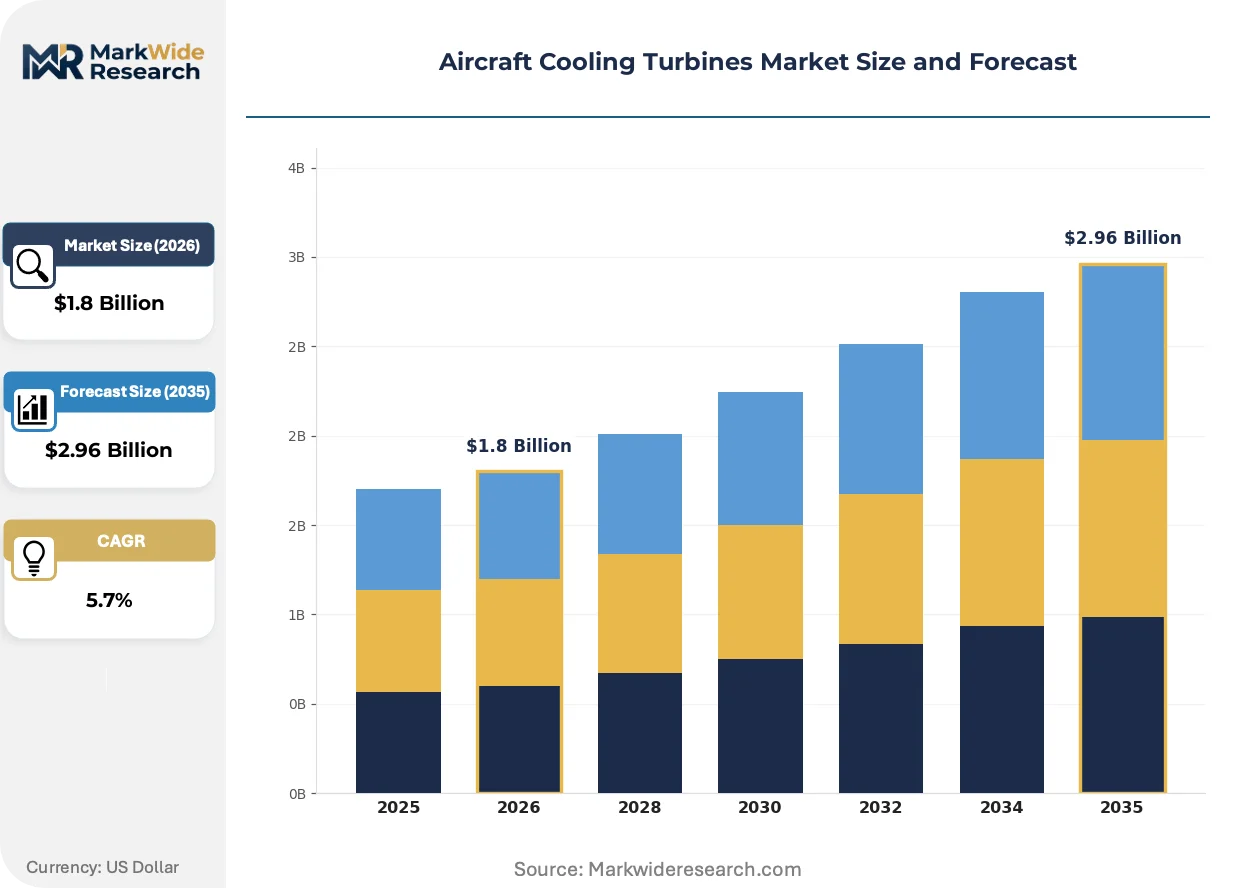
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial, Centrifugal, Mixed Flow, Variable Speed Application: Commercial Aviation, Military Aviation, General Aviation, Unmanned Aerial Vehicles Technology: Direct Drive, Electric, Hybrid, Pneumatic End User: OEMs, Aftermarket Providers, Airlines, Maintenance Repair Organizations |
| Companies Covered | Honeywell International Inc., Collins Aerospace, Safran S.A., Rolls-Royce Holdings plc, MTU Aero Engines AG, Pratt & Whitney, General Electric Company, Liebherr Group, AMETEK, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Cooling Turbines Market Emerging Trajectories
Active development in thermal management architectures is blurring the boundary between pneumatic and electric power distribution, with implications for component sourcing strategies and supplier qualification pathways.
Variable-speed cooling turbine technology is hybridizing traditional fixed-geometry pneumatic designs with electronically controlled variable inlet guide vanes that modulate mass flow against real-time cabin thermal demand. Airlines operating high-cycle narrow-body routes are adopting these units to reduce fuel burn during descent and ground operations. This technology is hybridizing the competitive landscape by enabling legacy suppliers to defend installed base positions while developing electric architecture competencies.
EASA F-Gas Regulation restrictions on high-global-warming-potential refrigerants are accelerating R&D investment in alternative working fluids for air cycle machines and vapor compression systems. The regulation forces thermal system suppliers to requalify entire product families under revised environmental safety protocols. Wide-body platform OEMs face the steepest compliance costs due to larger refrigerant charge volumes and extended certification timelines.
Airlines are consolidating aftermarket service contracts with environmental control system integrators rather than maintaining discrete component-level supplier relationships. This pattern concentrates procurement leverage with tier-one thermal management providers and compresses margins for specialized cooling turbine manufacturers. The shift is most pronounced among North American network carriers seeking to simplify fleet technical operations.
Aircraft Cooling Turbines Market Segmentation
Product architecture choices in aircraft cooling turbines determine replacement cycle velocity and aftermarket revenue capture. Segment boundaries are blurring as variable-speed and electric technologies hybridize legacy pneumatic designs.
Product Type:
Axial configurations dominate fleet-installed volumes with decades-long replacement cycles, while variable-speed units turn over faster as airlines retrofit for fuel efficiency gains.
- Axial:These turbines employ parallel-flow blade geometries optimized for high-volume, low-pressure-ratio applications. Legacy narrow-body fleets operated by US and Indian carriers sustain demand for spares and overhauls despite minimal new platform adoption.
- Variable Speed:Electronically modulated inlet guide vanes match cooling output to real-time thermal demand rather than fixed bleed extraction. Southwest Airlines and IndiGo have specified these units on recent narrow-body deliveries to reduce fuel burn during ground and descent phases.
- Centrifugal:Radial flow designs concentrate in business jet and regional turboprop applications where packaging constraints override efficiency optimization.
- Mixed Flow:Hybrid geometries blending axial and centrifugal characteristics serve specialized military platforms requiring broad operating envelope coverage.
Axial units anchor the volume base while variable speed gains share at the steepest rate.
Application:
Commercial aviation concentrates procurement leverage with tier-one integrators, whereas military and unmanned segments fragment buying power across specialized program offices.
- Commercial Aviation:Single-aisle and wide-body aircraft account for the dominant share of cooling turbine installations. Fleet operators in the United States and India are modernizing environmental control systems to meet tightening FAA and EASA thermal efficiency benchmarks.
- Unmanned Aerial Vehicles:High-altitude long-endurance platforms require miniature turbomachinery operating at extreme RPMs for avionics thermal management. Northrop Grumman and General Atomics programs are qualifying specialized units with reduced maintenance intervals.
- Military Aviation:Fighter and transport platforms prioritize redundancy and battle damage tolerance over fuel efficiency, sustaining demand for robust pneumatic architectures.
- General Aviation:Business jet manufacturers including Gulfstream and Dassault specify compact cooling turbines integrated with pressurization and temperature control systems.
Commercial aviation commands the revenue concentration while unmanned aerial vehicles expand most quickly as defense procurement shifts toward autonomous platforms.
Technology:
Direct drive and pneumatic systems face compressed replacement cycles as Boeing and Airbus accelerate more-electric aircraft development timelines.
- Pneumatic:Traditional bleed-air-driven turbines remain entrenched on in-service fleets. Airlines defer replacement until mandatory airworthiness directives force action, extending installed base economics for incumbent suppliers.
- Electric:Vapor compression and electro-mechanical cooling architectures eliminate engine bleed entirely. Airbus A320neo and Boeing 787 programs are piloting these systems for next-generation narrow-body derivatives.
- Direct Drive:Mechanically coupled turbines without intermediate gearboxes reduce weight and maintenance burden on regional aircraft platforms.
- Hybrid:Dual-mode systems switch between pneumatic and electric power sources depending on flight phase, bridging legacy and emerging architectures.
Pneumatic technology retains the installed base while electric configurations climb the fastest as airframers redesign thermal management around more-electric power distribution.
End User:
OEMs and airlines concentrate engineering resources on new platform specification, while aftermarket providers and MROs capture recurring revenue from aging fleet maintenance.
- OEMs:Boeing, Airbus, and Embraer specify cooling turbines during initial aircraft configuration. Long-term sole-source agreements with Honeywell and Collins Aerospace lock in supplier relationships through program life cycles.
- Aftermarket Providers:Independent distributors including HEICO and TransDigm acquire used serviceable material and reverse-engineer components to challenge OEM spare pricing on mature platforms.
- Airlines:Delta, United, and American Airlines are consolidating environmental control system contracts with integrators rather than maintaining discrete component supplier relationships.
- Maintenance Repair Organizations:ST Engineering and Lufthansa Technik expand cooling turbine overhaul capabilities to capture fleet aging tailwinds in Asia-Pacific and European markets.
OEMs anchor specification control while aftermarket providers gain share fastest as fleet age extends and airlines outsource component-level maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where OEM sole-source agreements lock in premium positioning, while Indian carriers negotiate harder on retrofit contracts due to fragmented supplier access.
United States
Boeing's 737 MAX and 787 production ramps sustain demand for variable-speed cooling turbines at its Everett and Charleston facilities. FAA airworthiness standards for thermal management efficiency tighten certification timelines for new entrants. Honeywell and Collins Aerospace anchor engineering clusters in Phoenix and Cedar Rapids, controlling specification access for domestic fleet operators.
Germany
MTU Aero Engines and Liebherr Group drive demand for compact turbomachinery in regional and business jet platforms. EASA F-Gas Regulation restrictions force requalification of air cycle machines using alternative working fluids. Munich and Friedrichshafen host concentrated development centers for high-speed bearing technologies exceeding 50,000 RPM.
India
IndiGo and Air India narrow-body expansion concentrates procurement for compact cooling configurations. CAAC harmonization with FAA thermal efficiency benchmarks accelerates aging fleet retrofit cycles. Bangalore and Hyderabad emerging as MRO hubs where ST Engineering and local providers build turbine overhaul capabilities.
China
COMAC C919 production ramps create qualification windows for domestic thermal system suppliers. MIIT standards for more-electric aircraft architectures pilot vapor compression alternatives to pneumatic bleed. Shanghai and Xi'an concentrate airframe integration activity with state-backed pressure for local component sourcing.
France
Airbus A320neo and A350 programs at Toulouse sustain specification control for Safran's pneumatic system architectures. ANSM interpretation of EASA CS-25 containment protocols extends qualification timelines for high-speed rotating machinery. Paris-Saclay aerospace cluster hosts specialized turbomachinery engineering talent concentrated among legacy suppliers.
Aircraft Cooling Turbines Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower specification access. The market structures around three tiers: diversified conglomerates with environmental control system portfolios, pure-play turbomachinery manufacturers, and aftermarket-focused independents. Competitive moves concentrate on sole-source agreement renewals and M&A targeting specialized bearing engineering capabilities.
Among diversified system integrators, Honeywell International Inc. and Collins Aerospace exemplify the platform-control archetype through long-term OEM relationships. Safran S.A. occupies a specialized position within the pneumatic architecture segment. These three entities anchor the competitive landscape by controlling specification access for new aircraft programs and fleet retrofit cycles.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Collins Aerospace |
| Safran S.A. |
| Rolls-Royce Holdings plc |
| MTU Aero Engines AG |
| Pratt & Whitney |
| General Electric Company |
| Liebherr Group |
| AMETEK, Inc. |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific freight corridors linking Shanghai to Long Beach transmit alloy cost volatility directly into cooling turbine pricing, concentrating margin pressure on suppliers without captive nickel sourcing while amplifying premiums for configured-to-order units with FAA-EASA dual certification.
Pricing Analysis
The customization-premium spread separates standard axial configurations from variable-speed units with electronic inlet guide vane modulation. Contract-based long-term offtake dominates OEM relationships, while spot procurement governs airline retrofit purchases. Price differentiation rests on certification tier and after-sales service bundling. Cost compression in the standard axial segment is intensifying because airlines consolidate contracts with tier-one integrators. Low-cost carriers in India exhibit highest price sensitivity; Gulfstream and Dassault business jet programs show lowest sensitivity due to performance-critical specifications.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized turbomachinery foundries in the United States, Germany, and Japan holding high-speed rotor capacity. Nickel-based superalloys, precision air bearings, and electronic control modules anchor raw material dependencies. Single-source vulnerability concentrates in superalloy forging for rotors exceeding 50,000 RPM operational thresholds. Distribution runs through sole-source OEM agreements for new platforms and independent aftermarket channels for fleet maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft cooling turbines fragment across pneumatic legacy, electric transition, and hybrid bridge architectures, creating niche entry points as airframers split procurement between established suppliers and emerging thermal management specialists.
For Market Incumbents: Build certification moats by accelerating FAA-EASA dual qualification for variable-speed units before electric architectures achieve scale. Deepen backward integration into nickel superalloy sourcing to neutralize input volatility. Lock in sole-source renewals on Boeing 737 MAX and Airbus A320neo programs before hybrid thermal systems reach production readiness.
For New Entrants and Emerging Players: Establish a beachhead in unmanned aerial vehicle thermal systems where miniature turbomachinery requirements outpace incumbent R&D bandwidth. Target high-altitude long-endurance platforms at General Atomics and Northrop Grumman with reduced maintenance interval designs. Pursue direct qualification with CAAC for COMAC C919 second-source opportunities.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with orphaned aerospace turbomachinery divisions lacking scale for standalone R&D. Long-term viability hinges on positioning across the pneumatic-to-electric transition window. Monitor Airbus and Boeing more-electric aircraft development milestones as inflection signals for installed base obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Sourcing | Captive supply of nickel-based rotor materials neutralizes price volatility from concentrated German and US suppliers. |
| Dual Certification Investment | Simultaneous FAA and EASA qualification compresses competitor entry timelines on next-generation narrow-body platforms. |
| Urban Air Mobility Thermal System Development | Battery thermal management architectures for Joby Aviation and Archer Aviation open adjacent revenue pools beyond traditional aviation. |
| Aftermarket Service Contract Consolidation | Long-term MRO agreements with Delta and United Airlines lock in recurring revenue against independent distributor encroachment. |
| Hybrid Pneumatic-Electric System Qualification | Dual-mode architectures bridge legacy fleet retrofit cycles and emerging more-electric aircraft specifications at Boeing and Airbus. |
Methodological Framework
Initial hypotheses were tested against primary input from environmental control system engineering directors, airline fleet procurement managers, MRO technical operations leads, and FAA certification specialists, and refined through secondary validation against EASA CS-25 regulatory filings, customs trade data for nickel alloy imports, SEC 10-K disclosures from tier-one suppliers, and aircraft production databases. Bottom-up unit economics triangulated with top-down fleet projection models.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling product type, application, technology, and end-user dimensions alongside airframe program lifecycle stages. CAGRs were derived from fleet replacement velocity and new platform delivery schedules. Forecast inputs incorporated bleed air optimization adoption curves and electric architecture transition timelines.
Macroeconomic conditions sit as an overlay; deviation in jet fuel price trajectories and commercial aviation traffic recovery would shift the trajectory. Quarterly review of Boeing and Airbus order backlogs, EASA F-Gas regulatory amendments, and nickel alloy spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
UAV Propulsion System Market
Aircraft Power Systems
Aircraft Electrical Power Distribution Systems Market
Aircraft Power Systems
Aviation High Speed Motor Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Low-Carbon Propulsion Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Gearbox Market