
 Aircraft Electrical Power Distribution Systems Market | 2026-2036
Aircraft Electrical Power Distribution Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Electrical Power Distribution Systems Market Insights
Aftermarket service revenue is tilting toward integrated power system upgrades as operators extend fleet lifecycles. Collins Aerospace leverages its position in solid-state distribution technology across multiple airframe programs. Safran Group anchors European aftermarket channels with specialized maintenance protocols for electromechanical components. Honeywell International Inc. competes through microprocessor-based control architectures that reduce weight and fault-response latency.
Aircraft electrical power distribution systems manage the generation, conversion, regulation, and routing of electrical energy throughout an airframe, typically operating at 115V AC at 400Hz or 28V DC with solid-state power controllers replacing traditional thermal circuit breakers. These systems enable the transition to more electric aircraft by replacing pneumatic and hydraulic actuation with electrically powered alternatives. AC systems retain the largest installed base across commercial fleets, though solid-state technology segments are expanding fastest as thermal efficiency and arc-fault containment requirements intensify. Microprocessor-based controls command premium positioning where airlines seek predictive load management and real-time diagnostic feedback.
FAA airworthiness directives and EASA certification specifications shape hardware qualification timelines, particularly for solid-state power distribution components subject to DO-160 environmental testing. The EU Green Deal and corresponding emissions benchmarks push OEMs toward lighter electrical architectures that reduce fuel burn. Stakeholders must monitor evolving standards for high-voltage DC distribution as next-generation aircraft platforms adopt 270V or 540V architectures.
Market Dynamics
The transition to more electric aircraft architectures is compressing traditional power distribution paradigms, forcing rapid replacement of electromechanical components with solid-state alternatives across commercial and military platforms.
Growth Catalysts
- FAA Certification Modernization:Streamlined airworthiness pathways for solid-state power controllers accelerate OEM adoption timelines for next-generation aircraft programs.
- Electrification of Flight Controls:Hydraulic and pneumatic actuation replacement with electrically powered alternatives multiplies distribution system complexity and component count per airframe.
- EU Green Deal Emissions Benchmarks:Mandated fuel efficiency improvements drive weight reduction imperatives that favor lighter electrical architectures over conventional power distribution.
Market Restraints
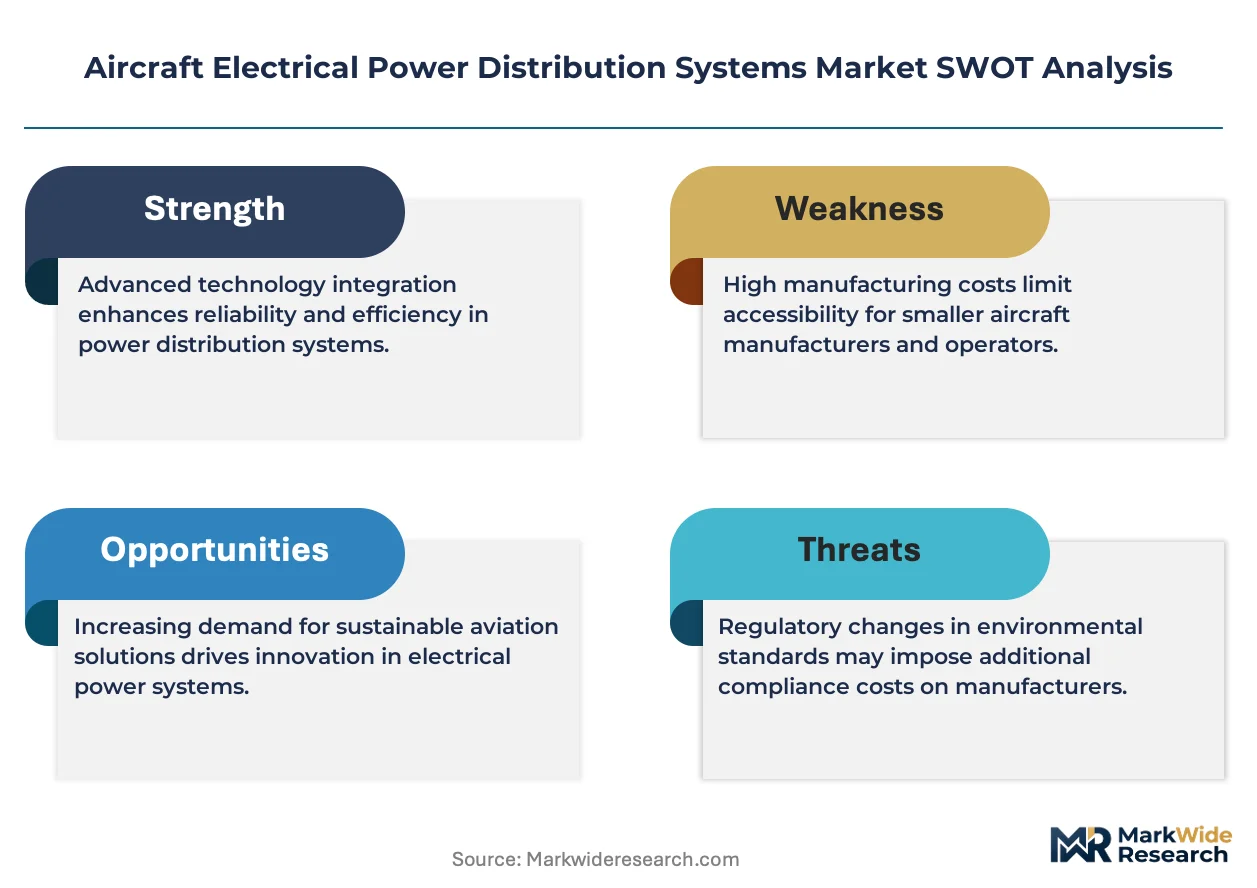
- DO-160 Qualification Costs:Environmental testing requirements for solid-state components impose substantial upfront validation expenses that constrain mid-tier supplier participation.
- Semiconductor Supply Concentration:Dependence on specialized silicon carbide and gallium nitride foundries in East Asia creates vulnerability to geopolitical trade disruptions.
- Thermal Management Limitations:Power density increases in compact solid-state controllers generate heat dissipation challenges that restrict packaging flexibility.
Strategic Opportunities
- Urban Air Mobility Segment:Electric vertical take-off and landing aircraft platforms require entirely novel 270V DC distribution architectures absent legacy constraints.
- India Defense Modernization:Indigenous combat aircraft programs under the Ministry of Defence create demand for import-substituted power distribution systems with localized certification.
- High-Voltage DC Convergence:Integration of 540V bus architectures with battery-electric propulsion systems opens greenfield design opportunities unencumbered by AC legacy standards.
Industry Challenges
- Embedded Software Certification:DO-178C compliance for microprocessor-based power controllers demands specialized avionics software engineering talent in short supply.
- Legacy Fleet Integration:Retrofitting solid-state distribution into 115V AC airframes requires complex interface engineering with existing electromechanical protection schemes.
- Cross-Platform Standardization Delays:Competing OEM proprietary bus architectures impede component interoperability and economies of scale across supplier bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Electrical Power Distribution Systems Market |
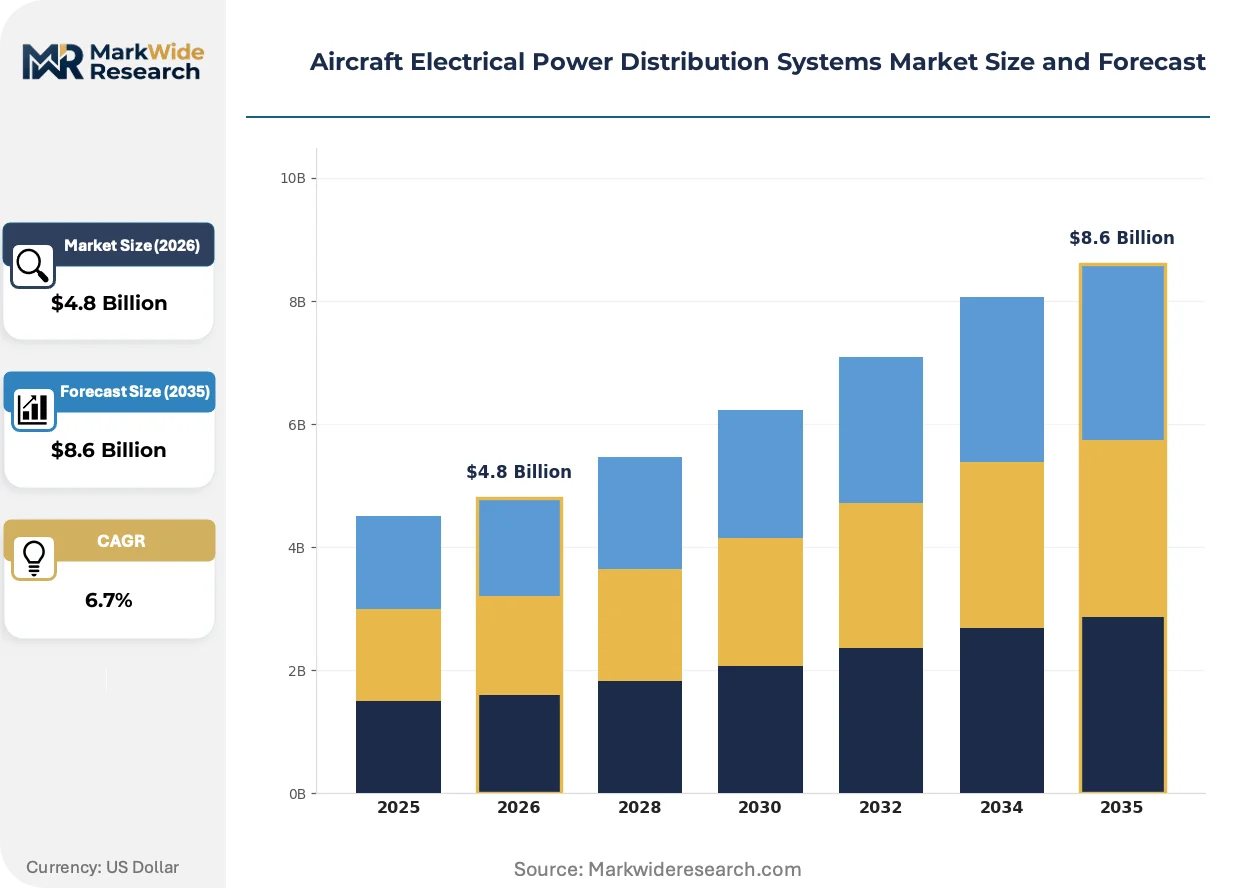
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: AC Systems, DC Systems, Integrated Power Systems, Hybrid Systems Technology: Solid State, Electromechanical, Hydraulic, Pneumatic, Microprocessor-Based Application: Commercial Aviation, Military Aircraft, Business Jets, Unmanned Aerial Vehicles, Rotorcraft End User: Original Equipment Manufacturers, Maintenance Providers, Retrofitters, Airlines |
| Companies Covered | AMETEK Inc., Thales Group, Collins Aerospace, Parker Hannifin Corp, Astronics Corporation, Safran Group, Crane Aerospace & Electronics, RTX Corporation, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Electrical Power Distribution Systems Market Trends and Innovations
Solid-state power distribution technology is fundamentally restructuring aircraft electrical architectures, eliminating electromechanical failure modes while introducing new design constraints around thermal management and electromagnetic compatibility.
Silicon carbide power semiconductors enable higher switching frequencies and reduced thermal losses in solid-state power controllers. Airlines operating long-haul widebody fleets are adopting these devices fastest where fuel burn reductions compound across flight hours. This transition is collapsing the installed base of thermal circuit breakers and electromechanical contactors within a single aircraft generation cycle.
EASA certification specifications for arc-fault containment now mandate advanced detection algorithms in power distribution units. Hardware manufacturers must demonstrate containment within milliseconds under DO-160 induced lightning conditions. European narrowbody programs face the most compressed compliance timelines as CS-25 amendments take effect retroactively on derivative aircraft designs.
Power-by-the-hour contracting models are displacing traditional component sales in aftermarket channels. Regional carriers and low-cost operators now bundle distribution system maintenance into airframe service agreements rather than managing spares inventories. This restructuring concentrates most visible in Southeast Asia where fleet expansion outpaces in-house technical capabilities.
Aircraft Electrical Power Distribution Systems Market Segmentation
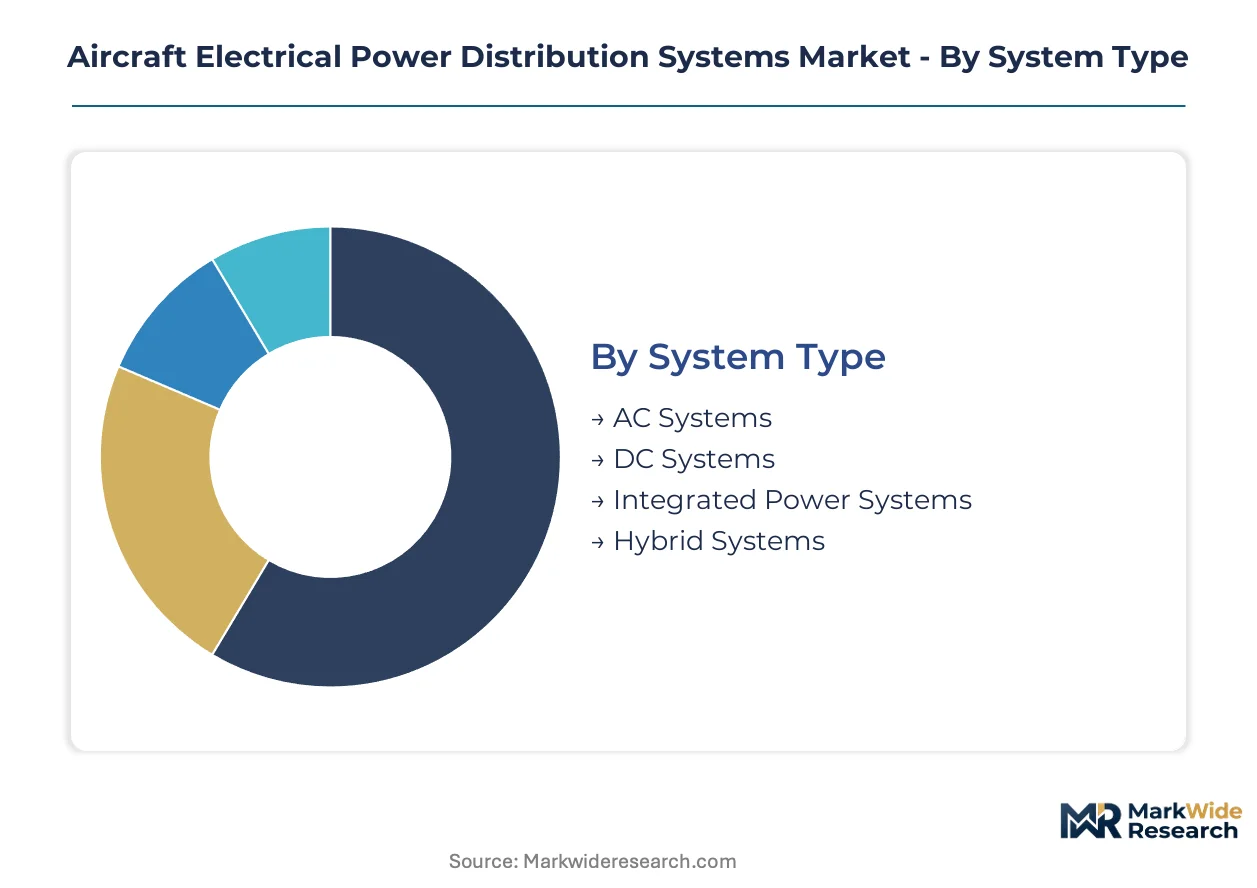
Aircraft electrical power distribution systems fragment across voltage architectures, control technologies, and airframe applications. Each segmentation axis carries distinct certification requirements and supplier capability thresholds that shape competitive positioning.
System Type:
Voltage architecture selection dictates thermal management requirements and component qualification pathways across airframe programs.
- AC Systems:These 115V AC at 400Hz architectures dominate existing commercial fleets with mature electromechanical protection schemes. Boeing 737 and Airbus A320 family programs in the United States and France anchor installed demand where operators prioritize proven mean-time-between-failure metrics over conversion costs.
- DC Systems:28V DC bus architectures serve auxiliary loads and battery backup functions with simpler protection requirements. Military transport programs under the US Air Force sustain procurement volumes where electromagnetic compatibility with legacy avionics remains mandatory.
- Integrated Power Systems:Unified generation-conversion-distribution architectures reduce wiring weight through centralized control.
- Hybrid Systems:AC primary with DC secondary buses optimize load matching across mixed-voltage airframe requirements.
AC Systems holds installed capacity. Integrated Power Systems is rotating up the share rankings.
Technology:
Control mechanism selection determines fault response speed, maintenance intervals, and qualification cost structures for OEM sourcing decisions.
- Solid State:Silicon carbide power controllers eliminate mechanical wear and enable millisecond arc-fault containment. FAA certification modernization for DO-160 lightning immunity is compressing adoption timelines at Boeing and Airbus supplier portals where thermal efficiency targets now outweigh upfront validation expenses.
- Electromechanical:Thermal circuit breakers and contactors retain cost advantages in non-critical load paths with established supply chains. Regional turboprop programs in Canada and Brazil specify these devices where procurement simplicity overrides weight optimization.
- Hydraulic:Fluid-power actuation persists in high-force flight control surfaces with integrated electrical monitoring.
- Pneumatic:Compressed air systems serve environmental control and engine starting with diminishing airframe penetration.
- Microprocessor-Based:Embedded control architectures enable predictive load management and real-time diagnostic telemetry. Business jet OEMs in the United States specify these controllers where power-by-the-hour contracts demand remote health monitoring capabilities.
Electromechanical retains volume concentration. Solid State is climbing the fastest as DO-160 qualification pathways mature.
Application:
Airframe category determines voltage level, redundancy requirements, and aftermarket service model structures.
- Commercial Aviation:Narrowbody and widebody programs drive highest absolute component demand with 115V AC standardization. Single-aisle fleet expansion at Southwest Airlines and Ryanair concentrates procurement leverage where power distribution unit standardization across Boeing 737 MAX and Airbus A320neo families enables supplier scale economies.
- Military Aircraft:Combat and transport platforms specify hardened architectures with nuclear electromagnetic pulse resilience. US Department of Defense programs under F-35 and B-21 development sustain dedicated supply chains where ITAR compliance restricts vendor pools.
- Business Jets:Fractional ownership models prioritize dispatch reliability through integrated diagnostic systems.
- Unmanned Aerial Vehicles:Swappable battery architectures favor modular 270V DC distribution with minimal certification heritage.
- Rotorcraft:Helicopter electrical loads concentrate in mission systems with severe weight constraints.
Commercial Aviation dominates procurement volume. Unmanned Aerial Vehicles is gaining share fastest as urban air mobility programs advance.
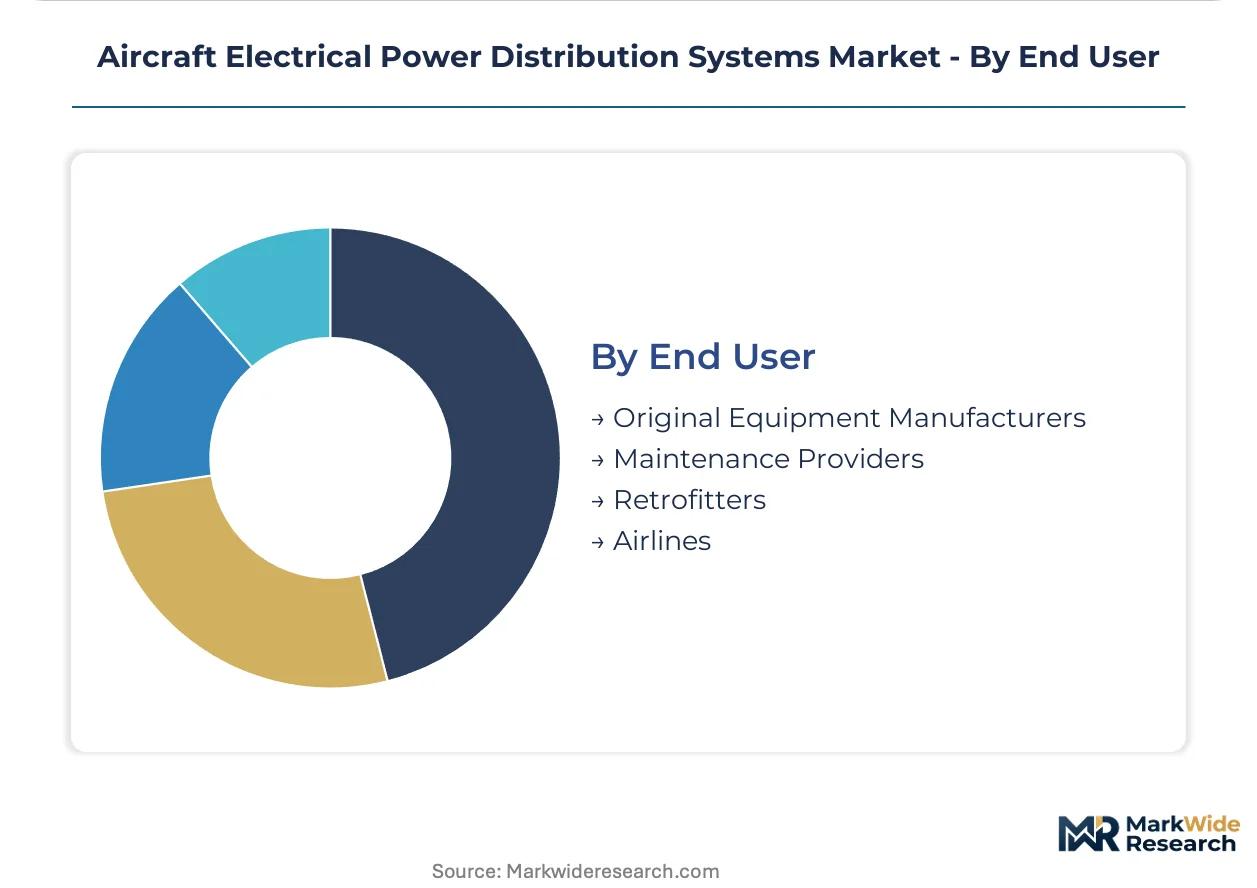
End User:
Procurement channel structure determines pricing mechanisms, technical specification authority, and inventory risk allocation.
- Original Equipment Manufacturers:Boeing, Airbus, and Lockheed Martin Martin control technical specifications and supplier qualification with long-term master agreements. These airframers in the United States and France concentrate design authority where power distribution architecture decisions cascade through tier-one electrical system integrators.
- Maintenance Providers:Third-party MROs manage component repair and overhaul with airline technical service agreements. ST Engineering and Lufthansa Technik in Singapore and Germany capture regional aftermarket concentration where power-by-the-hour contracts transfer inventory risk from operators.
- Retrofitters:Supplemental type certificate holders modify legacy fleet electrical systems for avionics upgrades.
- Airlines:Direct procurement concentrates in low-cost carriers with in-house engineering capabilities.
Original Equipment Manufacturers anchor design-in relationships. Maintenance Providers is expanding fastest as fleet ages and outsourcing deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States operators prioritize integrated power system retrofits for aging narrowbody fleets, while European carriers emphasize lightweight architectures aligned with emissions mandates. Asian defense programs drive indigenous certification pathways absent Western supply chain dependencies.
United States
Boeing 737 MAX production rates and F-35 program scale sustain demand for 115V AC distribution systems with solid-state upgrades. FAA certification modernization for DO-160 lightning immunity compresses supplier qualification timelines. Seattle-Tacoma aerospace corridor concentrates tier-one electrical system integrators serving both commercial and military platforms.
France
Airbus A320neo family expansion and Rafale export programs anchor procurement volumes for electromechanical-to-solid-state transitions. EASA CS-25 amendments for arc-fault containment mandate faster fault-response capabilities across narrowbody derivatives. Toulouse-Blagnac aerospace cluster hosts Safran Group operations specialized in power distribution maintenance protocols.
Germany
Lufthansa Technik's aftermarket power-by-the-hour contracts reshape regional carrier procurement models toward bundled service agreements. EU Green Deal fuel efficiency benchmarks drive weight reduction imperatives favoring integrated power architectures. Hamburg aviation maintenance hub concentrates MRO capacity for solid-state distribution system overhauls.
China
COMAC C919 indigenous narrowbody program creates demand for import-substituted power distribution systems with localized certification pathways. MIIT standards for high-voltage DC architectures in next-generation platforms diverge from Western 115V AC conventions. Shanghai-Pudong aerospace manufacturing base hosts state-owned avionics suppliers developing 270V DC distribution capabilities.
India
Ministry of Defence programs for Tejas light combat aircraft and AMCA next-generation fighter sustain procurement for hardened 28V DC distribution with nuclear electromagnetic pulse resilience. CEA regulations for electrical system safety in indigenous platforms constrain foreign vendor participation. Bengaluru defense aerospace cluster concentrates Hindustan Aeronautics Limited operations with captive power distribution development.
Aircraft Electrical Power Distribution Systems Market Competitive Landscape
Capability concentration sits with integrated system architects; scale advantage sits with component specialists serving multiple airframe programs. The vendor base stratifies across three tiers: full-service electrical system integrators owning generation-through-distribution architectures; solid-state power controller specialists commanding premium positioning in retrofit channels; and electromechanical component suppliers defending installed base maintenance revenue. Consolidation pressure intensifies as OEMs reduce qualified supplier lists to streamline certification liability. Strategic partnerships between semiconductor foundries and distribution system houses represent the dominant competitive move, followed by geographic expansion into India and Southeast Asian defense programs.
Within the integrated system tier, Collins Aerospace and Honeywell International Inc. exemplify full-architecture capability spanning generation, conversion, and distribution functions. Safran Group anchors European aftermarket positioning through specialized maintenance protocols. These three entities represent contrasting geographic bases—American, American, and French respectively—each occupying positions tied to their home regulator relationships and domestic airframe manufacturer proximity.
| Leading Market Players |
|---|
| AMETEK Inc. |
| Thales Group |
| Collins Aerospace |
| Parker Hannifin Corp |
| Astronics Corporation |
| Safran Group |
| Crane Aerospace & Electronics |
| RTX Corporation |
| Honeywell International Inc. |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Pudong to Hamburg air freight corridor's rate volatility transmits directly into landed costs for silicon carbide wafers and gallium nitride substrates, compressing margins for solid-state power controller manufacturers while amplifying price premiums on expedited delivery tiers for narrowbody retrofit programs.
Pricing Analysis
Long-term offtake agreements between tier-one electrical system integrators and semiconductor foundries dominate procurement, locking in volume commitments across multi-year horizons. Pricing stratifies across DO-160 qualification tiers, with certified components commanding substantial premiums over pre-qualified alternatives. Cost compression in electromechanical replacement segments is intensifying because regional carriers prioritize lowest-acquisition-cost sourcing for non-critical load paths. Low-cost operators in Southeast Asia exhibit highest price sensitivity, whereas business jet OEMs in the United States demonstrate lowest sensitivity due to power-by-the-hour contract bundling.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for specialized power semiconductor sourcing. Manufacturing concentrates in Taiwan, South Korea, and Japan for silicon carbide substrates and epitaxial wafer processing. Raw material dependencies include high-purity silicon carbide boules, gallium nitride on silicon wafers, and aerospace-grade aluminum enclosures. Distribution runs through tier-one electrical system integrators with captive certification laboratories, limiting direct supplier access to airframe OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across voltage architectures and certification pathways creates multiple niche entry points, as the shift toward urban air mobility platforms with 270V DC requirements fragments standardization and opens greenfield design competitions outside legacy supplier relationships.
For Market Incumbents: Build regulatory moats through accelerated DO-178C software certification investment and captive arc-fault testing laboratories. Consolidate tier-two electromechanical suppliers to secure aftermarket maintenance revenue streams against emerging solid-state retrofit specialists. Deepen backward integration into silicon carbide wafer supply through strategic foundry partnerships in Taiwan and South Korea.
For New Entrants and Emerging Players: Urban air mobility OEMs in the United States and Germany represent the most penetrable entry point, as these platforms require entirely novel 270V DC distribution architectures absent legacy 115V AC constraints. India's indigenous combat aircraft programs under the Ministry of Defence offer second-mover advantage through localized certification partnerships with Hindustan Aeronautics Limited. Pursue qualification-as-a-service business models that transfer regulatory burden from cash-constrained eVTOL developers.
For Investors and Strategic Acquirers: Solid-state power controller specialists with mature DO-160 qualification heritage and established FAA/EASA regulator relationships represent the highest-conviction acquisition archetype. Long-term viability hinges on exposure to next-generation high-voltage DC platforms rather than legacy AC retrofit cycles. Watch for inflection signals in urban air mobility platform order backlogs and corresponding 270V DC architecture specification releases from emerging OEMs.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Secures captive wafer supply for Collins Aerospace and Honeywell amid Taiwan capacity constraints. |
| DO-178C Software Certification Investment | Accelerates microprocessor-based controller approval timelines at FAA certification offices. |
| Urban Air Mobility Platform Integration | Positions suppliers for 270V DC architecture design wins at Joby Aviation and Lilium. |
| India Defense Localization Partnership | Enables CEA-compliant certification pathways for Tejas and AMCA programs. |
| Power-by-the-Hour Service Expansion | Captures recurring revenue from Southeast Asian regional carriers outsourcing maintenance. |
Research Methodology
A spread of perspectives from electrical system integration engineers, FAA certification specialists, airline fleet managers, and semiconductor procurement directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with tier-one supplier executives and aftermarket service heads with secondary validation against EASA CS-25 amendment filings, DO-160 test reports, and customs trade data for power semiconductor imports. Bottom-up build-ups across voltage architecture segments were triangulated against top-down airframe production forecasts from Boeing and Airbus.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include voltage architecture type, control technology tier, airframe application category, and procurement channel structure. CAGRs were derived from regression analysis against fleet expansion projections and retrofit penetration curves. Industry-specific forecast inputs encompassed FAA certification modernization timelines and EU Green Deal emissions benchmark compliance deadlines.
Macroeconomic conditions sit as an overlay; deviation in jet fuel price trajectories and aerospace semiconductor capital expenditure cycles would shift the trajectory materially. Forecasts reflect documented assumptions regarding solid-state adoption rates and regulatory amendment implementation schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Micro Turbine Engine Market
Aircraft Power Systems
Military Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Aircraft Lift Control Devices Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Fluid Power Components Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Space Power System Hardware-in-the-Loop Test Platforms Market
Aircraft Power Systems
Aircraft Thrust Reverser Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Aircraft Cooling Turbines Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Aircraft Electronic Ignition System Market