
 Electrified Aircraft Propulsion Market | 2026-2036
Electrified Aircraft Propulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Electrified Aircraft Propulsion Market Intelligence
OEM-direct procurement channels is rewriting how electrified propulsion suppliers reach aircraft integrators, bypassing traditional tier-one avionics distributors. Airbus leverages captive engineering partnerships to secure early access to megawatt-class motor designs. Rolls-Royce anchors its position through vertical integration into power electronics and thermal management subsystems. Safran competes via specialized electric actuator and generator portfolios purpose-built for hybrid architectures.
Electrified aircraft propulsion encompasses electric motors, power converters, energy storage systems, and thermal management hardware that replace or augment conventional turbine thrust generation, typically operating at power densities exceeding 10 kilowatts per kilogram for aviation-grade applications. The technology serves to reduce fuel consumption, emissions, and operating costs across commercial and military flight profiles. Battery electric systems currently occupy the most visible development lane for urban air mobility and training aircraft, while hybrid electric architectures dominate commercial short-haul roadmaps due to energy density constraints in lithium-ion cell chemistries. Fuel cell propulsion represents the fastest-growing technology segment for regional cargo routes where hydrogen infrastructure investment is accelerating.
The FAA governs airworthiness certification pathways for electric propulsion under Part 23 and Part 33 reforms, while EASA's CS-23 framework adapts to novel powertrain architectures through special conditions. The EU Green Deal binds member states to fleet decarbonization targets that mandate zero-emission regional aircraft deployment by mid-century, directly shaping OEM product roadmaps. Stakeholders must monitor certification harmonization progress between Washington and Brussels, as divergent standards would fragment platform development economics and supplier qualification burdens.
Market Dynamics
Airworthiness certification harmonization between Washington and Brussels is compressing development timelines for electric propulsion architectures, forcing suppliers to engineer for dual-jurisdiction qualification from prototype stage.
Growth Catalysts
- EU Green Deal fleet mandates:Binding decarbonization targets require zero-emission regional aircraft deployment by 2050, compelling OEMs to accelerate hybrid-electric roadmaps and lock in propulsion supplier contracts.
- Urban air mobility demand:Short-range aerial vehicle operators in Germany, France, and the United States are expanding procurement of battery-electric systems for pilot training and intracity shuttle routes.
- Megawatt-class motor maturation:Advances in silicon carbide power electronics and high-temperature superconducting materials are pushing aviation-grade power densities past 10 kilowatts per kilogram.
Market Restraints
- Lithium-ion energy density ceiling:Current cell chemistries cap all-electric range to sub-500 kilometer missions, constraining commercial short-haul adoption and forcing hybrid architectures for longer routes.
- Power electronics supply concentration:Wide-bandgap semiconductor fabrication clusters in Taiwan and South Korea create single-source vulnerability for inverter and converter subsystems.
- FAA-EASA certification divergence:Misaligned special conditions for novel powertrain architectures under Part 23 reforms and CS-23 adaptations force redundant testing protocols.
Strategic Opportunities
- Hydrogen fuel cell regional cargo:Accelerating infrastructure investment in Germany, the Netherlands, and Japan opens deployment corridors for fuel cell propulsion on 500-1000 kilometer freight routes.
- Thermal management subsystem specialization:Liquid cooling and phase-change materials represent underdeveloped supplier niches as power densities climb and heat rejection requirements intensify.
- India PLI scheme leverage:Production-linked incentives for advanced chemistry cell manufacturing could anchor battery pack assembly for Southeast Asian urban air mobility markets.
Industry Challenges
- Multiphysics simulation talent scarcity:Electromagnetic-thermal-structural coupled modeling expertise concentrates in aerospace primes and select German automotive suppliers, constraining tier-two engineering capacity.
- Legacy airframe integration friction:Retrofitting electric propulsion into certified turbine platforms requires structural modifications that trigger full recertification cycles under FAA Part 25 and EASA CS-25.
- Intellectual property thickets:Overlapping patent estates in axial-flux motor topologies and integrated motor-drive architectures complicate freedom-to-operate analysis for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrified Aircraft Propulsion Market |
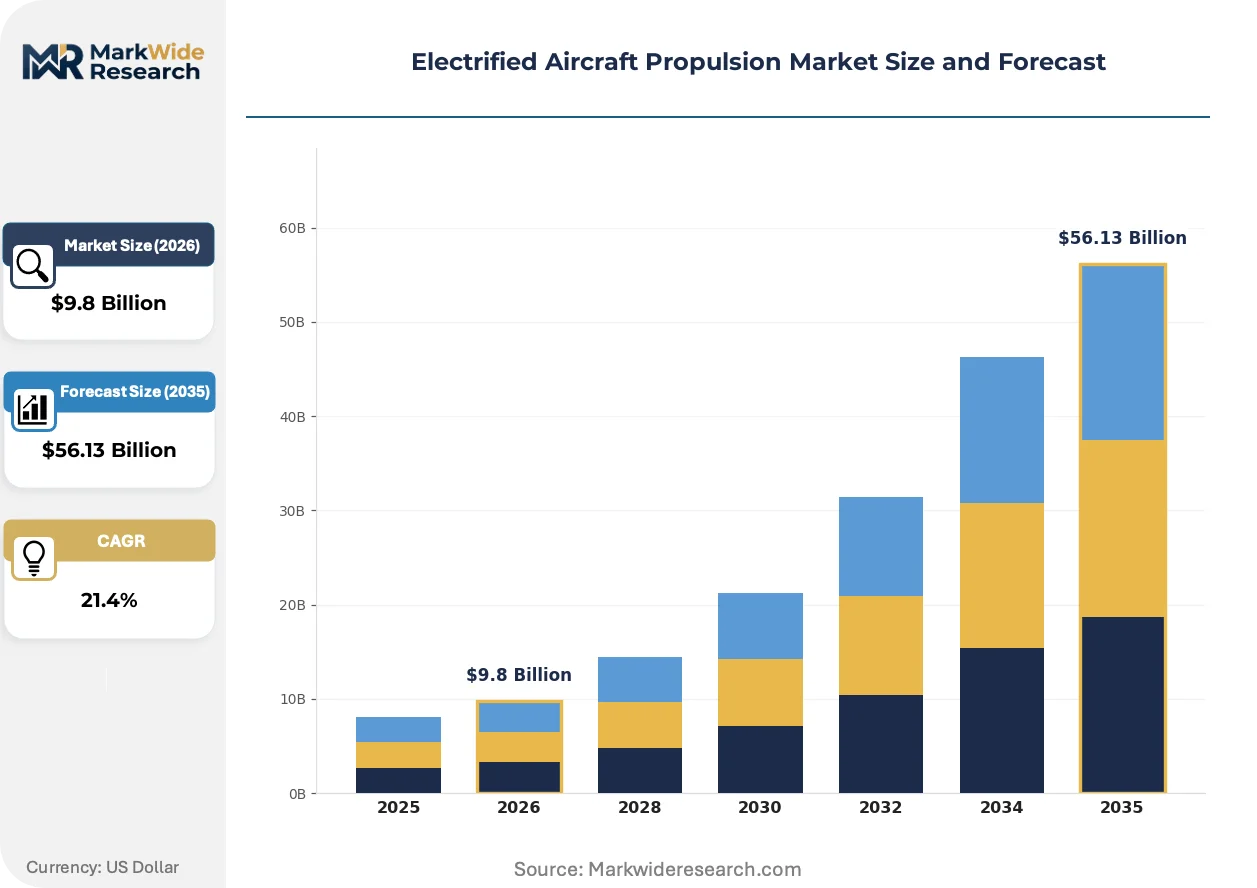
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $56.13 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Battery Electric, Hybrid Electric, Fuel Cell, Turboelectric End User: Commercial Aviation, Military Aviation, Cargo Transport, Urban Air Mobility Application: Short Haul Flights, Long Haul Flights, Cargo Operations, Training Flights Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Airbus, Rolls-Royce, GE Aviation, Honeywell International, Safran, Raytheon Technologies, Thales Group, Meggitt, Astronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrified Aircraft Propulsion Market Strategic Shifts & Innovations
Digital twin architectures and model-based systems engineering are displacing document-centric certification approaches, compressing validation cycles for electric propulsion integration.
Silicon carbide MOSFET modules are digitizing power conversion efficiency in aviation-grade inverters, cutting switching losses by half against silicon IGBT predecessors. Urban air mobility OEMs in the United States and Germany are adopting these devices for 800-volt architectures. The shift is digitizing thermal management system design by enabling higher frequency operation with reduced cooling overhead.
EASA's CS-23 special conditions for electric and hybrid propulsion are forcing concurrent type certification of batteries, motors, and power distribution as unified systems rather than discrete components. This regulatory consolidation eliminates modular substitution pathways that characterized turbine-era procurement. Short-haul commercial programs face the steepest compliance burden as they balance hybrid architecture complexity against single-fault tolerance requirements.
Airline procurement departments are consolidating electric propulsion vendor panels around vertically integrated suppliers capable of delivering motor-inverter-thermal packages as unified line-replaceable units. This behavior is displacing the tiered avionics distribution model that historically separated component sourcing from system integration. The pattern is most visible in European flag carrier RFPs for 19-seat hybrid commuter programs.
Electrified Aircraft Propulsion Market Segmentation
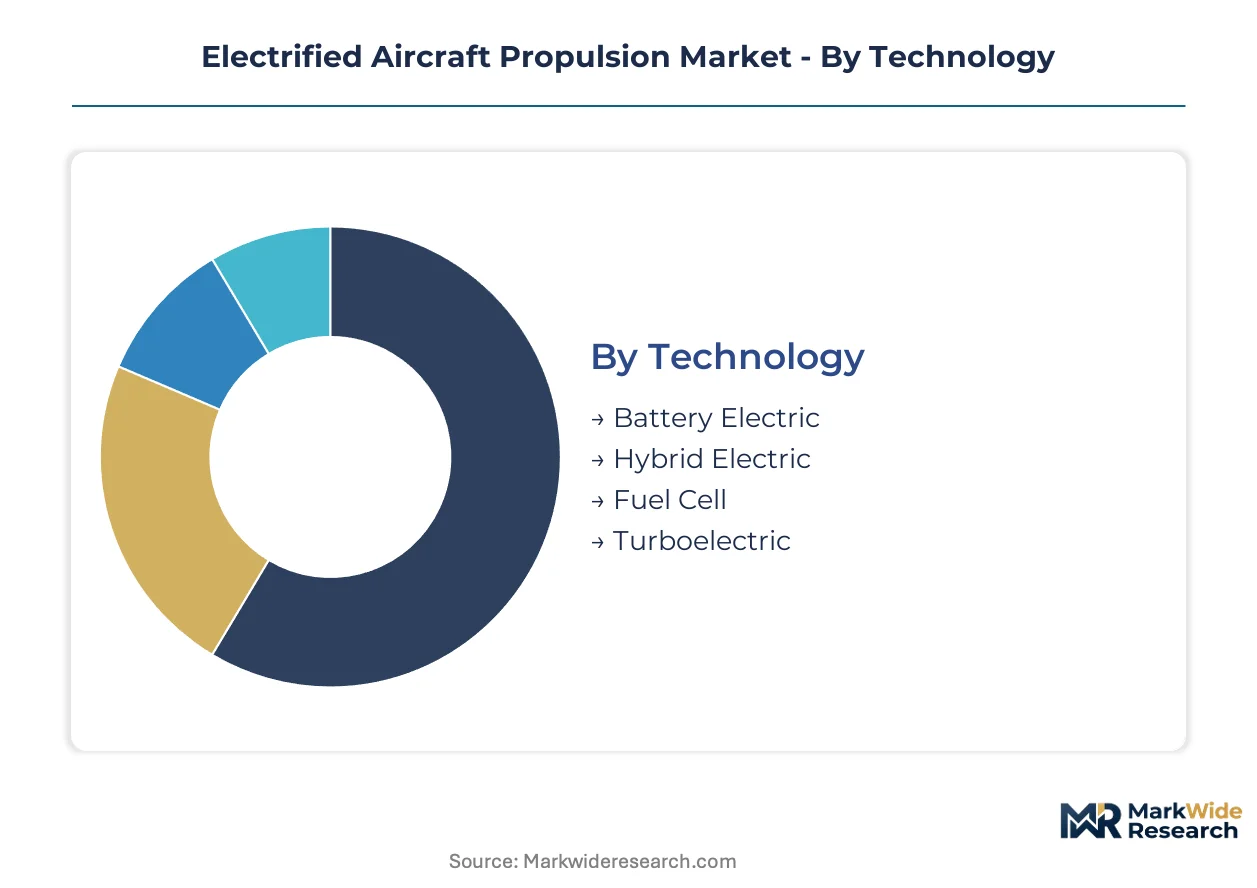
Segmentation in electrified aircraft propulsion reveals how energy density constraints, certification pathways, and mission profiles fragment technology adoption. Each dimension exposes distinct supplier capabilities and customer procurement patterns across aviation subsectors.
Technology:
Powertrain architectures span the full spectrum from all-electric elimination of combustion to turbine-electric distributed thrust arrangements.
- Battery Electric:Lithium-ion cell packs power motors directly, delivering zero-emission operation for missions under 500 kilometers. Urban air mobility operators in Germany and the United States dominate procurement for pilot training and intracity shuttle routes where range constraints are acceptable.
- Hybrid Electric:Turbogenerator-electric combinations preserve fuel flexibility while downsizing conventional engines. Commercial short-haul programs concentrate demand here as OEMs balance decarbonization mandates against lithium-ion energy density ceilings on routes exceeding regional distances.
- Fuel Cell:Hydrogen proton-exchange membrane stacks generate electricity for electric motors, enabling longer zero-emission missions than battery alternatives. Infrastructure investment corridors in Germany, the Netherlands, and Japan are accelerating procurement for 500-1000 kilometer cargo routes.
- Turboelectric:Gas turbines drive generators that power distributed electric fans or propellers, decoupling engine placement from thrust generation. Military aviation programs explore this architecture for enhanced survivability through redundant power distribution.
The dominant share belongs to Hybrid Electric, while Fuel Cell is closing the gap fastest.
End User:
Customer procurement patterns diverge sharply between regulated commercial operators and mission-driven military buyers.
- Commercial Aviation:Flag carriers and regional operators pursue hybrid-electric retrofits and clean-sheet designs under EU Green Deal fleet mandates. EASA CS-23 special conditions force concurrent certification of batteries, motors, and power distribution as unified systems.
- Military Aviation:Defense procurement prioritizes survivability and operational flexibility over fuel efficiency metrics. Turboelectric architectures attract development funding for their distributed thrust survivability advantages.
- Cargo Transport:Freight operators value payload-range economics over passenger comfort, making hydrogen fuel cell architectures viable earlier. Dedicated cargo corridors between industrial clusters in Germany and the Netherlands anchor initial deployment.
- Urban Air Mobility:Electric vertical takeoff and landing operators procure battery-electric systems exclusively for intracity missions under 100 kilometers. FAA Part 23 reforms and EASA CS-23 adaptations compress certification timelines for these novel aircraft categories.
Commercial Aviation commands the largest procurement volume, though Urban Air Mobility is expanding most quickly.
Application:
Mission duration and operational tempo dictate powertrain selection more than airframe size alone.
- Short Haul Flights:Regional routes under 800 kilometers suit hybrid-electric architectures balancing battery weight against turbine redundancy. European flag carrier RFPs for 19-seat hybrid commuter programs concentrate supplier competition.
- Long Haul Flights:Transcontinental missions remain beyond current battery-electric feasibility, driving turboelectric and hydrogen combustion research. No commercial deployments operate yet.
- Cargo Operations:Predictable schedules and hub-and-spoke infrastructure enable hydrogen fuel cell adoption on medium-haul freight corridors. Dedicated cargo operators pilot these systems between German industrial zones.
- Training Flights:Repetitive pattern work and short durations make battery-electric ideal for flight schools. Urban air mobility OEMs in the United States and Germany supply this segment with 800-volt architectures using silicon carbide power electronics.
Short Haul Flights absorb the majority of current investment, while Cargo Operations show the steepest expansion trajectory.
Power Rating:
Aviation-grade power density requirements stratify supplier capabilities and semiconductor technology choices.
- Low Power:Systems under 100 kilowatts serve training aircraft and light urban air mobility vehicles. Silicon carbide MOSFET modules enable these architectures with reduced thermal management overhead.
- Medium Power:100-500 kilowatt systems power regional commuters and cargo drones. Megawatt-class motor maturation in silicon carbide electronics pushes aviation-grade power densities past 10 kilowatts per kilogram.
- High Power:500 kilowatt to 2 megawatt systems target short-haul commercial aircraft. Thermal management specialization in liquid cooling and phase-change materials becomes critical at this scale.
- Ultra High Power:Exceeding 2 megawatts, these systems remain developmental for single-aisle jet replacements. High-temperature superconducting materials research concentrates in German automotive-aerospace supplier clusters.
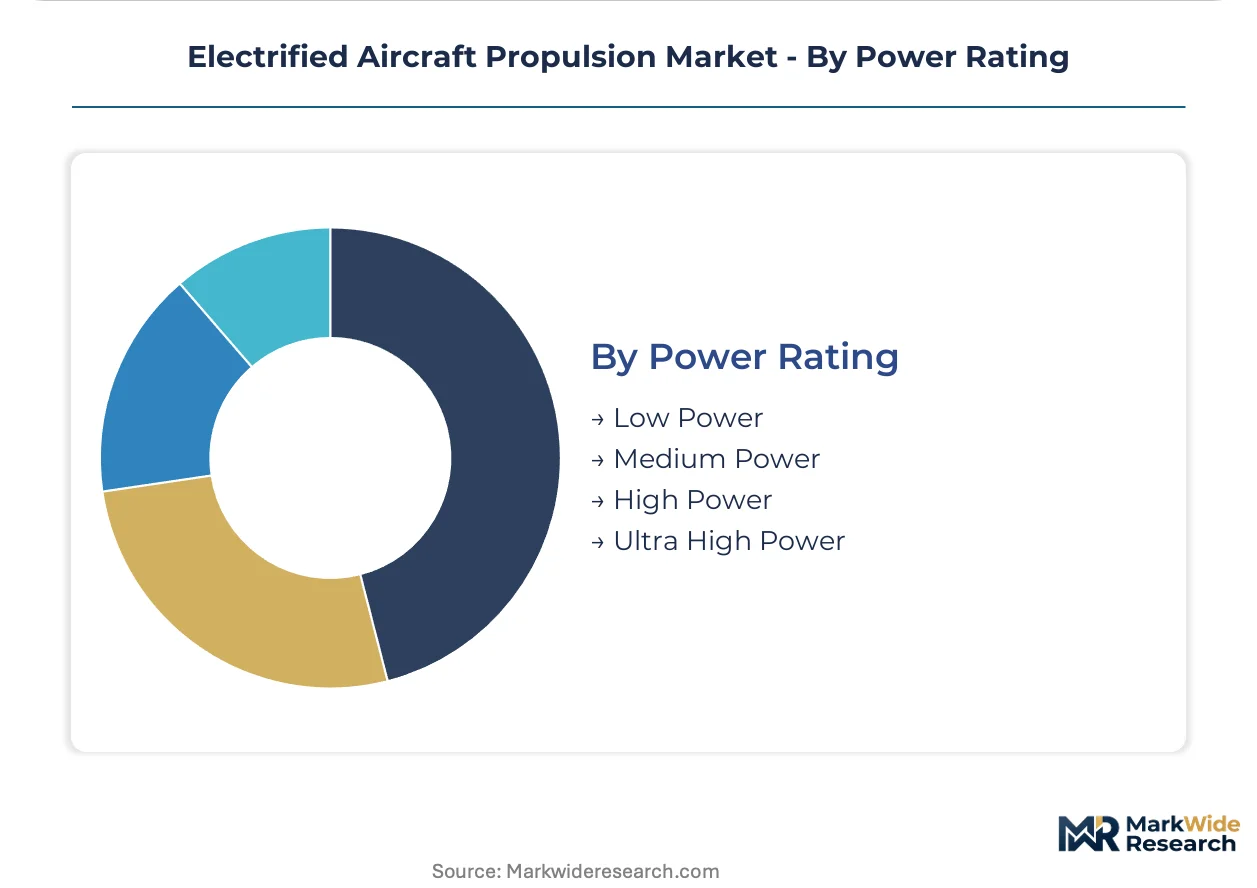
Medium Power systems dominate current procurement, though High Power is gaining share fastest as commercial programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA governs airworthiness certification pathways under Part 23 and Part 33 reforms, while EASA's CS-23 framework adapts through special conditions. Washington and Brussels anchor the regulatory divergence that shapes supplier engineering priorities across key development clusters.
Germany
Urban air mobility operators expand procurement of battery-electric systems for intracity shuttle routes. The EU Green Deal binds fleet decarbonization targets mandating zero-emission regional aircraft deployment by mid-century. Munich and Hamburg anchor clustered R&D facilities where hybrid-electric demonstrators advance megawatt-class motor maturation.
United States
FAA Part 23 reforms compress certification timelines for novel electric aircraft categories. The Inflation Reduction Act channels production-linked incentives toward advanced battery cell manufacturing. Los Angeles and Dallas-Fort Worth concentrate urban air mobility operator headquarters procuring 800-volt architectures.
France
Flag carriers issue RFPs for 19-seat hybrid commuter programs under EU Green Deal compliance pressure. EASA CS-23 special conditions force concurrent type certification of batteries, motors, and power distribution. Toulouse hosts captive engineering partnerships securing early access to aviation-grade power electronics.
United Kingdom
Defense procurement prioritizes turboelectric architectures for distributed thrust survivability advantages. The Civil Aviation Authority aligns with EASA frameworks for hybrid propulsion certification. Bristol and Derby anchor vertical integration into power electronics and thermal management subsystems.
Japan
METI accelerates hydrogen infrastructure investment opening deployment corridors for fuel cell propulsion. National hydrogen roadmaps target 500-1000 kilometer cargo routes between industrial clusters. Nagoya concentrates supplier development of high-temperature superconducting materials research.
Electrified Aircraft Propulsion Market Key Industry Players
Vertically integrated aerospace primes and specialized subsystem suppliers split the market into distinct capability tiers. Consolidation concentrates around entities commanding captive engineering partnerships and in-house production of power electronics. Three archetypes dominate: full-stack integrators controlling motor-inverter-thermal packages, component specialists in electric actuators and generators, and tier-two suppliers focused on thermal management hardware. Competitive moves center on strategic partnerships for megawatt-class motor access and backward integration into wide-bandgap semiconductor supply.
Within the full-stack integrator tier, Airbus and Rolls-Royce exemplify divergent strategic positioning. Airbus leverages captive engineering partnerships to secure early technology access, while Rolls-Royce anchors its position through upstream control over power electronics and thermal management. Safran occupies a position representing the component specialist archetype, with portfolios purpose-built for hybrid architectures. These three entities collectively illustrate how OEM-direct procurement channels displace traditional tier-one avionics distribution models across European flag carrier programs.
| Leading Market Players |
|---|
| Airbus |
| Rolls-Royce |
| GE Aviation |
| Honeywell International |
| Safran |
| Raytheon Technologies |
| Thales Group |
| Meggitt |
| Astronics Corporation |
| Others |
Cost & Logistics Intelligence
Taipei-Hsinchu semiconductor corridor capacity dynamics feed directly into inverter subsystem pricing power, as wide-bandgap fabrication bottlenecks concentrate negotiation leverage among a handful of foundry operators serving aviation-grade power electronics demand.
Pricing Analysis
Price spreads between German and South Korean motor-inverter packages reflect certification-grade differentiation rather than pure manufacturing cost, with EASA CS-23 special conditions adding 15-25% premium tiers for concurrent type-approved systems. Three-tier pricing structure across premium, standard, and economy levels stratifies around thermal management bundling and field service contract duration. Cost compression in medium-power segments is intensifying because silicon carbide MOSFET supply expansion outpaces demand growth from urban air mobility OEMs. Training aircraft operators exhibit highest price sensitivity due to thin fleet margins, while flag carriers prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for lithium-ion cell procurement, forcing dual-sourcing strategies that inflate working capital requirements. Wide-bandgap semiconductor fabrication draws from Taiwan, South Korea, and Japan; rare-earth magnet processing rests on Chinese separation capacity; and aviation-grade copper winding feeds from German and Austrian metallurgical specialists. Single-source vulnerability in silicon carbide substrate supply creates qualification bottlenecks stretching 18-24 months for new entrants. Distribution runs through OEM-direct channels that displace traditional tier-one avionics distributors, with Airbus and Rolls-Royce captive engineering partnerships controlling early access to megawatt-class designs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where thermal management subsystem contracts and predictive maintenance software subscriptions expand at multiples of hardware revenue growth, particularly as power densities climb past 10 kilowatts per kilogram.
For Market Incumbents: Build certification moats by accelerating FAA-EASA harmonization lobbying and pre-qualifying battery-motor-power distribution as unified line-replaceable units before competitors complete modular substitution pathways. Lock in exclusive silicon carbide supply agreements with Taiwanese foundries to deny emerging entrants access to 800-volt architecture components. Threat substitution from fuel cell regional cargo programs demands parallel hydrogen propulsion R&D investment to defend hybrid-electric positioning. For New Entrants and Emerging Players: Indian PLI scheme jurisdictions offer underpenetrated battery pack assembly opportunities for Southeast Asian urban air mobility markets, with production-linked incentives offsetting capital intensity disadvantages against established Chinese cell manufacturers. Target thermal management hardware specialization as the most penetrable niche, where liquid cooling and phase-change material expertise concentrates in German automotive-aerospace clusters and engineering talent scarcity constrains incumbent expansion. Go-to-market through joint development agreements with urban air mobility OEMs seeking second-source motor-inverter packages. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EU Green Deal fleet mandates and FAA reauthorization pressures create structural demand visibility independent of fuel price volatility, with decarbonization compliance becoming non-negotiable for flag carrier operating certificates. Acquisition focus should center on vertically integrated suppliers commanding in-house power electronics and thermal management production, or specialized electric actuator portfolios purpose-built for hybrid architectures. Signal to monitor: EASA-FAA special conditions convergence timeline, as harmonization acceleration would compress qualification economics and favor scaled incumbents over niche specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures 800-volt inverter capacity from Taiwanese foundries before qualification queues lengthen. |
| Thermal Management Specialization | Captures liquid cooling niche as power densities intensify heat rejection requirements beyond incumbent capacity. |
| Concurrent Certification Investment | Aligns battery-motor-power distribution as unified systems under EASA CS-23 special conditions before modular pathways close. |
| Hydrogen Fuel Cell R&D Partnership | Positions for regional cargo corridor deployment as METI and EU infrastructure investment accelerates. |
| Urban Air Mobility OEM Second-Source | Displaces captive engineering partnerships through competitive motor-inverter-thermal package offerings. |
Research Approach
Desk research of FAA Part 23 reform documentation, EASA CS-23 special conditions filings, EU Green Deal fleet mandate texts, and wide-bandgap semiconductor foundry capacity disclosures preceded structured interviews with electric propulsion system engineering directors, airworthiness certification managers at OEMs, airline procurement executives evaluating hybrid commuter RFPs, and thermal management subsystem specialists. Primary fieldwork combined with secondary validation from customs trade data, SEC aviation supplier filings, and national hydrogen roadmap publications. Bottom-up segment sizing triangulated against top-down OEM procurement pipeline estimates.
Assumptions held fixed include current lithium-ion energy density ceilings, existing FAA-EASA certification divergence timelines, and announced EU Green Deal compliance deadlines; variables tested across scenarios included hydrogen infrastructure buildout pace, silicon carbide substrate supply expansion, and urban air mobility operator fleet deployment acceleration. Segmentation modeling spanned technology architecture, end-user procurement pattern, mission application, and power rating tier across the projection horizon. CAGRs derived from regression analysis against OEM announced program entry-into-service dates and supplier contract visibility. Industry-specific inputs incorporated megawatt-class motor maturation curves and thermal management heat rejection scaling factors.
Macroeconomic conditions sit as an overlay; deviation in aviation fuel price volatility, interest rate environments affecting aircraft lessor fleet renewal decisions, or geopolitical disruption to rare-earth magnet supply chains would shift the trajectory. Forecasts reflect assumptions documented above and acknowledge regulatory harmonization delays, battery cell chemistry breakthroughs, or hydrogen infrastructure investment shortfalls as specific revision risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Low-Carbon Propulsion Market
Aircraft Power Systems
Aircraft Lift Control Devices Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Global Aircraft Electrification Market
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Aircraft Thrust Reverser Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Space Power System Hardware-in-the-Loop Test Platforms Market