
 Asia-Pacific Aircraft Circuit Breakers Market | 2026-2036
Asia-Pacific Aircraft Circuit Breakers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aircraft Circuit Breakers Market Insights
Buyer concentration among Asia-Pacific commercial aviation operators is consolidating as low-cost carriers in Indonesia, Vietnam, and the Philippines expand fleet commonality programs. Safran Group leverages its integrated electrical systems portfolio to anchor supply relationships with COMAC and regional tier-one distributors. Honeywell International competes through its smart power distribution architectures, while Sensata Technologies specializes in high-reliability thermal breaker solutions for narrow-body platforms.
Aircraft circuit breakers are electromechanical or solid-state protective devices that interrupt fault currents in onboard electrical distribution networks, typically rated for aerospace voltage classes and designed to withstand altitude-induced arc quenching challenges. Their primary purpose is to isolate short-circuit or overload conditions without crew intervention, preserving avionics, flight control, and cabin system integrity during transient electrical events. Electronic breakers are displacing hydraulic and magnetic variants across civil aviation applications as fly-by-wire architectures multiply discrete load channels. Smart circuit breaker technology captures expanding margin pools in integrated power management systems, whereas conventional thermal designs still dominate military aircraft retrofit budgets.
China's MIIT enforces GB standards alignment with airworthiness directives for indigenous commercial programs, while India's CEA and DGFT coordinate import substitution mandates through PLI-linked aerospace component certification. Japan's METI promotes JIS-compliant electrical system upgrades in next-generation regional jet development. Stakeholders must monitor divergence between Chinese domestic certification pathways and harmonized APAC safety frameworks as fleet electrification deepens.
Market Dynamics
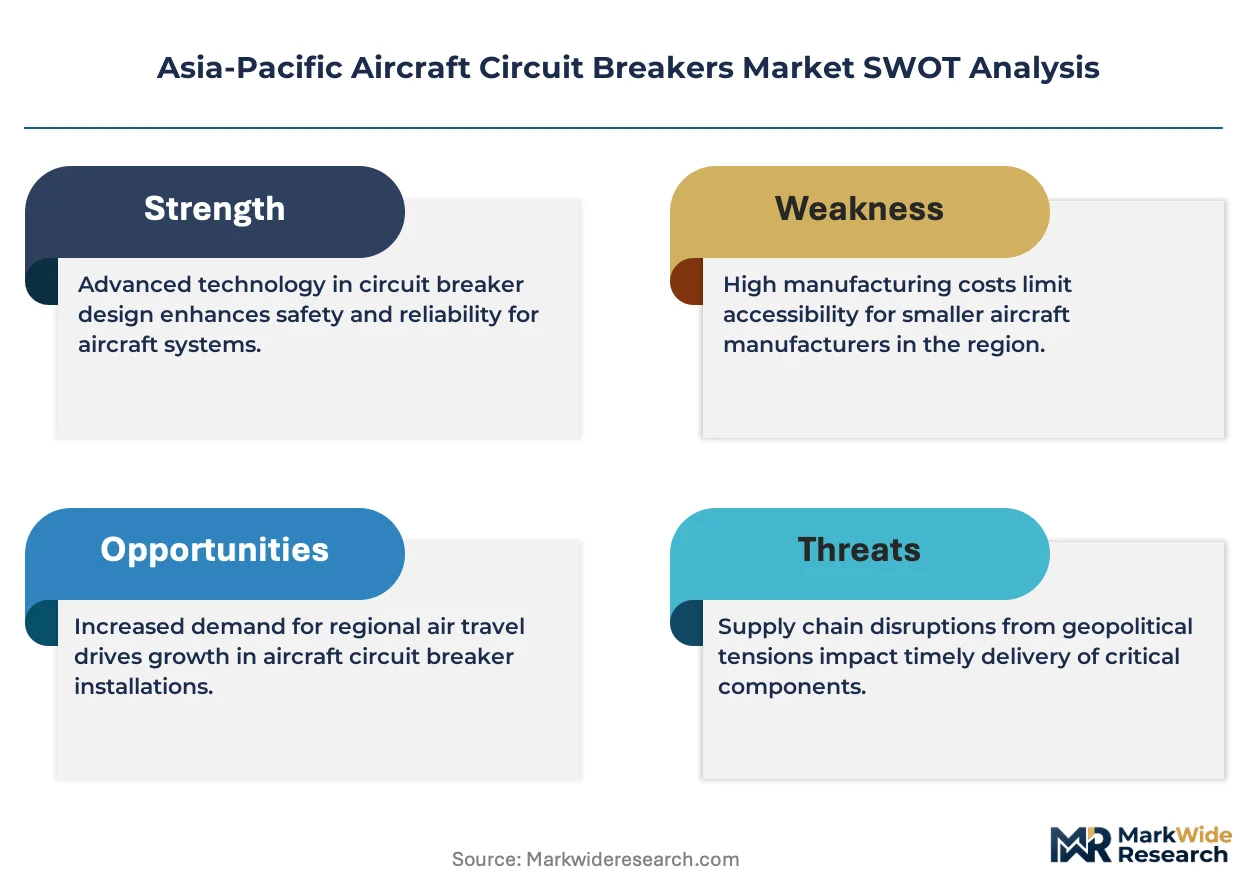
Solid-state power distribution is compressing procurement cycles across Asia-Pacific commercial aviation as fly-by-wire architectures multiply discrete load channels beyond legacy thermal breaker capacity.
Growth Catalysts
- COMAC supply chain localization:China's MIIT airworthiness directives for indigenous narrow-body programs mandate certified domestic electrical distribution components, creating captive demand for qualified circuit breaker suppliers.
- India's PLI-linked aerospace certification:The CEA and DGFT coordinate import substitution mandates that channel defense aviation modernization budgets toward indigenous component qualification.
- Solid-state thermal management:Electronic breakers with integrated arc fault detection are penetrating regional low-cost carrier retrofit programs as fleet commonality standards tighten.
Market Restraints
- Silver-copper alloy input volatility:Contact material costs swing with precious metal markets, compressing margins on high-current breaker variants.
- Single-source semiconductor dependency:Wide-bandgap power transistor supply concentrates in East Asian foundries, exposing lead time risks for solid-state breaker assemblers.
- Dual certification burden:China's GB standards divergence from harmonized APAC safety frameworks forces redundant testing for suppliers serving both domestic and export programs.
Strategic Opportunities
- Vietnam's emerging MRO hub:Da Nang and Ho Chi Minh City maintenance clusters lack qualified indigenous breaker suppliers, creating first-mover positioning for certified entrants.
- Urban air mobility electrical architectures:eVTOL platforms demand ultra-fast solid-state protection for high-voltage battery distribution networks.
- Japan's METI regional jet electrification:JIS-compliant electrical system upgrades for next-generation programs specify smart breaker integration with predictive load management.
Industry Challenges
- Embedded software certification backlog:DO-178C compliance for smart breaker firmware stretches development timelines as civil aviation authorities lack dedicated power electronics review capacity.
- Legacy magnetic breaker obsolescence management:Military retrofit programs require sustaining engineering for thermal-hydraulic designs no longer supported by original equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aircraft Circuit Breakers Market |
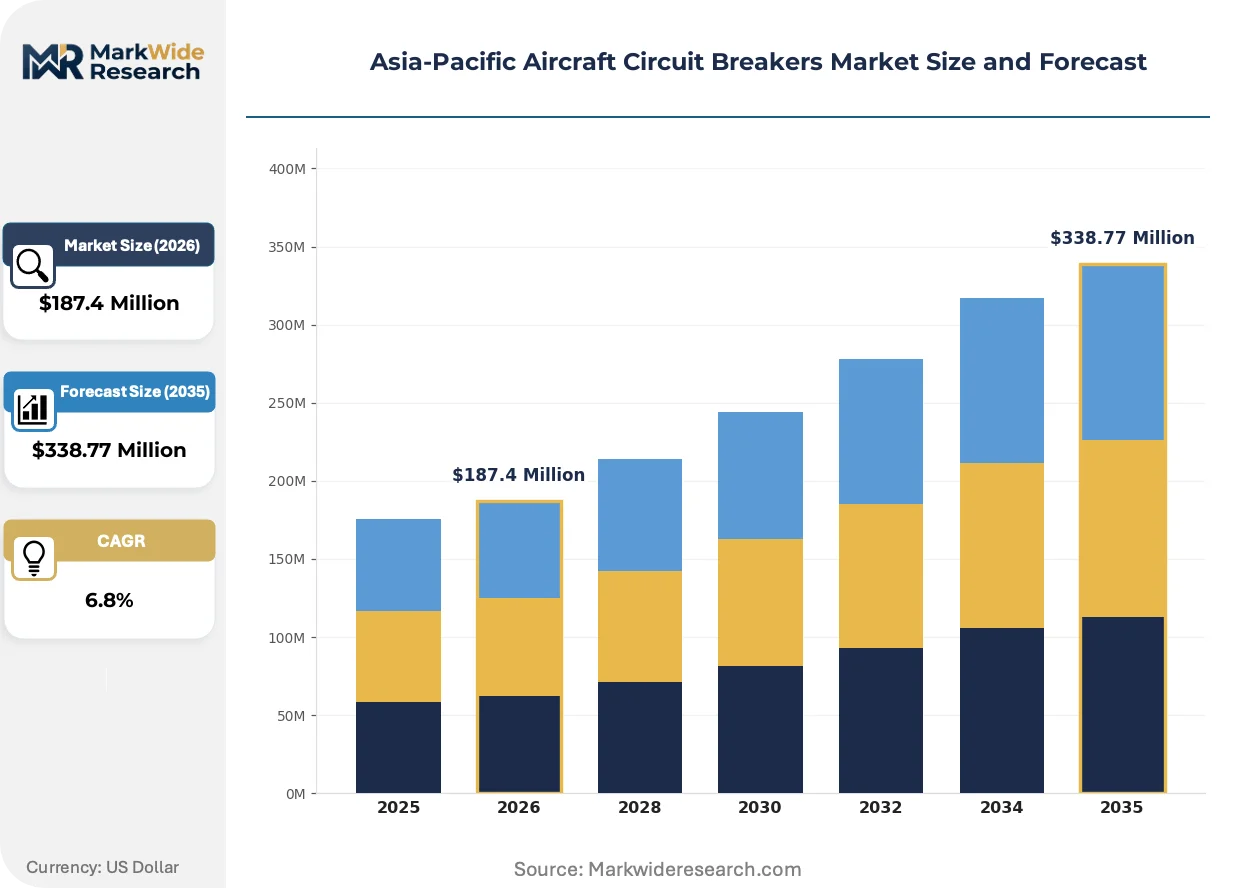
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electronic, Thermal, Magnetic Application: Civil Aviation, Military Aircraft, UAVs, Spacecraft End User: Aerospace Manufacturers, Maintenance Providers, Operators, Agencies Technology: Smart Circuit Breakers, Conventional Circuit Breakers, Integrated Systems, Modular Designs |
| Companies Covered | Safran Group, Collins Aerospace, Honeywell International, Sensata Technologies, Astronics Corporation, AMETEK, Crouzet, Eaton Aerospace, Commercial Aircraft Corporation of China Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aircraft Circuit Breakers Market Trends and Innovations
Power semiconductor integration is collapsing the boundary between protection and distribution management, enabling predictive electrical system architectures that anticipate rather than react to fault conditions.
Silicon carbide MOSFET arrays are electrifying solid-state breaker topologies for high-voltage DC distribution in next-generation commercial platforms. COMAC's C919 electrical system suppliers are qualifying these devices for 540VDC bus protection. The technology is electrifying competitive positioning as thermal-hydraulic breaker incumbents face capability gaps in high-speed current limiting.
China's MIIT is tightening GB standard alignment with airworthiness directives for indigenous commercial programs, forcing component suppliers into parallel certification tracks. The regulation compresses time-to-market for export-oriented products. India's defense procurement is responding with accelerated indigenous qualification timelines under PLI-linked aerospace component schemes.
Fleet commonality programs at Indonesian and Vietnamese low-cost carriers are consolidating supplier relationships around integrated electrical system portfolios. Regional distributors are losing share to direct OEM contracting for narrow-body platforms. The shift concentrates procurement leverage with Safran and Honeywell system integrators serving COMAC and Airbus Asia-Pacific final assembly lines.
Asia-Pacific Aircraft Circuit Breakers Market Segmentation
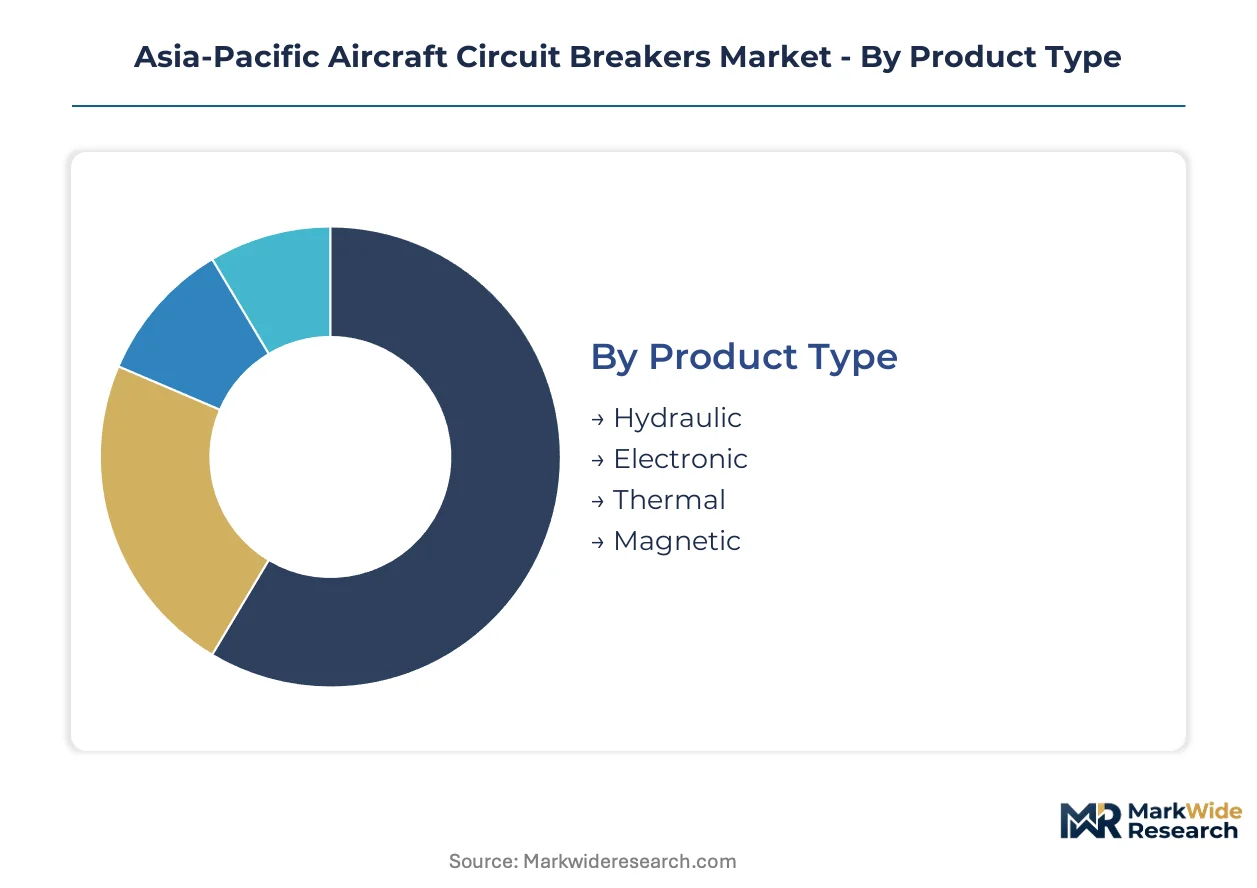
Segmentation in the Asia-Pacific aircraft circuit breakers market reflects divergent procurement priorities across defense modernization programs and commercial fleet electrification. Buyer decision criteria split sharply between legacy airworthiness certification requirements and emerging solid-state performance specifications.
Product Type:
Procurement cycles compress as fly-by-wire architectures multiply discrete load channels beyond legacy thermal breaker capacity.
- Electronic:Solid-state topologies employ silicon carbide MOSFET arrays for 540VDC bus protection in next-generation narrow-body platforms. China's COMAC supply chain mandates certified domestic electronic breaker suppliers under MIIT airworthiness directives, creating captive demand pools.
- Thermal:Bimetallic strip designs with silver-copper alloy contacts dominate military retrofit budgets where sustaining engineering for obsolete hydraulic variants strains OEM support. India's defense aviation modernization channels procurement toward indigenous thermal breaker qualification under PLI-linked aerospace component schemes.
- Hydraulic:Pneumatic-actuated designs persist in legacy wide-body fleets requiring arc quenching at extreme altitudes.
- Magnetic:Electromagnetic trip mechanisms serve high-current applications in cargo aircraft electrical distribution networks.
Volume sits with Thermal designs; growth tilts toward Electronic variants.
Application:
Certification burden intensity varies by platform maturity and operational criticality.
- Civil Aviation:Narrow-body platforms drive electronic breaker penetration as Indonesian and Vietnamese low-cost carriers consolidate fleet commonality programs. Regional distributors lose share to direct OEM contracting for integrated electrical system portfolios.
- Military Aircraft:India's CEA and DGFT coordinate import substitution mandates channeling defense modernization budgets toward indigenous component qualification. Thermal-hydraulic designs face obsolescence management challenges as original manufacturers exit legacy product support.
- UAVs:Miniaturized solid-state protection addresses high-voltage battery distribution in tactical unmanned platforms.
- Spacecraft:Radiation-hardened thermal breakers serve satellite electrical bus protection requirements.
Procurement scale concentrates in Civil Aviation; steepest expansion trajectory belongs to Military Aircraft.
End User:
Contracting leverage shifts with integration depth and fleet ownership structure.
- Aerospace Manufacturers:COMAC's C919 program and Japan's METI-sponsored regional jet development specify smart breaker integration with predictive load management. System integrators anchor supply relationships through bundled electrical distribution architectures.
- Maintenance Providers:Vietnam's emerging MRO hubs in Da Nang and Ho Chi Minh City lack qualified indigenous breaker suppliers, creating first-mover positioning for certified entrants.
- Operators:Fleet commonality programs consolidate supplier relationships around integrated electrical system portfolios serving Airbus Asia-Pacific final assembly lines.
- Agencies:Defense procurement authorities specify MIL-SPEC compliance for tactical aircraft electrical protection systems.
Revenue capture favors Aerospace Manufacturers; margin expansion targets Maintenance Providers.
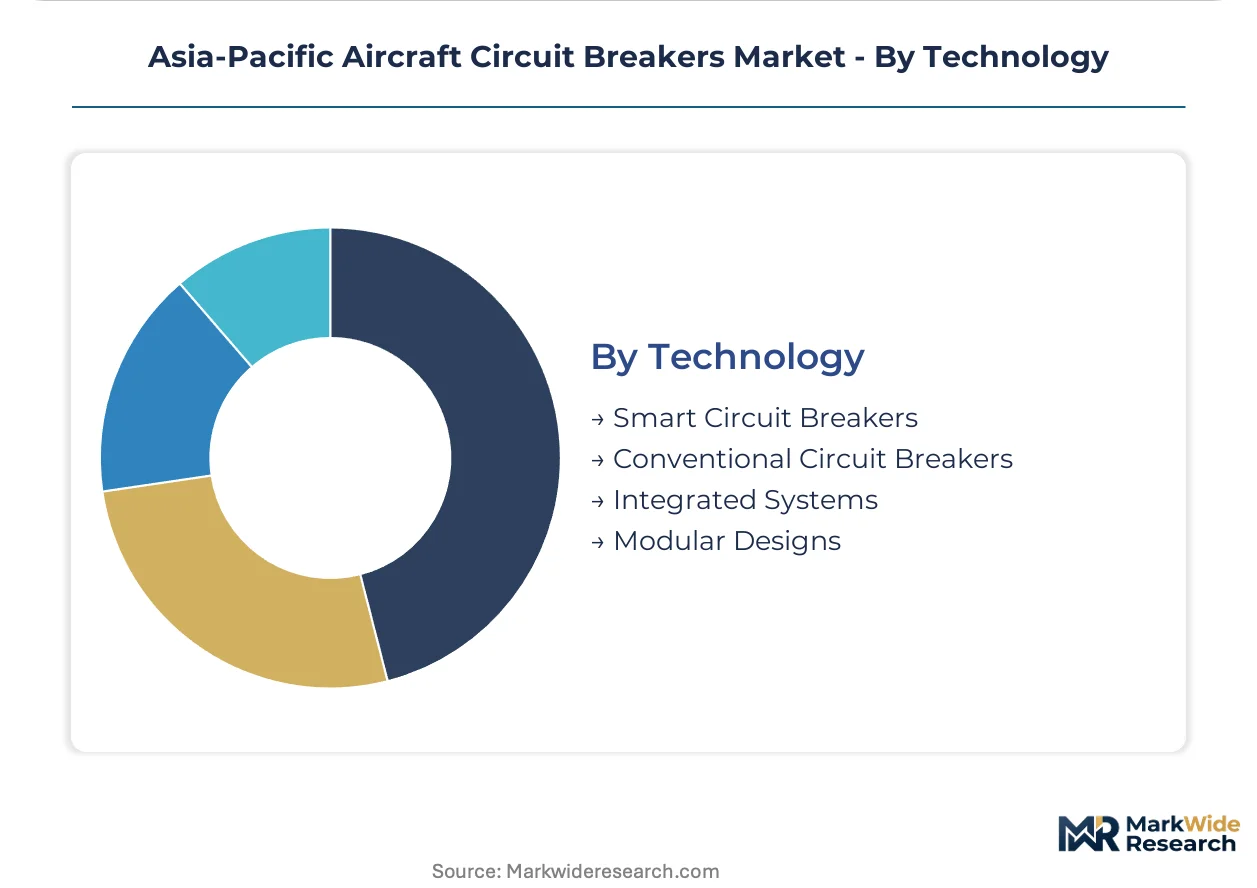
Technology:
Embedded software certification requirements reshape competitive barriers.
- Smart Circuit Breakers:DO-178C firmware compliance stretches development timelines as civil aviation authorities lack dedicated power electronics review capacity. Predictive fault detection algorithms anticipate rather than react to electrical system anomalies.
- Conventional Circuit Breakers:Thermal-hydraulic and magnetic designs dominate retrofit markets where airworthiness recertification costs constrain technology migration. Silver-copper alloy contact material volatility compresses margins on high-current variants.
- Integrated Systems:Power semiconductor integration collapses boundaries between protection and distribution management in next-generation commercial platforms.
- Modular Designs:Field-replaceable units reduce MRO turnaround times for line maintenance operations.
Installation base clusters around Conventional designs; technology investment flows toward Smart Circuit Breakers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement leverage through COMAC's indigenous narrow-body programs, while India's defense modernization and Southeast Asia's low-cost carrier expansion fragment demand across multiple national frameworks. Japan's regional jet electrification and Vietnam's emerging MRO infrastructure add further sub-regional specialization.
China
COMAC's C919 program and ARJ21 derivative fleets anchor electronic breaker demand through MIIT-mandated domestic certification pathways. GB standards alignment with airworthiness directives forces parallel testing tracks for export-oriented suppliers. Shanghai and Xi'an aerospace clusters concentrate tier-one electrical system integration for indigenous commercial platforms.
India
Defense aviation modernization under CEA and DGFT coordination channels thermal breaker procurement toward PLI-linked indigenous qualification. Import substitution mandates accelerate component certification timelines for tactical aircraft retrofit programs. Bengaluru and Hyderabad house emerging electrical distribution suppliers serving HAL and private defense contractors.
Japan
METI-sponsored regional jet development specifies smart breaker integration with predictive load management for next-generation platforms. JIS-compliant electrical system upgrades differentiate domestic suppliers from harmonized APAC frameworks. Nagoya and Tokyo aerospace corridors concentrate tier-two component fabrication for Mitsubishi Aircraft programs.
Vietnam
Low-cost carrier fleet commonality programs at VietJet and Bamboo Airways consolidate supplier relationships around narrow-body platform standards. Da Nang and Ho Chi Minh City MRO clusters lack qualified indigenous breaker suppliers, creating certification gaps for maintenance providers. The country's aviation infrastructure expansion outpaces qualified electrical component availability.
Indonesia
Lion Air Group and Garuda Indonesia fleet standardization drives thermal breaker retrofit demand across mixed-generation narrow-body assets. DGCA airworthiness enforcement tightens electrical system inspection intervals for aging aircraft. Jakarta and Surabaya maintenance hubs source breaker replacements through regional distributor networks with limited direct OEM contracting.
Asia-Pacific Aircraft Circuit Breakers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state specialization and MRO service anchoring. The vendor base stratifies between integrated electrical system architects and discrete component fabricators, with consolidation pressure intensifying around COMAC and Airbus Asia-Pacific supply chains. Three archetypes dominate: diversified aerospace conglomerates with bundled distribution portfolios, power electronics specialists with semiconductor integration capabilities, and regional maintenance service providers backward-integrating into component supply. Competitive moves center on certification pre-positioning in Vietnam's MRO hubs and silicon carbide foundry partnerships for high-voltage DC breaker topologies.
Among diversified system integrators, Safran Group and Honeywell International anchor tier-one contracting relationships through bundled electrical distribution architectures. Sensata Technologies occupies a position exemplifying power electronics specialization with thermal management expertise. These three entities represent the competitive spectrum from integrated platform supply to discrete component fabrication, with each archetype responding differently to China's GB certification divergence and India's PLI-linked procurement mandates.
| Leading Market Players |
|---|
| Safran Group |
| Collins Aerospace |
| Honeywell International |
| Sensata Technologies |
| Astronics Corporation |
| AMETEK |
| Crouzet |
| Eaton Aerospace |
| Commercial Aircraft Corporation of China Ltd |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers in China's COMAC supply chain and family-owned mid-caps serving India's defense aviation programs anchor pricing discipline through captive certification investments and import substitution mandates. Silver-copper alloy contact material volatility feeds directly into contract renegotiation cycles, while semiconductor foundry concentration in East Asia compresses margins for solid-state breaker assemblers unable to secure long-term wafer allocations.
Pricing Analysis
Volume concentrates in thermal-hydraulic designs for military retrofit programs where sustaining engineering costs prop pricing; margins accrue to electronic variants with silicon carbide MOSFET integration for COMAC C919 platforms. Three-tier pricing structure separates MIL-SPEC certified units from commercial airworthiness-grade and economy aftermarket replacements. Pricing pressure stems from precious metal input volatility on high-current thermal variants. Defense procurement authorities exhibit lowest price sensitivity due to qualification timelines; Vietnamese MRO providers face acute cost compression from limited indigenous supplier alternatives.
Supply Chain Analysis
Regional distribution centers in Shanghai and Singapore coordinate hub-and-spoke patterns for COMAC and Airbus Asia-Pacific final assembly lines. Manufacturing concentrates in China, Japan, and South Korea for power semiconductor fabrication and precision contact assembly. Raw material dependencies center on silver-copper alloys from Australian mining operations and wide-bandgap silicon carbide substrates from Japanese crystal growers. Single-source semiconductor vulnerability exposes lead time risks for solid-state breaker production. Distribution runs through tier-one system integrators with direct OEM contracting displacing regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified semiconductor foundry capacity constitutes the binding constraint propping pricing for solid-state variants, as civil aviation authorities lack dedicated power electronics review bandwidth to accelerate competitor qualification.
For Market Incumbents: Deploy certification pre-positioning in Vietnam's Da Nang and Ho Chi Minh City MRO clusters before indigenous suppliers achieve airworthiness qualification. Anchor supply relationships through bundled electrical distribution architectures that complicate disaggregation by low-cost carrier procurement teams. Lock in multi-year silver-copper alloy offtake agreements to insulate margins from precious metal volatility threatening high-current thermal breaker profitability. For New Entrants and Emerging Players: Capture white-space in Vietnam's maintenance provider segment where qualified breaker suppliers remain absent despite fleet expansion. Target India's PLI-linked aerospace component schemes for defense aviation thermal breaker qualification under CEA and DGFT coordination. Enter through specialized solid-state thermal management partnerships with regional low-cost carrier retrofit programs seeking arc fault detection integration. For Investors and Strategic Acquirers: Distressed-cycle entries favor power electronics specialists with semiconductor integration capabilities in Japan's METI-sponsored regional jet supply chain. Long-term viability hinges on silicon carbide foundry partnerships and DO-178C firmware certification infrastructure. Watch for MIIT acceleration of GB standards harmonization with APAC safety frameworks as inflection signal for export-oriented supplier revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Secures wafer supply for 540VDC bus protection in COMAC C919 electrical systems. |
| Vietnam MRO Certification Investment | Establishes first-mover positioning in Da Nang and Ho Chi Minh City maintenance clusters. |
| PLI-Linked Indigenous Qualification | Channels India's defense aviation modernization budgets toward domestic component suppliers. |
| Smart Breaker Firmware Development | Addresses DO-178C compliance gaps as civil aviation authorities expand review capacity. |
| Silver-Copper Alloy Supply Agreement | Mitigates contact material cost volatility compressing margins on high-current variants. |
Research Methodology
Independent corroboration across tier-one electrical system integrators, defense procurement officers at India's CEA and DGFT, and commercial aviation procurement leads at Indonesian and Vietnamese low-cost carriers underwrites the qualitative findings. Primary interviews with Safran Group and Honeywell International platform engineers, Sensata Technologies thermal management specialists, and Vietnam MRO maintenance directors combined with secondary validation from MIIT airworthiness directives, METI regional jet specifications, and PLI scheme documentation. Bottom-up shipment data from COMAC supply chain participants triangulates against top-down fleet expansion projections across the analysis window.
Rate-of-change decomposition separates volume growth in narrow-body platform deliveries from value migration toward solid-state electronic variants and smart breaker integration. Segmentation dimensions span product type, application platform, end-user contracting structure, and technology tier across the modeling period. CAGRs derive from installed base replacement cycles, fleet electrification trajectories, and certification timeline assumptions for indigenous commercial programs. Forecast inputs incorporate silver-copper alloy price band sensitivity and wide-bandgap semiconductor availability constraints.
The model holds under sustained MIIT enforcement of domestic certification pathways and stable precious metal input costs; deviation in GB standards harmonization pace or semiconductor foundry allocation disruptions would shift trajectory. Forecasts reflect documented assumptions regarding COMAC production ramp and India's defense procurement acceleration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Auxiliary Power Unit Gearbox Market
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Aerospace and Military Auxiliary Power Unit (APU) Market
Aircraft Power Systems
Thrust Vector Control (TVC) Systems Market
Aircraft Power Systems
Aircraft Hydraulic System Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aircraft Electronic Ignition System Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Aviation Actuator System Market